
 CPU Water Cooling Radiator Market | 2026-2036
CPU Water Cooling Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
CPU Water Cooling Radiator Market Insights
All-in-one radiator bundling with pre-filled loops and integrated pump-reservoir units is repositioning enthusiast buyer choice away from custom open-loop assemblies. Corsair leverages its captive controller ecosystem and iCUE software integration to sustain premium attach rates across gaming builds. EK Water Blocks anchors its position through deep specialization in custom copper cold plates and monoblock configurations for high-end workstations. Cooler Master competes aggressively on manufacturing scale, occupying the mid-market with standardized 240mm and 360mm aluminum radiator SKUs distributed through mass retail channels.
A CPU water cooling radiator is a heat exchanger device, typically constructed from aluminum or copper fin arrays brazed to flat tube channels, that dissipates thermal energy from a processor to a circulating liquid coolant via forced convection from attached fans. Its primary commercial purpose is to maintain CPU operating temperatures below thermal throttling thresholds in high-performance computing environments where air-cooled solutions prove thermally insufficient. Copper radiator configurations command margin concentration due to superior thermal conductivity and durability demands from sustained overclocking applications. The 360mm cooling capacity segment leads volume as mid-tower case compatibility expands, while 480mm units represent the fastest-growing configuration among dedicated server and workstation deployments where dual-processor thermal loads dominate.
The EPA ENERGY STAR program and FCC electromagnetic interference standards in the United States shape pump motor efficiency mandates and fan controller shielding requirements for imported radiator assemblies. The EU RoHS directive and REACH chemical framework restrict lead-based solders and certain glycol formulations, forcing reformulation of coolant pre-mixes sold with bundled kits. Stakeholders must monitor evolving ISO thermal performance testing protocols and regional extended producer responsibility laws that will determine which radiator materials and coolant chemistries retain market access across major economies.
Market Dynamics
The EU F-Gas Regulation and EPA energy efficiency mandates are forcing simultaneous reformulation of coolant chemistry and pump motor design, compressing product development cycles while opening compliance-driven substitution windows for copper-based thermal architectures.
Growth Catalysts
- Data center liquid cooling mandates:Hyperscale operators in the United States and Germany are deploying 480mm radiator arrays to manage dual-processor thermal loads exceeding 500W per socket.
- REACH-compliant glycol reformulation:European manufacturers are commercializing propylene-based coolant pre-mixes that satisfy ECHA chemical restrictions without sacrificing thermal transfer coefficients.
- Overclocking community expansion:Domestic PC builder communities in China are driving 360mm unit volume through competitive benchmarking and sustained thermal stress testing cultures.
Market Restraints
- Copper price volatility:Raw material cost swings for electrolytic-grade copper directly compress margins on premium cold plate and radiator fin stack configurations.
- Aluminum supply concentration:Extruded tube and folded fin production for mid-market radiators clusters with Chinese smelters and rolling mills, creating geographic single-point vulnerability.
- Air cooler performance convergence:Heat pipe tower designs from established thermal vendors now dissipate 200W+ TDP processors at sub-$50 price points, narrowing the performance-per-dollar gap with entry AIO liquid kits.
Strategic Opportunities
- Edge computing micro-datacenters:Distributed AI inference nodes in secondary German and Japanese cities require compact 240mm radiator form factors with redundant pump architectures.
- EU Green Deal thermal efficiency incentives:Member state rebate programs for energy-efficient computing hardware are creating pull-through demand for pump motors exceeding 80% hydraulic efficiency ratings.
- Direct-to-consumer assembly kits:E-commerce channels in the United States are enabling unbundled radiator, pump, and reservoir procurement for custom loop builders seeking component-level optimization.
Industry Challenges
- ISO thermal testing protocol fragmentation:Absence of unified heat dissipation measurement standards forces manufacturers to maintain multiple validation rigs for regional certification acceptance.
- Electronics-fluid integration complexity:RGB controller and fan hub firmware must synchronize with motherboard BIOS implementations across Intel and AMD platform generations, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CPU Water Cooling Radiator Market |
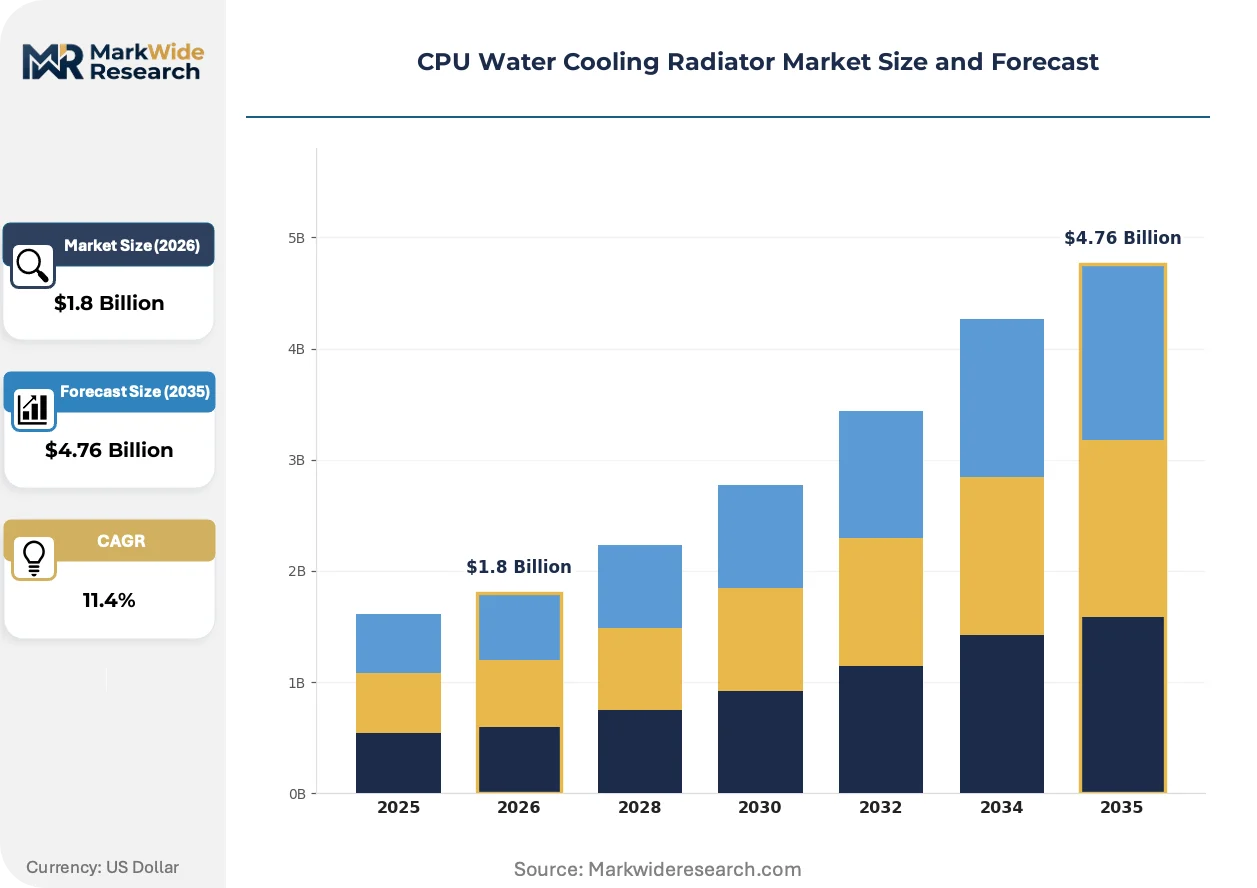
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Brass, Plastic Cooling Capacity: 120mm, 240mm, 360mm, 480mm Fitting Size: 1/4", 3/8", 1/2", G1/4 Application: Gaming PCs, Workstations, Servers, Overclocking |
| Companies Covered | Corsair, Cooler Master, NZXT, Thermaltake, EK Water Blocks, DeepCool, Alphacool, Bitspower, Aquacomputer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CPU Water Cooling Radiator Market Trends and Innovations
Radiator architecture is fragmenting along thermal performance and serviceability axes as enthusiast buyers reject sealed AIO limitations and data center operators demand field-replaceable pump modules. Material science advances and regulatory chemistry constraints are simultaneously reshaping coolant formulation and wetted surface metallurgy.
Copper-nickel alloy tubing is modularizing radiator core construction by enabling thinner wall profiles without galvanic corrosion penalties when paired with ethylene glycol coolants. High-frequency traders and quantitative finance workstation builders in Frankfurt and Chicago are specifying these configurations for 24/7 sustained loads. The shift is compressing demand for traditional brass-tube aluminum-fin assemblies while expanding addressable margin capture for specialized metallurgy suppliers.
EPA pump motor efficiency standards are mandating electronically commutated designs with minimum 75% energy conversion ratings for imported assemblies entering the United States. The rule is accelerating obsolescence of brushed DC pump architectures and forcing Asian contract manufacturers to retool winding and controller production lines. Gaming peripheral vendors targeting North American distribution channels are absorbing certification costs through premium SKU positioning rather than portfolio-wide compliance.
Builder preference is fragmenting between sealed convenience and open-loop serviceability as YouTube tutorial ecosystems democratize custom loop assembly skills. Mid-tower case manufacturers in Taiwan and South Korea are responding with standardized 360mm mounting locations and integrated fill ports. The behavioral shift is most pronounced in the United States and Germany, where PCPartPicker configuration sharing and Reddit community validation have compressed the perceived risk differential between AIO and custom liquid deployments.
CPU Water Cooling Radiator Market Segmentation
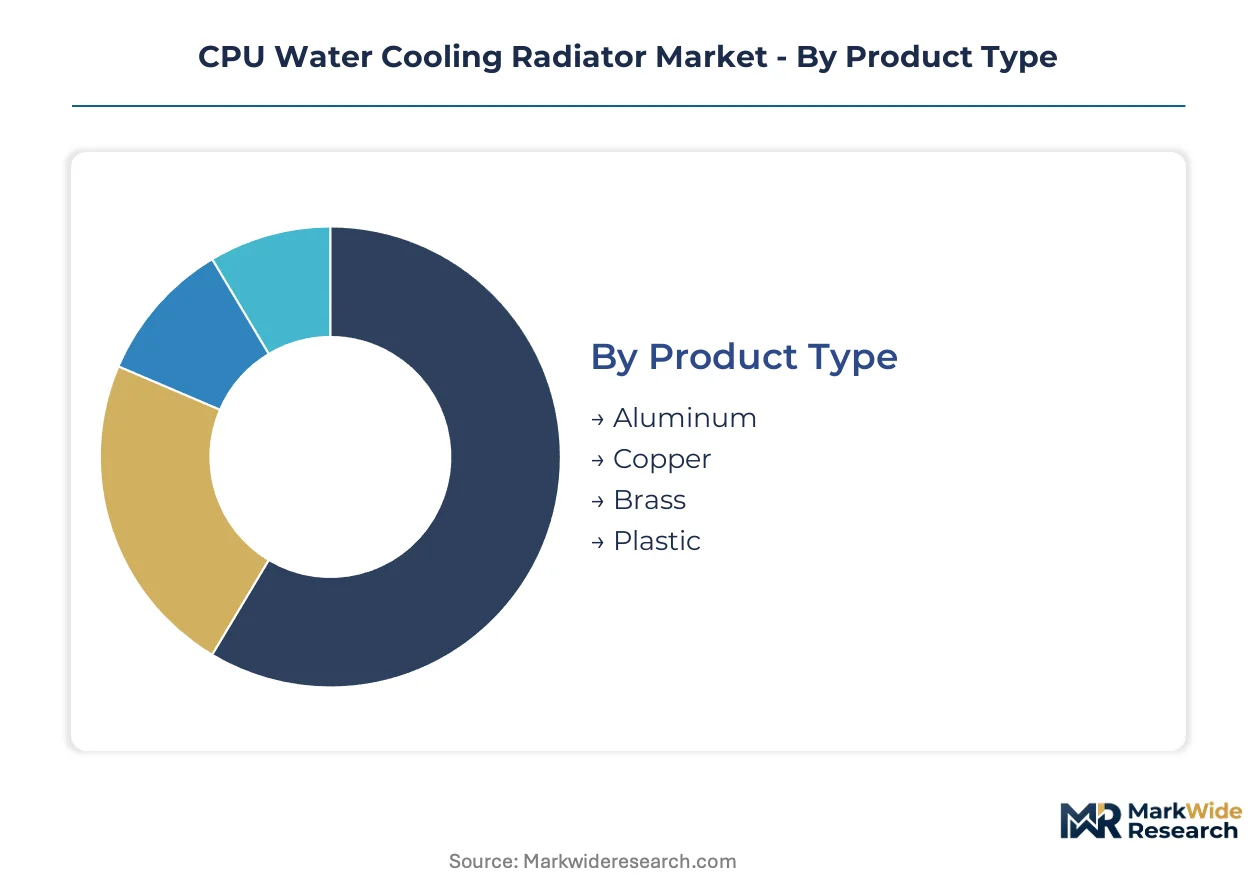
Radiator material selection and cooling capacity configuration determine thermal headroom, system longevity, and compliance posture across divergent end-use environments. Segmentation reveals how copper premiumization, 360mm mainstreaming, and server-grade 480mm scaling create distinct competitive arenas with margin and volume trade-offs.
Product Type:
Thermal conductivity coefficients and galvanic compatibility requirements divide material selection between performance-optimized and cost-engineered architectures.
- Aluminum:Extruded tube-and-fin assemblies with folded louvered fins dominate mid-market AIO bundles through manufacturing scale advantages. Chinese rolling mills supply substrate to Taiwanese radiator fabricators serving gaming peripheral brands targeting sub-$150 price tiers. Aluminum's lighter mass enables 240mm and 360mm configurations in compact mid-tower cases where structural load limits apply.
- Copper:Electrolytic-grade cold plates and fin arrays deliver thermal conductivity approximately double that of aluminum alloys, sustaining sub-60°C core temperatures under sustained 250W+ overclocking loads. Frankfurt quantitative finance workstations and Shenzhen competitive benchmarking rigs specify pure copper loops with nickel-plated surfaces to prevent oxidation in closed-loop ethylene glycol systems. Copper price volatility from London Metal Exchange fluctuations compresses margins on premium SKUs during commodity spike cycles.
- Brass:Copper-zinc alloy tubing offers intermediate thermal performance with superior machinability for custom fitting integration. Brass sees niche deployment in open-loop builds where builder preference favors aesthetic patina development over raw thermal metrics.
- Plastic:Glass-reinforced nylon pump housings and reservoir bodies reduce galvanic corrosion risk in mixed-metal loops. Plastic components enable translucent coolant visibility for RGB-integrated builds targeting visual customization markets.
Mature deployment sits with Aluminum. Newer deployment is concentrated in Copper.
Cooling Capacity:
Radiator surface area directly scales heat dissipation potential through extended fin exposure to forced airflow, with form factor constraints dictating chassis compatibility boundaries.
- 360mm:Triple 120mm fan configurations balance thermal headroom against mid-tower case prevalence, emerging as the volume leader across enthusiast retail channels. German PC builder communities and United States gaming peripheral e-commerce platforms report 360mm SKUs as the default recommendation for 200W-class processors. Taiwan case manufacturers now standardize 360mm top-mount locations as baseline feature sets.
- 480mm:Quadruple 120mm arrays deliver redundant thermal capacity for dual-socket server deployments and extreme overclocking scenarios exceeding 400W processor loads. Hyperscale operators in Virginia and Hesse deploy 480mm radiators in direct-to-chip liquid cooling manifolds for AI training clusters. The form factor demands full-tower or rackmount chassis, limiting addressable market to workstation and data center verticals.
- 240mm:Dual-fan configurations retain relevance in compact builds and small-form-factor cases where thermal loads remain below 150W TDP. 240mm units serve edge computing micro-datacenters in secondary Japanese cities requiring redundant pump architectures in constrained footprints.
- 120mm:Single-fan radiators persist in legacy ITX builds and low-profile server replacements where space constraints override thermal optimization priorities.
Mainstream volume concentrates in 360mm. Steepest expansion trajectory belongs to 480mm.
Fitting Size:
Thread specification and tubing diameter standardization determine loop compatibility, flow rate optimization, and serviceability in custom versus sealed system designs.
- G1/4:The BSPP threading standard dominates enthusiast custom loops through universal compatibility with pump-reservoir units, flow meters, and quick-disconnect fittings. G1/4 threading enables modular component swapping without complete loop drainage.
- 1/2":Larger bore tubing reduces flow restriction in high-capacity loops with multiple blocks and extended runs. 1/2" ID configurations suit workstation builds integrating GPU and CPU blocks in series.
- 3/8":Intermediate diameter balances flow rate against tubing flexibility for compact chassis routing. 3/8" remains common in pre-filled AIO units where manufacturer-controlled loop geometry optimizes pump curve efficiency.
- 1/4":Restricted bore diameter limits application to low-flow decorative loops and miniature ITX builds where space constraints predominate.
Standardization centers on G1/4. Performance-oriented builds are migrating toward 1/2".
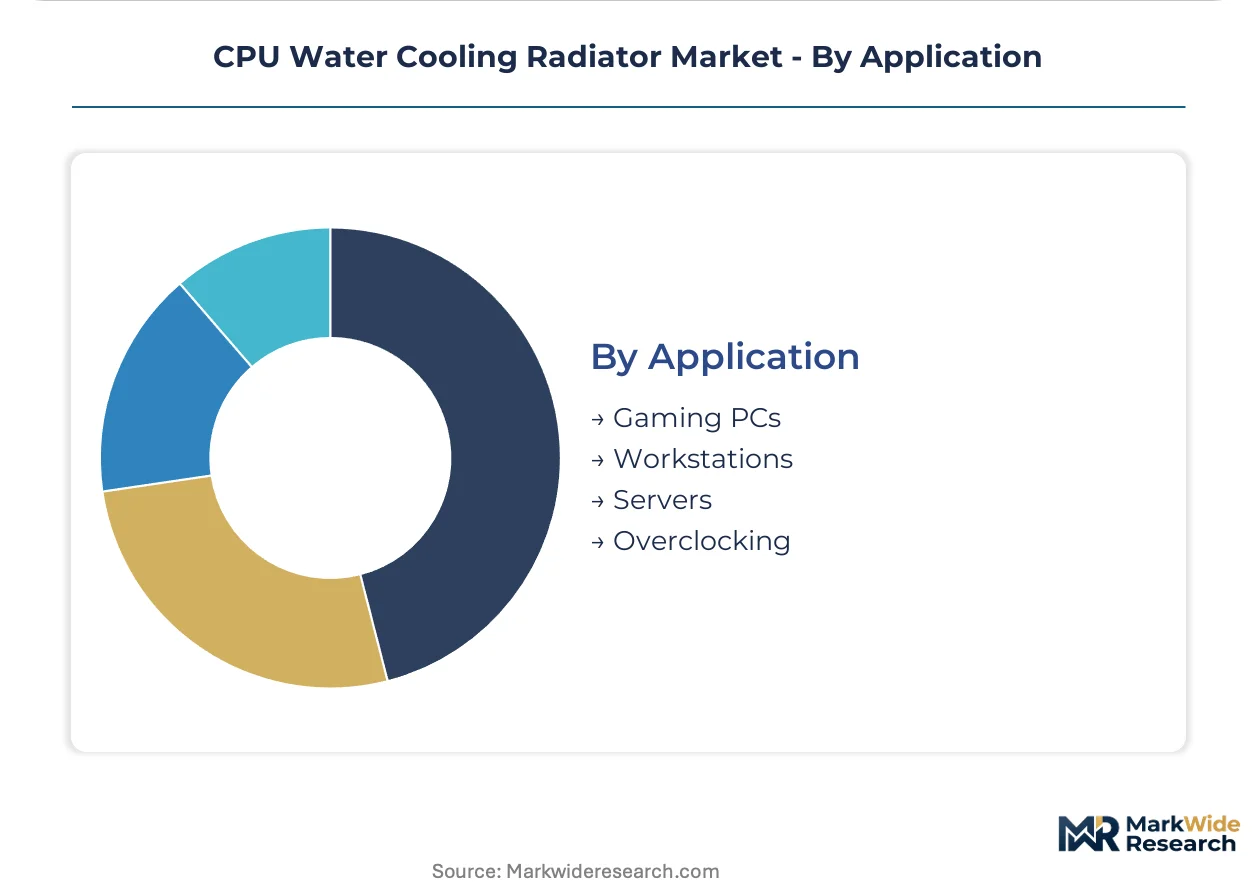
Application:
End-use thermal load profiles and reliability requirements fragment demand across consumer enthusiasm, professional computation, and infrastructure-grade deployment.
- Gaming PCs:RGB-integrated AIO bundles with pre-configured fan curves dominate volume through reduced assembly complexity. Gaming builds prioritize acoustic profile over absolute thermal margins, accepting 70°C peak temperatures for silent operation.
- Servers:Dual-processor thermal loads exceeding 500W per socket mandate redundant pump architectures and 480mm radiator arrays with hot-swappable fan modules. Server deployments require MTBF certifications and field-replaceable components absent from consumer SKUs.
- Workstations:Professional visualization and simulation workloads demand sustained thermal stability for 24/7 rendering operations. Workstation builders in Chicago and Frankfurt specify copper-nickel alloy tubing with propylene glycol coolants for corrosion resistance in continuous-duty cycles.
- Overclocking:Competitive benchmarking communities in China and Germany drive demand for custom open-loop configurations with flow rate monitoring and sub-ambient cooling potential. Overclocking applications prioritize thermal headroom margins above 50°C below throttle thresholds.
Volume concentration rests with Gaming PCs. Infrastructure scaling is accelerating in Servers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Chinese extrusion mills and Taiwanese radiator fabricators, while consumption concentrates in United States gaming markets, German workstation clusters, and Chinese overclocking communities.
United States
Hyperscale data center operators in Virginia and Texas deploy 480mm radiator arrays for AI training clusters exceeding 500W per socket thermal loads. The EPA ENERGY STAR program mandates electronically commutated pump motors with minimum 75% efficiency ratings for imported assemblies. Gaming peripheral e-commerce platforms in California and Washington state drive 360mm AIO volume through PCPartPicker configuration sharing ecosystems.
Germany
Quantitative finance workstation builders in Frankfurt specify copper-nickel alloy tubing with propylene glycol coolants for 24/7 sustained rendering operations. The EU F-Gas Regulation and REACH framework restrict lead-based solders and certain glycol formulations, forcing coolant pre-mix reformulation. Domestic PC builder communities in Berlin and Munich anchor European demand for custom open-loop configurations with flow rate monitoring capabilities.
China
Competitive benchmarking communities in Shenzhen and Beijing drive 360mm unit volume through sustained thermal stress testing cultures and overclocking competitions. The MIIT and GB standards framework shapes domestic pump motor efficiency requirements and electromagnetic compatibility certifications. Yangtze River Delta extrusion mills supply aluminum substrate to Taiwanese radiator fabricators serving global gaming peripheral brands.
Japan
Edge computing micro-datacenters in Osaka and Nagoya require compact 240mm radiator form factors with redundant pump architectures for distributed AI inference nodes. METI energy efficiency guidelines influence domestic procurement standards for data center thermal management equipment. Tokyo-based system integrators specialize in workstation builds integrating GPU and CPU blocks for professional visualization workloads.
South Korea
Mid-tower case manufacturers in Seoul and Suwon standardize 360mm top-mount radiator locations as baseline feature sets for gaming builds. Domestic semiconductor foundry expansion creates adjacent demand for liquid-cooled test equipment and reliability validation rigs. Busan-Ulsan industrial clusters supply precision-machined cold plate components to global AIO assembly lines.
CPU Water Cooling Radiator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning strata. The vendor base spans gaming peripheral conglomerates with captive controller ecosystems, thermal engineering specialists with deep metallurgy expertise, and mass-market fabricators competing on manufacturing scale. Three archetypes dominate: software-integrated lifestyle brands, custom loop metallurgy specialists, and aluminum-scale commodity producers. Competitive moves concentrate on strategic partnerships for controller firmware integration and geographic expansion through e-commerce direct-to-consumer channels.
Among lifestyle-integrated gaming peripheral vendors, Corsair exemplifies the software-captive archetype through its iCUE ecosystem positioning, while NZXT occupies a similar tier with builder-community-focused industrial design. EK Water Blocks represents the metallurgy-specialist archetype with concentrated expertise in custom copper configurations. These three anchors illustrate how competitive positioning fragments between convenience-driven sealed AIO bundling and enthusiast-grade open-loop serviceability.
| Leading Market Players |
|---|
| Corsair |
| Cooler Master |
| NZXT |
| Thermaltake |
| EK Water Blocks |
| DeepCool |
| Alphacool |
| Bitspower |
| Aquacomputer |
| Others |
Pricing and Supply Chain Analysis
EPA pump motor efficiency mandates for imported assemblies are forcing North American distributors to absorb certification costs through premium SKU repositioning, compressing mid-market margin structures while copper price volatility from London Metal Exchange fluctuations squeezes premium cold plate configurations.
Pricing Analysis
Margin tightening in aluminum mid-market tiers reflects Yangtze River Delta extrusion mill concentration and gaming peripheral brand price wars. Three-tier pricing structure across premium copper-nickel alloy, standard aluminum AIO bundles, and economy brass-tube configurations dominates, with differentiation anchored in thermal conductivity certification and MTBF ratings. Cost-down pressure on 240mm compact units accelerates because air cooler performance convergence narrows the performance-per-dollar gap. Gaming PC builders exhibit highest price sensitivity, while Frankfurt quantitative finance workstation operators accept 40-60% premiums for 24/7 corrosion-resistant metallurgy.
Supply Chain Analysis
Domestic-content incentives in German and Japanese edge computing procurement are reshaping sourcing patterns for redundant pump architectures and field-replaceable fan modules. Manufacturing gravity centers on Chinese extrusion mills, Taiwanese radiator fabricators, and South Korean precision-machined cold plate suppliers. Raw material flows draw from London Metal Exchange copper contracts, Chinese primary aluminum smelters, and Japanese electrolytic-grade nickel. Single-source vulnerability concentrates in Yangtze River Delta rolling mill capacity for folded louvered fin substrate. Distribution runs through California and Washington state e-commerce platforms, German system integrator channels, and Shenzhen competitive benchmarking community direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive pump motor winding and controller production lines is emerging as the decisive competitive lever as EPA efficiency mandates and FCC electromagnetic compatibility standards reshape qualification timelines.
For Market Incumbents: Deploy firmware ecosystem lock-in through motherboard BIOS synchronization investments to defend against custom loop democratization. Corsair's iCUE captive controller architecture exemplifies this defensive posture. Absorb copper price volatility through long-term London Metal Exchange hedging rather than spot market exposure. Capacity addition in Taiwanese radiator fabrication with automated brazing lines preserves margin against Chinese mid-market challengers.
For New Entrants and Emerging Players: Edge computing micro-datacenter operators in secondary Japanese and German cities represent the most penetrable buyer archetype, requiring compact 240mm redundant pump configurations absent from incumbent gaming-focused portfolios. Direct-to-consumer unbundled component e-commerce in the United States offers white-space access outside established retail channel gatekeepers. Specialist metallurgy positioning in copper-nickel alloy tubing for quantitative finance workstations commands premium positioning without scale disadvantages.
For Investors and Strategic Acquirers: The window for entry favors metallurgy-specialist targets with ISO thermal performance certification capabilities and established ECHA REACH-compliant coolant formulation pipelines. Long-term viability rests on regulatory compliance infrastructure rather than volume scale. The signal to watch is EPA pump motor efficiency rule expansion to brushed DC architecture obsolescence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Pump Motor Efficiency Certification | EPA ENERGY STAR compliance unlocks North American distribution access for imported radiator assemblies. |
| Copper-Nickel Alloy Metallurgy Investment | Frankfurt quantitative finance workstation demand sustains 24/7 corrosion-resistant thermal performance premiums. |
| Custom Loop Component Unbundling | PCPartPicker configuration sharing ecosystems enable direct-to-consumer bypass of retail channel margin extraction. |
| Redundant Pump Architecture Development | Edge computing micro-datacenter deployments in Osaka and Nagoya require field-replaceable reliability specifications. |
| ECHA REACH-Compliant Coolant Reformulation | Propylene glycol pre-mix validation preserves European market access under evolving chemical restriction frameworks. |
Research Methodology
Multi-period observation of thermal design power trajectories from AMD and Intel, EPA regulatory filing patterns, and London Metal Exchange copper price cycles anchored the trend analysis, supplemented by interviews with thermal engineering directors at gaming peripheral brands, procurement leads at Virginia hyperscale data center operators, and regulatory affairs specialists at German workstation integrators. Secondary validation drew from EPA ENERGY STAR certification databases, ECHA REACH substance restriction updates, SEC 10-K disclosures from listed thermal component suppliers, and customs records of aluminum extrusion and copper cold plate imports. Bottom-up SKU-level volume aggregation and top-down end-use thermal load modeling enabled cross-verification.
Segment-weighting across material type, cooling capacity configuration, fitting specification, and end-use application determined value distribution throughout the projection horizon. CAGRs were derived from installed base thermal load growth curves and replacement cycle compression patterns. Industry-specific forecast inputs included Intel and AMD processor roadmap TDP disclosures, hyperscale data center liquid cooling deployment announcements, and EU F-Gas Regulation implementation timelines.
Revisions become necessary when EPA pump motor efficiency thresholds tighten beyond current 75% mandates, copper price volatility exceeds historical bands, or ISO thermal performance testing protocols achieve harmonization across regional certification bodies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
United States Data Center Cooling Market