
 Molded Fiber Containers Market | 2026-2036
Molded Fiber Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Containers Market Foresight
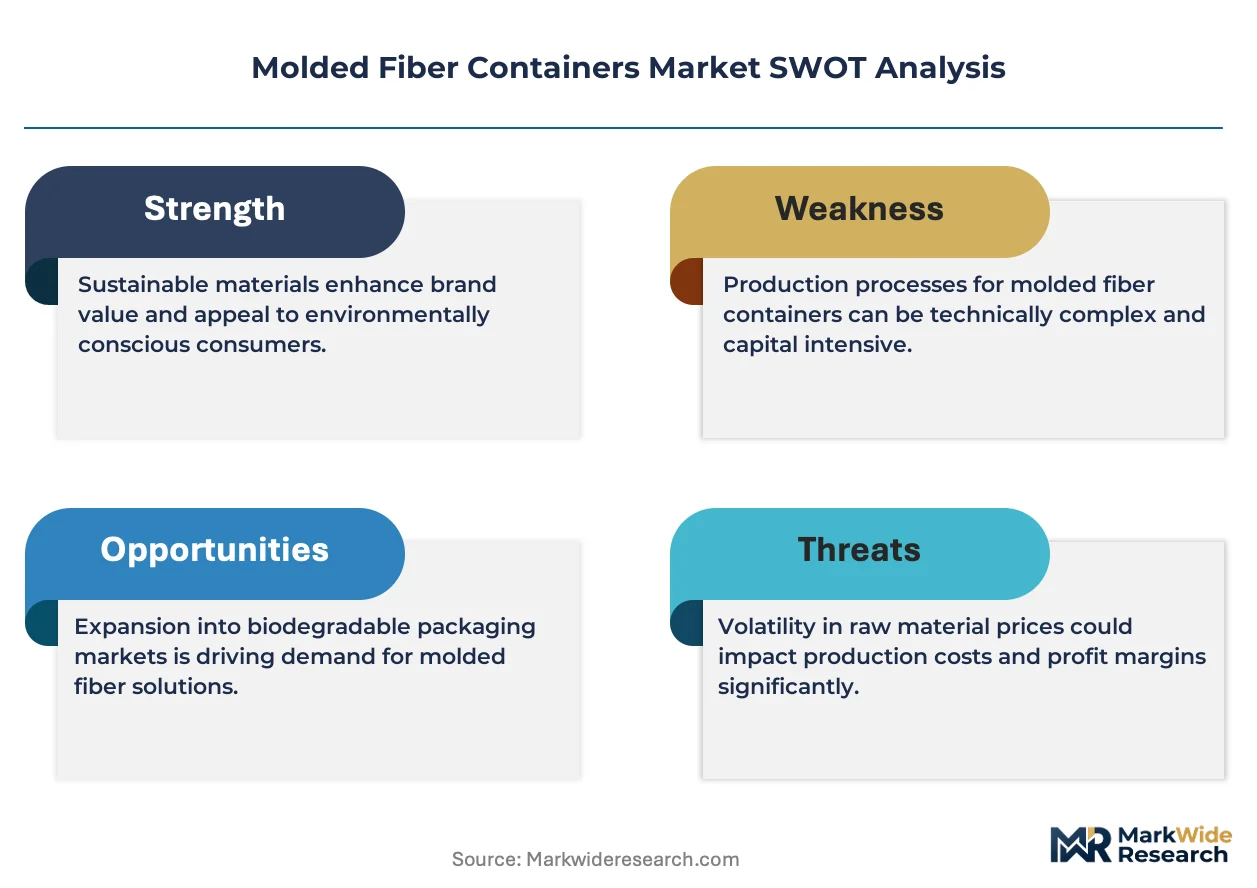
Aftermarket composting infrastructure revenue is reshaping how packaging suppliers capture value beyond the point of sale. Huhtamaki Oyj leverages its European pulp molding footprint to anchor large-volume contracts with quick-service restaurant chains. Brødrene Hartmann sustains cost leadership through integrated recycled paper sourcing across its Danish and Polish mills. Sonoco Products Company competes on custom-engineered protective formats for electronics and medical device segments.
Molded fiber containers are rigid packaging articles formed from slurried cellulose fibers—typically recycled newsprint, corrugated, or agricultural residues—pressed and dried into shaped articles with defined wall thickness, moisture resistance, and stack strength specifications; they serve primarily as protective and presentation packaging for perishable goods and fragile products. Trays and clamshells dominate foodservice procurement volumes, with clamshells capturing premium margins in hot-food and grab-and-go applications where grease resistance and hinged-lid functionality justify higher unit pricing. The compostable form category is expanding fastest as industrial composting certification becomes a gatekeeping specification for national grocery and foodservice distributor RFPs.
The EU F-Gas Regulation and REACH compliance frameworks constrain fluorochemical additives in grease-resistant coatings, pushing suppliers toward PFAS-free barrier technologies. FDA food contact substance notifications govern pulp additives and coatings for US food packaging applications, while California's Safer Food Packaging and Cookware Act imposes additional state-level substance restrictions. Stakeholders must monitor composting infrastructure build-out rates and evolving state-by-state extended producer responsibility frameworks to align capacity investments with actual end-of-life processing availability.
Market Dynamics
Compostable packaging mandates across multiple jurisdictions are compressing conversion timelines for foodservice buyers, forcing rapid retooling of procurement specifications and supplier qualification processes.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive's ban on expanded polystyrene food containers redirects institutional procurement toward molded fiber alternatives across Germany, France, and the Netherlands.
- Quick-service restaurant chains:Burger King, McDonald's, and Wendy's system-wide sustainability commitments are standardizing molded fiber tray specifications for hot-food applications.
- Recycled pulp integration:Closed-loop fiber recovery systems at major corrugated mills are lowering input costs for container-grade pulp slurry production.
Market Restraints
- PFAS coating restrictions:California's Safer Food Packaging and Cookware Act and parallel EU F-Gas Regulation constraints eliminate fluorochemical grease barriers, forcing costly reformulation cycles.
- Composting infrastructure gaps:Industrial composting facility density in the US Midwest and Southern Europe lags behind container deployment rates, creating end-of-life processing bottlenecks.
- Energy cost volatility:Natural gas price spikes at German and Polish pulp-drying operations compress operating margins for European molded fiber producers.
Strategic Opportunities
- Electronics protective packaging:Smartphone and laptop manufacturers are qualifying molded fiber cushions to replace expanded polyethylene foam in premium unboxing experiences.
- Extended producer responsibility frameworks:France's AGEC Law and upcoming UK packaging taxes create compliance-driven demand for certified compostable formats.
- Direct-to-consumer meal kits:HelloFresh and Blue Apron are specifying custom-molded fiber inserts to replace plastic chill packs and separator trays.
Industry Challenges
- Barrier coating R&D timelines:PFAS-free alternatives require 18-24 month food contact notification cycles with FDA, delaying product launches.
- Tooling capex intensity:Precision aluminum molds for complex hinged-lid clamshells demand six-figure investments per SKU, constraining product portfolio breadth for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Containers Market |
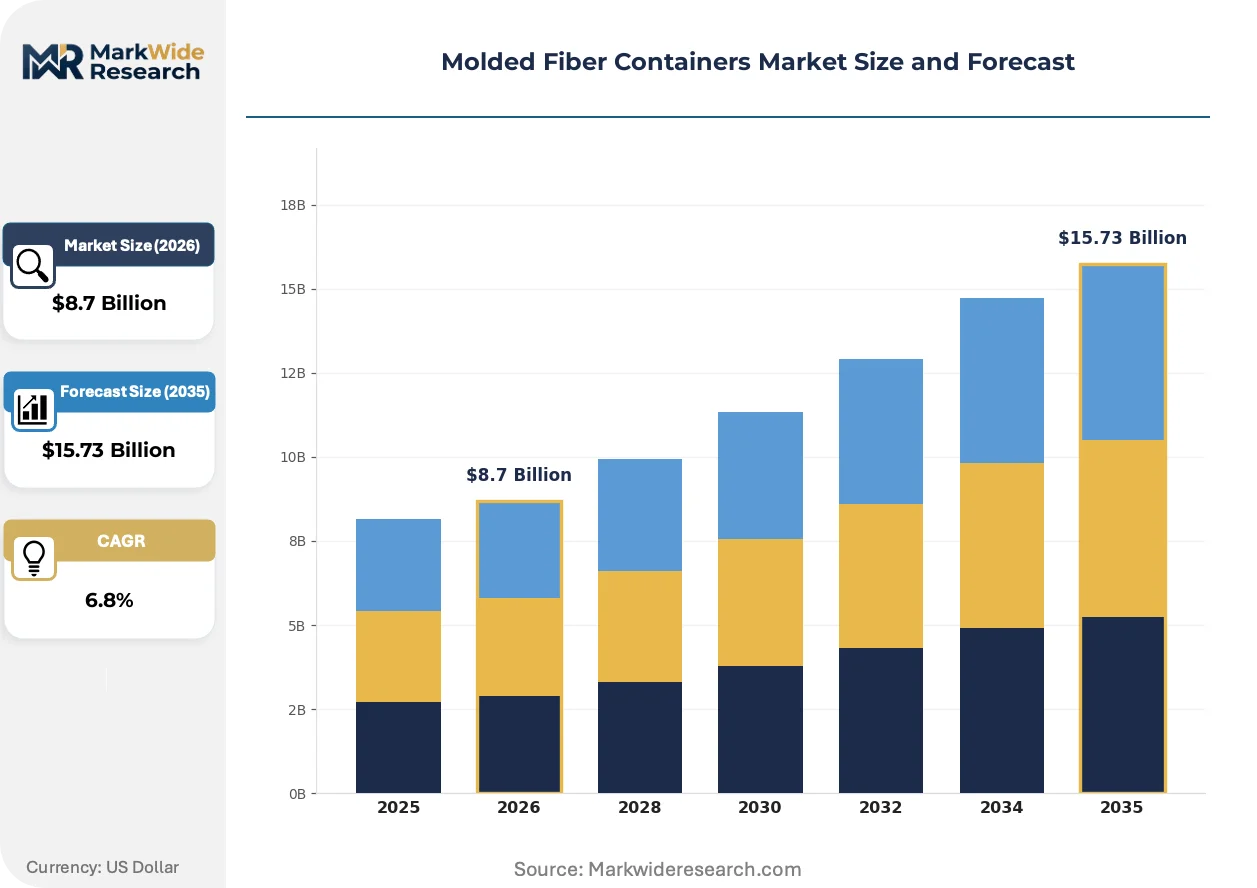
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Boxes, Plates End Use: Food Packaging, Electronics, Consumer Goods, Medical Supplies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Form: Biodegradable, Compostable, Recyclable, Custom |
| Companies Covered | Huhtamaki Oyj, Pactiv Evergreen, UFP Technologies, Brødrene Hartmann, Sonoco Products Company, FiberCel Packaging LLC, Genpak LLC, Henry Molded Products, CKF Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Containers Market Shifts & Advancements
Digital design tools and barrier chemistry breakthroughs are compressing product development cycles while expanding the performance envelope of cellulose-based packaging beyond traditional foodservice applications.
Barrier coating technology is virtualizing the functional gap between molded fiber and plastic containers. Spray-applied polylactic acid and bio-based wax emulsions now achieve comparable grease resistance to polyethylene laminates. Foodservice distributors in California and New York are qualifying these formats for hot-oil applications previously restricted to plastic. The technology is virtualizing material substitution decisions by collapsing the performance premium historically commanded by petroleum-based alternatives.
REACH compliance frameworks and state-level substance restrictions are fragmenting additive approval pathways. ECHA's evolving restrictions on intentional per- and polyfluoroalkyl substances eliminate cross-Atlantic coating formulations, forcing dual R&D tracks. European suppliers are accelerating bio-based barrier investments while US counterparts navigate parallel FDA notification requirements. Quick-service chains with transatlantic footprints face specification divergence that complicates global menu packaging standardization.
Certification-driven procurement is consolidating supplier relationships around industrial composting credentials. Food retailers and institutional buyers now require BPI or TÜV Austria OK compost HOME certification as a gatekeeping specification, disqualifying uncertified competitors. Distributor RFPs in Germany and Austria specify certified fiber content percentages alongside compostability. This behavioral shift favors suppliers with established certification infrastructure and captive testing relationships with accredited laboratories.
Molded Fiber Containers Market Segmentation
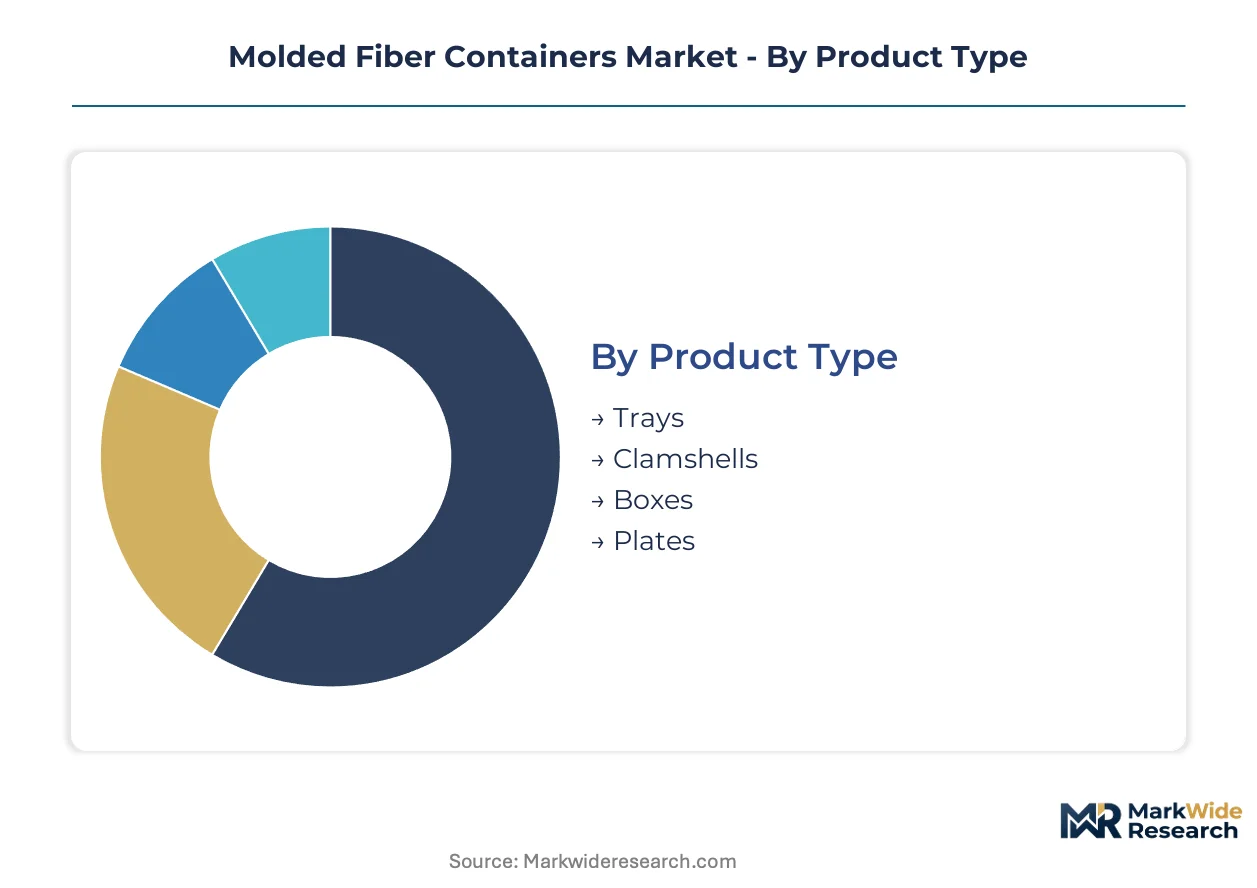
Segmentation in molded fiber containers reveals how procurement cycles, certification requirements, and end-use performance standards fragment supplier strategies across foodservice, electronics, and institutional channels. Understanding these divides clarifies where capital-intensive tooling investments yield returns versus where commoditized volume plays dominate.
Product Type:
Cycle times vary sharply across formats, with single-use foodservice items turning over in weeks while protective packaging for electronics operates on annual procurement calendars with rigid qualification protocols.
- Trays:Flat-bottomed fiber formats with raised edges for containment, engineered for stack stability and automated filling line compatibility. Quick-service restaurant chains in Germany and California standardize these for hot-food applications where grease-resistant coatings meet FDA and REACH compliance thresholds. Trays anchor the volume base while clamshells gain share at the steepest rate.
- Clamshells:Hinged-lid configurations with integral locking mechanisms, demanding precision aluminum molds and 18-24 month food contact notification cycles. HelloFresh and Blue Apron procurement teams specify these for meal kit insulation layers, paying premium unit prices for certified compostable formats that satisfy France's AGEC Law requirements.
- Boxes:Rigid six-sided containers for bulk produce and industrial components, produced on lower-cost tooling with longer production runs. Agricultural cooperatives in the Netherlands favor these for soft-fruit export packaging.
- Plates:Shallow dish formats with rim reinforcement for structural integrity under load. Institutional cafeteria operators in New York State specify these for compliance with expanded polystyrene bans.
Trays and clamshells together concentrate foodservice procurement volumes, though plates capture incremental share where regulatory bans accelerate SKU conversion timelines.
End Use:
Cost tiers separate commodity food packaging from precision-engineered protective formats where performance specifications justify 3-5x unit price multiples and dedicated R&D relationships.
- Food Packaging:The dominant demand channel spanning quick-service chains, grocery private-label programs, and institutional foodservice. Burger King and McDonald's system-wide sustainability commitments standardize molded fiber tray specifications across thousands of locations, creating volume anchors for suppliers with multi-continental production footprints.
- Electronics:Premium protective cushioning for smartphones, laptops, and medical devices, replacing expanded polyethylene foam in unboxing experiences. Apple and Samsung qualification processes demand months of drop-testing and vibration protocol validation before supplier approval.
- Consumer Goods:Presentation packaging for cosmetics, housewares, and premium retail items where fiber textures communicate sustainability positioning. Direct-to-consumer brands specify these for Instagram-friendly unboxing moments.
- Medical Supplies:Sterile barrier systems and procedure kit containment with exacting particulate and fiber-shedding specifications. FDA device packaging regulations and EU MDR compliance frameworks govern material selection and validation documentation.
Food packaging absorbs the majority of production capacity while electronics represents the margin expansion frontier where technical qualification barriers limit competitive entry.
Distribution Channel:
Volume concentrates through wholesale and supermarket procurement offices, though online retail growth is fragmenting buyer power and enabling mid-tier suppliers to bypass traditional distributor gatekeepers.
- Online Retail:Direct-to-consumer fulfillment packaging specified by e-commerce pure-plays and omnichannel retailers. Amazon's Frustration-Free Packaging guidelines and Walmart's sustainability scorecards drive fiber format adoption for damage reduction and waste minimization.
- Supermarkets:Private-label produce and prepared food packaging where retail buyers negotiate annual volume contracts with certified compostable requirements. German retailers leverage Hartmann's production network for rapid SKU conversion programs.
- Specialty Stores:Premium and niche formats for organic grocers, zero-waste shops, and hospitality suppliers where certification storytelling commands shelf price premiums.
- Wholesale:Institutional and foodservice distributor procurement aggregating demand from independent restaurants, schools, and healthcare facilities. Sysco and US Foods RFPs increasingly specify BPI certification as a gatekeeping requirement.
Wholesale channels anchor procurement volumes while online retail expands most quickly as direct brand relationships reshape traditional distribution economics.
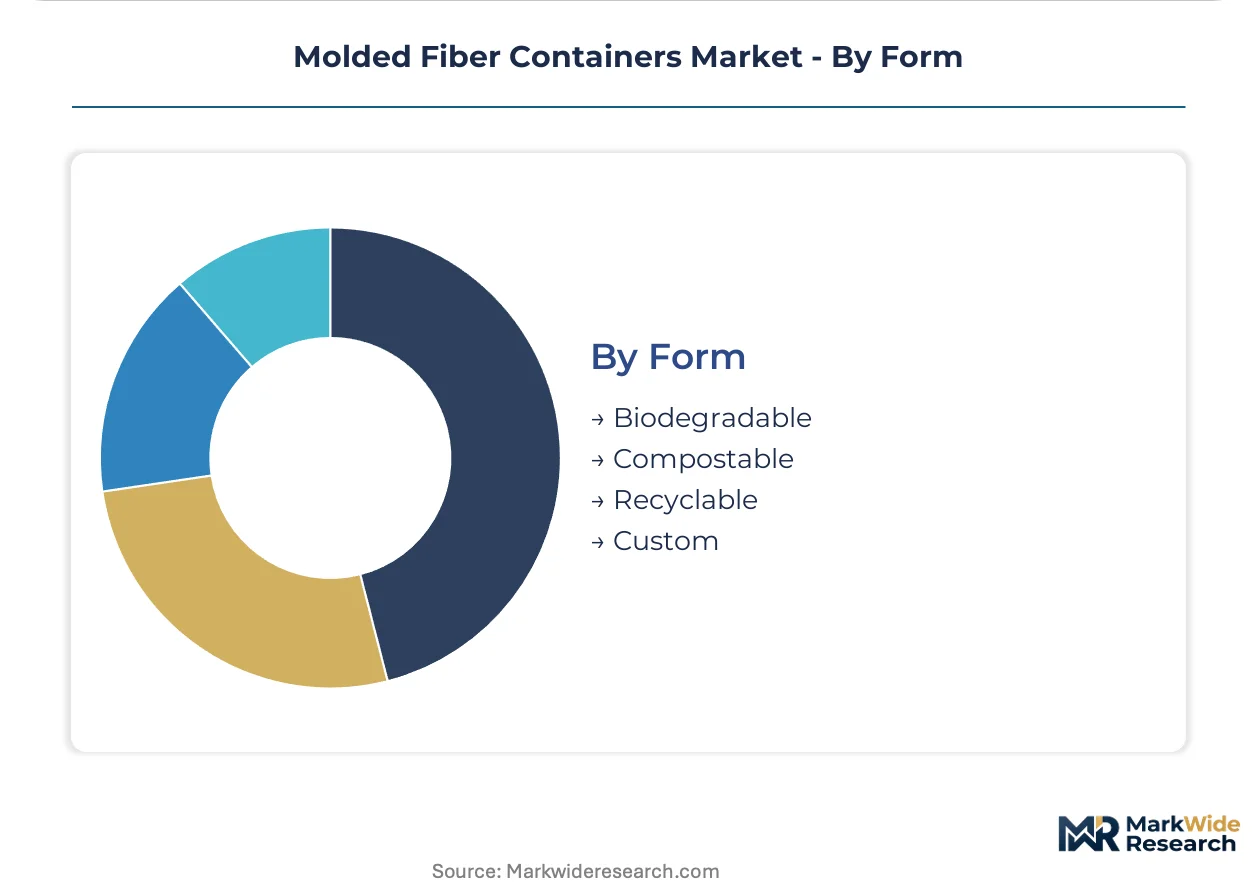
Form:
Certification grade stratifies pricing and supplier relationships, with industrial compostable credentials becoming non-negotiable for national grocery and foodservice distributor contracts while recyclable formats compete on cost in less regulated channels.
- Biodegradable:Materials that break down through natural microbial action without requiring industrial composting infrastructure, though degradation timelines vary widely by environment. These formats compete in regions where composting facility density remains underdeveloped.
- Compostable:Certified formats meeting ASTM D6400 or EN 13432 standards for industrial composting facility processing, with BPI and TÜV Austria OK compost HOME credentials now mandatory for distributor RFPs in Germany, Austria, and California. Quick-service chains with transatlantic footprints face specification divergence as ECHA restrictions and FDA notification requirements force dual R&D tracks.
- Recyclable:Fiber formats compatible with existing paper and corrugated recycling streams, avoiding composting infrastructure dependencies but lacking the end-of-life marketing claims that drive foodservice procurement shifts. These capture price-sensitive segments where certification premiums are unrecoverable.
- Custom:Engineered formats with proprietary barrier coatings, dimensional specifications, or branding elements for exclusive customer relationships. Tooling capex intensity and 18-24 month food contact notification cycles constrain supplier participation in this tier.
Compostable formats concentrate revenue growth while recyclable alternatives defend position in cost-driven procurement segments where infrastructure gaps limit certified format viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement markets, with German retail buyers absorbing certification premiums while US Midwest foodservice operators resist cost increases where composting infrastructure remains sparse.
United States
Quick-service chains and institutional cafeterias drive tray and clamshell procurement volumes across California, New York, and the Pacific Northwest. California's Safer Food Packaging and Cookware Act and parallel state-level expanded polystyrene bans redirect procurement toward certified compostable formats. The Los Angeles basin concentrates supplier qualification activity as distributors consolidate sourcing relationships around BPI-certified manufacturers.
Germany
Supermarket private-label programs and quick-service sustainability commitments compress SKU conversion timelines for fiber-based food packaging. The EU Single-Use Plastics Directive and REACH compliance frameworks constrain coating formulations while creating procurement mandates. The North Rhine-Westphalia industrial corridor hosts dense pulping and molding operations that support rapid format switching for retail buyers.
France
Institutional foodservice and meal-kit distributors specify certified compostable containers under AGEC Law extended producer responsibility frameworks. ANSM and ECHA substance restrictions eliminate fluorochemical barriers from approved coating lists. The Île-de-France region concentrates distributor procurement offices and composting facility planning authorities.
Netherlands
Agricultural export cooperatives and soft-fruit distributors favor rigid six-sided fiber boxes for produce shipping to German and UK retail channels. National packaging waste regulations align with EU Green Deal circular economy targets. The Rotterdam port cluster anchors logistics-intensive packaging procurement for export-oriented growers.
United Kingdom
Upcoming packaging taxes and retailer sustainability scorecards accelerate fiber format adoption for prepared foods and produce. The Food Standards Agency governs food contact notifications while Environment Agency frameworks shape composting infrastructure investment. The Midlands manufacturing belt concentrates molding operations serving national grocery chains.
Molded Fiber Containers Market Competitive Landscape
Integrated pulp-to-container specialists and regional molding specialists split the market between cost leadership and customization capabilities. Consolidation concentrates around European producers with captive recycled fiber supply and North American specialists with quick-service restaurant chain relationships. Three archetypes dominate: vertically integrated European groups with mill networks, North American foodservice-focused molders with distributor channel density, and Asian equipment-and-technology suppliers expanding into Western markets. Capacity expansion and PFAS-free barrier technology licensing represent the dominant competitive moves as suppliers race to meet certification-driven procurement deadlines.
Among Nordic-integrated specialists, Brødrene Hartmann anchors cost leadership through Danish and Polish mill networks, while Huhtamaki Oyj exemplifies the multi-continental contract manufacturer archetype with European pulp molding footprints. Sonoco Products Company occupies a position in protective packaging specialization for electronics and medical segments. These three represent distinct strategic postures: captive fiber supply, global quick-service scale, and precision-engineered protective formats.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Pactiv Evergreen |
| UFP Technologies |
| Brødrene Hartmann |
| Sonoco Products Company |
| FiberCel Packaging LLC |
| Genpak LLC |
| Henry Molded Products |
| CKF Inc. |
| Others |
Supply & Pricing Matrix
Danish and Polish pulp mill networks anchor input cost stability for European molded fiber producers, concentrating margin capture downstream at quick-service restaurant chains and certified compostable packaging tiers where buyers absorb sustainability premiums.
Pricing Analysis
Aftermarket composting infrastructure revenue and extended producer responsibility compliance services now drive lifetime value beyond unit sales. Three-tier pricing structure across premium, standard, and economy levels separates BPI-certified compostable clamshells from recyclable trays and uncertified commodity formats. Cost compression in standard-grade recyclable tiers intensifies because natural gas price volatility at German drying operations squeezes mid-tier suppliers. Institutional cafeteria operators in the US Midwest exhibit highest price sensitivity, while German supermarket private-label buyers accept certification premiums.
Supply Chain Analysis
Tariff exposure between US and Chinese pulp equipment suppliers dominates capital expenditure planning for North American molders expanding capacity. Raw material sourcing draws from recycled corrugated networks in Germany, agricultural residue collectors in the Netherlands, and post-consumer newsprint recovery systems across Denmark and Poland. Single-source vulnerability concentrates in precision aluminum mold fabrication, where German toolmakers control hinged-lid clamshell tooling. Distribution runs through wholesale foodservice distributors like Sysco and US Foods, with direct-to-consumer meal kit channels fragmenting traditional procurement hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molded fiber containers represent an early-cycle expansion story as EU Single-Use Plastics Directive mandates and parallel US state-level EPS bans accelerate SKU conversion timelines across foodservice procurement.
For Market Incumbents: Insulate margin pools by deepening captive recycled fiber supply through Danish and Polish mill network expansion, while accelerating PFAS-free barrier R&D to preempt FDA notification bottlenecks. Huhtamaki and Hartmann demonstrate how multi-continental production footprints defend against regional energy cost spikes. Certification infrastructure investment—BPI and TÜV Austria laboratory relationships—creates switching costs that lock in national distributor contracts. For New Entrants and Emerging Players: Mid-tier electronics protective packaging for smartphone and laptop manufacturers represents the most penetrable entry point, as Apple and Samsung qualification protocols limit incumbent lock-in compared to foodservice channels. Direct-to-consumer meal kit insulation layers for HelloFresh and Blue Apron offer second-mover advantage through custom-molded fiber insert specifications. A go-to-market angle centered on drop-testing validation partnerships with Midwest US electronics assemblers bypasses entrenched distributor gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated European specialists with captive pulp supply and established composting certification infrastructure, where 5-10 year viability rests on extended producer responsibility framework proliferation. The acquisition target archetype combines German or Polish production assets with active FDA food contact notification pipelines. The signal to watch is industrial composting facility permitting velocity in US Midwest and Southern European markets, as infrastructure gaps threaten certified format value propositions regardless of regulatory mandates.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier R&D Investment | FDA notification cycles for bio-based coatings determine competitive entry timing for quick-service chains. |
| Composting Certification Infrastructure | BPI and TÜV Austria laboratory relationships gatekeep national distributor RFP participation in Germany and California. |
| Electronics Protective Packaging Qualification | Apple and Samsung drop-testing protocols open margin expansion beyond commoditized foodservice trays. |
| Captive Recycled Fiber Supply Expansion | Danish and Polish mill networks insulate Hartmann and Huhtamaki from energy cost volatility. |
| Direct-to-Consumer Channel Development | Amazon Frustration-Free Packaging guidelines and meal kit specifications fragment traditional wholesale procurement. |
Research Methodology
Desk research of FDA food contact substance notifications, EU ECHA restriction dossiers, and BPI-certified product registries preceded structured interviews with quick-service restaurant procurement directors, molded fiber plant operations managers, composting facility permitting officers, and wholesale foodservice distributor category buyers. Secondary validation drew from SEC 10-K filings of packaging suppliers, EU Single-Use Plastics Directive implementation reports, and state-level extended producer responsibility legislation tracking. Bottom-up volume modeling triangulated against top-down market sizing across product type, end use, and certification grade dimensions.
Assumptions held fixed include current EU F-Gas Regulation and REACH compliance frameworks, California Safer Food Packaging and Cookware Act enforcement timelines, and existing industrial composting facility density across modeled geographies. Variables included natural gas price trajectories at European drying operations, PFAS-free coating food contact notification approval velocities, and quick-service chain system-wide sustainability commitment acceleration. Segmentation dimensions spanned trays, clamshells, boxes, and plates by food packaging, electronics, consumer goods, and medical supplies end uses, with compostable, recyclable, and biodegradable form grades. CAGRs derived from regression analysis of historical procurement volume data against regulatory mandate implementation schedules and infrastructure investment pipelines.
Practitioners should monitor industrial composting facility permitting velocity, PFAS-free coating FDA notification approval rates, and natural gas price volatility at German and Polish pulp operations for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market