
 Container Coating Market | 2026-2036
Container Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Container Coating Market Analysis
EU REACH is broadening the cost-of-entry calculus for coating suppliers serving European container fleets. PPG Industries sustains R&D intensity across low-VOC epoxy formulations for marine cargo units. Akzo Nobel dominates European regulatory compliance with its specialized antifouling and corrosion-resistant product lines. Chugoku Marine Paints anchors Asian supply relationships through its concentrated maritime coating expertise.
Container coatings are thermoset or thermoplastic film systems applied to steel, aluminum, or plastic substrates to prevent corrosion, chemical leaching, and surface degradation during multi-modal transport; epoxy formulations typically achieve dry-film thicknesses of 80-200 microns and must pass ISO 12944 corrosion-class testing for salt-laden environments. Epoxy coatings lead the coating type category due to their adhesion strength and chemical resistance in harsh maritime cycles. Polyurethane segments are gaining share in food packaging applications where flexible cure properties and lower odor transfer matter. Steel remains the dominant material type, though aluminum substrates are expanding in lightweight beverage container designs.
FDA, EPA, and EMA frameworks govern direct-contact coatings for food and pharmaceutical containers, with FDA 21 CFR 175.300 setting migration limits for resinous and polymeric coatings. ECHA substance restrictions under REACH Annex XVII are phasing out bisphenol-A derivatives in food-contact epoxy systems, forcing reformulation investments across suppliers. Stakeholders must monitor evolving biocide regulations in major container manufacturing jurisdictions to anticipate product registration requirements and avoid supply discontinuities.
Market Dynamics
REACH compliance deadlines are compressing formulation cycles across European container coating supply chains, forcing suppliers to accelerate low-VOC epoxy development while maintaining ISO 12944 salt-spray performance thresholds.
Growth Catalysts
- Fleet Renewal Programs:Maritime operators in Singapore, Rotterdam, and Shanghai are accelerating container replacement schedules, creating sustained coating demand for new-build steel units.
- REACH Annex XVII:ECHA restrictions on bisphenol-A derivatives in food-contact applications are mandating reformulation investments that favor compliant suppliers with established regulatory infrastructure.
- Port Infrastructure Expansion:Chinese manufacturing clusters along the Yangtze River Delta are scaling container production capacity to match terminal throughput growth.
Market Restraints
- Raw Material Concentration:Epoxy resin supply concentrates among petrochemical complexes in the US Gulf Coast and Northeast Asia, exposing coating formulators to feedstock volatility.
- Technical Limitation:Current waterborne epoxy systems fail to achieve equivalent salt-spray resistance versus solvent-borne alternatives in C5-M marine corrosion categories.
- Regulatory Friction:Divergent FDA 21 CFR 175.300 and EFSA migration limit protocols force parallel certification tracks for food-contact coatings.
Strategic Opportunities
- Aluminum Substrate Penetration:Lightweight beverage container designs in Germany and Japan are expanding addressable coating surface area beyond traditional steel dominance.
- Biocide-Free Formulations:EU Green Deal sustainability incentives are creating preference premiums for non-biocidal antifouling systems in European fleet maintenance.
- Digital Coating Specification:Engineering platforms are displacing traditional distributor channels for technical coating selection in large fleet procurement.
Industry Challenges
- Formulation Talent Scarcity:Specialized expertise in low-VOC epoxy curing chemistry is concentrating among retiring technical workforces in European and Japanese coating centers.
- ISO 12944 Certification Timelines:Extended salt-spray and cyclic corrosion testing protocols delay new product commercialization by 18-24 months.
- Legacy System Integration:Automated spray application lines in established container plants require retrofit compatibility with next-generation coating viscosities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Coating Market |
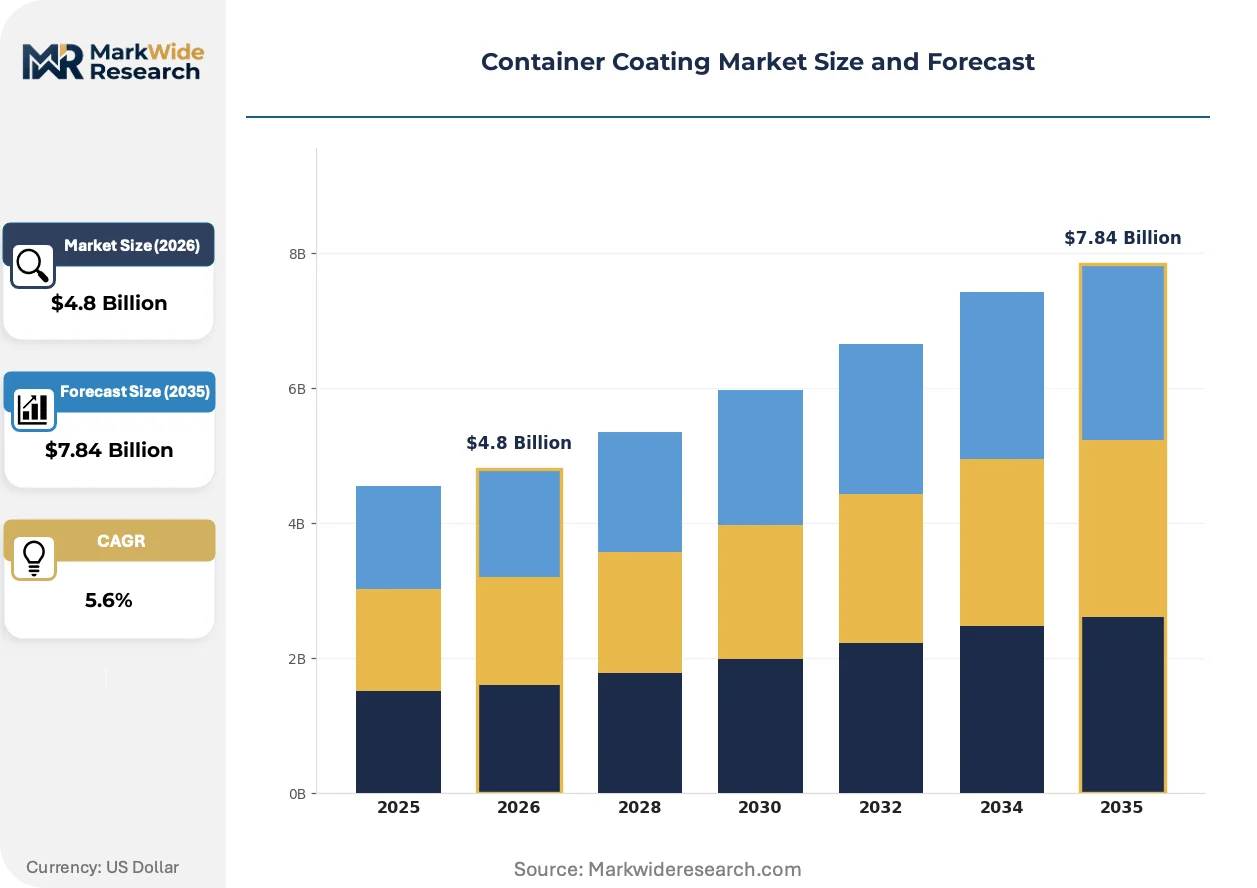
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyurethane, Acrylic, Alkyd Application: Food Packaging, Chemical Storage, Beverage Containers, Pharmaceutical Packaging Material Type: Steel, Aluminum, Plastic, Glass End User: Manufacturing, Food & Beverage, Pharmaceuticals, Personal Care |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., Chugoku Marine Paints, Ltd., KANGNAM JEVISCO CO., LTD., Axalta Coating Systems, LLC, Kansai Paint Co., Ltd., Ultrimax Coatings, Nordson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Coating Market Emerging Trajectories
Waterborne epoxy technology is overtaking solvent-borne dominance in regulatory-sensitive segments, while digital specification tools and biocide-free formulations are compressing traditional competitive moats across maritime and food-contact applications.
Waterborne epoxy systems are achieving functional parity with solvent-borne alternatives in C4 corrosion environments through advanced curing agent chemistry. Major fleet operators in Northern Europe are specifying these formulations for new-build containers to preempt REACH enforcement actions. This transition is overtaking incumbent solvent-borne suppliers in tender competitions where environmental compliance scores determine award criteria.
ECHA substance restrictions under REACH Annex XVII are eliminating bisphenol-A diglycidyl ether from food-contact epoxy formulations by 2026. Coating manufacturers are accelerating bio-based epoxy development to maintain pharmaceutical and food container certifications. European suppliers with established ECHA pre-registration dossiers are capturing reformulation contracts from competitors facing registration gaps.
Container fleet procurement is consolidating through direct technical partnerships between coating suppliers and top-tier maritime operators. Traditional distributor networks are losing specification influence as engineering teams centralize coating selection through digital platforms. This pattern concentrates most visibly in Singapore and Hamburg, where large fleet managers are unbundling coating procurement from general maintenance contracts.
Container Coating Market Segmentation
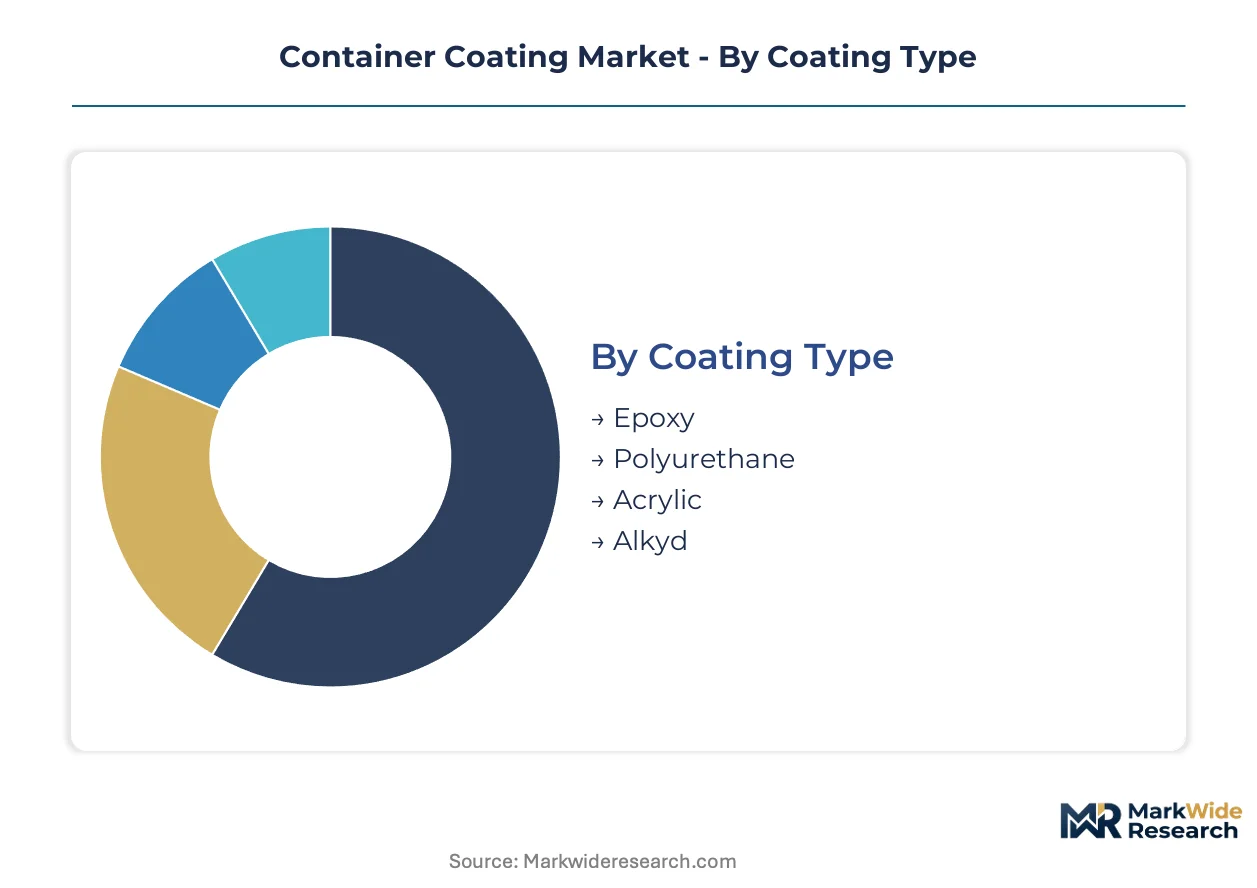
Coating specification varies sharply across container substrates and end-use compliance requirements. Technical segmentation reveals where formulation investments concentrate and which material transitions are reshaping procurement patterns.
Coating Type:
Capital intensity escalates with curing complexity and regulatory certification burdens.
- Epoxy:Two-component thermoset systems achieve 80-200 micron dry-film thickness with ISO 12944 C5-M salt-spray certification. Demand concentrates in Shanghai and Rotterdam maritime clusters where fleet operators mandate corrosion resistance across 15-year service cycles.
- Polyurethane:Flexible cure chemistry enables thinner film builds with lower odor transfer characteristics. German and Japanese beverage container manufacturers specify these formulations for aluminum substrates where food-contact migration limits tighten.
- Acrylic:Waterborne dispersion technology dominates decorative and light-duty applications.
- Alkyd:Solvent-borne oxidative cure systems retain niche presence in legacy steel drum fabrication.
Most installed capacity flows through Epoxy. Expansion is steepest in Polyurethane.
Application:
Regulatory jurisdiction determines formulation cost tiers more than substrate chemistry.
- Food Packaging:Direct-contact coatings face FDA 21 CFR 175.300 and EFSA migration limit protocols. REACH Annex XVII bisphenol-A restrictions are forcing European suppliers into bio-based epoxy redevelopment.
- Chemical Storage:Aggressive media resistance requires specialized novolac epoxy modifications. Singapore and Houston petrochemical clusters drive specification for solvent-resistant tank internals.
- Beverage Containers:Lightweight aluminum designs in Germany and Japan expand coating surface area per unit.
- Pharmaceutical Packaging:EMA and FDA cGMP compliance adds validation layers to coating selection.
Food Packaging commands the highest certification overhead. Beverage Containers are climbing the fastest as aluminum penetration accelerates.
Material Type:
Substrate density and surface preparation requirements reshape coating viscosity and application equipment economics.
- Steel:Abrasive blast profiling to Sa 2.5 standards precedes multi-layer epoxy builds. Chinese Yangtze River Delta manufacturing clusters anchor global volume for new-build maritime containers.
- Aluminum:Conversion coating pretreatment replaces blast cleaning, reducing capital equipment footprint. Japanese beverage can lines specify these substrates for weight reduction in distribution logistics.
- Plastic:Corona or plasma surface activation enables adhesion on polyolefin substrates.
- Glass:Silane coupling agent chemistry addresses low-surface-energy challenges.
Steel retains dominant installed base. Aluminum shows steepest expansion trajectory.
End User:
Procurement centralization varies with fleet scale and regulatory exposure.
- Manufacturing:Industrial container fleets in Singapore and Hamburg consolidate coating specification through direct supplier partnerships.
- Food & Beverage:Migration limit compliance drives dual-track FDA-EFSA certification investments.
- Pharmaceuticals:EMA oversight adds batch validation requirements.
- Personal Care:Fragrance and cosmetic compatibility testing extends qualification timelines.
Manufacturing channels most procurement volume. Food & Beverage faces the steepest regulatory escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container coating manufacturing originated in post-war Japan and expanded through German and Dutch maritime engineering clusters before consolidating in Chinese port cities during the 2000s infrastructure boom.
China
Port infrastructure expansion along the Yangtze River Delta drives container production capacity scaling. MEE enforcement of dual carbon goals tightens VOC emission thresholds for coating application facilities. Shanghai manufacturing clusters anchor global volume for new-build maritime containers serving export trade lanes.
Germany
Lightweight beverage container designs expand aluminum substrate coating demand. ECHA REACH Annex XVII restrictions on bisphenol-A derivatives force reformulation investments across food-contact epoxy systems. Hamburg fleet operators consolidate procurement through direct technical partnerships with compliant suppliers.
United States
Petrochemical storage tank specifications drive novolac epoxy modifications for aggressive media resistance. EPA oversight of marine coating emissions intersects with FDA 21 CFR 175.300 migration limits for food-contact applications. Houston-area industrial clusters concentrate chemical-resistant coating demand from energy sector operators.
Japan
Maritime coating expertise accumulated over decades anchors Asian supply relationships for corrosion-resistant formulations. METI industrial standards govern salt-spray performance certification timelines. Kansai manufacturing centers concentrate specialized curing chemistry knowledge for low-VOC epoxy development.
Singapore
Fleet renewal programs among maritime operators create sustained coating demand for new-build steel units. The country's national maritime regulator enforces ballast water management standards that intersect with hull coating specifications. Port terminal operators centralize coating procurement decisions through engineering platform specifications.
Container Coating Market Vendor Landscape
The competitive structure tilts toward diversified chemical conglomerates with established regulatory compliance infrastructure. Market concentration remains moderate, with formulation expertise and certification timelines creating defensive moats around incumbent positions. Two strategic archetypes dominate: integrated coatings divisions of multinational chemical groups, and specialized marine paint manufacturers with concentrated maritime expertise. Competitive moves center on low-VOC formulation licensing agreements and direct technical partnerships with fleet operators displacing traditional distribution channels.
Among diversified coatings conglomerates, PPG Industries and Akzo Nobel occupy positions defined by regulatory infrastructure breadth across multiple jurisdictions. Chugoku Marine Paints exemplifies the specialized maritime archetype, with company structure indicating concentrated technical focus. These three entities represent the competitive spectrum from global compliance scale to regional application expertise, with positioning determined by ECHA dossier depth and ISO 12944 certification portfolios rather than manufacturing scale alone.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Chugoku Marine Paints, Ltd. |
| KANGNAM JEVISCO CO., LTD. |
| Axalta Coating Systems, LLC |
| Kansai Paint Co., Ltd. |
| Ultrimax Coatings |
| Nordson Corporation |
| Others |
Supply Flow & Price Mechanics
Waterborne epoxy curing chemistry is simultaneously compressing formulation margins and redistributing supply power toward suppliers with proprietary low-VOC certification portfolios. This transition concentrates procurement leverage among fleet operators in Rotterdam and Shanghai who can mandate compliance thresholds while squeezing commodity coating tiers.
Pricing Analysis
Coating procurement is splintering between bundled fleet-maintenance contracts and unbundled technical-specification awards. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 12944 certification grade and REACH pre-registration status. Cost compression in standard epoxy tiers is intensifying because Chinese manufacturing clusters are internalizing application services. Chemical storage operators show lowest price sensitivity due to novolac modification requirements, while general freight fleets drive aggressive tender competition.
Supply Chain Analysis
Container refurbishment flows from European and North American depots back to Asian recoating facilities are creating dedicated reverse-logistics lanes for steel substrate reprocessing. Epoxy resin production draws from petrochemical complexes in the US Gulf Coast, Northeast Asia, and the Middle East. Supply chain risk centers on bisphenol-A feedstock restrictions under REACH Annex XVII. Distribution runs through direct technical partnerships with large fleet operators, displacing traditional distributor networks in Singapore and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's 2026 bisphenol-A phase-out deadline is forcing premature coating replacement cycles across European food-contact fleets.
For Market Incumbents: Extend ECHA dossier depth into bio-based epoxy pre-registrations before reformulation contracts consolidate. Acquire specialized curing chemistry talent in Kansai and Rotterdam technical centers to offset workforce attrition. Threat of ISO 12944 certification delays favors suppliers with established salt-spray testing infrastructure. For New Entrants and Emerging Players: Enter via biocide-free antifouling formulations for European fleet maintenance, where EU Green Deal incentives create preference premiums. Aluminum beverage substrate coatings in Germany and Japan offer the most penetrable expansion corridor. Go-to-market leverage rests on digital specification platform partnerships with engineering teams at Hamburg and Singapore fleet managers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier coating formulators lacking REACH Annex XVII compliance infrastructure. Long-term viability favors entities with captive ECHA registration capabilities and ISO 12944 C5-M certification portfolios. Signal to track: acceleration of direct procurement unbundling from general maintenance contracts at top-twenty fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Pre-Registration | Establishes regulatory moat before ECHA's bisphenol-A deadline eliminates non-compliant suppliers. |
| Backward Integration into Epoxy Resin | Captive supply of low-VOC curing agents insulates margin pressure from petrochemical feedstock volatility. |
| Digital Specification Platform Partnership | Engineering platform integration with Hamburg and Singapore fleet operators displaces distributor intermediation. |
| Aluminum Substrate Coating Capacity | Lightweight beverage container demand in Germany and Japan expands addressable surface area per unit. |
| Biocide-Free Formulation Development | EU Green Deal sustainability premiums reward non-biocidal antifouling systems in European fleet maintenance. |
Methodological Framework
Direct dialogue with coating formulators, fleet procurement directors, ECHA regulatory consultants, and marine engineering specification teams grounded qualitative findings. Secondary validation drew from ECHA substance restriction dossiers, ISO 12944 certification registries, customs trade data for epoxy resin flows, and SEC filings from diversified coatings conglomerates. Bottom-up volume estimates from individual manufacturing clusters triangulated against top-down market sizing from trade lane throughput projections.
Top-down demand modeling from maritime fleet renewal schedules cross-checked against bottom-up coating consumption rates per twenty-foot equivalent unit. Segmentation dimensions span coating type, substrate material, end-use application, and regional regulatory jurisdiction. CAGRs were derived from regression analysis of historical fleet replacement cycles and projected port infrastructure expansion across the analysis window. Forecast inputs incorporated MEE dual carbon enforcement timelines and ECHA substance restriction phase-out schedules.
Inputs from ECHA pre-registration databases and ISO certification registries were available through the study window; gaps in proprietary formulation cost structures introduce uncertainty bands around margin projections. Practitioners should monitor REACH enforcement actions and fleet operator procurement unbundling announcements for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Food Containers Market
Containers
Half Height Containers Market
Containers
Square Pails Market
Containers
Flexible Water Tanks Market
Containers
Global Container Monitoring Market
Containers
Foldable Large Containers Market
Containers
Thin Wall Containers Market
Containers
Vials Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Wide Mouth Jars Market
Containers
Durable Insulated Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Gable Top Container Market
Containers
USA and Canada Packer Bottle Market
Containers
PET Containers Market
Containers
Lab Storage Container Market