
 Grab and Go Containers Market | 2026-2036
Grab and Go Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Grab and Go Containers Market Foresight
Aftermarket recycling and collection revenue is fragmenting across third-party logistics networks and retail take-back schemes. Huhtamaki leverages its European thermoforming footprint to control high-margin custom formats. Dart Container Corporation dominates North American foam and hinged-lid production through captive resin sourcing. Berry Global extends its flexible film leadership into mono-material pouch structures for food delivery brands.
Grab and go containers are single-use or limited-reuse vessels engineered for prepared food portability, typically specifying leak resistance to 30 kPa, temperature tolerance from -40°C to 120°C, and compliance with FDA or EFSA migration limits for food contact. Their primary commercial purpose is preserving food safety and sensory quality during uncontrolled ambient exposure between retail handoff and consumption. Thermoformed containers lead unit volume due to low per-piece tooling cost and rapid changeover for seasonal SKUs. Biodegradable plastics represent the fastest-expanding material class as composting infrastructure scales in France and Italy. Flexible bags occupy the thinnest margin pool, commoditized by Asian converters with vertically integrated blown film lines.
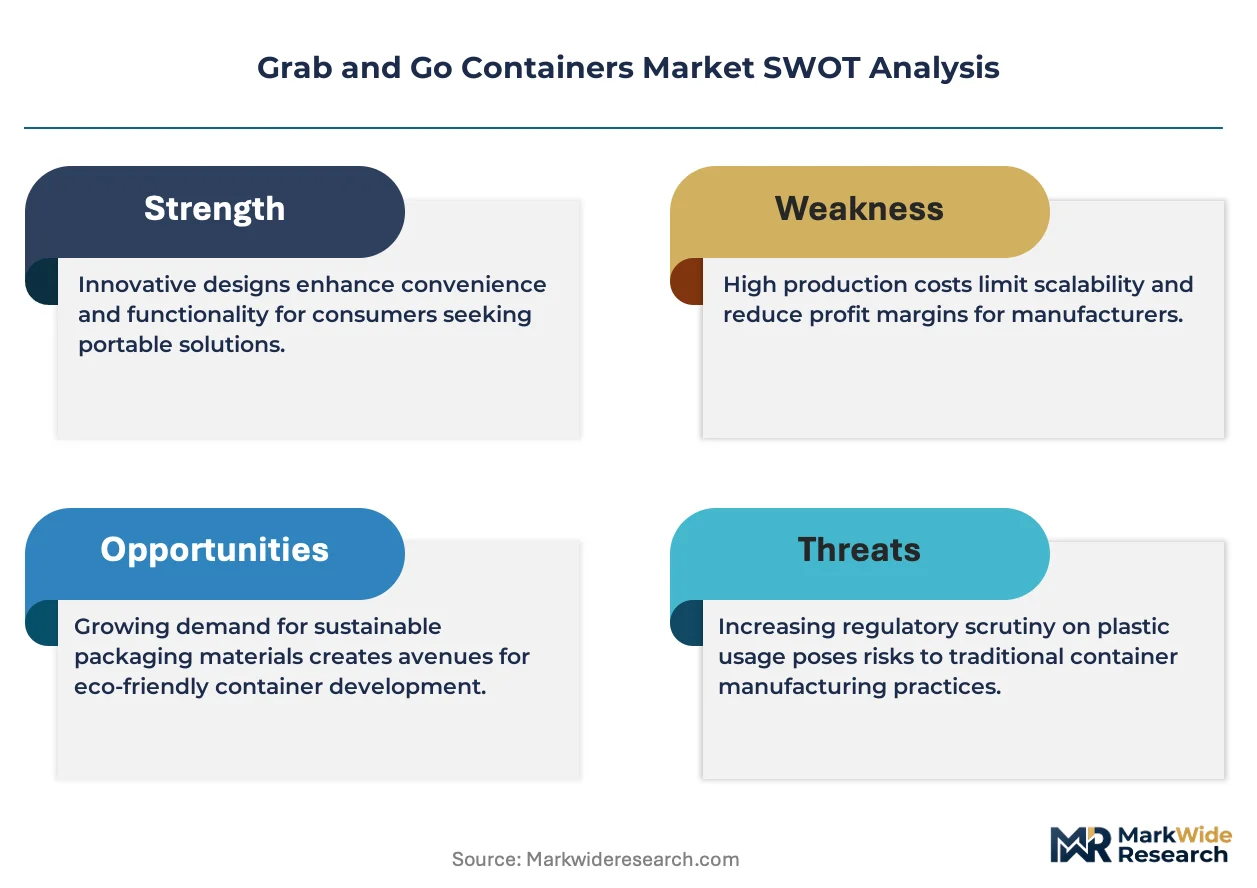
The EU F-Gas Regulation and REACH chemical restrictions constrain fluorinated grease barriers in paper-based formats, redirecting R&D toward PLA and PHA biopolymer coatings. The US FDA maintains 21 CFR 177 food contact notification requirements that delay new material qualification by 12-18 months, sheltering incumbents with approved substance inventories. Stakeholders must monitor pending US state-level extended producer responsibility laws that would shift collection cost liability from municipalities to packaging suppliers.
Market Dynamics
The EU Single-Use Plastics Directive is compressing lead times for biodegradable material qualification while fragmenting converter margins across legacy and next-generation production lines. Thermoformers with captive biopolymer sourcing now capture pricing power previously held by resin distributors.
Growth Catalysts
- Quick-service cold-chain expansion:North American fast-casual chains are scaling grab-and-go prepared meal programs, driving procurement of dual-ovenable containers with integrated venting.
- REACH chemical restrictions:The EU's tightening limits on fluorinated grease barriers in paperboard formats are redirecting foodservice R&D toward PLA and PHA barrier coatings with composting certification.
- Biopolymer coating advances:Italian and French composting infrastructure scale-up is enabling commercial volumes of aqueous-coated fiber bowls that withstand 120°C hot-fill applications.
Market Restraints
- Resin price volatility:Fossil-based polypropylene and polystyrene input costs swing with crude oil indices, compressing margins for non-integrated thermoformers in Germany's foodservice corridor.
- FDA notification timelines:The US 21 CFR 177 food contact substance approval process extends 12-18 months, sheltering incumbents with grandfathered substance inventories and delaying new entrant commercialization.
- Composting infrastructure gaps:Biodegradable container adoption outruns industrial composting facility coverage in Eastern European markets, creating collection and contamination risks for foodservice operators.
Strategic Opportunities
- Extended producer responsibility tailwinds:Pending US state-level EPR legislation would shift collection cost liability from municipalities to packaging suppliers, favoring vertically integrated converters with established take-back logistics.
- Mono-material flexible pouches:Food delivery platforms in urban India are piloting recyclable polyethylene pouch structures that replace multi-layer laminates in ready-meal distribution.
- Smart packaging convergence:Integration of time-temperature indicators with thermoformed lids is enabling premium positioning in Japanese convenience store chains with strict cold-chain compliance requirements.
Industry Challenges
- Biopolymer processing expertise scarcity:PLA and PHA thermoforming requires distinct temperature and moisture control protocols versus conventional resins, constraining workforce availability in European converter networks.
- Legacy equipment retooling costs:Transitioning existing form-fill-seal lines to handle thinner-gauge biodegradable films demands capital outlays that mid-tier converters struggle to finance without offtake guarantees.
- Cross-border certification complexity:Divergent compostability standards between BPI in North America and TÜV OK Compost in Europe force dual testing protocols for multinational food brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grab and Go Containers Market |
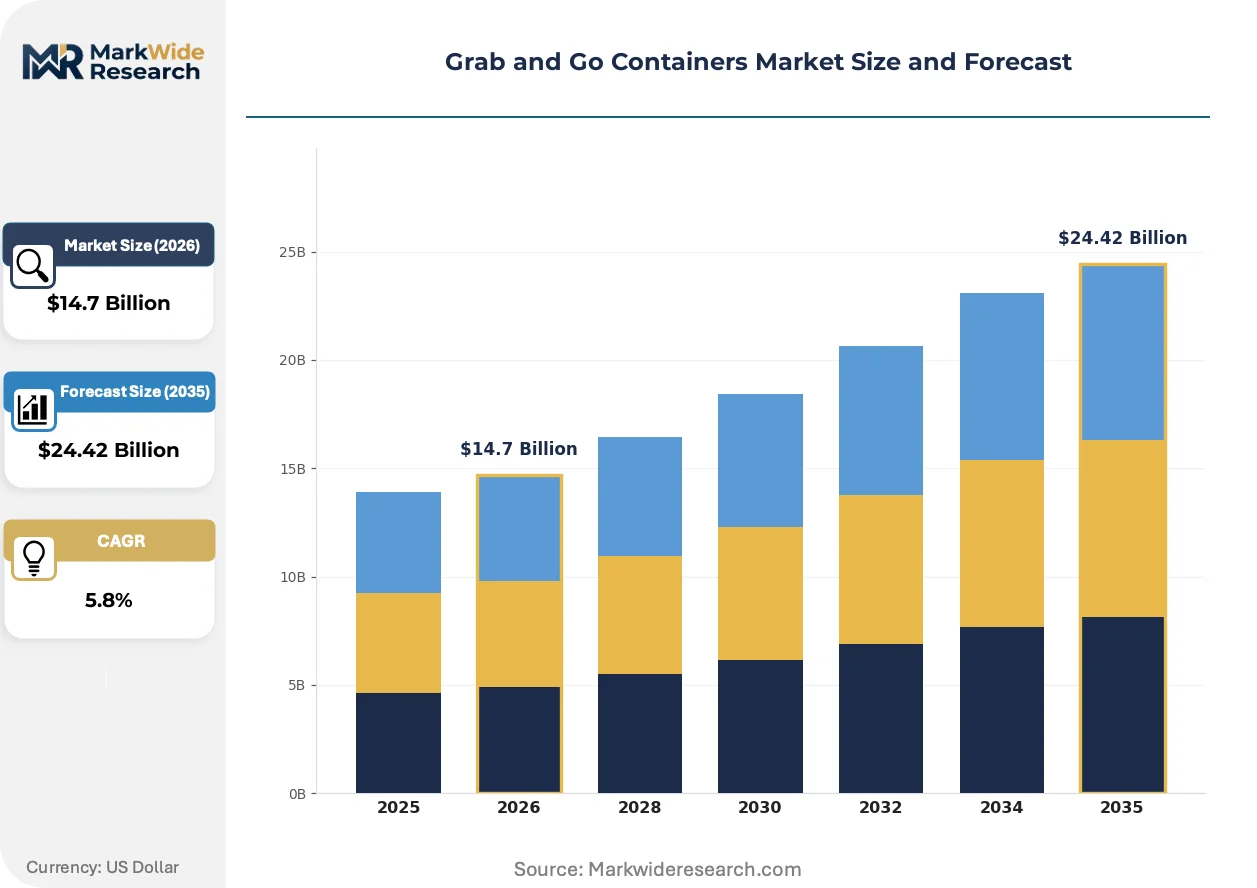
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Plastic Boxes, Thermoformed Containers, Glass Jars Material: Polyethylene, Polypropylene, Biodegradable Plastics, Glass End User: Restaurants, Catering Services, Retail Stores, Food Delivery Services Size: Small, Medium, Large, Custom |
| Companies Covered | Amcor plc, Berry Global, Huhtamaki, Sealed Air, Pactiv Evergreen, Dart Container Corporation, WestRock, Genpak, Sabert Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grab and Go Containers Market Shifts & Advancements
Digital design workflows and bio-based material platforms are compressing product development cycles while fragmenting the traditional converter-customer relationship. Three developments are restructuring competitive advantage.
Thermoformed container design is virtualizing through cloud-native CAD-to-tooling platforms that collapse prototype-to-production timelines from weeks to days. Mid-size food brands in the UK and Netherlands are adopting these systems to execute seasonal SKU rotations without minimum order penalties. The technology is virtualizing the economics of short-run customization, eroding volume-based pricing power held by large-format thermoformers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in expanded polystyrene production, forcing German and French converters toward CO2-based physical blowing agents or alternative rigid formats. This industrial consequence is elevating capital requirements for foam container manufacturing while advantaging fiber-based competitors with established pulping infrastructure. Quick-service chains with pan-European supply contracts are consolidating procurement around converters with certified low-GWP production lines.
Centralized procurement consolidation among multinational foodservice operators is compressing supplier rosters and demanding volume-flexible contract terms. Regional distributor networks in Italy and Spain are losing share to direct manufacturer relationships as buyers seek price transparency and sustainability data traceability. This pattern is most visible in the ready-meal segment, where private-label brands now specify blockchain-tracked packaging origin as a procurement criterion.
Grab and Go Containers Market Segmentation
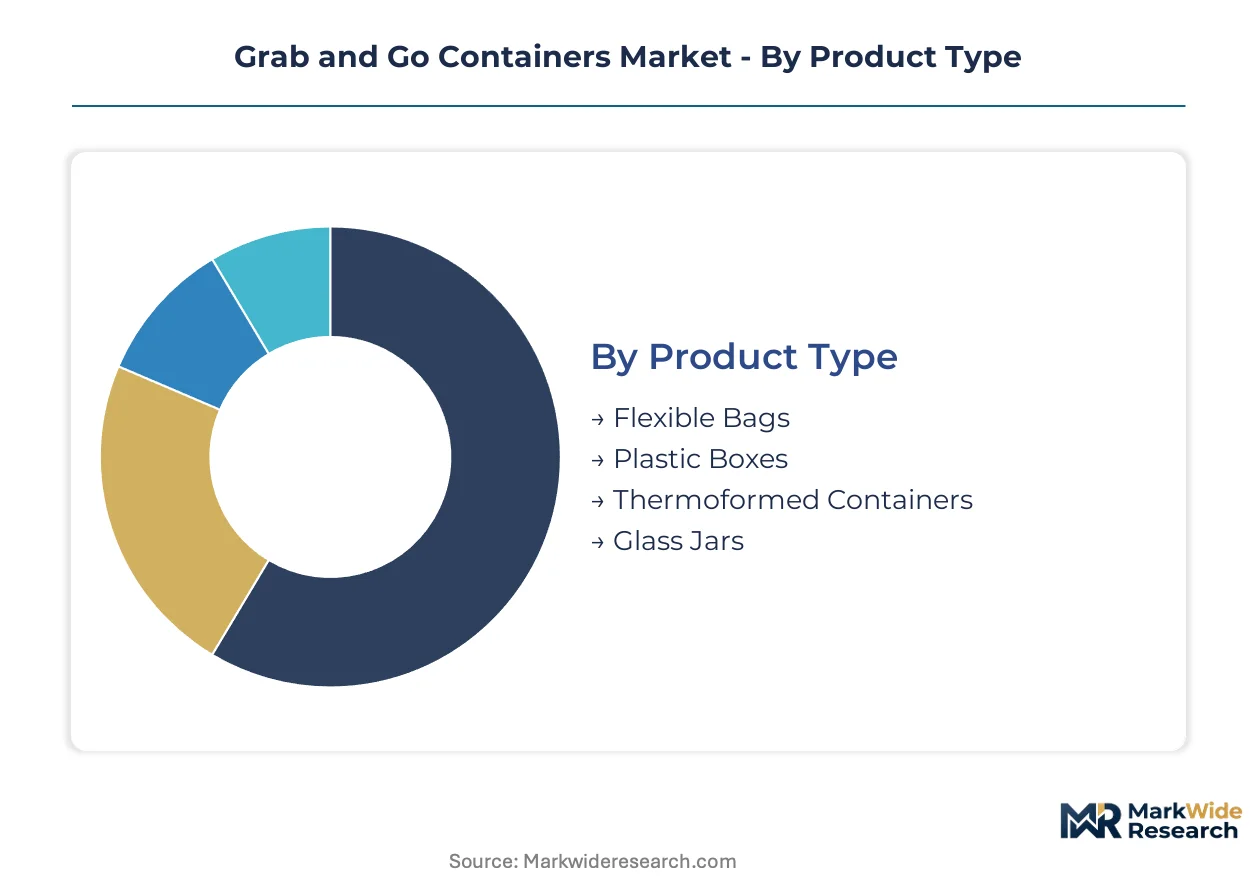
Product architecture in grab and go containers determines thermal performance specifications, regulatory compliance pathways, and equipment compatibility for foodservice operators. Segmentation by material chemistry and end-use application reveals divergent margin structures and qualification timelines across converter networks.
Product Type:
Cost tier differentiation separates commodity formats from engineered solutions with integrated functional features.
- Thermoformed Containers:Vacuum-formed polystyrene or polypropylene shells specify leak resistance to 30 kPa and temperature tolerance from -40°C to 120°C. Quick-service chains in Germany's foodservice corridor specify these for cold-chain ready meal programs with integrated venting lids.
- Flexible Bags:Multi-layer or mono-material pouches for ambient and refrigerated distribution. Food delivery platforms in urban India pilot recyclable polyethylene structures that replace laminated films in ready-meal logistics.
- Plastic Boxes:Injection-molded hinged-lid formats with snap-seal closures for repeated handling. Catering services specify these for transport durability in high-volume institutional feeding.
- Glass Jars:Reusable vessels with hermetic sealing for premium positioning. Specialty retail channels in France and Italy specify these for artisanal prepared foods with deposit-return schemes.
Thermoformed containers command the established base. The steepest expansion runs through flexible bags.
Material:
Application requirements for temperature exposure and end-of-life disposal route material selection toward distinct regulatory compliance frameworks.
- Biodegradable Plastics:PLA and PHA biopolymers with composting certification per BPI or TÜV OK Compost standards. Italian and French composting infrastructure scale-up enables commercial volumes for hot-fill fiber bowls.
- Polypropylene:Fossil-based resin with FDA 21 CFR 177 clearance and broad thermoforming compatibility. Dart Container Corporation leverages captive resin sourcing to control North American hinged-lid production.
- Polyethylene:Linear low-density and high-density grades for blown film and injection molding. Berry Global extends flexible film leadership into mono-material pouch structures for food delivery brands.
- Glass:Silicate-based reusable format with unlimited recycling loops. Deposit-return infrastructure in Germany and Scandinavia supports closed-loop collection economics.
Polypropylene commands the established base. Biodegradable plastics are climbing the fastest.
End User:
Customer type determines volume concentration, customization requirements, and sustainability data traceability demands in procurement specifications.
- Restaurants:Full-service and fast-casual operators with seasonal SKU rotation needs. UK and Netherlands mid-size brands adopt cloud-native CAD-to-tooling platforms for short-run customization without minimum order penalties.
- Food Delivery Services:Platform aggregators with centralized procurement and blockchain-tracked packaging origin requirements. Urban density in Indian metropolitan markets drives pilot programs for recyclable pouch structures.
- Retail Stores:Supermarket and convenience store private-label programs with strict cold-chain compliance. Japanese convenience store chains specify time-temperature indicator integration for premium positioning.
- Catering Services:Institutional and event feeding operators with transport durability priorities. Volume-flexible contract terms dominate procurement negotiations with multinational foodservice operators.
Restaurants command the established base. Food delivery services are gaining share fastest.
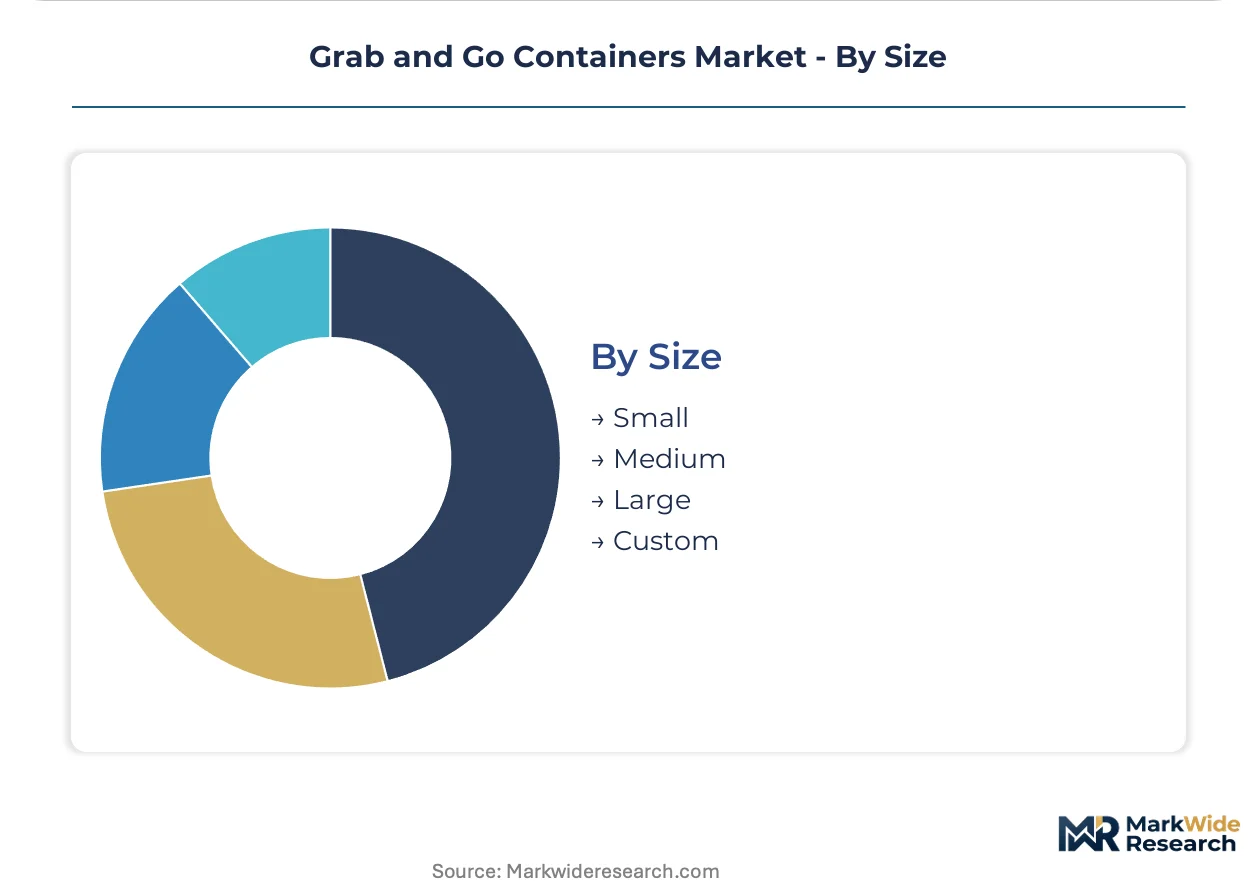
Size:
Volume requirements and equipment standardization create segmentation across portion control and transportation efficiency dimensions.
- Medium:Standardized formats matching automated form-fill-seal line outputs. German thermoformers optimize tooling for this volume tier to minimize changeover downtime.
- Custom:Brand-specific dimensions for proprietary equipment or shelf-space optimization. Seasonal programs in UK and Netherlands food brands drive demand for rapid prototyping workflows.
- Small:Single-serve portions for snack and beverage applications. Quick-service condiment and side-dish specifications concentrate demand here.
- Large:Family-size and bulk formats for catering and institutional channels. Transport weight and stacking efficiency constrain adoption in home delivery networks.
Medium formats command the established base. Custom specifications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter networks cluster in Germany's foodservice manufacturing corridor and North American thermoforming hubs, with emerging capacity scaling in India and Southeast Asia. Regulatory divergence between FDA notification timelines and EU Single-Use Plastics Directive compliance windows fragments qualification pathways across export-oriented suppliers.
United States
Quick-service cold-chain expansion drives dual-ovenable container procurement with integrated venting specifications. FDA maintains 21 CFR 177 food contact substance approval processes that extend 12-18 months. Dart Container Corporation anchors hinged-lid production through captive resin sourcing in Michigan and Ohio manufacturing clusters.
Germany
Foodservice manufacturing corridor concentrates thermoformer capacity for European quick-service supply chains. EU F-Gas Regulation phases down hydrofluorocarbon use in expanded polystyrene production, forcing CO2-based physical blowing agent transitions. Bavarian and North Rhine-Westphalian converter networks face margin compression from biopolymer processing expertise scarcity.
India
Food delivery platforms in Mumbai, Delhi-NCR, and Bangalore pilot recyclable polyethylene pouch structures replacing multi-layer laminates. FSSAI food contact material regulations lag behind composting infrastructure development, creating certification gaps for biodegradable formats. Maharashtra and Karnataka thermoformers scale capacity for domestic ready-meal distribution networks.
Japan
Convenience store chains specify time-temperature indicator integration for premium cold-chain compliance positioning. METI industrial standards guide smart packaging convergence with thermoformed lids. Kanto and Kansai manufacturing belts concentrate high-barrier coating R&D for 120°C hot-fill applications.
France
Composting infrastructure scale-up in Île-de-France and Auvergne-Rhône-Alpes enables commercial volumes of aqueous-coated fiber bowls. REACH chemical restrictions on fluorinated grease barriers redirect foodservice R&D toward PLA and PHA barrier coatings. Paris-based procurement consolidation demands blockchain-tracked packaging origin data from converter networks.
Grab and Go Containers Market Competitive Landscape
Integrated resin-to-format specialists and regional thermoforming networks split the market between margin-capture and volume-flexibility strategies. Three archetypes dominate: captive resin converters with grandfathered FDA substance inventories, cloud-native design platforms enabling short-run customization, and Asian blown-film specialists with vertically integrated polymer supply. Capacity expansion and strategic partnerships represent the dominant competitive moves as EPR liability shifts reshape collection infrastructure economics.
Among North American resin-integrated converters, Dart Container Corporation exemplifies the captive supply archetype through Michigan-based foam and hinged-lid production. Huhtamaki Oyj anchors European thermoforming networks with Finnish-headquartered biopolymer qualification capabilities. Berry Global Inc. occupies the flexible film specialist position, extending mono-material pouch structures into food delivery procurement channels. These three represent divergent responses to regulatory fragmentation between FDA notification timelines and EU composting certification requirements.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Huhtamaki |
| Sealed Air |
| Pactiv Evergreen |
| Dart Container Corporation |
| WestRock |
| Genpak |
| Sabert Corporation |
| Others |
Supply & Pricing Matrix
Crude oil index volatility compresses margins for non-integrated thermoformers while simultaneously widening pricing tier spreads between fossil-based polypropylene formats and certified biopolymer alternatives. This input cost instability forces converters to choose between absorbing margin erosion or passing through resin price swings, reshaping procurement relationships across Germany's foodservice manufacturing corridor and North American quick-service supply chains.
Pricing Analysis
The EU Single-Use Plastics Directive dictates the pricing tier structure across European converter networks, separating grandfathered fossil-based formats from next-generation biopolymer alternatives requiring fresh qualification investments. Three-tier pricing stratification across premium certified-compostable, standard food-grade, and economy non-certified tiers reflects divergent regulatory compliance burdens and material input costs. Pricing pressure stems from biopolymer processing expertise scarcity in Bavarian and North Rhine-Westphalian converter networks, which limits supply elasticity for certified formats. Quick-service chains with centralized procurement functions demonstrate lowest price sensitivity due to sustainability data traceability requirements, while independent foodservice distributors in Italy and Spain face acute cost compression.
Supply Chain Analysis
Upstream fossil-based resin production anchors in Saudi Arabia, the United States, and South Korea, while biopolymer feedstock cultivation concentrates in Brazilian sugarcane regions and Thai cassava processing zones. Raw material dependencies span polypropylene homopolymer grades, PLA lactide monomers, and PHA fermentation feedstocks. Single-source vulnerability runs through European converters lacking captive biopolymer sourcing, exposing margin structures to resin distributor pricing power. Distribution runs through direct manufacturer relationships with multinational foodservice operators, bypassing traditional regional distributor networks in favor of blockchain-tracked packaging origin verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against fiber-based bowl formats and reusable deposit-return glass systems that threaten single-use thermoformed container volumes in French and Italian premium channels.
For Market Incumbents: Build regulatory approval moats through accelerated FDA 21 CFR 177 food contact substance inventories and EU composting certification pipelines. Secure captive biopolymer supply agreements with Brazilian or Thai feedstock processors to isolate margin structures from resin distributor pricing power. Counter fiber-based competitors by embedding smart packaging features—time-temperature indicators, venting lids—into thermoformed formats that aqueous-coated bowls cannot replicate. For New Entrants and Emerging Players: Build out cloud-native CAD-to-tooling platforms serving UK and Netherlands mid-size food brands with seasonal SKU rotation needs and no minimum order penalties. Target India's urban food delivery platforms piloting recyclable polyethylene pouch structures, where FSSAI regulatory lag creates temporary certification windows for innovative formats. Lead with blockchain-tracked packaging origin as a procurement differentiator for multinational operators consolidating supplier rosters. For Investors and Strategic Acquirers: The market sits at a material transition phase that favors converters with dual fossil-and-bio production capabilities and established take-back logistics infrastructure. Long-term viability across the next decade hinges on positioning ahead of pending US state-level extended producer responsibility legislation that would shift collection cost liability to packaging suppliers. Monitor composting infrastructure build-out rates in Eastern European markets as the critical inflection signal for biopolymer format scalability. Cross-checking against industrial composting facility permitting data and municipal collection contract awards is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Qualification Pipeline | Accelerates FDA and EU composting certification timelines to capture pricing premiums before regulatory deadlines tighten. |
| Cloud-Native Design Platform Launch | Enables short-run customization for UK and Netherlands mid-size brands without volume-based minimum order constraints. |
| Captive Resin Sourcing Agreement | Isolates margin structures from crude oil index volatility through backward integration into polypropylene or PLA feedstock. |
| Smart Packaging Integration | Embeds time-temperature indicators into thermoformed lids for Japanese convenience store chains with strict cold-chain compliance. |
| Take-Back Logistics Buildout | Positions converters to absorb extended producer responsibility liability shifts in pending US state-level legislation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across converter networks, foodservice procurement functions, and regulatory compliance roles. Primary interviews captured plant managers at German and North American thermoforming facilities, category buyers at quick-service chain headquarters, and regulatory affairs leads navigating FDA notification timelines and EU Single-Use Plastics Directive compliance windows. Secondary validation drew from customs and trade data, SEC 10-K filings of resin-integrated packaging manufacturers, and BPI and TÜV OK Compost certification registries. Bottom-up volume modeling across material chemistry and end-use segments triangulated against top-down macroeconomic indicators.
Calibration against historical volume trajectories and regulatory implementation schedules anchored projection parameters across the modeling period. Segmentation dimensions spanned product architecture, material chemistry, end-user type, and geographic production cluster, with cross-validation against equipment installation data and form-fill-seal line capacity announcements. CAGRs were derived from segment-level growth rate distributions weighted by base-year volume concentrations, incorporating biopolymer processing expertise scarcity constraints and composting infrastructure coverage gaps as industry-specific dampening factors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Asian blown-film specialists or accelerated EPR legislation implementation by California and New York regulators would shift outcomes beyond modeled ranges. Cross-checking against industrial composting facility permitting databases and municipal collection contract awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pails Market
Containers
Container Liner Market
Containers
Pail Lids Market
Containers
Laminated Bulk Bins Market
Containers
Container Market
Containers
North America Insulated Shipping Containers Market
Containers
Thermoformed Shallow Trays Market
Containers
EPS Container Market
Containers
Pocket Containers Market
Containers
Foldable Steel Containers Market
Containers
Global Food Containers Market
Containers
Belgium Container Glass Market
Containers
Trays Market
Containers
Cubitainer Market
Containers
Stackable Container Market
Containers
Soup Containers Market