
 Asia Pacific Process Automation Market | 2026-2036
Asia Pacific Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Process Automation Market Outlook
Asset-light leasing models for control systems and sensors are reshaping competitive entry barriers across the Asia Pacific Process Automation landscape. ABB Ltd leverages its regional service network to sustain long-term plant automation contracts. Mitsubishi Electric anchors its position through in-house production of precision drives and controllers. Schneider Electric differentiates via integrated software-hardware platforms for energy-intensive process industries.
Asia Pacific Process Automation encompasses engineered systems that monitor, control, and optimize continuous and batch industrial operations through programmable logic controllers, field instrumentation, and real-time data networks operating at millisecond response cycles. These systems reduce unplanned downtime, enforce safety limits, and normalize product quality across variable feedstock conditions. Distributed Control System deployments dominate capital expenditure among technology segments, while Safety Instrumented System demand accelerates fastest as petrochemical complexes expand in Indonesia and Vietnam. Cloud-based Services within the solution dimension capture expanding recurring revenue pools as manufacturers shift from perpetual licenses to subscription operational analytics.
China's MIIT mandates smart manufacturing standards that compel domestic factories to upgrade legacy control architectures. India's BIS certification requirements for industrial electronics restrict market access to tested and labeled automation components. Japan's METI energy efficiency directives sustain demand for advanced process control in refining and chemicals. Stakeholders must weigh regulatory compliance timelines against the capital intensity of retrofitting existing plant floors with connected automation infrastructure.
Market Dynamics
MIIT smart factory directives in China are compressing deployment cycles for distributed control systems, forcing automation vendors to reconfigure service delivery around compliance-driven retrofit timelines rather than organic replacement schedules.
Growth Catalysts
- CDSCO compliance mandates:Pharmaceutical manufacturers across India must install validated batch control systems, expanding Safety Instrumented System procurement in sterile processing facilities.
- Cloud-based operational analytics:Subscription models for predictive maintenance software are displacing perpetual licenses, creating recurring revenue streams for automation service providers.
- Indonesia petrochemical expansion:New olefins complexes in Banten and East Java require integrated process safety systems, concentrating demand for flame and gas detection networks.
Market Restraints
- Semiconductor component concentration:Precision analog chips for field instrumentation rely on concentrated East Asian foundry capacity, exposing lead time volatility.
- BIS certification delays:Industrial electronics testing protocols extend product launch timelines by 8-14 months for unregistered automation vendors.
- Legacy protocol fragmentation:Proprietary fieldbus standards from the 1990s persist in installed bases, complicating interoperability with Ethernet-APL infrastructure.
Strategic Opportunities
- Vietnam electronics manufacturing:Underpenetrated semiconductor fabrication facilities present greenfield demand for ultra-pure gas distribution automation.
- Digital twin convergence:Integration of physics-based simulation with live DCS data streams enables virtual commissioning of process modifications.
- Japan METI carbon accounting rules:Energy-intensive refiners must deploy advanced process control to document emissions intensity per unit output.
Industry Challenges
- OT cybersecurity certification:IEC 62443 compliance for control system networks requires specialized assessors, creating bottlenecks in project handover.
- Legacy DCS migration complexity:Hot-cutover procedures for continuous processes demand extended shutdown windows, compressing implementation margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Process Automation Market |
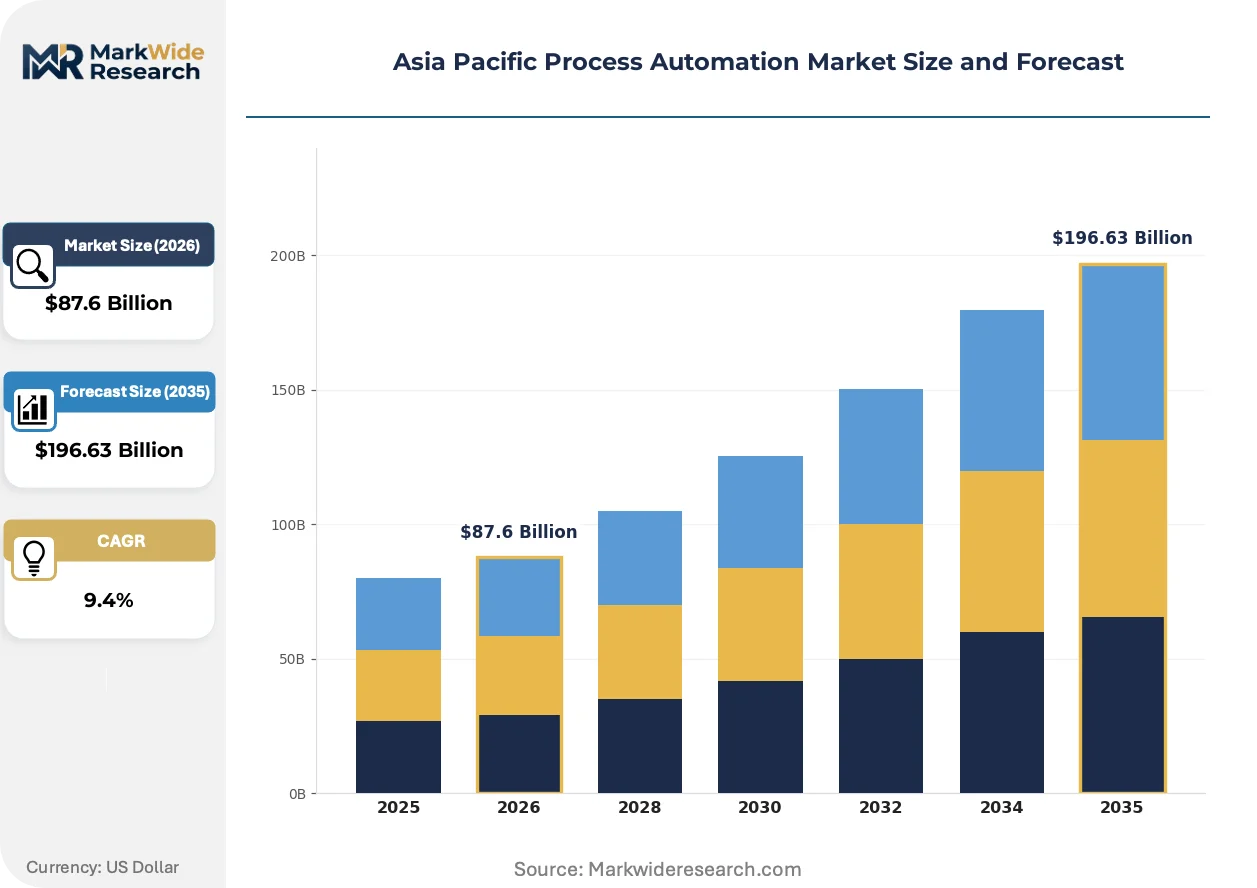
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Distributed Control System, Supervisory Control and Data Acquisition, Human Machine Interface, Safety Instrumented System End User: Oil & Gas, Chemicals, Pharmaceuticals, Food & Beverages Application: Manufacturing Automation, Process Control, Operational Analytics, Asset Management Solution: Control Systems, Sensors, Software Solutions, Cloud-based Services |
| Companies Covered | ABB Ltd, Mitsubishi Electric, Schneider Electric, Emerson Electric Co, Rockwell Automation, Fuji Electric, Siemens AG, Honeywell International Inc, Yokogawa Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Process Automation Market Strategic Shifts
Software-defined architectures are decoupling control logic from proprietary hardware, enabling automation vendors to monetize functionality through subscription layers rather than capital equipment sales alone.
Edge-native control platforms are virtualizing safety and process control functions onto industrial servers, eliminating dedicated controller chassis. Petrochemical operators in China's Zhejiang and Jiangsu provinces are piloting these architectures for greenfield ethylene crackers. This virtualization is compressing hardware refresh cycles while expanding software attach rates per installation.
Japan's METI energy efficiency directives now mandate documented process optimization for designated chemical facilities, compelling refiners to retrofit advanced multivariable control. The regulation specifically targets steam systems and fired heaters, segments where Japanese engineering contractors maintain strong integration capabilities. Domestic automation specialists are responding with packaged APC solutions that accelerate compliance documentation.
Asset-light leasing for sensors and final control elements is displacing traditional capital purchase models among Southeast Asian specialty chemical producers. Regional distributors in Thailand and Malaysia are building subscription revenue through calibrated instrument pools with embedded replacement guarantees. This shift is most visible in agrochemical formulation plants where batch flexibility requirements outpace internal calibration capabilities.
Asia Pacific Process Automation Market Segmentation
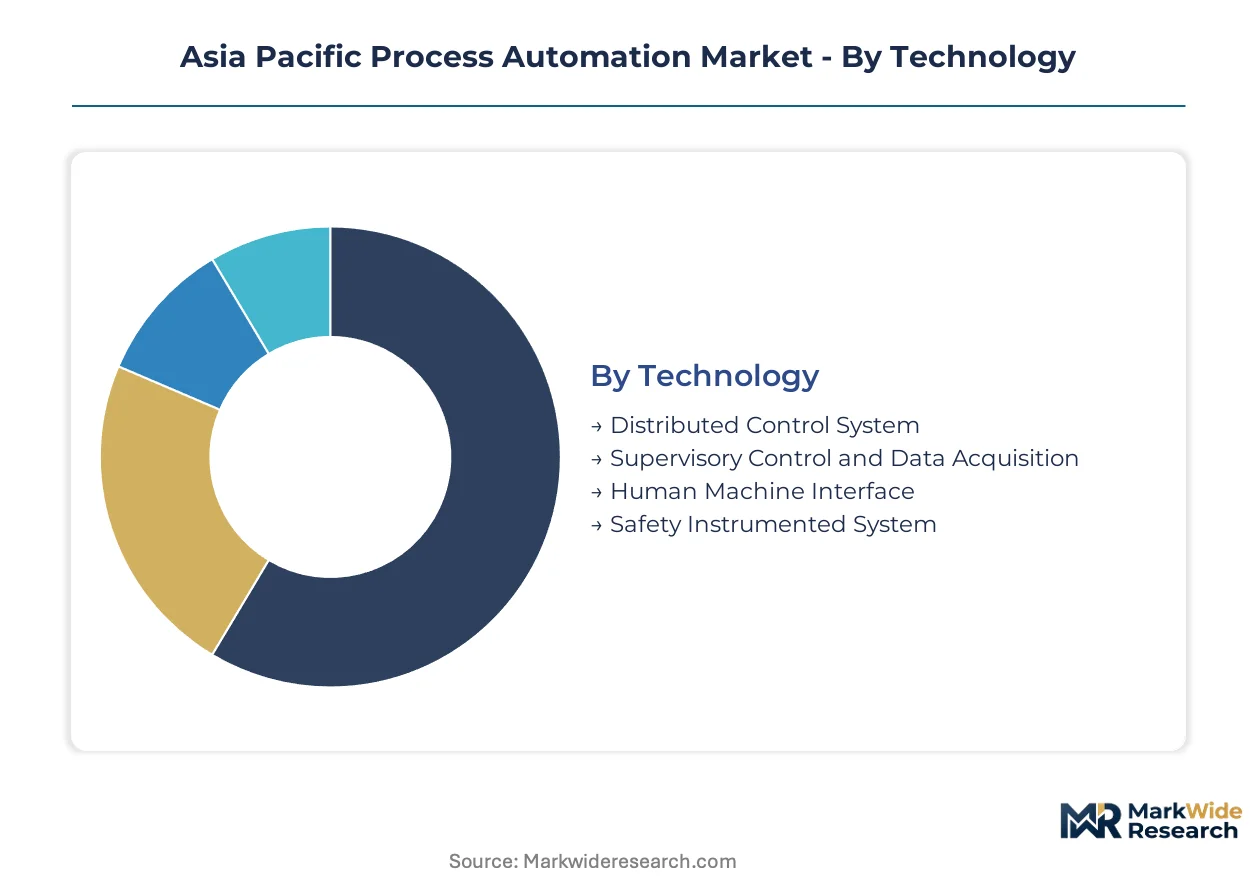
Process automation procurement patterns diverge sharply across technology maturity, regulatory exposure, and capital intensity. Segment boundaries determine vendor pricing power, service attach rates, and retrofit versus greenfield sales mix across Asia Pacific industrial clusters.
Technology:
Use cases span continuous process stability, discrete batch control, operator visualization, and emergency shutdown protection.
- Distributed Control System:Multi-loop process controllers coordinate thousands of I/O points across refinery and petrochemical units. China's coastal manufacturing clusters deploy these systems most densely under MIIT smart factory directives that mandate centralized monitoring architectures.
- Safety Instrumented System:Independent logic solvers enforce safety limits through redundant architectures certified to IEC 61511. Demand concentrates in Indonesia's expanding olefins complexes and India's CDSCO-regulated pharmaceutical sterile processing facilities where functional safety documentation is mandatory.
- Supervisory Control and Data Acquisition:Wide-area telemetry systems aggregate data from geographically dispersed assets.
- Human Machine Interface:Operator workstations and mobile visualization layers simplify complex process interactions.
The dominant share belongs to Distributed Control System, while Safety Instrumented System is closing the gap fastest.
End User:
Capital intensity and regulatory stringency create distinct automation procurement profiles across process industries.
- Oil & Gas:Upstream production, midstream pipelines, and downstream refining operations require explosion-proof instrumentation and SIL-rated safety systems. Australia's offshore LNG facilities and Singapore's refining hub sustain premium automation spend per installed barrel.
- Chemicals:Continuous and batch chemical manufacturing demands precise temperature, pressure, and flow control. Southeast Asian specialty chemical producers in Thailand and Malaysia are shifting toward asset-light sensor leasing models to manage batch flexibility requirements.
- Pharmaceuticals:Validated batch control and electronic record-keeping dominate procurement criteria.
- Food & Beverages:Hygienic design standards and recipe management drive automation specifications.
Oil & Gas commands the largest technology budget, though Pharmaceuticals is expanding most quickly on compliance-driven replacement cycles.
Application:
Functional scope determines hardware-to-software spend ratios and recurring revenue potential.
- Process Control:Real-time regulatory control and advanced multivariable optimization stabilize unit operations against feedstock variability. Japan's METI energy efficiency mandates specifically target steam systems and fired heaters, compelling refiners to retrofit multivariable control packages.
- Operational Analytics:Predictive maintenance and performance optimization software layers extract value from operational data. Subscription pricing models are displacing perpetual licenses across Asia Pacific manufacturing, creating recurring revenue streams for automation service providers.
- Manufacturing Automation:Discrete and hybrid process coordination for assembly and packaging operations.
- Asset Management:Instrument calibration tracking and predictive replacement scheduling.
Process Control retains the deepest installed base, while Operational Analytics shows the steepest expansion trajectory.
Solution:
Delivery models range from capital-intensive hardware ownership to subscription-based service consumption.
- Cloud-based Services:Hosted operational analytics and remote monitoring platforms reduce on-premise infrastructure requirements. Manufacturers across Asia Pacific are migrating from perpetual software licenses to subscription operational analytics, compressing upfront capital needs while expanding vendor recurring revenue.
- Control Systems:Programmable controllers, I/O modules, and network infrastructure form the automation backbone. China's Zhejiang and Jiangsu provinces are piloting edge-native virtualized control for greenfield ethylene crackers, compressing hardware refresh cycles.
- Sensors:Field instrumentation for temperature, pressure, flow, and analytical measurements.
- Software Solutions:On-premise applications for simulation, optimization, and compliance documentation.
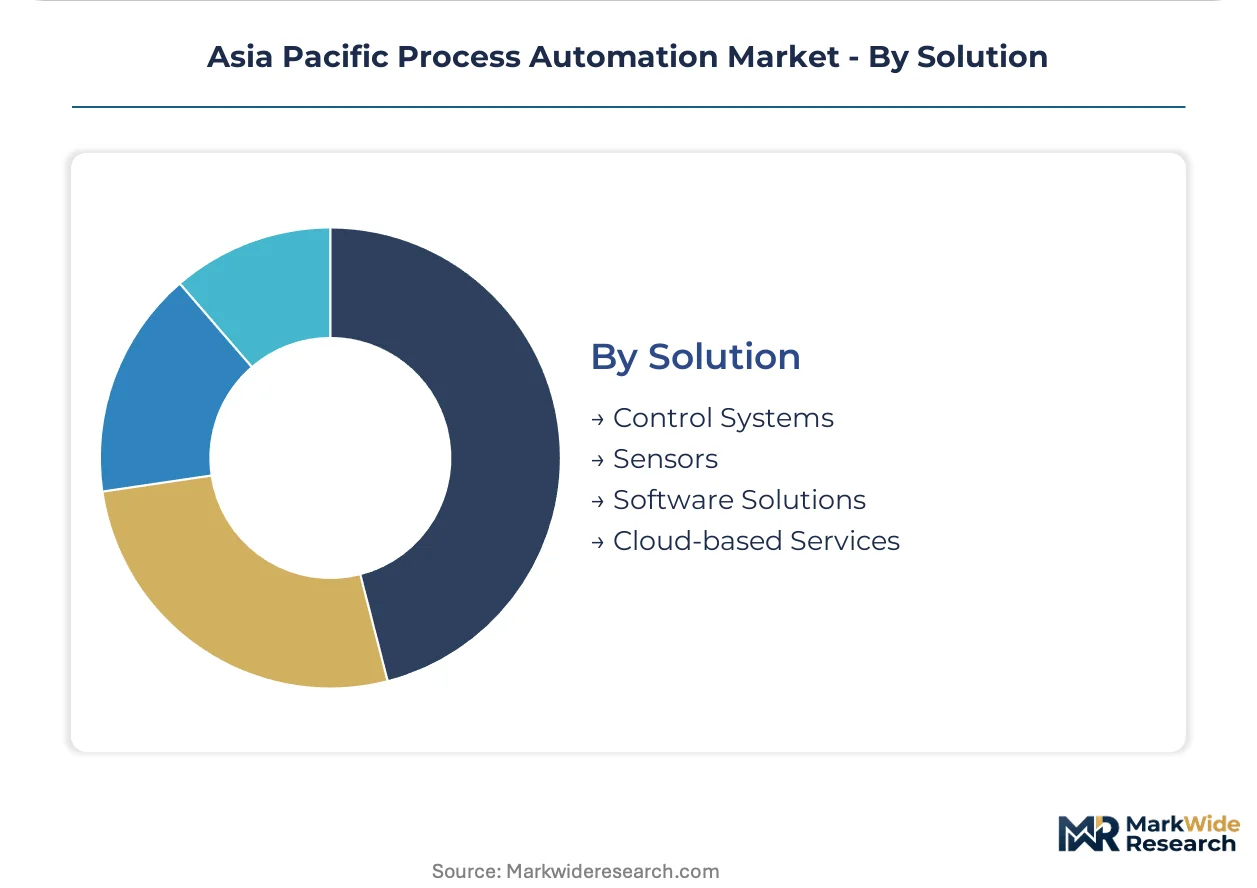
Control Systems still represent the largest revenue pool, yet Cloud-based Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT smart factory directives across China compress deployment timelines for distributed control systems, while India's BIS certification requirements reshape vendor access patterns. Southeast Asian petrochemical expansion and Japan's METI energy efficiency mandates create divergent compliance-driven demand profiles.
China
Zhejiang and Jiangsu province ethylene crackers pilot edge-native virtualized control platforms that eliminate dedicated controller chassis. MIIT mandates compel coastal manufacturing clusters to upgrade legacy architectures with centralized monitoring systems. Shanghai and Ningbo automation service providers report compressed hardware refresh cycles alongside expanded software attach rates.
India
Pharmaceutical sterile processing facilities in Hyderabad and Ahmedabad expand Safety Instrumented System procurement to meet CDSCO validation requirements. BIS certification delays of 8-14 months restrict market access for unregistered automation vendors. Maharashtra and Gujarat chemical producers accelerate automation adoption to satisfy BIS industrial electronics labeling protocols.
Japan
Refiners deploy advanced multivariable control packages to document emissions intensity under METI carbon accounting rules targeting steam systems and fired heaters. Kanto and Kansai industrial corridors sustain premium automation spend as domestic engineering contractors leverage strong integration capabilities. Yokohama-based automation specialists package APC solutions that accelerate compliance documentation.
Indonesia
New olefins complexes in Banten and East Java require integrated flame and gas detection networks for process safety systems. Jakarta-based system integrators concentrate procurement for petrochemical automation infrastructure. Batam manufacturing zones attract sensor leasing models from regional distributors building subscription revenue pools.
Vietnam
Underpenetrated semiconductor fabrication facilities in Ho Chi Minh City and Hanoi present greenfield demand for ultra-pure gas distribution automation. Northern industrial zones near Bac Ninh and Hai Phong attract first-mover automation vendors establishing service networks. Da Nang chemical processing parks expand batch control system procurement for specialty chemical formulation.
Asia Pacific Process Automation Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform providers with regional service networks. Swiss-German engineering conglomerates and Japanese electrical manufacturers anchor the premium tier through captive component production. Three archetypes dominate: vertically integrated hardware specialists, software-hardware platform integrators, and asset-light service orchestrators. Competitive moves center on long-term plant automation contracts and subscription-based operational analytics migration.
Within the integrated platform tier, ABB Ltd leverages its regional service infrastructure to sustain extended plant automation engagements. Mitsubishi Electric anchors its position through in-house production of precision drives and controllers. Schneider Electric exemplifies the software-hardware convergence archetype via integrated platforms targeting energy-intensive process industries.
| Leading Market Players |
|---|
| ABB Ltd |
| Mitsubishi Electric |
| Schneider Electric |
| Emerson Electric Co |
| Rockwell Automation |
| Fuji Electric |
| Siemens AG |
| Honeywell International Inc |
| Yokogawa Electric |
| Others |
Value Chain & Pricing Dynamics
Semiconductor component concentration across East Asian foundries creates dual vulnerability for automation vendors, compressing hardware margins while forcing tiered service pricing that separates certified-system premiums from commodity-equipment baselines. This single-source dependency for precision analog chips reshapes procurement calendars and locks in three-tier pricing stratification across the Asia Pacific Process Automation landscape.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with BIS-tested and IEC 61511-validated systems commanding substantial premiums over unregistered alternatives. Subscription models for cloud-based operational analytics are displacing perpetual licenses, generating recurring revenue streams that offset hardware margin compression. Cost compression in sensor hardware intensifies as regional distributors build asset-light leasing pools with embedded replacement guarantees. Southeast Asian specialty chemical producers exhibit highest price sensitivity due to batch flexibility requirements, while Australian LNG operators sustain premium tolerance for SIL-rated safety systems.
Supply Chain Analysis
Tariff exposure between China and key trading partners dominates supply chain risk calculus for precision drives and controller components. Manufacturing concentration centers on Japan, South Korea, and coastal Chinese provinces for precision analog chips, industrial servers, and field instrumentation. Raw material dependencies span rare earth elements for magnetic drives, high-purity silicon for sensors, and specialized alloys for explosion-proof housings. Distribution runs through regional system integrators in Shanghai, Yokohama, and Jakarta who coordinate procurement for petrochemical and pharmaceutical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
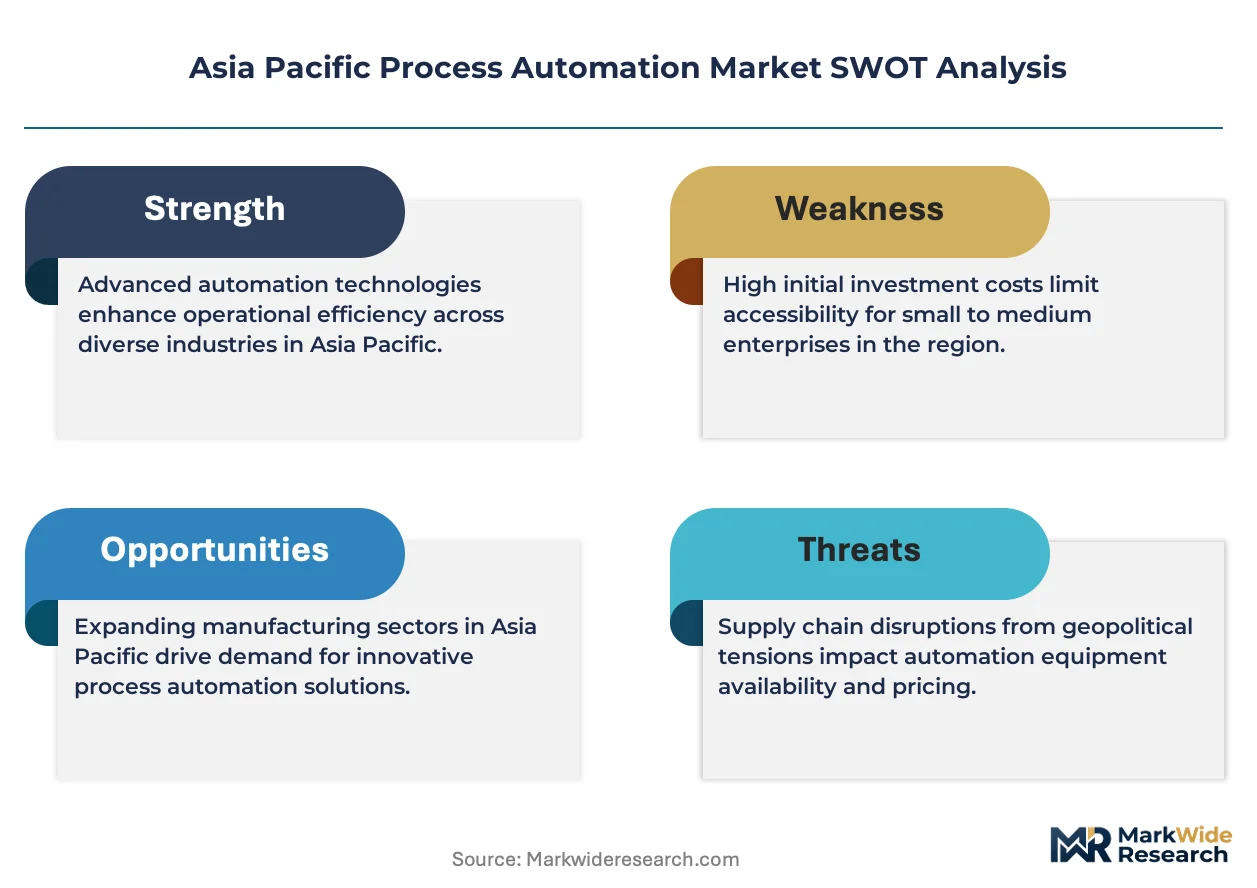
Fragmentation across compliance timelines and technology maturity creates niche entry points for specialized automation providers. Cloud-native architectures and asset-light service models are splintering procurement patterns away from integrated-platform incumbents.
For Market Incumbents: Entrench position through captive certification infrastructure that accelerates BIS and CDSCO compliance timelines for clients. Deepen regional service density in Zhejiang and Jiangsu provinces where MIIT mandates compress retrofit windows. Acquire specialized system integrators in Jakarta and Ho Chi Minh City to preempt emerging-platform competitors from establishing local relationships. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated semiconductor fabrication automation segment before integrated-platform vendors complete service network buildouts. Target sensor leasing models for Thai and Malaysian agrochemical formulators where internal calibration capabilities lag batch flexibility requirements. Lead with edge-native virtualized control pilots that eliminate dedicated controller chassis and compress hardware refresh cycles. For Investors and Strategic Acquirers: Regional system integrators with established CDSCO validation capabilities represent the most defensible acquisition archetype as pharmaceutical compliance requirements intensify. Long-term viability hinges on recurring revenue share from subscription operational analytics rather than capital equipment sales. Watch for inflection when edge-native control pilots in Chinese ethylene crackers demonstrate measurable downtime reduction against legacy DCS architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | BIS and CDSCO pre-validation capabilities accelerate client compliance timelines and lock in long-term service contracts. |
| Edge-Native Control Platform Launch | Virtualized safety and process functions onto industrial servers compress hardware refresh cycles for Zhejiang petrochemical operators. |
| Regional System Integrator Acquisition | Jakarta and Ho Chi Minh City service networks capture Indonesia petrochemical expansion and Vietnam semiconductor greenfield demand. |
| Asset-Light Sensor Leasing Model | Subscription revenue pools with embedded replacement guarantees penetrate Thai and Malaysian specialty chemical batch flexibility requirements. |
| Cloud-Based Operational Analytics Partnership | Hosted predictive maintenance platforms displace perpetual licenses and expand recurring revenue across Asia Pacific manufacturing clusters. |
Study Parameters
A standing panel of plant automation directors, regional system integrators, pharmaceutical validation specialists, and procurement leads at petrochemical operators provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through MIIT directive filings, BIS certification registries, CDSCO compliance documentation, and customs data on industrial electronics imports. Bottom-up installation counts and top-down capital expenditure estimates were triangulated to anchor market sizing.
Scenario-bracketing around regulatory enforcement intensity and semiconductor supply normalization shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, end-use industry, solution delivery model, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical adoption patterns, with specific inputs from METI energy efficiency mandate timelines and Indonesia olefins complex construction schedules.
Sensitivities concentrate around BIS certification processing delays, East Asian foundry capacity allocation, and CDSCO enforcement intensity in pharmaceutical sterile processing. Forecasts reflect documented assumptions on regulatory compliance timelines and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Global Blasting Automation Services Market