
 Global Warehouse Automation Market | 2026-2036
Global Warehouse Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Warehouse Automation Market Outlook
Omnichannel fulfillment networks is reconfiguring how retailers orchestrate inventory flow between stores, warehouses, and last-mile nodes. Daifuku leverages its conveyor and automated storage expertise to anchor large-scale distribution centers across Asia. Swisslog Holding AG competes through deep specialization in robotic piece-picking and pharmacy automation. KION Group sustains manufacturing scale through its industrial truck portfolio and warehouse system integration capabilities.
Warehouse automation encompasses the hardware, software, and control systems that execute material handling, storage, retrieval, and sortation with minimal human intervention, typically integrating programmable logic controllers with sub-millimeter positioning accuracy to optimize throughput density. Its primary commercial purpose centers on compressing order cycle times while expanding inventory cube utilization in high-velocity fulfillment environments. Automated Guided Vehicles and Sortation Systems represent the most capital-intensive product categories, with margin pools concentrating in system integration and aftermarket software services. Artificial Intelligence and Internet of Things technology layers are expanding fastest as operators seek predictive maintenance and real-time slotting optimization.
The EU Machinery Directive and CE marking framework govern equipment safety and electromagnetic compatibility for systems deployed across Europe, while OSHA standards in the United States mandate specific guarding and lockout protocols for robotic work cells. Germany's KBA and France's labor inspectorates are intensifying scrutiny of human-robot collaboration zones, directly shaping sensor and light-curtain specifications. Stakeholders must monitor how divergent AI liability regimes between the European Union and United States influence software architecture decisions and vendor risk allocation.
Market Dynamics
SKU proliferation in e-commerce fulfillment is compressing order cycle time requirements below four hours, forcing operators to reconfigure fixed automation architectures into modular, re-deployable cell-based systems that adapt to demand volatility without full line shutdowns.
Growth Catalysts
- OSHA robotic work cell standards:Clarified guarding and lockout protocols in the United States reduce insurer liability premiums for early automation adopters, accelerating payback calculations for brownfield retrofits.
- Pharmaceutical cold chain expansion:Temperature-controlled biologics distribution demands automated storage and retrieval systems with continuous environmental monitoring, driving specification upgrades in fulfillment networks.
- Pennsylvania distribution cluster density:Concentrated last-mile nodes within seventy miles of major population centers create network effects that justify capital-intensive sortation investments for regional operators.
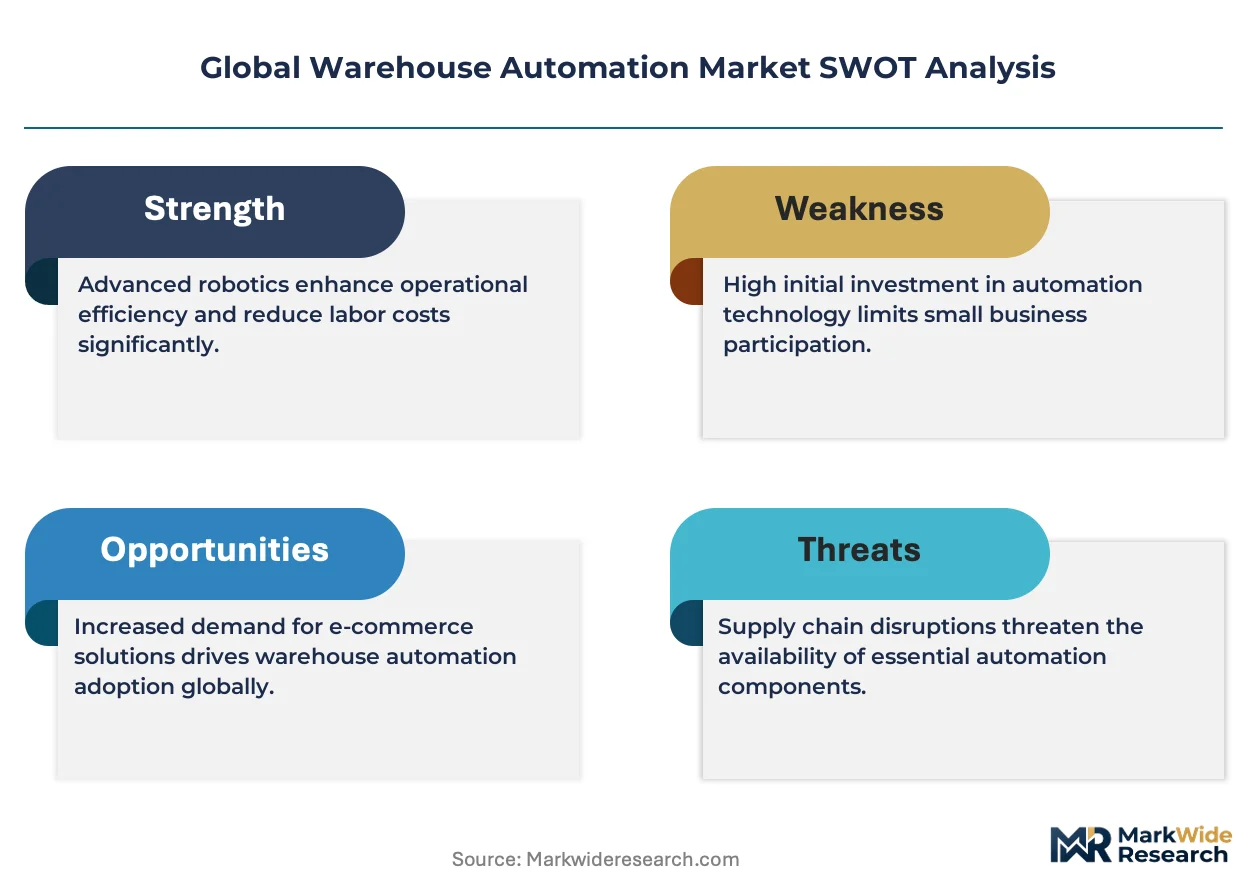
Market Restraints
- Steel and rare-earth magnet input volatility:Permanent magnet costs for linear motor drives fluctuate with Chinese export quotas, destabilizing system integrator quoting and project financing.
- European system integrator concentration:Germany and Italy host over sixty percent of certified high-bay crane manufacturers, creating single-source vulnerability for multi-site rollouts.
- CE marking timeline friction:EU Machinery Directive conformity assessment for AI-enabled sortation now requires notified body intervention, extending deployment schedules by four to six months.
Strategic Opportunities
- India warehouse modernization:The PLI scheme for logistics infrastructure subsidizes automation capex for cold storage and agri-processing, opening a historically manual market to robotic palletizing.
- Computer vision and edge computing convergence:Real-time damage detection and dimensioning at induction points eliminates manual quality stations, reducing labor headcount in high-velocity hubs.
- EU AI Act liability clarity:Risk-based classification of warehouse robotics creates predictable insurance frameworks that encourage vendor risk-sharing through performance guarantees.
Industry Challenges
- Controls engineering talent scarcity:PLC programming and motion control expertise concentrates among technicians over fifty-five, creating succession risk for system commissioning and field service.
- WMS-to-WCS integration complexity:Legacy warehouse management systems lack API-native architectures, forcing expensive middleware development for multi-vendor automation stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Warehouse Automation Market |
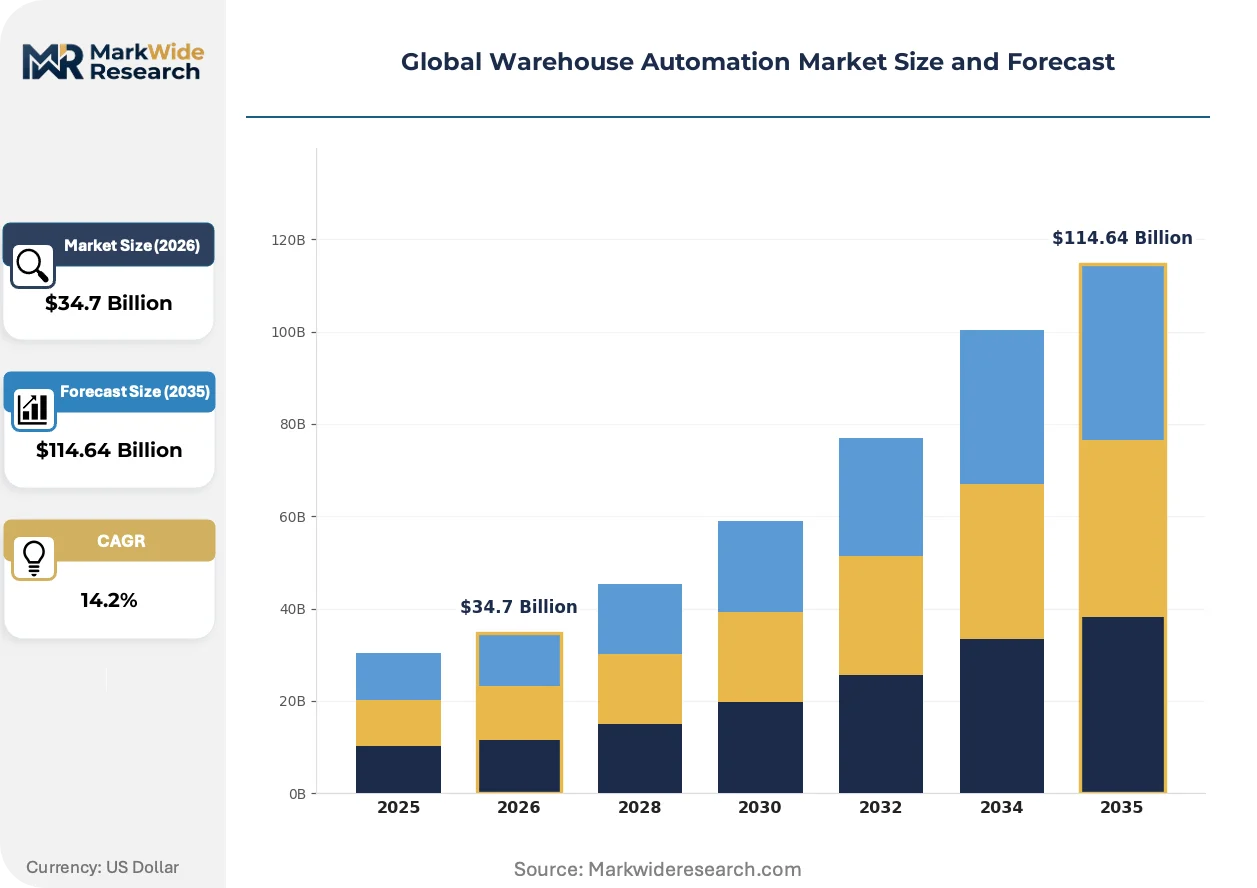
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $114.64 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Conveyor Systems, Sortation Systems Technology: Artificial Intelligence, Machine Learning, Internet of Things, Robotics End User: E-commerce, Retail, Manufacturing, Food & Beverage Distribution Channel: Direct Sales, Online Sales, Distributors, System Integrators |
| Companies Covered | Dematic, Daifuku, Honeywell Intelligrated, Swisslog Holding AG, KNAPP, SSI Schaefer, Murata Machinery, KION Group, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Warehouse Automation Market Strategic Shifts
Artificial intelligence inference at the edge is compressing decision latency from seconds to milliseconds, enabling real-time re-routing of totes and packages without centralized warehouse control system bottlenecks.
Autonomous mobile robots with onboard manipulation capabilities are rendering obsolete fixed conveyor-based induct stations in e-commerce fulfillment centers. Retailers operating seasonal peak volumes are deploying these units within weeks rather than months. The shift collapses infrastructure amortization periods from ten-year horizons to three-year equipment refresh cycles.
The EU AI Act's risk classification framework for autonomous industrial equipment mandates conformity assessment for systems making unsupervised sorting decisions. German KBA inspectors now require documented failure-mode analysis for human-robot collaboration zones. System integrators are responding by pre-certifying sensor fusion architectures rather than custom-designing per installation.
Third-party logistics providers are unbundling automation-as-a-service from facility leases, charging per-touch rather than per-square-foot. This procurement model transfers obsolescence risk to equipment financiers and accelerates refresh cycles. California-based e-commerce operators are the primary adopters, driven by tax treatment advantages for operating versus capital expenditures.
Global Warehouse Automation Market Segmentation
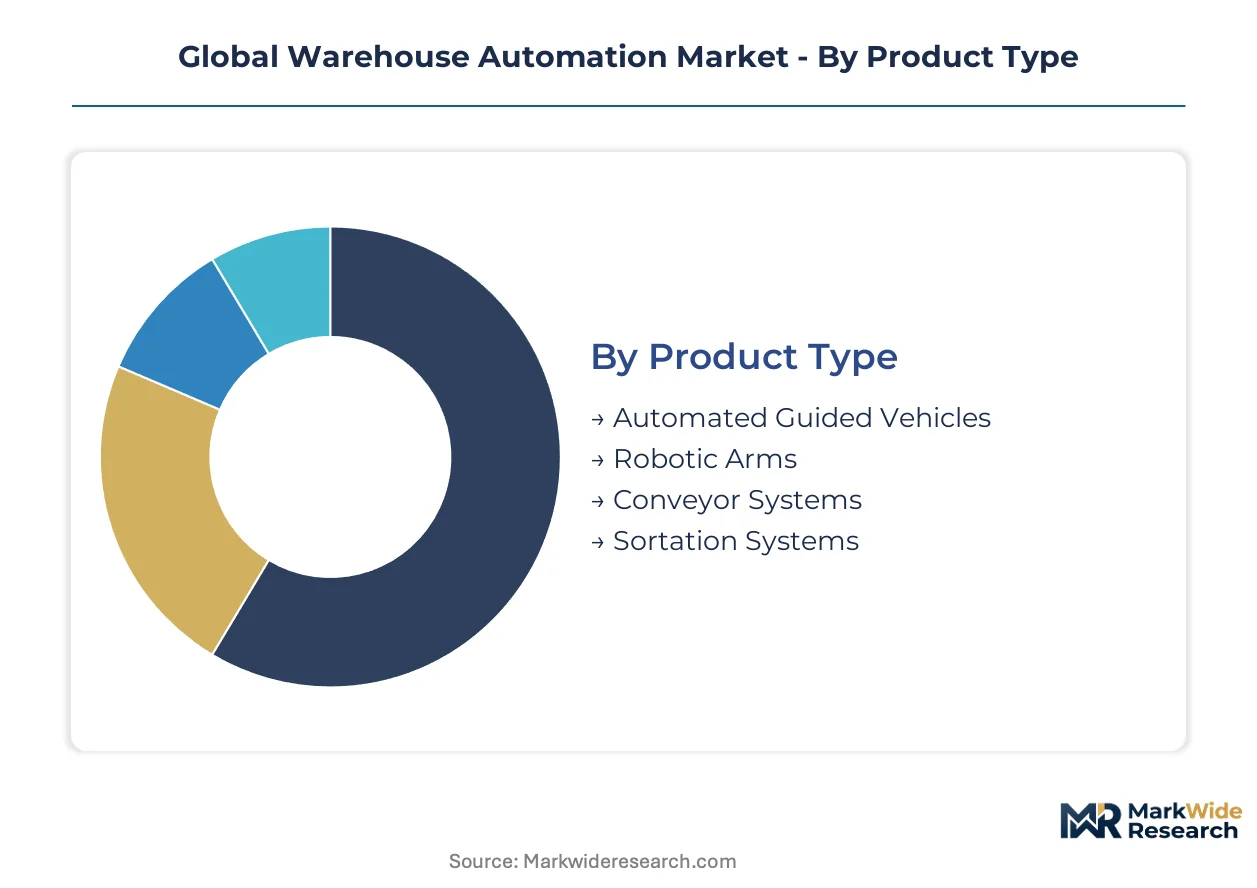
Warehouse automation procurement varies dramatically by velocity profile. High-turnover segments refresh equipment every three years, while fixed infrastructure amortizes over decades. Understanding these divergent replacement cycles shapes vendor strategy and financing structures.
Product Type:
Cycle-time compression distinguishes mobile equipment from fixed infrastructure. Sortation systems turn over fastest as e-commerce peak volumes strain mechanical components. Automated storage cranes operate slowest, with structural steel frames lasting twenty-plus years in climate-controlled environments.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate via magnetic tape, laser triangulation, or vision-based localization. Retailers in California deploy these for seasonal flexibility, collapsing induction station footprints during peak periods. Fleet refresh cycles now run thirty-six months as lithium-ion energy density improves.
- Sortation Systems:Cross-belt, tilt-tray, and sliding-shoe mechanisms achieve throughput exceeding twenty thousand packages hourly. Pennsylvania distribution clusters specify these for same-day delivery commitments. Mechanical wear from polybag handling accelerates component replacement schedules.
- Robotic Arms:Articulated manipulators with six-plus degrees of freedom execute piece-picking and palletizing. Pharmaceutical cold chain operators in Germany favor these for temperature-controlled environments.
- Conveyor Systems:Belt, roller, and accumulation configurations form the backbone of fixed automation architectures. Heavy-gauge steel construction supports fifteen-year depreciation schedules in manufacturing facilities.
Conveyor systems dominate installed base. Sortation systems are where expansion concentrates.
Technology:
Software layers command premium pricing over hardware foundations. Edge computing and AI inference engines attach higher margins than sensor hardware or mechanical actuators. System integrators capture value through proprietary control algorithms.
- Artificial Intelligence:Neural networks optimize slotting decisions, predict equipment failures, and enable robotic grasp planning. Real-time damage detection at induction points eliminates manual quality stations in high-velocity hubs.
- Internet of Things:Sensor networks stream vibration, temperature, and current-draw data to cloud analytics platforms. Predictive maintenance contracts now represent forty percent of vendor recurring revenue.
- Machine Learning:Supervised learning models refine order batching and route optimization based on historical throughput patterns. Demand forecasting accuracy improves pick-face allocation.
- Robotics:Kinematic control systems coordinate multi-axis motion with sub-millimeter repeatability. Collaborative robot installations in France require documented failure-mode analysis under KBA inspector protocols.
Robotics anchors capital expenditure. Artificial intelligence is climbing the fastest as operators seek autonomous decision-making.
End User:
Order velocity and SKU complexity shape automation intensity. E-commerce fulfillment demands the highest touch density per square meter. Manufacturing warehouses prioritize pallet-level throughput over piece-picking precision.
- E-commerce:Omnichannel networks orchestrate inventory across stores, dark stores, and fulfillment centers. Same-day delivery commitments in the United States force sub-four-hour order cycle times. Modular cell-based architectures replace fixed lines to handle demand volatility.
- Retail:Store replenishment and direct-to-consumer hybrid models require flexible sortation. Seasonal volume swings favor redeployable autonomous mobile robots over permanent conveyor infrastructure.
- Manufacturing:Raw material staging and finished goods buffering emphasize pallet-level handling. Automotive suppliers in Germany integrate automated storage with just-in-sequence production lines.
- Food & Beverage:Temperature-controlled storage and retrieval systems maintain cold chain integrity. Automated palletizing in India agri-processing facilities benefits from PLI scheme subsidies.
Manufacturing holds the largest installed base. E-commerce is gaining share fastest as fulfillment networks densify.
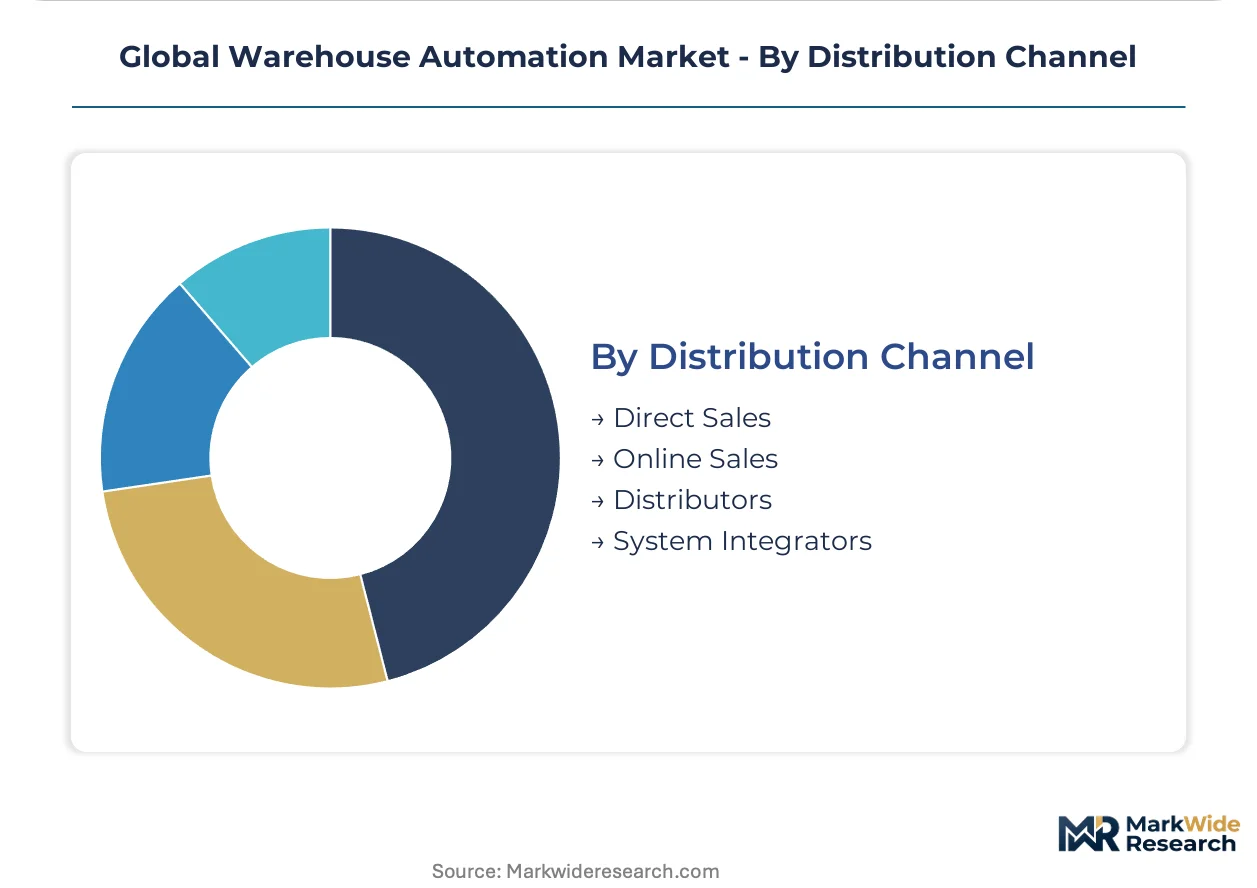
Distribution Channel:
Procurement complexity scales with system integration requirements. Direct relationships dominate large-scale deployments. Intermediaries serve mid-market operators lacking in-house engineering resources.
- System Integrators:Engineering firms design, install, and commission multi-vendor automation stacks. WMS-to-WCS middleware development represents the highest-margin service line. European concentration in Germany and Italy creates single-source vulnerability for multi-site rollouts.
- Direct Sales:Original equipment manufacturers engage Fortune 500 operators for turnkey facility design. Long sales cycles accompany ten-million-dollar-plus project values.
- Distributors:Regional inventory and field service networks support spare parts and retrofit markets. Replacement conveyor components and sensor modules move through this channel.
- Online Sales:Standardized components—light curtains, programmable logic controllers, and safety relays—transact through digital procurement platforms. Small and medium enterprises favor this route for brownfield upgrades.
System integrators dominate project value. Direct sales is where expansion concentrates as vendors seek recurring software revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA robotic work cell standards in the United States anchor the regulatory framework shaping capital deployment decisions across major warehouse automation markets. Equipment certification timelines and labor safety protocols vary sharply between jurisdictions, forcing multi-national operators to maintain parallel compliance architectures.
United States
Pennsylvania distribution clusters within seventy miles of major population centers justify capital-intensive sortation investments for regional operators. OSHA clarified guarding and lockout protocols, reducing insurer liability premiums for brownfield retrofits. California-based e-commerce operators accelerate adoption of automation-as-a-service procurement models.
Germany
Automotive suppliers integrate automated storage with just-in-sequence production lines across Baden-Württemberg and Bavaria. The KBA intensifies scrutiny of human-robot collaboration zones, mandating documented failure-mode analysis for sensor fusion architectures. High-bay crane manufacturers concentrate in Germany, creating single-source vulnerability for multi-site European rollouts.
China
Dual carbon goals and MIIT industrial upgrading directives accelerate robotic palletizing in Yangtze River Delta logistics hubs. GB standards for electromagnetic compatibility govern equipment safety certification. Zhejiang and Jiangsu provinces host dense clusters of conveyor component fabricators serving domestic fulfillment networks.
India
The PLI scheme for logistics infrastructure subsidizes automation capex for cold storage and agri-processing facilities. DGFT import regulations shape equipment sourcing strategies for system integrators. Maharashtra and Gujarat warehouse operators deploy robotic palletizing in historically manual markets.
Japan
METI productivity enhancement programs drive pharmaceutical cold chain automation investments around Osaka and Nagoya. JIS standards for industrial robotics influence sensor specifications across Asia-Pacific deployments. Kanto region fulfillment centers prioritize sub-millimeter positioning accuracy for high-velocity e-commerce operations.
Global Warehouse Automation Market Competitive Environment
Full-system integrators and component specialists split the market between turnkey project execution and modular retrofit supply. The vendor base concentrates among European and Japanese engineering groups with decades of installed base relationships. Three archetypes dominate: conveyor-centric infrastructure builders, robotic manipulation specialists, and software-layer control system vendors. Consolidation proceeds through strategic technology licensing and geographic expansion rather than horizontal mergers.
Among Japanese industrial conglomerates, Daifuku and Murata Machinery occupy positions anchored in conveyor and automated storage expertise. Swisslog Holding AG exemplifies the robotic piece-picking specialization archetype. These three represent divergent strategic postures within a market where hardware foundations commoditize while software control layers command premium pricing.
| Leading Market Players |
|---|
| Dematic |
| Daifuku |
| Honeywell Intelligrated |
| Swisslog Holding AG |
| KNAPP |
| SSI Schaefer |
| Murata Machinery |
| KION Group |
| ABB |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor anchors cost dynamics across warehouse automation supply chains, where container rate volatility feeds directly into configured-to-order pricing premiums and compresses margins on standard equipment tiers. German system integrators and Chinese component fabricators occupy divergent positions in this freight-cost architecture, with downstream price differentiation widening as logistics expenses concentrate in the mid-market buyer segment.
Pricing Analysis
The customization-premium spread separates project-based configured-to-order pricing from catalog standard equipment, with the gap widening where CE marking and AI safety certification requirements layer compliance costs onto engineered solutions. Price differentiation hinges on certification tier—EU Machinery Directive conformity assessment commands substantial premiums over baseline OSHA-compliant configurations—and geographic delivery cost, with Pennsylvania distribution clusters absorbing lower freight expenses than West Coast fulfillment hubs. Pricing pressure stems from rare-earth magnet input volatility tied to Chinese export quota fluctuations, squeezing linear motor drive margins. Mid-market regional operators exhibit the highest price sensitivity, while Fortune 500 e-commerce operators prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Supplier-financing facilities from German high-bay crane manufacturers and Japanese conveyor specialists extend payment terms to sixty-plus days, easing capital constraints for multi-site rollout operators. Geographic supply concentration centers on Germany, Italy, and China, with over sixty percent of certified crane fabrication anchored in the first two and Zhejiang-Jiangsu provinces hosting dense component manufacturing clusters. Raw material dependencies encompass structural steel, permanent magnets for linear drives, and lithium-ion cells for mobile robot fleets. Single-source vulnerability pervades European system integrator concentration, where KION Group and SSI Schaefer dominance creates procurement risk for continental multi-site deployments. Distribution runs through direct OEM relationships for turnkey projects and regional distributor networks for spare parts and retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehouse automation demand traces a cyclical recovery pattern anchored to e-commerce fulfillment network expansion, with Pennsylvania and California distribution cluster investments signaling trough-to-peak inflection as order cycle time compression accelerates capital deployment.
For Market Incumbents: Pre-empt modular cell-based system displacement of fixed conveyor architectures by accelerating software control layer monetization through predictive maintenance subscriptions. Vertical integration into edge computing hardware reduces sensor fusion architecture vulnerability to AI-enabled sortation competitors. Certification pre-engineering for EU AI Act risk classifications defends margin position against compliance timeline friction from notified body bottlenecks. For New Entrants and Emerging Players: Build out automation-as-a-service financing capabilities to capture California e-commerce operators seeking operating expenditure treatment for tax advantages. India warehouse modernization under PLI scheme subsidies represents the most penetrable geography, with cold storage and agri-processing robotic palletizing demand outpacing local system integrator capacity. Channel partnerships with established WMS vendors accelerate WCS middleware integration without legacy platform development burden. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive automation divisions lacking standalone software revenue scale. Long-term viability favors vendors with recurring service income exceeding forty percent of revenue mix, insulating against hardware commoditization cycles. Controls engineering talent scarcity—concentrated among technicians over fifty-five—signals acquisition premium for field service organizations with documented knowledge transfer protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Software Control Layer Monetization | Predictive maintenance subscriptions from Daifuku and Swisslog capture recurring revenue above hardware margins. |
| EU AI Act Pre-Certification | Documented failure-mode analysis for sensor fusion architectures compresses deployment schedules by four to six months. |
| Automation-as-a-Service Financing | Per-touch pricing transfers obsolescence risk to equipment financiers and accelerates refresh cycles for California operators. |
| India PLI Scheme Localization | Cold storage and agri-processing subsidies open historically manual markets to robotic palletizing system integrators. |
| Edge Computing Hardware Integration | Onboard AI inference eliminates centralized WCS bottlenecks and enables millisecond tote re-routing decisions. |
Study Parameters
Initial hypotheses were tested against primary input from warehouse operations directors, system integrator project engineers, OEM aftermarket service heads, and e-commerce fulfillment network planners and refined through secondary validation against SEC 10-K filings, EU Machinery Directive conformity assessment databases, customs trade data for automation component flows, and OSHA enforcement records for robotic work cell incidents. Bottom-up equipment shipment aggregation and top-down fulfillment network capex analysis were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, technology layer, end-use velocity profile, and regional regulatory cluster. CAGRs were derived from logistic curve penetration modeling calibrated to historical automation adoption cycles in e-commerce fulfillment. Forecast inputs encompassed lithium-ion energy density improvement trajectories and EU AI Act implementation timelines for risk classification enforcement.
Stress conditions across rare-earth magnet export quota volatility, CE marking timeline extensions, and controls engineering labor supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about e-commerce order cycle time compression and omnichannel inventory orchestration adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Smart Warehouse Technologies Market