
 Europe Retail Automation Market | 2026-2036
Europe Retail Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Retail Automation Market Foresight
Modular point-of-sale configurations is expanding across European retail chains as buyers unbundle hardware, software, and service components to reduce vendor lock-in. Datalogic SpA leverages its Italian manufacturing base to dominate fixed retail scanning across Southern Europe. Diebold Nixdorf Incorporated sustains its position in self-service terminal deployment through extensive service networks in Germany and the Benelux region. Toshiba Global Commerce Solutions Inc. competes on cloud-native architecture for grocery chains seeking scalable checkout infrastructure.
Europe Retail Automation encompasses integrated hardware-software systems that manage transaction processing, inventory tracking, and customer flow optimization through specifications including RFID tag read rates exceeding 99% and edge computing nodes processing data within 50 milliseconds. Its primary commercial purpose centers on reducing labor dependency while maintaining transaction accuracy and regulatory compliance across high-volume retail environments. Self-Checkout Systems generate the largest revenue pool as mature installations across French hypermarkets reach replacement cycles, while Smart Shelves represent the fastest-expanding segment as electronic shelf labels with NFC pairing spread through German drugstore chains. Artificial Intelligence and IoT technologies concentrate margin capture among vendors offering unified analytics platforms rather than discrete sensor deployments.
GDPR enforcement by national data protection authorities across France, Germany, and Italy directly constrains facial recognition and biometric payment authentication deployments in retail settings. The EU AI Act risk classification framework forces vendors to recalibrate automated decision-making features in customer analytics software before market entry. REACH compliance and RoHS substance restrictions additionally shape hardware material specifications for touchscreen terminals and printed circuit assemblies. Stakeholders must monitor evolving conformity assessment timelines under the EU Cybersecurity Act as connected retail infrastructure faces expanded network security obligations.
Market Dynamics
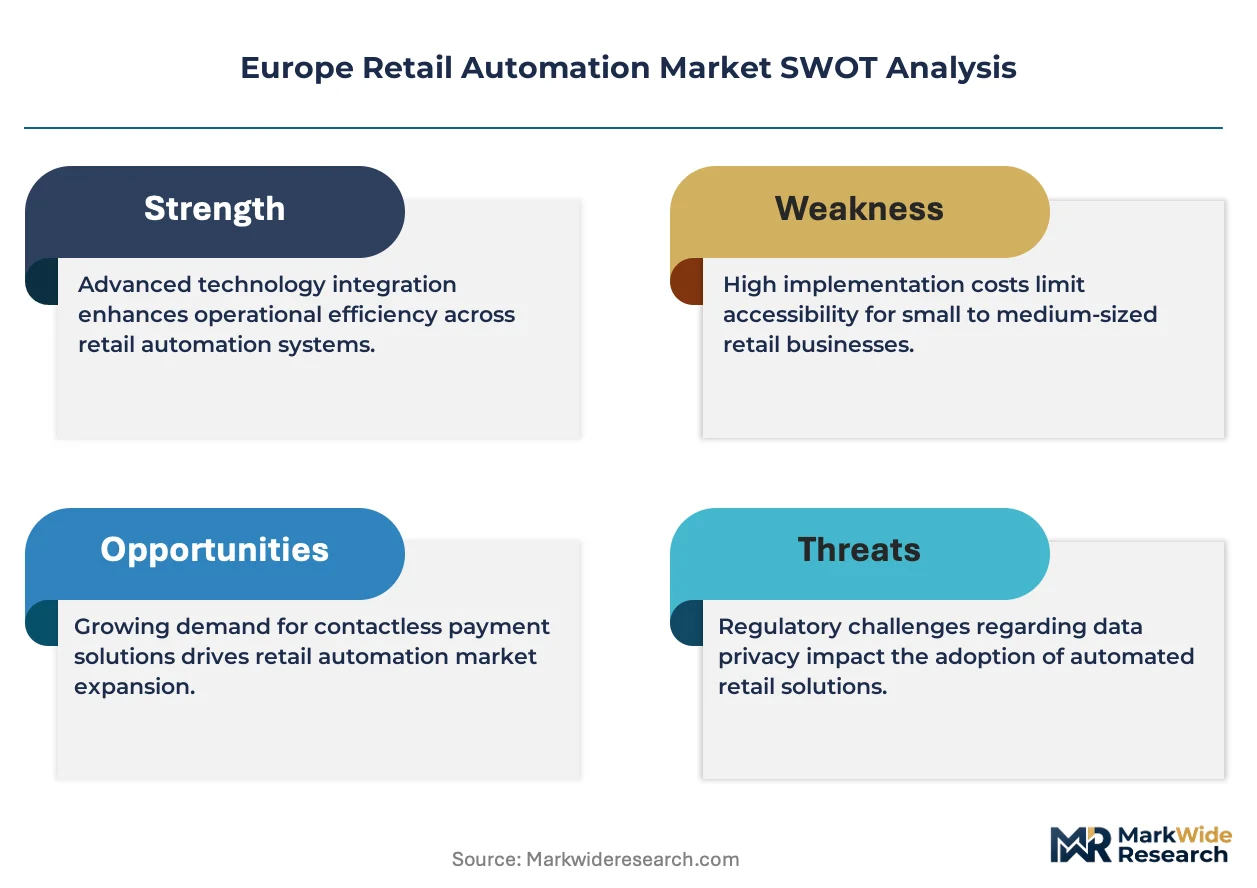
The EU AI Act risk classification framework and GDPR enforcement by CNIL and German data protection authorities are forcing vendors to reengineer computer vision and biometric authentication systems before deployment across French and German retail networks.
Growth Catalysts
- Labor Cost Pressures:German supermarkets face statutory minimum wage escalations that accelerate self-checkout terminal procurement to reduce front-of-store staffing requirements.
- REACH and RoHS Compliance:Hardware vendors redesign touchscreen terminals and printed circuit assemblies to eliminate restricted substances, creating replacement demand across installed bases.
- Electronic Shelf Labels:NFC-pairing smart shelf systems spread through German drugstore chains as inventory accuracy mandates tighten.
Market Restraints
- GDPR Facial Recognition Friction:Biometric payment authentication deployments stall under Article 9 special category data restrictions enforced by Italian and French regulators.
- Edge Computing Hardware Costs:Sub-50 millisecond processing requirements demand specialized GPU configurations that inflate unit economics for mid-tier retail chains.
- Vendor Concentration Risk:Self-service terminal servicing networks concentrate in Germany and Benelux, creating geographic coverage gaps for Southern European deployments.
Strategic Opportunities
- Italian Market Penetration:Fixed retail scanning infrastructure remains underdeployed across Southern European independent grocers relative to Northern European saturation.
- EU Cybersecurity Act Expansion:Network security obligations for connected retail infrastructure create certification service revenue streams for compliance consultancies.
- Cloud-Native POS Convergence:Grocery chains seek scalable checkout infrastructure that unbundles legacy hardware-software bundles.
Industry Challenges
- Legacy System Integration Complexity:ERP and inventory management platforms in established French hypermarkets resist API compatibility with modular automation components.
- Conformity Assessment Timelines:CE marking and EU AI Act high-risk system evaluations extend vendor time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Retail Automation Market |
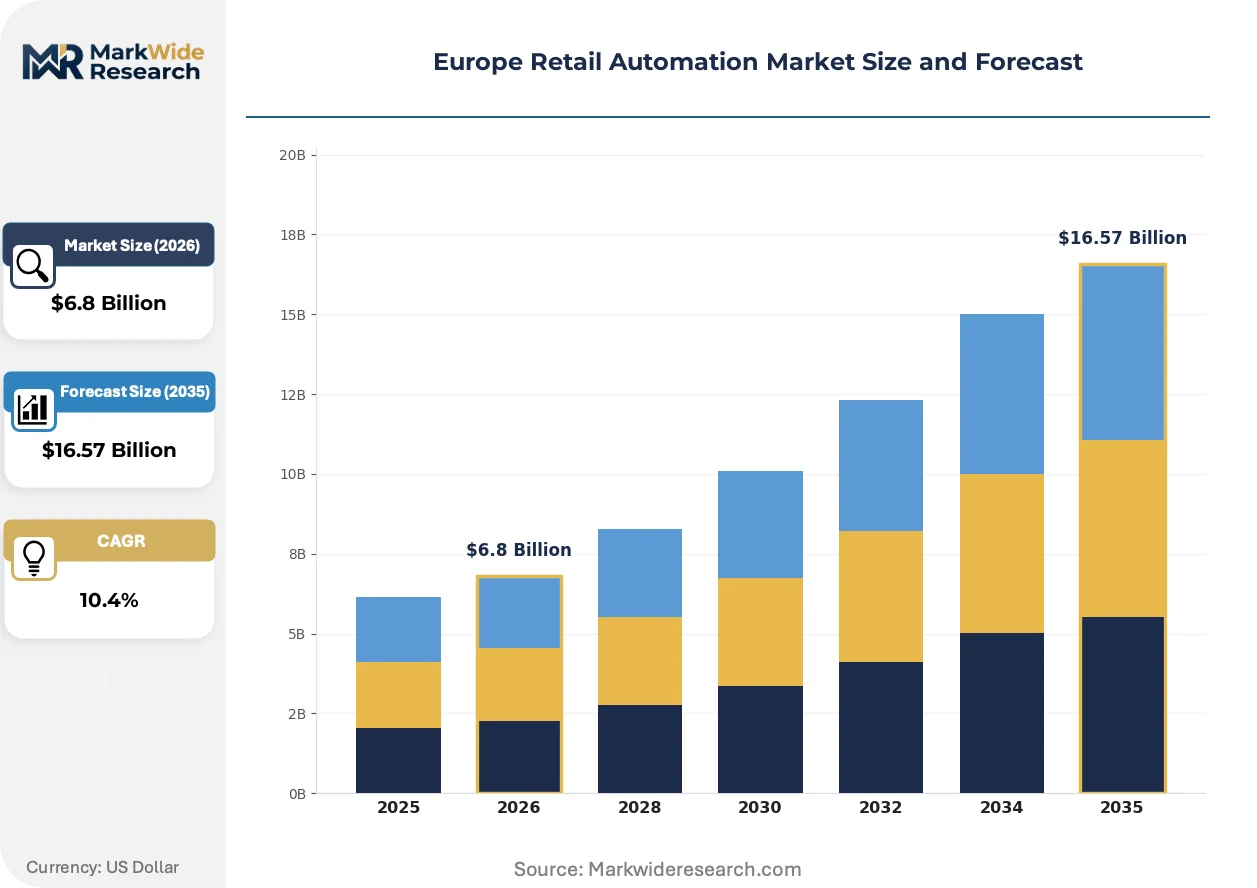
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Checkout Systems, Automated Inventory Management, Point of Sale Systems, Smart Shelves End User: Supermarkets, Specialty Stores, E-Commerce, Department Stores Technology: Artificial Intelligence, IoT, RFID, Machine Learning Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Datalogic SpA, Diebold Nixdorf Incorporated, Toshiba Global Commerce Solutions Inc., Emarsys eMarketing Systems AG, Fujitsu Limited, Honeywell International Inc., NCR Corporation, Zebra Technologies Corp., Pricer AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Retail Automation Market Shifts & Advancements
Computer vision analytics and edge computing architectures are reconfiguring how European retailers process transaction and inventory data at the store level. Three developments dominate vendor roadmaps and buyer procurement criteria.
Edge computing nodes with sub-50 millisecond processing capability are expanding into high-volume grocery environments. French hypermarket operators deploy these systems to enable real-time inventory tracking without cloud latency penalties. This architecture is expanding into customer flow optimization applications previously handled by centralized servers.
The EU AI Act's risk classification framework redefines permissible automated decision-making in retail customer analytics. Vendors must document conformity assessments for systems affecting consumer behavior before French and German market entry. High-risk classification forces recalibration of loyalty program algorithms and dynamic pricing engines across Western European deployments.
Modular procurement models displace bundled hardware-software-service contracts among German and UK retail chains. Buyers unbundle components to reduce vendor lock-in and accelerate technology refresh cycles. This pattern concentrates among omnichannel grocery operators seeking API-flexible infrastructure.
Europe Retail Automation Market Segmentation
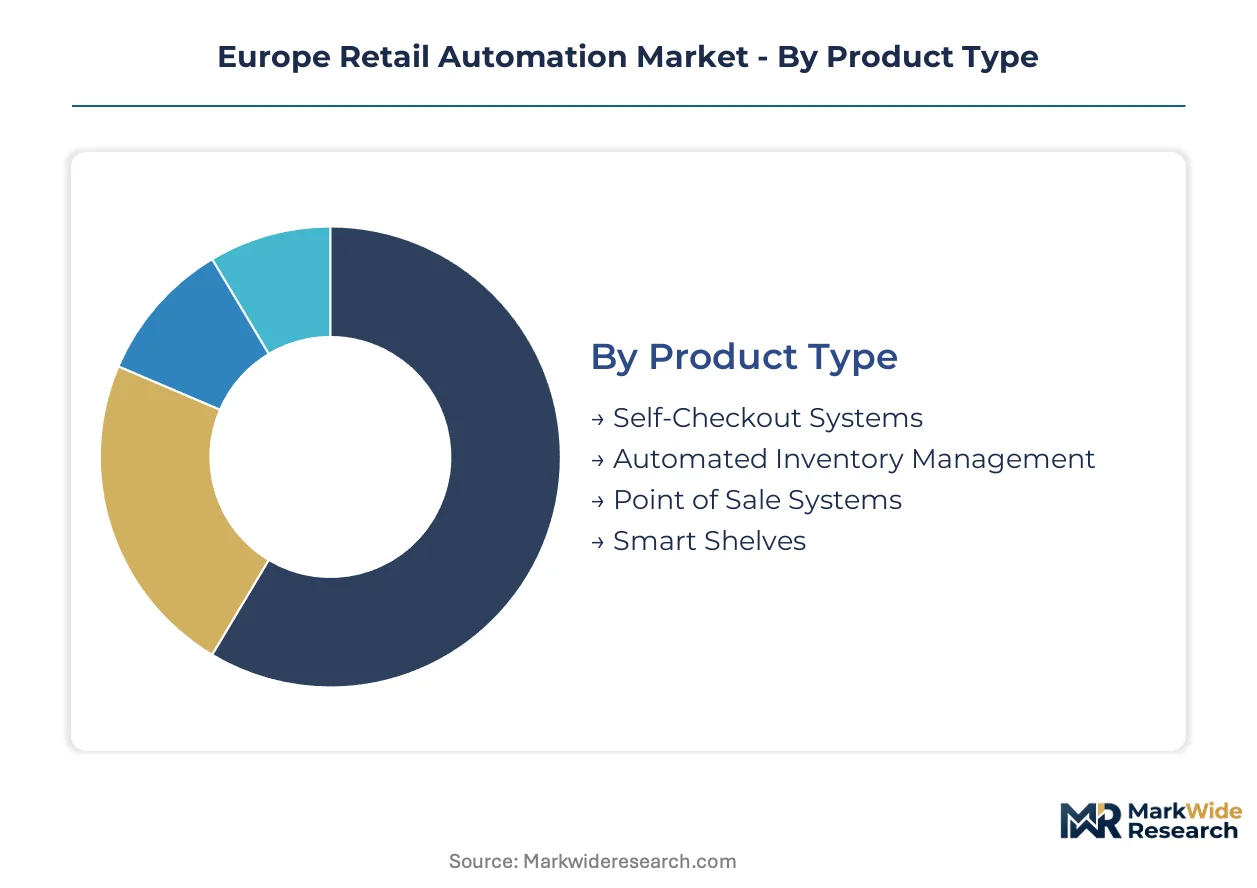
European retail automation procurement patterns diverge sharply across product configurations, end-use environments, and technology architectures. Buyers unbundle legacy bundles to optimize for GDPR compliance, labor cost pressures, and omnichannel integration requirements specific to Western European regulatory and competitive conditions.
Product Type:
Supply concentration among German and Italian hardware vendors shapes competitive dynamics across equipment categories, with service network density determining geographic penetration.
- Self-Checkout Systems:Fixed and mobile terminal configurations process transactions through integrated weighing scales, barcode scanners, and payment interfaces. French hypermarket operators drive replacement demand as first-generation installations reach end-of-life cycles amid statutory minimum wage escalations.
- Smart Shelves:Electronic shelf labels with NFC pairing and computer vision sensors enable real-time price updates and inventory tracking. German drugstore chains deploy these systems to meet tightening accuracy mandates while reducing manual shelf auditing labor.
- Automated Inventory Management:Back-of-store robotics and RFID tunnel systems streamline stock replenishment workflows.
- Point of Sale Systems:Modular hardware-software configurations unbundle legacy bundled contracts across UK grocery chains.
Self-Checkout Systems absorb the bulk of installed capacity; Smart Shelves is expanding most quickly.
End User:
Application intensity varies by format scale, with labor cost exposure and inventory complexity determining automation depth.
- Supermarkets:High-volume grocery operators deploy integrated checkout, shelf monitoring, and back-of-store systems simultaneously. German chains accelerate procurement to offset front-of-store staffing reductions mandated by wage policy shifts.
- E-Commerce:Dark stores and micro-fulfillment centers deploy robotic picking and automated sortation for last-mile delivery optimization.
- Specialty Stores:Smaller format retailers prioritize compact self-checkout and mobile POS flexibility.
- Department Stores:Multi-category operators focus on customer flow analytics and unified commerce platforms.
Supermarkets command the largest deployment base; E-Commerce is climbing the fastest as fulfillment infrastructure scales.
Technology:
Margin capture concentrates among vendors offering unified analytics platforms rather than discrete sensor deployments.
- Artificial Intelligence:Computer vision and automated decision-making systems face EU AI Act high-risk classification requirements. Vendors must document conformity assessments before French and German market entry, extending time-to-revenue timelines.
- IoT:Connected sensor networks enable real-time shelf monitoring and predictive maintenance across distributed store footprints.
- RFID:Tag-based inventory tracking achieves read rates exceeding specifications required for automated replenishment triggers.
- Machine Learning:Demand forecasting algorithms optimize stock positioning and dynamic pricing engines.
Artificial Intelligence captures premium pricing; IoT is gaining share fastest as connectivity infrastructure matures.
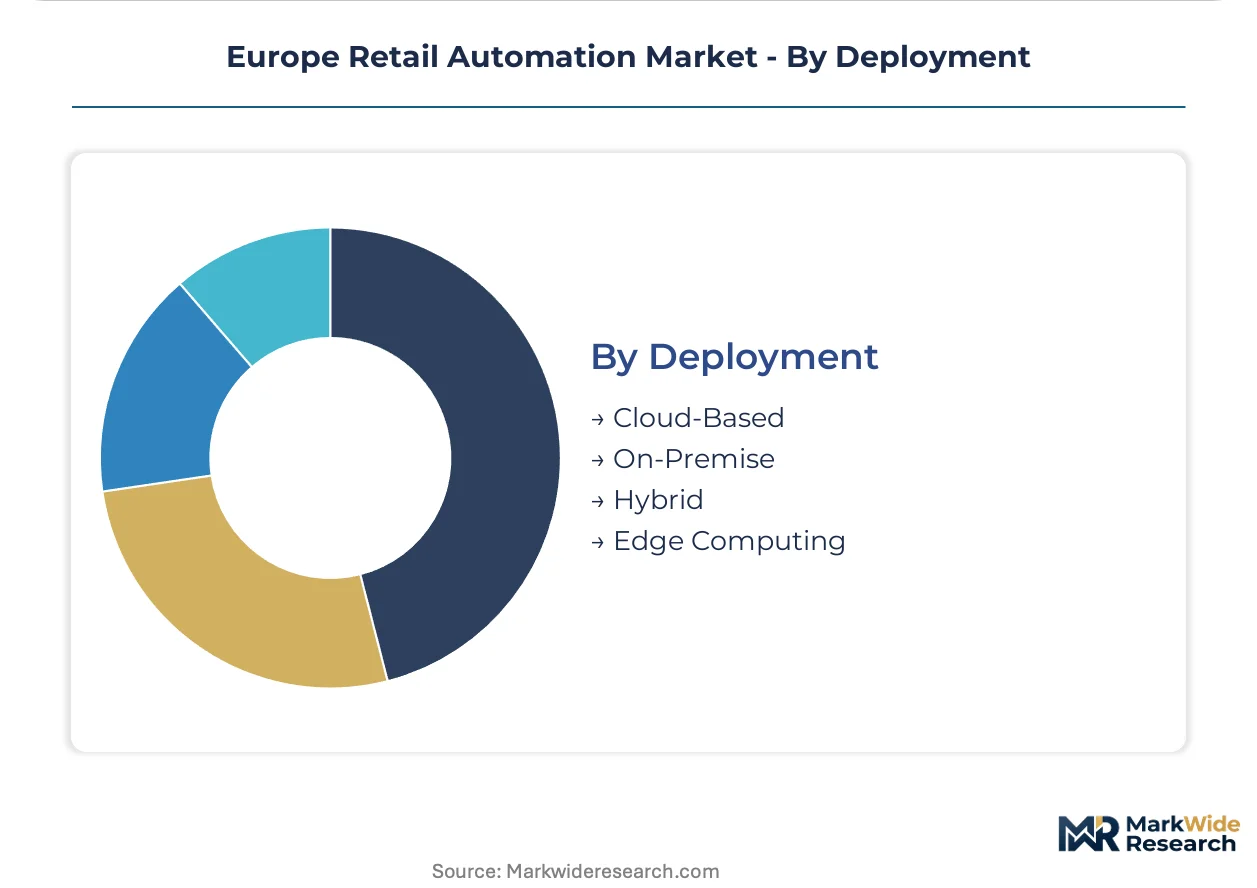
Deployment:
Architecture selection hinges on latency requirements, data sovereignty constraints, and legacy system integration complexity.
- Cloud-Based:Scalable infrastructure enables centralized analytics and rapid feature deployment across multi-store networks. UK grocery chains prioritize this model for omnichannel integration flexibility.
- Edge Computing:Sub-50 millisecond processing nodes handle real-time inventory and customer flow optimization without cloud latency penalties. French hypermarkets deploy these systems for high-frequency transaction environments.
- On-Premise:Localized data storage addresses GDPR data residency requirements for sensitive customer analytics.
- Hybrid:Split architectures balance real-time processing at store level with centralized analytics and model training.
Edge Computing dominates high-volume grocery installations; Cloud-Based is expanding most quickly among mid-tier chains seeking scalability without capital intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail automation equipment production concentrates in Germany and Italy while consumption spreads across Western European markets with varying labor cost pressures and regulatory stringency.
Germany
Statutory minimum wage escalations drive supermarket chains toward self-checkout terminal procurement to reduce front-of-store staffing. The KBA and federal data protection authorities enforce GDPR Article 9 restrictions on biometric payment authentication. Munich and Stuttgart industrial clusters host precision manufacturing of edge computing nodes for sub-50 millisecond transaction processing.
United Kingdom
Omnichannel grocery operators prioritize cloud-native POS infrastructure to unbundle legacy hardware-software bundles. The Information Commissioner's Office scrutinizes automated decision-making in customer loyalty analytics under UK GDPR alignment. London-based retail technology consultancies facilitate mid-tier chain adoption of modular procurement models.
France
Hypermarket operators face replacement cycles for first-generation self-checkout installations amid CNIL enforcement of facial recognition prohibitions in retail settings. The EU AI Act high-risk classification forces conformity assessment documentation for computer vision analytics before market entry. Lyon and Paris logistics corridors anchor smart shelf deployment for real-time inventory accuracy mandates.
Italy
Independent grocers across Southern Europe present underpenetrated demand for fixed retail scanning infrastructure relative to Northern European saturation. ANSM and Garante privacy regulators constrain automated customer tracking technologies in specialty store formats. Bologna's manufacturing base supports Datalogic SpA production of barcode scanning equipment for regional distribution.
Netherlands
Benelux retail networks concentrate self-service terminal servicing capabilities that create geographic coverage advantages for vendor deployment. The Dutch Data Protection Authority enforces strict data residency requirements for cloud-connected retail infrastructure. Rotterdam distribution hubs facilitate cross-border equipment logistics into Belgian and Luxembourg markets.
Europe Retail Automation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, software platforms, and integrated service delivery. The vendor base organizes into three strategic archetypes: industrial automation conglomerates with retail divisions, dedicated retail technology pure-plays, and IT services firms with retail vertical specialization. Consolidation pressures intensify as modular procurement models reduce switching costs for buyers. Competitive moves center on M&A for service network density and strategic partnerships for cloud-native architecture integration.
Among Italy-based hardware specialists, Datalogic SpA exemplifies the focused manufacturing archetype with regional production advantages. Diebold Nixdorf Incorporated and Toshiba Global Commerce Solutions Inc. represent diversified technology conglomerates with established European service footprints. These three entities occupy positions across the equipment-to-services value chain without exclusive segment dominance.
| Leading Market Players |
|---|
| Datalogic SpA |
| Diebold Nixdorf Incorporated |
| Toshiba Global Commerce Solutions Inc. |
| Emarsys eMarketing Systems AG |
| Fujitsu Limited |
| Honeywell International Inc. |
| NCR Corporation |
| Zebra Technologies Corp. |
| Pricer AB |
| Others |
Supply & Pricing Matrix
German supermarket chains and French hypermarket operators concentrate procurement volume among three to five vendor relationships per national market, locking in contract-based long-term offtake pricing with hardware-software service bundles. This buyer concentration forces tiered pricing stratification across premium, standard, and economy certification levels, with CE marking and EU AI Act conformity assessments acting as gatekeepers to premium tier access.
Pricing Analysis
Margin tightening in mid-tier self-checkout terminals reflects GPU component cost inflation for sub-50 millisecond edge processing requirements. Pricing stratifies across premium, standard, and economy tiers based on CE certification grade and after-sales service bundling. Cost compression accelerates because German statutory wage escalations pressure buyers toward economy-tier configurations. Specialty store operators exhibit highest price sensitivity; omnichannel grocery chains absorb premium pricing for API-flexible modular architectures.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket demand while regional distributors serve independent grocers across Southern Europe. Manufacturing concentrates in Germany, Italy, and the Netherlands for precision edge computing nodes and electronic shelf label assemblies. Component supply draws from Taiwanese semiconductor foundries, South Korean display panel manufacturers, and Chinese PCB fabrication facilities. Single-source vulnerability in GPU accelerators for computer vision systems creates procurement risk. Distribution runs through Rotterdam and Hamburg logistics hubs for cross-border fulfillment into Benelux and Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular procurement models and EU AI Act compliance costs are forcing consolidation among hardware vendors without unified analytics platforms. Weaker players lacking service network density or cloud-native architectures face exit pressure as replacement cycles concentrate among integrated suppliers.
For Market Incumbents: To counter cloud-native POS entrants from IT services firms, deepen backward integration into edge computing node manufacturing and expand certification investment for EU AI Act high-risk system documentation. Capacity addition in Bologna and Stuttgart industrial clusters reinforces geographic coverage advantages against Southern European coverage gaps. For New Entrants and Emerging Players: Enter via underpenetrated independent grocers across Italy and Spain where fixed retail scanning infrastructure remains below Northern European saturation levels. White-space opportunity concentrates in compact self-checkout for specialty store formats. Go-to-market positioning should emphasize GDPR-compliant customer analytics without biometric authentication to bypass CNIL and Garante enforcement friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor service-network-constrained hardware vendors in Southern European markets where vendor concentration risk creates coverage gaps. Long-term viability hinges on unified analytics platform capabilities spanning computer vision and inventory optimization. Monitor CE marking backlog timelines at notified bodies as inflection signal for vendor time-to-revenue compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Documentation capabilities unlock French and German hypermarket procurement cycles ahead of competitors. |
| Edge Computing Manufacturing Scale-Up | Sub-50 millisecond processing nodes capture replacement demand from first-generation self-checkout installations. |
| Cloud-Native POS Platform Integration | API-flexible architectures displace bundled hardware-software contracts among UK omnichannel grocery operators. |
| Southern European Service Network Expansion | Geographic coverage gaps in Italy and Spain create first-mover advantage for independent grocer penetration. |
| GDPR-Compliant Biometric Alternative Development | NFC-pairing and QR-code authentication bypass Article 9 restrictions enforced by CNIL and German data protection authorities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with supermarket procurement directors, retail technology integration specialists, and hardware vendor sales executives combined with ECHA REACH registration databases, EU AI Act implementation guidance from national regulators, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up store-level deployment estimates triangulated against top-down vendor revenue segmentation.
Granularity-level modeling tracked self-checkout terminals, smart shelves, and POS systems by deployment architecture across Germany, France, the United Kingdom, Italy, and the Netherlands. Technology dimensions included artificial intelligence, IoT, RFID, and machine learning with edge computing latency tiers. CAGRs derived from replacement cycle analysis, wage policy trajectory, and regulatory compliance timeline integration across the projection horizon. Forecast inputs incorporated statutory minimum wage escalation schedules and EU Cybersecurity Act certification pathway announcements.
Revisions become necessary when GDPR enforcement actions expand biometric authentication prohibitions or when GPU supply constraints extend edge computing hardware lead times beyond current baselines. Forecasts reflect assumptions regarding CE marking processing efficiency and modular procurement adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Assembly Automation Systems Market