
 North America Automated Rotary Indexing Table Market | 2026-2036
North America Automated Rotary Indexing Table Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automated Rotary Indexing Table Market Analytics
Buyer concentration among automotive OEMs is hardening as Detroit-area manufacturers consolidate supplier relationships around fewer automation vendors. WEISS North America Inc. leverages its servo-driven indexing expertise to anchor high-precision assembly contracts with tier-one suppliers. Haas Automation Inc. competes on vertical manufacturing scale, while DESTACO differentiates through its gripper-integrated rotary platform designs for robotic workcells.
An automated rotary indexing table is a precision positioning device that rotates workpieces or tooling stations through fixed angular increments, typically achieving repeatability within ±0.01 mm through cam-driven or direct-drive mechanisms, and serves to synchronize multi-station manufacturing operations without manual intervention. Electric actuation is displacing pneumatic systems in structural terms because servo motors deliver programmable flexibility and energy recovery that hydraulic alternatives cannot match in cleanroom environments. Assembly line applications occupy the dominant margin pool, though inspection systems represent the fastest-growing segment as machine vision integration demands higher indexing accuracy.
OSHA machine guarding standards and the US Inflation Reduction Act's domestic content provisions are reshaping procurement criteria, pushing OEMs toward certified North American suppliers over imported alternatives. The EPA's energy efficiency guidelines for industrial equipment are accelerating electric actuation adoption against legacy hydraulic systems. Stakeholders must monitor how NHTSA traceability requirements for automotive components cascade into indexing table specification standards.
Market Dynamics
Servo-electric actuation is consolidating its dominance over pneumatic and hydraulic alternatives across North American assembly operations, driven by the Inflation Reduction Act's energy efficiency mandates and cleanroom compatibility requirements in automotive and medical device manufacturing.
Growth Catalysts
- US Inflation Reduction Act:Domestic content provisions channel capital toward certified North American suppliers, accelerating equipment upgrade cycles across Michigan and Ohio manufacturing corridors.
- Machine vision integration:Inspection systems demand indexing accuracy below ±0.01 mm, pulling precision rotary table specifications tighter across automotive tier-one supplier contracts.
- Great Lakes industrial corridor:Detroit-area OEM consolidation around fewer automation vendors concentrates demand for high-repeatability positioning equipment in Michigan, Ohio, and Illinois.
Market Restraints
- Steel and rare earth magnet costs:Servo motor input volatility compresses margin buffers for electric actuation systems against legacy pneumatic alternatives.
- Single-source cam mechanism suppliers:Precision indexing component concentration in specialized German and Japanese machine tool vendors creates supply vulnerability for North American integrators.
- OSHA machine guarding compliance:Retrofit requirements for existing rotary installations impose unplanned downtime costs that delay replacement cycles.
Strategic Opportunities
- Mexico nearshoring expansion:Automotive OEMs relocating capacity from Asia to Baja California and Monterrey create demand for new rotary indexing installations with local service support.
- Battery cell assembly:Gigafactory construction across Nevada, Tennessee, and Kentucky requires contamination-resistant indexing for electrode stacking and cell formation processes.
- EPA energy efficiency guidelines:Industrial equipment standards accelerate electric actuation adoption against hydraulic systems in food processing and pharmaceutical cleanrooms.
Industry Challenges
- Mechatronics technician scarcity:Servo tuning and cam profile optimization skills lag demand across Midwest automation integrators, extending commissioning timelines.
- Legacy PLC integration complexity:Retrofitting servo-driven tables into existing Allen-Bradley or Siemens control architectures requires custom communication modules that inflate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automated Rotary Indexing Table Market |
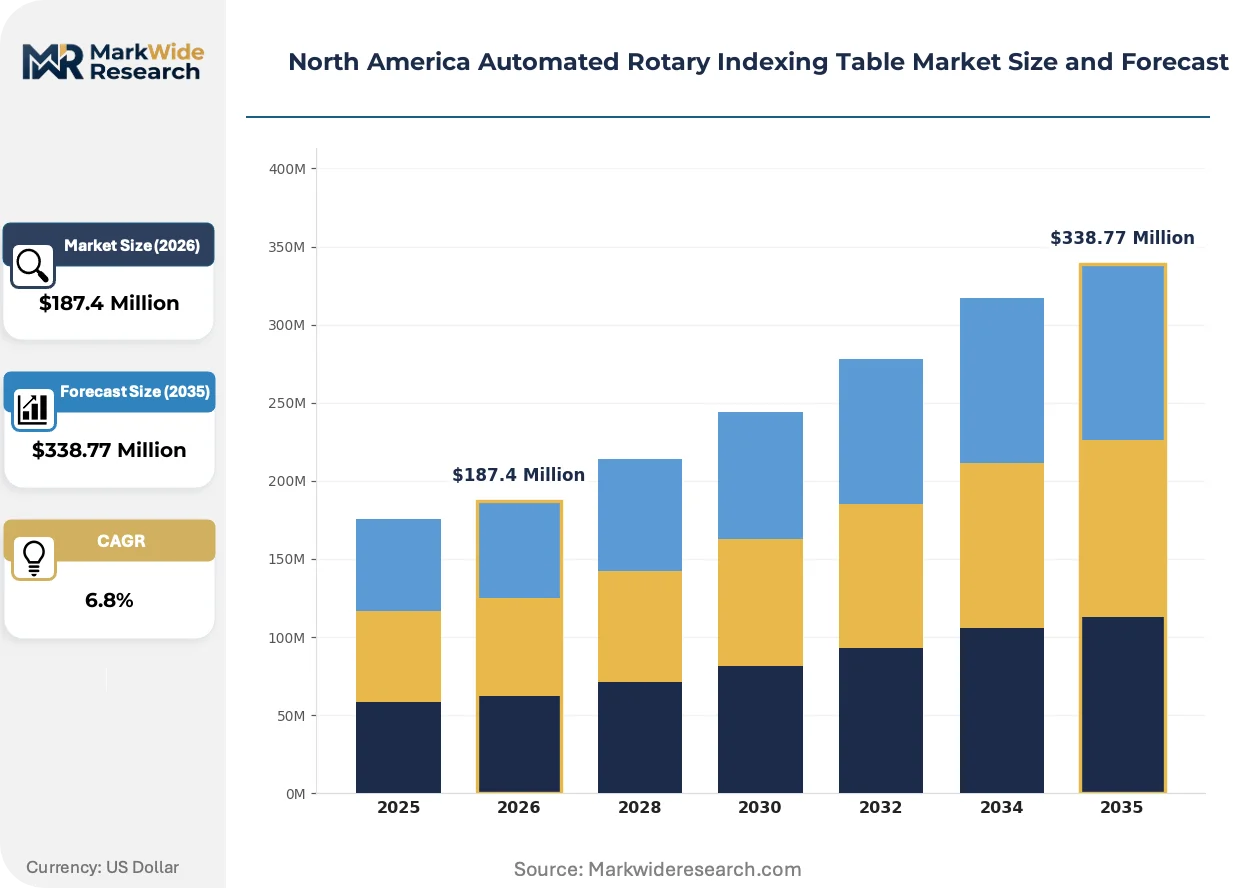
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis, Dual-Axis, Multi-Axis, Custom Solutions End User: Automotive OEMs, Electronics Manufacturers, Food Processing, Pharmaceutical Companies Technology: Electric Actuation, Pneumatic, Hydraulic, Mechanical Application: Assembly Lines, Packaging, Material Handling, Inspection Systems |
| Companies Covered | WEISS North America Inc., A Dover Company, Sankyo Automation, DESTACO, Nexen Group Inc., Haas Automation Inc., TAKTOMAT, Kitagawa North Tech, Inc., Motion Index Drives, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automated Rotary Indexing Table Market Evolving Landscape
Direct-drive torque motor technology is consolidating market position against traditional cam-driven mechanisms, while regulatory pressure on energy consumption and domestic sourcing reshapes procurement criteria across the region.
Servo-driven direct-drive rotary tables are consolidating their position in high-precision assembly applications by eliminating mechanical backlash and enabling programmable acceleration profiles. Automotive OEMs in Michigan and Ohio are specifying these systems for electric powertrain component assembly. The technology is consolidating supplier margins around motion control expertise rather than mechanical fabrication scale.
The US Inflation Reduction Act's domestic content provisions are forcing equipment procurement toward certified North American suppliers over imported alternatives. OEMs must document supply chain provenance to qualify for federal tax credits on manufacturing facility investments. Battery and electric vehicle assembly lines in Tennessee and Kentucky face the most acute compliance pressure.
Buyer concentration among Detroit-area automotive OEMs is compressing supplier negotiation cycles and unbundling after-sales service contracts from initial equipment purchases. Tier-one suppliers now procure rotary tables through consolidated automation platform vendors rather than direct indexing specialists. This pattern is most visible in Michigan's Warren and Sterling Heights manufacturing clusters.
North America Automated Rotary Indexing Table Market Segmentation
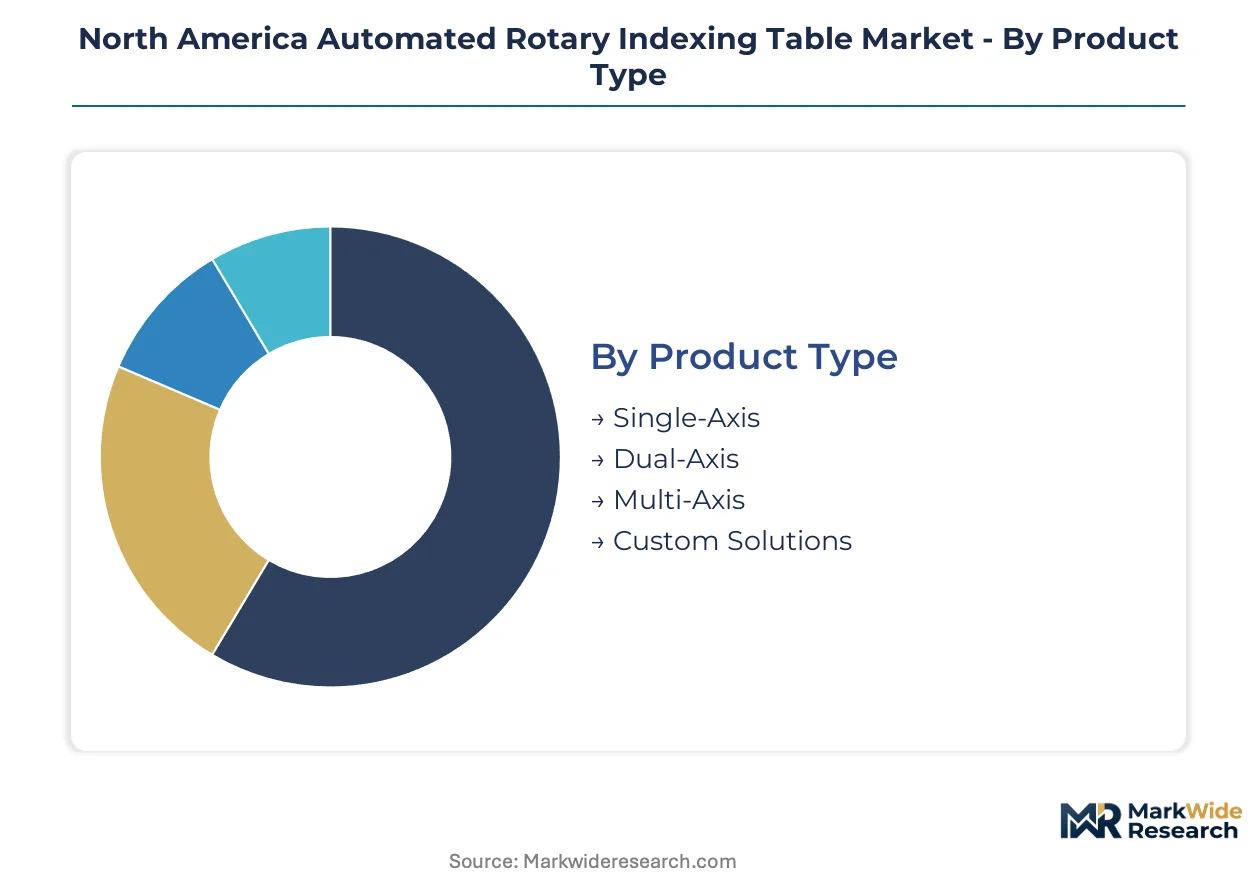
Segmentation in the North America automated rotary indexing table market reveals how buyer priorities diverge across precision requirements, regulatory exposure, and integration complexity. Procurement patterns in Michigan automotive corridors differ materially from pharmaceutical cleanrooms in New Jersey or battery gigafactories in Nevada.
Product Type:
Buyers select axis configuration based on station count, part geometry complexity, and downstream retooling flexibility needs.
- Single-Axis:Cam-driven or direct-drive mechanisms rotate workpieces through fixed angular increments with repeatability within ±0.01 mm. Automotive tier-one suppliers in Ohio and Illinois specify these for high-volume powertrain component assembly where station count stays below eight positions.
- Dual-Axis:Tilt-and-rotate configurations enable compound angular positioning for complex part geometries. Medical device manufacturers in Minnesota and Massachusetts require these for orthopedic implant machining cells where access angles determine surface finish quality.
- Multi-Axis:Integrates rotary motion with linear positioning stages for five-sided part access. Demand concentrates in aerospace component finishing operations across Kansas and Connecticut.
- Custom Solutions:Engineered-to-order configurations accommodate oversized payloads or cleanroom-rated sealing. Battery electrode stacking lines in Nevada and Tennessee drive specification volume for contamination-resistant envelope designs.
Single-axis configurations lead on scale; custom solutions lead on momentum as gigafactory construction accelerates.
End User:
End-user selection hinges on throughput velocity, contamination tolerance, and traceability mandate intensity.
- Automotive OEMs:Detroit-area manufacturers consolidate supplier relationships around fewer automation vendors. The Inflation Reduction Act's domestic content provisions channel capital toward certified North American equipment upgrades across Michigan and Ohio assembly corridors.
- Electronics Manufacturers:Semiconductor packaging and PCB assembly operations require sub-micron indexing accuracy. Cleanroom compatibility specifications in Arizona and Texas fabrication facilities favor electric actuation over pneumatic alternatives.
- Food Processing:USDA sanitary design standards dictate stainless steel construction and washdown-rated sealing. Midwest protein processing plants specify these for portioning and packaging rotary systems.
- Pharmaceutical Companies:FDA cGMP requirements and batch record traceability drive validation documentation intensity. New Jersey and North Carolina drug manufacturing clusters specify indexed inspection stations for vial and syringe quality verification.
Automotive OEMs anchor volume demand; pharmaceutical companies are expanding most quickly on inspection system integration.
Technology:
Actuation technology selection reflects energy efficiency mandates, precision requirements, and maintenance access constraints.
- Electric Actuation:Servo motors deliver programmable flexibility, energy recovery, and position feedback without hydraulic fluid contamination. The EPA's industrial equipment efficiency guidelines and cleanroom requirements across automotive and medical device manufacturing accelerate displacement of legacy alternatives.
- Pneumatic:Compressed air systems retain cost advantage in coarse-positioning applications with lower repeatability requirements. Food processing plants in the Midwest specify these where washdown compatibility outweighs precision needs.
- Hydraulic:High-torque density suits heavy payload applications in metal forming and forging operations. Energy consumption penalties and EPA emissions scrutiny constrain new installations outside legacy equipment replacement cycles.
- Mechanical:Cam-driven Geneva mechanisms offer deterministic positioning without electronic complexity. Maintenance-intensive designs retain niche presence in low-automation-maturity manufacturing environments.
Electric actuation leads on scale; mechanical systems retain position only in cost-constrained retrofit scenarios.
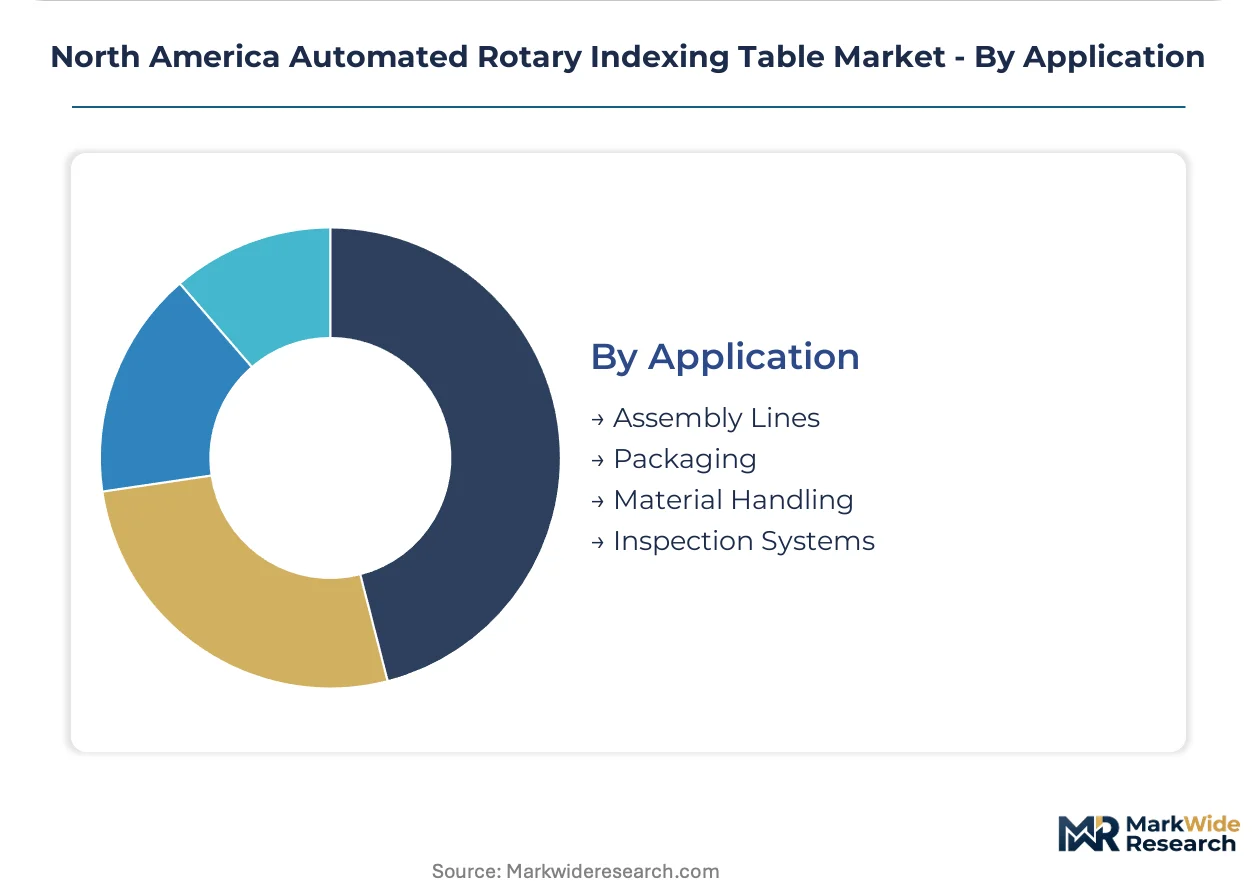
Application:
Application selection determines indexing speed, accuracy tier, and peripheral integration density.
- Assembly Lines:Multi-station synchronous operation with robotic part loading and torque-controlled fastening. Michigan and Ohio automotive powertrain plants represent the dominant margin pool for high-repeatability positioning equipment.
- Packaging:High-speed indexing for carton forming, filling, and sealing operations. Food and beverage processors specify these for throughput rates exceeding 200 cycles per minute.
- Material Handling:Pallet-based workpiece transport between machining centers or inspection stations. Flexible manufacturing system retrofits in existing Great Lakes industrial facilities drive specification volume.
- Inspection Systems:Machine vision integration demands indexing accuracy below ±0.01 mm with programmable dwell times. Battery cell formation and electrode stacking processes in Tennessee and Kentucky gigafactories represent the steepest expansion trajectory.
Assembly lines anchor revenue concentration; inspection systems gain share fastest on metrology integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of North American rotary indexing table demand, while Mexico's nearshoring momentum is accelerating faster than Canada's industrial equipment refresh cycles.
United States
Automotive OEM consolidation in Michigan and Ohio drives concentrated procurement of high-repeatability positioning equipment. The Inflation Reduction Act's domestic content provisions channel capital toward certified suppliers across the Great Lakes industrial corridor. Warren and Sterling Heights manufacturing clusters anchor tier-one supplier automation upgrade cycles.
Mexico
Automotive OEMs relocating capacity from Asia to Baja California and Monterrey create fresh demand for rotary indexing installations with local service support. Mexico's federal manufacturing incentives complement USMCA regional content rules. Querétaro and Guanajuato industrial parks attract precision automation vendors establishing regional technical centers.
Canada
Automotive powertrain plants in Ontario's Windsor-Oshawa corridor pursue selective equipment modernization rather than greenfield expansion. Health Canada's medical device regulations drive cleanroom-compatible indexing specifications for Toronto-area orthopedic manufacturers. Hamilton and Kitchener-Waterloo precision machining clusters represent niche demand pockets.
North America Automated Rotary Indexing Table Market Competitive Landscape
German and Japanese producers anchor one tier; North American specialists hold contract consolidation advantages in Detroit-area procurement. The vendor base stratifies across three tiers: integrated automation platforms, precision indexing specialists, and regional fabrication houses. Two dominant competitive moves are reshaping positioning: tier-one suppliers bundling rotary tables into consolidated automation contracts, and servo-drive technology licensing agreements accelerating electric actuation adoption.
Among North American-based specialists, WEISS North America Inc. and DESTACO exemplify the gripper-integrated platform archetype, while Haas Automation Inc. represents vertical manufacturing scale. These three entities occupy positions across the precision-motion spectrum, with each anchoring distinct competitive vectors in automotive and medical device manufacturing procurement.
| Leading Market Players |
|---|
| WEISS North America Inc. |
| A Dover Company |
| Sankyo Automation |
| DESTACO |
| Nexen Group Inc. |
| Haas Automation Inc. |
| TAKTOMAT |
| Kitagawa North Tech, Inc. |
| Motion Index Drives |
| Others |
Value Network & Pricing Analysis
Performance-grade divergence between servo-electric and pneumatic actuation systems manifests in pricing spreads exceeding three-to-one for comparable station counts, while supply chain configurations cluster around cam mechanism sourcing from specialized German and Japanese machine tool vendors. This bifurcation concentrates margin capture among motion control specialists with captive servo-drive expertise, leaving pneumatic assemblers exposed to commodity steel and aluminum input volatility.
Pricing Analysis
Capacity additions in Mexico's Baja California and Monterrey manufacturing corridors are reshaping price floors for mid-tier rotary indexing equipment as local assembly reduces freight and import duty burdens. Pricing stratifies across premium servo-electric tiers with ±0.01 mm repeatability certification, standard cam-driven configurations for automotive powertrain assembly, and economy pneumatic units for food processing washdown environments. Cost compression in the standard tier is intensifying because tier-one automotive suppliers unbundle after-sales service contracts from initial equipment purchases. Electronics manufacturers in Arizona and Texas fabrication facilities demonstrate the least price sensitivity due to cleanroom compatibility mandates, while Midwest protein processing plants prioritize capital expenditure minimization over precision specifications.
Supply Chain Analysis
Dual-sourcing requirements from Detroit-area automotive OEMs now mandate qualified suppliers for both cam-driven Geneva mechanisms and direct-drive torque motor assemblies, forcing integrators to maintain parallel vendor relationships across Germany, Japan, and domestic North American specialists. Precision indexing component supply draws from specialized machine tool producers in Germany and Japan for cam profiles, rare earth magnet processors in China for servo motors, and domestic steel service centers for fabricated bases. Single-source vulnerability concentrates in high-precision cam grinding equipment where Japanese vendors hold specialized capability. Distribution runs through consolidated automation platform vendors rather than direct indexing specialists, compressing supplier negotiation cycles across Michigan and Ohio procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on electric actuation's displacement of legacy hydraulic systems and the premium pricing power conferred by cleanroom-rated servo-drive certifications.
For Market Incumbents: Anchor high-repeatability positioning contracts through captive servo tuning expertise and localized technical service centers in Warren and Sterling Heights manufacturing clusters. Deepen backward integration into direct-drive torque motor assembly to reduce exposure to rare earth magnet cost volatility. Defend against tier-one supplier consolidation around consolidated automation platform vendors by unbundling software commissioning modules from hardware shipments. For New Entrants and Emerging Players: Launch via regional technical center partnerships in Querétaro and Guanajuato industrial parks to capture automotive OEM nearshoring momentum from Asia to Mexico. Target battery electrode stacking applications in Nevada and Tennessee gigafactories where contamination-resistant envelope designs command specification premiums. Pursue white-space penetration through FDA cGMP validation documentation services for pharmaceutical cleanroom installations in New Jersey and North Carolina. For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics technician scarcity extends commissioning timelines and inflates project risk for mid-tier automation integrators. Long-term viability favors precision motion control specialists with software-defined positioning platforms over mechanical fabrication houses tethered to cam-driven legacy architectures. Acquisition target archetypes include servo-drive technology licensors and gripper-integrated rotary platform designers. Watch NHTSA traceability requirement cascades into indexing table specification standards as the inflection indicator for compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Technology Licensing | Accelerates electric actuation adoption against pneumatic alternatives in EPA-regulated cleanrooms. |
| Regional Technical Center Expansion | Captures automotive OEM nearshoring demand across Baja California and Monterrey manufacturing corridors. |
| Gripper-Integrated Platform Development | Addresses robotic workcell synchronization requirements in Michigan tier-one supplier contracts. |
| FDA cGMP Validation Documentation | Unlocks pharmaceutical procurement in New Jersey and North Carolina drug manufacturing clusters. |
| Rare Earth Magnet Supply Agreements | Secures input cost stability for servo motor production against commodity price volatility. |
Research Methodology
Multiple input streams — structured interviews with automation integrators and OEM procurement teams, trade data reconciliation, and regulatory filing analysis — were reconciled to construct demand estimates across the North American rotary indexing table market. Primary fieldwork engaged plant engineers at Michigan and Ohio automotive facilities, aftermarket service heads at tier-one suppliers, and biomedical equipment specialists at Minnesota and Massachusetts medical device manufacturers. Secondary validation drew from OSHA machine guarding standard updates, EPA industrial equipment efficiency guideline releases, USMCA regional content rule documentation, and SEC filings from publicly traded automation equipment vendors. Bottom-up equipment shipment tallies were triangulated against top-down manufacturing capital expenditure forecasts.
Data-stream reconciliation anchored volume projections across product type, actuation technology, end-user industry, and regional production cluster dimensions throughout the forecast period. Segmentation modeling captured axis configuration selection patterns, cleanroom compatibility requirements, and machine vision integration intensity as industry-specific demand drivers. CAGRs were derived from fitted growth curves calibrated to historical equipment replacement cycles and announced greenfield facility investments. Forecast inputs included Inflation Reduction Act domestic content provision compliance timelines, gigafactory construction permitting velocity, and servo motor input cost trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in FDA cGMP or EPA emissions standards, abrupt rare earth export restrictions, and automotive OEM platform cancellations. Forecasts reflect documented assumptions regarding technician availability for servo commissioning and PLC integration complexity timelines. Deviation in NHTSA traceability mandate implementation schedules or USMCA regional content rule enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Connected Worker Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Smart Industries Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Grippers Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Global Warehouse Automation Market