
 India Compound Feed Market | 2026-2036
India Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
India Compound Feed Market Foresight
Subscription-based feed formulation software is decoupling nutritional advisory from physical product sales across India's compound feed sector. Godrej Agrovet Limited leverages its veterinary services network to lock in long-term farmer relationships. De Heus India anchors its position through backward integration into premix manufacturing near its Andhra Pradesh production base. Cargill Incorporated competes by controlling bulk grain sourcing corridors from Madhya Pradesh and Rajasthan.
Compound feed denotes industrially blended rations combining cereals, oilseed meals, vitamins, and minerals in precise ratios to meet species-specific nutritional requirements, typically pelleted or mash-processed for mechanized distribution. Its primary purpose is to standardize livestock productivity metrics across fragmented smallholder operations. Poultry feed dominates volume throughput given the broiler integration model concentrated in southern and western states, while aquaculture feed captures accelerating margin pools as shrimp export certification tightens. Premium grade formulations are displacing standard grade in dairy corridors where cooperative procurement boards enforce milk solids-linked incentive pricing.
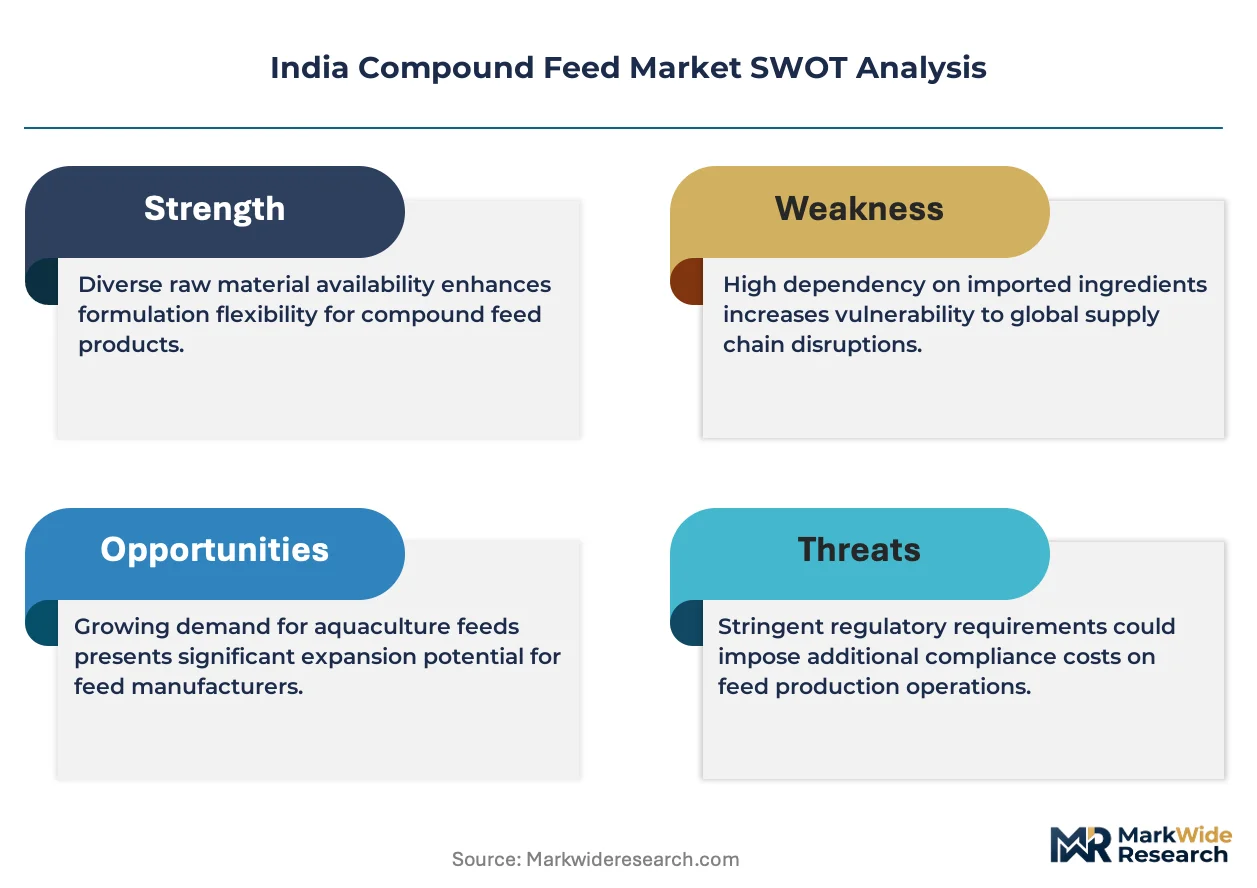
BIS mandates on maximum aflatoxin levels and crude protein labeling accuracy shape product liability exposure for millers operating across state lines. The PLI scheme for animal husbandry inputs and FSSAI-adjacent state feed control laboratories collectively redirect investment toward certified manufacturing infrastructure rather than unorganized blending units. Stakeholders must monitor how state-level dairy development boards reconcile cooperative procurement pricing with escalating micronutrient fortification costs.
Market Dynamics
Dairy cooperatives in Maharashtra and Gujarat are enforcing milk solids-linked incentive pricing, forcing feed millers to upgrade micronutrient fortification capabilities or lose procurement contracts.
Growth Catalysts
- PLI scheme for animal husbandry inputs:Production-linked incentives are redirecting capital toward certified manufacturing infrastructure and away from unorganized blending units.
- BIS feed-grade certification mandates:Tighter aflatoxin thresholds and crude protein labeling requirements are consolidating demand around quality-compliant millers.
- Poultry belt concentration:Broiler integration across Telangana, Andhra Pradesh, and Tamil Nadu is standardizing mechanized feed distribution at scale.
Market Restraints
- Maize and soybean meal volatility:Input costs swing with monsoon-dependent domestic harvests and import parity pricing from Argentina and Brazil.
- Premix supply concentration:Technical-grade vitamins and amino acids depend on a narrow base of Chinese and European chemical manufacturers.
- BIS cross-state enforcement gaps:Feed control laboratories vary in testing capacity, creating compliance arbitrage between organized and unorganized producers.
Strategic Opportunities
- Subscription-based formulation software:Nutritional advisory services are decoupling from physical product sales, locking in farmer relationships through data-driven ration optimization.
- Aquaculture feed certification:Shrimp export standards are tightening, creating margin pools for traceable, antibiotic-free formulations.
- Backward integration into premix manufacturing:Captive production of micronutrient blends near southern production bases reduces import dependency and freight costs.
Industry Challenges
- Skilled nutritionist scarcity:Species-specific formulation expertise lags behind dairy cooperative demand for precision rationing.
- Cooperative procurement pricing tension:State dairy development boards struggle to reconcile farmer milk price floors with escalating fortification input costs.
- Legacy blending unit retrofit costs:Unorganized millers face prohibitive capex to meet BIS pelleting and storage infrastructure standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Compound Feed Market |
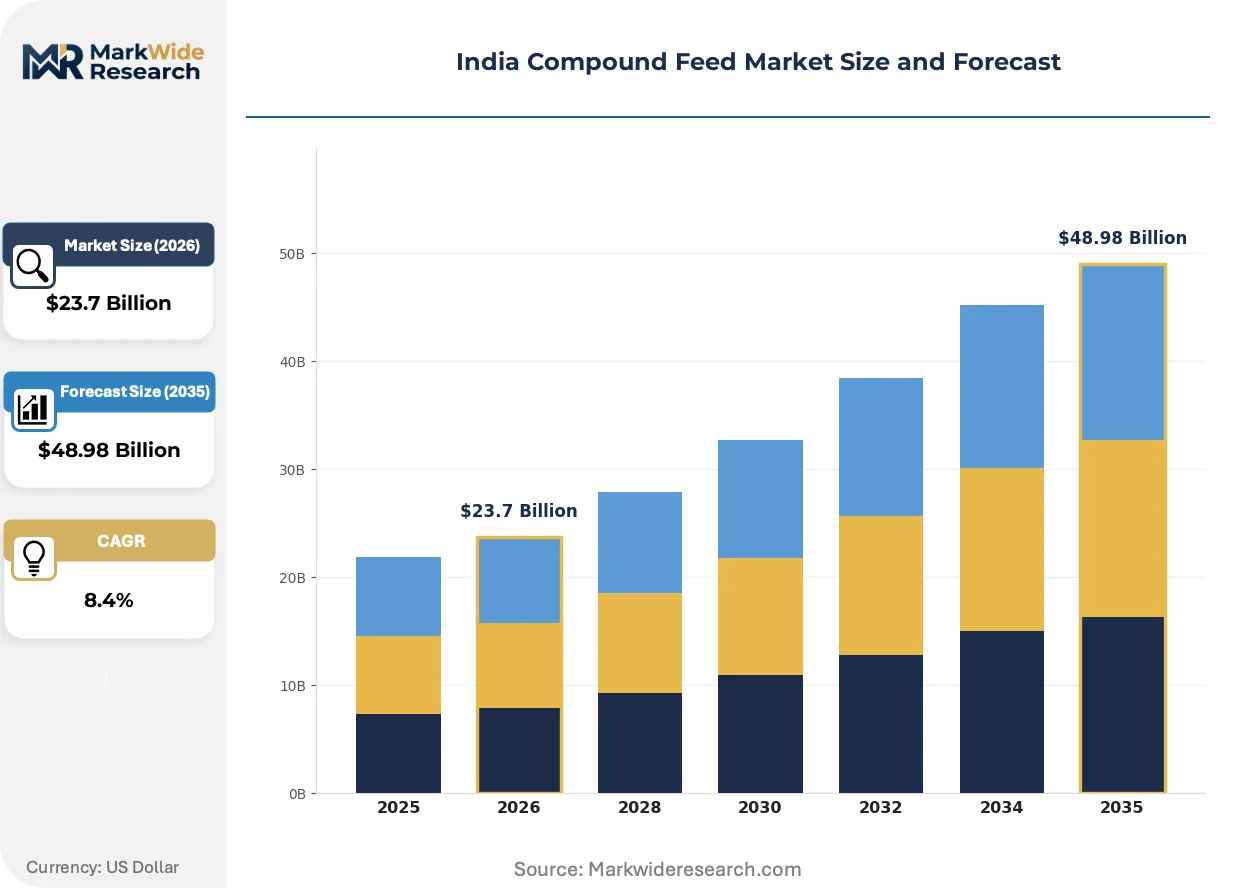
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Aquaculture Feed, Pet Food End User: Farmers, Livestock Producers, Pet Owners, Aquaculture Operators Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Wholesale Feed Grade: Standard Grade, Premium Grade, Organic Grade, Specialty Feed |
| Companies Covered | Japfa Comfeeds India Pvt Ltd, De Heus India, Godrej Agrovet Limited, Anmol Feeds Pvt. Ltd, Venkateshwara Hatcheries Pvt. Ltd., Cargill Incorporated, Nutreco N.V., SKM Animal Feeds & Foods (India) Private Limited, Suguna Foods Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Compound Feed Market Shifts & Advancements
Precision livestock technologies and regulatory quality mandates are compressing the gap between commodity feed and performance-optimized nutrition across India's fragmented smallholder base.
Near-infrared spectroscopy for real-time ingredient analysis is converging with cloud-based formulation platforms. Large dairy cooperatives in Gujarat are deploying these systems at procurement collection centers. The technology is converging with farmer mobile penetration to enable dynamic ration adjustments based on milk output data.
BIS mandates on maximum aflatoxin levels and mandatory crude protein disclosure are reshaping product liability exposure. Millers now carry batch-level testing documentation across state lines. Poultry integrators in Andhra Pradesh and Tamil Nadu are most affected, responding by consolidating supplier bases around certified manufacturing partners.
Cooperative procurement boards are unbundling nutritional advisory from feed supply, forcing millers to compete on formulation value rather than volume discounts. Subscription software vendors are inserting themselves between traditional distributors and dairy farmers. This shift is most visible in Maharashtra's cooperative corridor where milk unions now specify nutrient density targets rather than brand names in tender documents.
India Compound Feed Market Segmentation
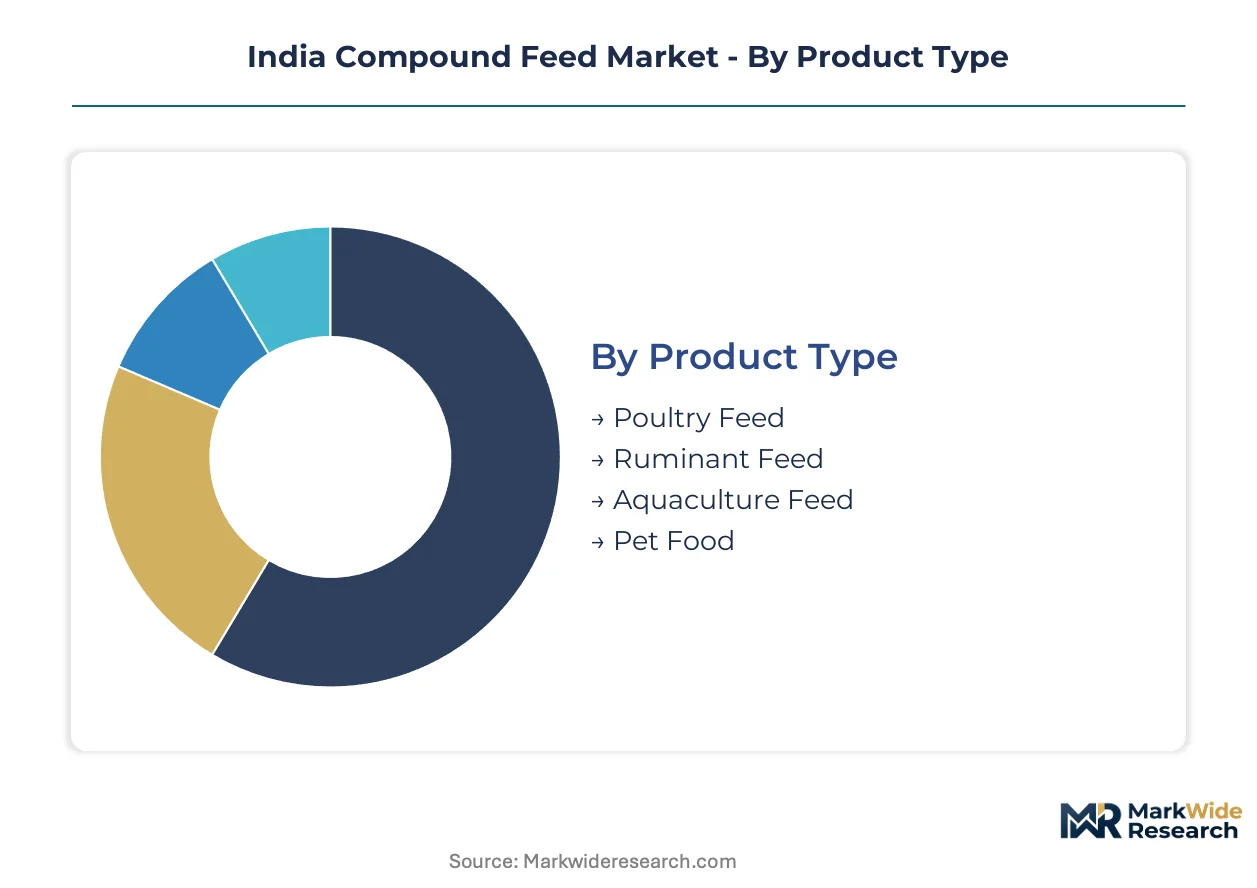
Segmentation in India's compound feed market determines which millers capture procurement contracts from dairy cooperatives, poultry integrators, and aquaculture exporters. BIS certification requirements vary sharply across product grades, creating compliance moats that reshape competitive boundaries.
Product Type:
Poultry feed carries mandatory BIS IS 1374 certification for crude protein disclosure, while aquaculture feed faces additional FSSAI-adjacent state laboratory testing for antibiotic residues.
- Poultry Feed:Broiler and layer rations formulated with maize, soybean meal, and synthetic amino acids to optimize feed conversion ratios. Demand concentrates in Telangana, Andhra Pradesh, and Tamil Nadu where integrators enforce mechanized distribution standards. BIS pelleting mandates have eliminated unorganized suppliers from tender pools.
- Ruminant Feed:Dairy-optimized blends balancing bypass protein, bypass fat, and chelated minerals for milk solids enhancement. Procurement boards in Maharashtra and Gujarat now specify nutrient density targets rather than brand names, forcing millers to demonstrate formulation precision through batch documentation.
- Aquaculture Feed:Shrimp and fish diets requiring traceable, antibiotic-free certification for export market access.
- Pet Food:Niche category driven by urban household pet ownership expansion in metropolitan corridors.
Leading the category by volume: Poultry Feed. Growing fastest: Aquaculture Feed.
End User:
Cost tier segmentation separates price-sensitive smallholders from integrators willing to pay formulation premiums for productivity-linked outcomes.
- Farmers:Fragmented smallholders purchasing through cooperative procurement boards or retail networks. Maharashtra's dairy unions aggregate demand to negotiate micronutrient fortification standards.
- Livestock Producers:Commercial operations with direct mill relationships and volume-based contracting.
- Pet Owners:Urban consumers driving premium and organic grade demand through veterinary clinic channels.
- Aquaculture Operators:Export-oriented shrimp farms requiring certified feed documentation for international market access.
Highest volume concentration: Farmers. Steepest margin expansion: Aquaculture Operators.
Distribution Channel:
Channel selection reflects geographic infrastructure maturity, with southern states favoring direct sales while northern corridors retain retail dominance.
- Direct Sales:Mill-to-farm delivery for poultry integrators and large dairy cooperatives. De Heus India and Godrej Agrovet leverage veterinary service networks to lock in recurring orders through embedded advisory relationships.
- Retail Outlets:Kirana-format feed shops serving unorganized dairy farmers in Bihar, Uttar Pradesh, and Madhya Pradesh.
- Online Platforms:Emerging channel for formulation software subscriptions and premix reorders among tech-adopting cooperatives.
- Wholesale:Aggregator intermediaries supplying regional distributors in fragmented procurement zones.
Dominant channel by tonnage: Direct Sales. Fastest channel expansion: Online Platforms.
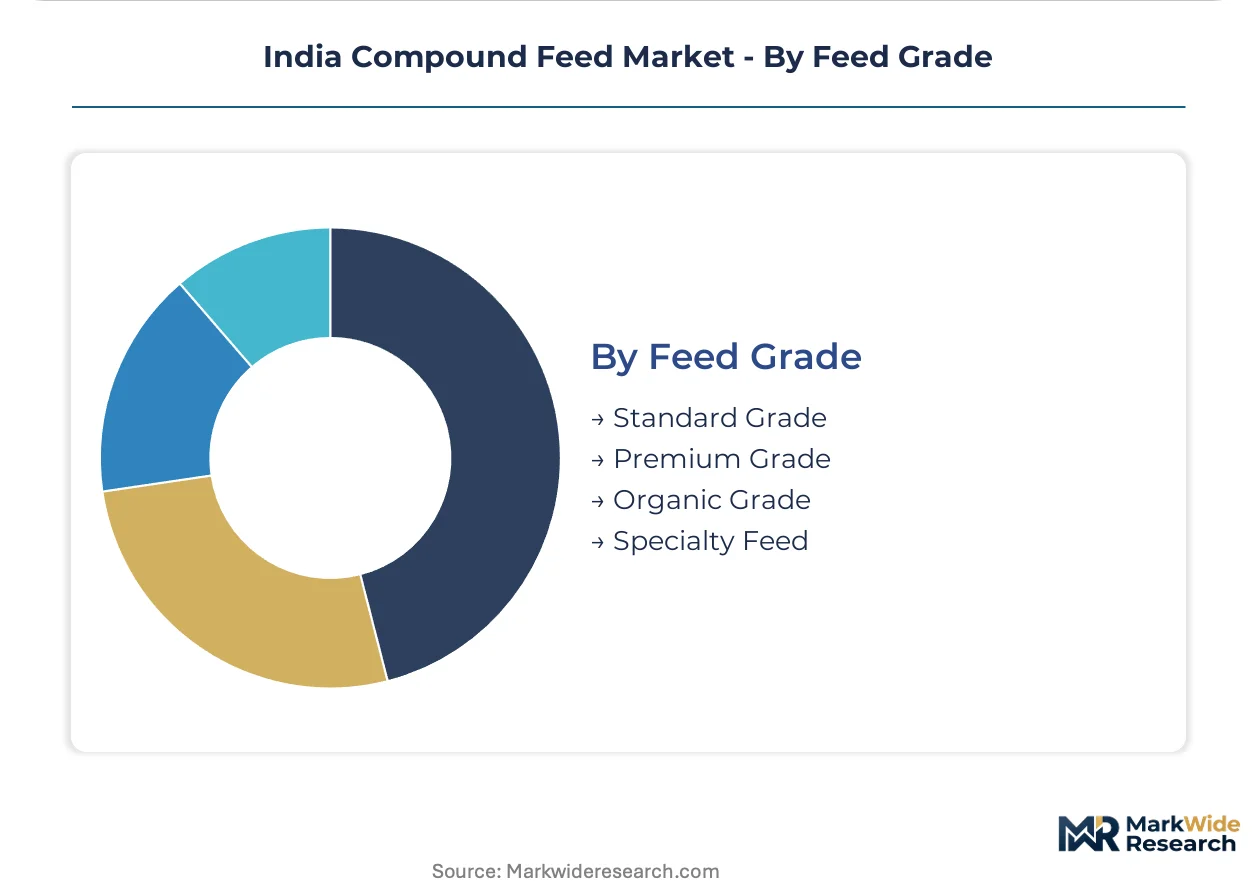
Feed Grade:
Grade stratification aligns with certification burden intensity, from basic BIS compliance to organic accreditation requiring full supply chain audit trails.
- Standard Grade:Baseline formulations meeting minimum BIS crude protein and maximum aflatoxin thresholds. Procurement is consolidating around quality-compliant millers as state feed control laboratories expand testing capacity.
- Premium Grade:Performance-optimized rations with specified amino acid profiles and chelated mineral inclusion for dairy cooperatives enforcing milk solids-linked incentive pricing.
- Organic Grade:Feed produced without synthetic additives, requiring third-party certification for export-oriented livestock operations.
- Specialty Feed:Species-specific formulations for exotic breeds, racing equines, or therapeutic nutritional interventions.
Volume leader: Standard Grade. Gaining share fastest: Premium Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in southern and western India while consumption spreads across dairy-intensive northern corridors. Feed millers navigate this geographic mismatch through dedicated distribution networks anchored to poultry integrators and cooperative procurement boards.
Maharashtra
Dairy cooperatives in Kolhapur and Nashik enforce milk solids-linked incentive pricing that forces micronutrient fortification upgrades. The state's dairy development board reconciles farmer price floors with escalating input costs through tender specifications. Mumbai-Pune industrial corridor hosts formulation software vendors inserting themselves between traditional distributors and milk unions.
Gujarat
Amul-fed dairy networks represent the country's most sophisticated cooperative procurement system for bypass protein and chelated mineral blends. BIS feed-grade certification mandates from the Bureau of Indian Standards operate with full enforcement capacity here. Anand and Mehsana districts concentrate premix manufacturing investments triggered by PLI scheme incentives for animal husbandry inputs.
Andhra Pradesh
Broiler integration density across Guntur and East Godavari districts standardizes mechanized feed distribution at unmatched scale. State feed control laboratories maintain testing parity with BIS aflatoxin thresholds, eliminating compliance arbitrage. De Heus India anchors backward integration into premix manufacturing near its Nellore production base to capture margin pools.
Telangana
Poultry belt expansion around Hyderabad drives demand for synthetic amino acid formulations and precision pelleting infrastructure. The state's veterinary university corridor supplies scarce species-specific nutritionist expertise to integrators. Medak and Rangareddy districts attract grain sourcing operations controlling maize corridors from neighboring Madhya Pradesh.
Tamil Nadu
Layer and broiler operations across Namakkal and Salem districts maintain India's highest feed conversion ratio benchmarks. Aquaculture feed certification requirements for shrimp export markets concentrate technical talent in coastal Thoothukudi and Nagapattinam clusters. FSSAI-adjacent state laboratory testing for antibiotic residues shapes supplier qualification protocols.
India Compound Feed Market Competitive Landscape
Top-tier vendors anchor integrated poultry and dairy supply chains, while mid-tier millers compete on formulation precision for cooperative procurement tenders. The vendor base stratifies across three archetypes: multinational grain traders controlling bulk sourcing corridors, domestic agribusiness conglomerates leveraging veterinary service networks, and regional specialists optimizing for single-species segments. Consolidation pressure intensifies as BIS pelleting mandates raise retrofit costs for unorganized blending units. Capacity expansion near southern grain corridors and strategic partnerships with dairy development boards represent the dominant competitive moves.
Among Dutch-origin integrated nutrition specialists, De Heus India and Nutreco N.V. exemplify the premix manufacturing archetype through captive micronutrient production near southern feed bases. Domestic agribusiness conglomerates Godrej Agrovet Limited and Cargill Incorporated occupy positions spanning veterinary advisory services and bulk grain sourcing control. Japfa Comfeeds India Pvt Ltd represents the Southeast Asian integration model adapted to Indian poultry belt economics. These anchors illustrate how geographic production positioning and certification compliance separate procurement contract winners from tender-excluded competitors.
| Leading Market Players |
|---|
| Japfa Comfeeds India Pvt Ltd |
| De Heus India |
| Godrej Agrovet Limited |
| Anmol Feeds Pvt. Ltd |
| Venkateshwara Hatcheries Pvt. Ltd. |
| Cargill Incorporated |
| Nutreco N.V. |
| SKM Animal Feeds & Foods (India) Private Limited |
| Suguna Foods Private Limited |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap millers across Maharashtra and Gujarat anchor procurement relationships through cooperative financing structures that simultaneously constrain pricing flexibility and enforce supply discipline. Their embedded position within dairy development board tender systems creates bid-ask compression when maize and soybean meal volatility spikes, forcing margin absorption or farmer price renegotiation.
Pricing Analysis
Margin tightening in premium-grade ruminant formulations reflects escalating chelated mineral and bypass protein input costs. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified millers from unorganized blending units, with certification grade and volume scale as primary differentiation drivers. Cost-down pressure on standard-grade poultry feed accelerates because integrators consolidate supplier bases around mechanized pelleting capabilities. Smallholder farmers through cooperative procurement boards exhibit highest price sensitivity, while export-oriented aquaculture operators accept formulation premiums for antibiotic-free certification.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Nellore and Guntur production clusters across Andhra Pradesh's poultry belt, with regional distribution centers buffering monsoon-dependent grain flow variability. Geographic supply concentration centers on India for maize and soybean meal, with critical vitamin and amino acid premixes drawing from China and European chemical manufacturers. Single-source vulnerability in technical-grade micronutrients creates procurement risk when DGFT import clearance timelines extend. Distribution runs through direct mill-to-farm channels for integrators and cooperative collection centers for dairy procurement boards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into premix manufacturing represents the decisive upstream lever in this vertical-integration race, with captive micronutrient production separating contract winners from tender-excluded competitors.
For Market Incumbents: Cement procurement relationships by embedding veterinary advisory services within dairy cooperative networks, neutralizing subscription-based formulation software entrants. Defend margin position through captive premix manufacturing investments near southern grain corridors, offsetting import dependency risks from Chinese and European chemical suppliers.
For New Entrants and Emerging Players: Launch via subscription-based nutritional advisory platforms targeting Maharashtra's cooperative corridor, where milk unions now specify nutrient density targets rather than brand names. White-space concentration exists in aquaculture feed certification for antibiotic-free shrimp export formulations, with FSSAI-adjacent state laboratory testing creating compliance moats against unorganized competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor BIS-noncompliant blending units in Bihar and Uttar Pradesh facing prohibitive retrofit capex, with PLI scheme incentives for animal husbandry inputs providing post-acquisition rehabilitation funding. Monitor state feed control laboratory testing capacity expansion as inflection indicator for compliance arbitrage elimination between organized and unorganized producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Manufacturing | Captive micronutrient production near Andhra Pradesh bases reduces import dependency and freight costs. |
| Subscription-Based Formulation Software Launch | Decouples nutritional advisory from physical sales, locking in farmer relationships through data-driven optimization. |
| BIS Certification Infrastructure Investment | Pelleting and storage upgrades eliminate tender exclusion risks from cross-state enforcement gaps. |
| Aquaculture Feed Certification Program | Antibiotic-free traceability unlocks shrimp export margin pools through FSSAI-adjacent state laboratory compliance. |
| Veterinary Service Network Expansion | Embedded advisory relationships at cooperative collection centers secure recurring procurement contract renewals. |
Research Methodology
BIS regulatory filings, PLI scheme disbursement records, and state feed control laboratory capacity reports formed the secondary backbone, cross-referenced with primary interviews involving dairy cooperative procurement managers, poultry integrator nutritionists, premix manufacturing executives, and veterinary service network operators. Bottom-up triangulation across formulation software vendors and top-down validation through grain sourcing corridor analysis anchored volume and value estimates.
Historical trendline analysis of cooperative procurement tender awards and integrator supplier consolidation patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, feed grade tier, distribution channel, and end-user scale category. CAGRs derived from input cost elasticity modeling and BIS compliance penetration curves, with monsoon variability and import parity pricing as industry-specific forecast inputs.
Monsoon failure, DGFT import clearance delays, and state-level dairy price floor adjustments are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Mushroom Cultivation Market