
 Tarragon Market | 2026-2036
Tarragon Market Size, Share, and Industry Trends Forecast 2026-2036
Tarragon Market Outlook
Subscription-based spice replenishment services is repositioning how tarragon reaches end users, shifting volume from episodic retail purchases toward recurring household supply. McCormick & Company leverages its direct-to-consumer platform to capture recurring revenue in the home cook segment. Frontier Co-op anchors the organic and fair-trade channel through its cooperative sourcing model. Givaudan competes at the extract and flavoring level, supplying beverage and seasoning manufacturers with standardized tarragon oleoresin.
Tarragon, Artemisia dracunculus, is a perennial herb of the Asteraceae family containing estragole and anethole as signature volatile compounds, cultivated primarily for its aromatic leaves used in French cuisine and commercial flavoring. Dried tarragon commands the largest volume share due to extended shelf stability and lower logistics costs, while tarragon extract captures the highest margin pool through pharmaceutical and premium beverage applications. The food industry end-user segment leads absolute consumption, though culinary professionals represent the fastest-growing demand channel as restaurant recovery accelerates specialty herb procurement.
The FDA's Good Manufacturing Practices for dietary supplements and the EPA's pesticide tolerance standards for imported herbs both govern tarragon sold in the United States, while the EU's EFSA botanical safety assessments and REACH compliance for extracted compounds shape European market access. Organic certification under USDA NOP and EU 2018/848 regulations creates a dual-track supply structure that segments pricing and distribution channels. Stakeholders must monitor evolving botanical novel food classifications and pesticide residue thresholds as these standards increasingly determine which cultivation regions maintain market entry.
Market Dynamics
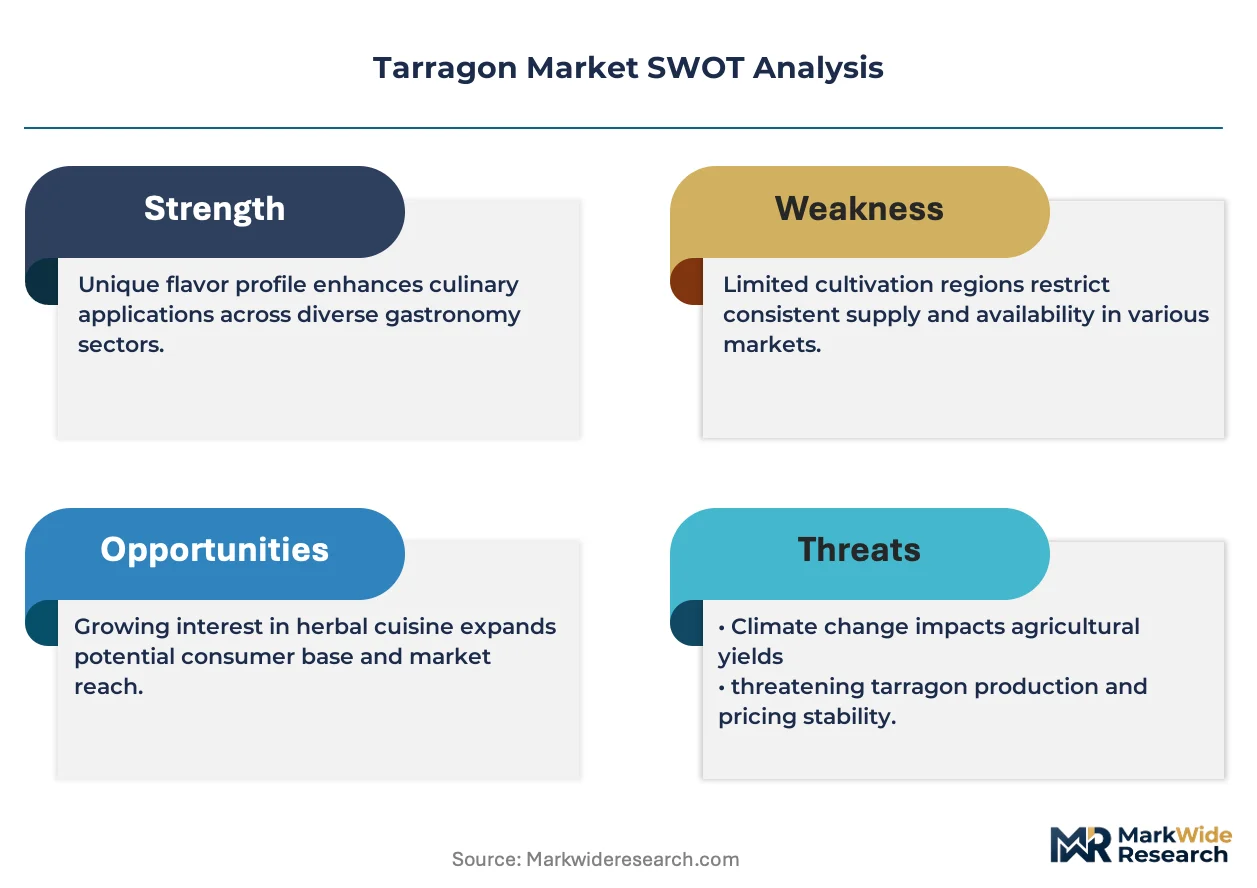
Protected geographic indication enforcement for Estragon de Béarn is concentrating supply authority among certified French growers while compressing margins for uncertified competitors across Eastern European cultivation zones.
Growth Catalysts
- EU Novel Food Regulation updates:Standardized botanical safety assessments under EFSA guidelines are accelerating market entry for tarragon extract suppliers who achieve pre-market authorization, consolidating the pharmaceutical-grade segment.
- Restaurant recovery procurement:Culinary professionals in France and Italy are expanding specialty herb purchasing as table-service volume rebounds, pulling premium French tarragon through wholesale foodservice channels.
- Controlled-environment agriculture:Hydroponic cultivation systems in the Netherlands are extending the fresh tarragon harvest window, reducing seasonal supply volatility for processors requiring year-round raw material input.
Market Restraints
- Input cost volatility:Natural gas prices for greenhouse heating in Poland and Romania are squeezing margins for dried herb processors dependent on energy-intensive dehydration equipment.
- Supply concentration risk:French tarragon seed stock is controlled by a narrow breeder network, creating genetic bottleneck vulnerability for cultivators outside the Béarn certification zone.
- Estragole content limits:EU Regulation 1333/2008 on food additives restricts estragole levels in flavorings, forcing reformulation costs on extract manufacturers targeting beverage applications.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland exhibit low per-capita tarragon consumption relative to Mediterranean benchmarks, presenting white-space potential for seasoning blend localization.
- Subscription channel expansion:Direct-to-consumer spice replenishment platforms are capturing recurring household demand that traditional retail has failed to secure.
- Organic certification arbitrage:USDA NOP and EU 2018/848 dual certification is commanding 35-40% price premiums in North American specialty retail, rewarding growers who bridge both regulatory frameworks.
Industry Challenges
- Pesticide residue compliance timelines:EPA tolerance verification for imported dried herbs requires 90-120 day testing cycles, straining working capital for traders sourcing from multiple origin countries.
- Botanical authentication complexity:Differentiating Artemisia dracunculus from adulterant species demands PCR-based testing infrastructure that small-scale cooperatives lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tarragon Market |
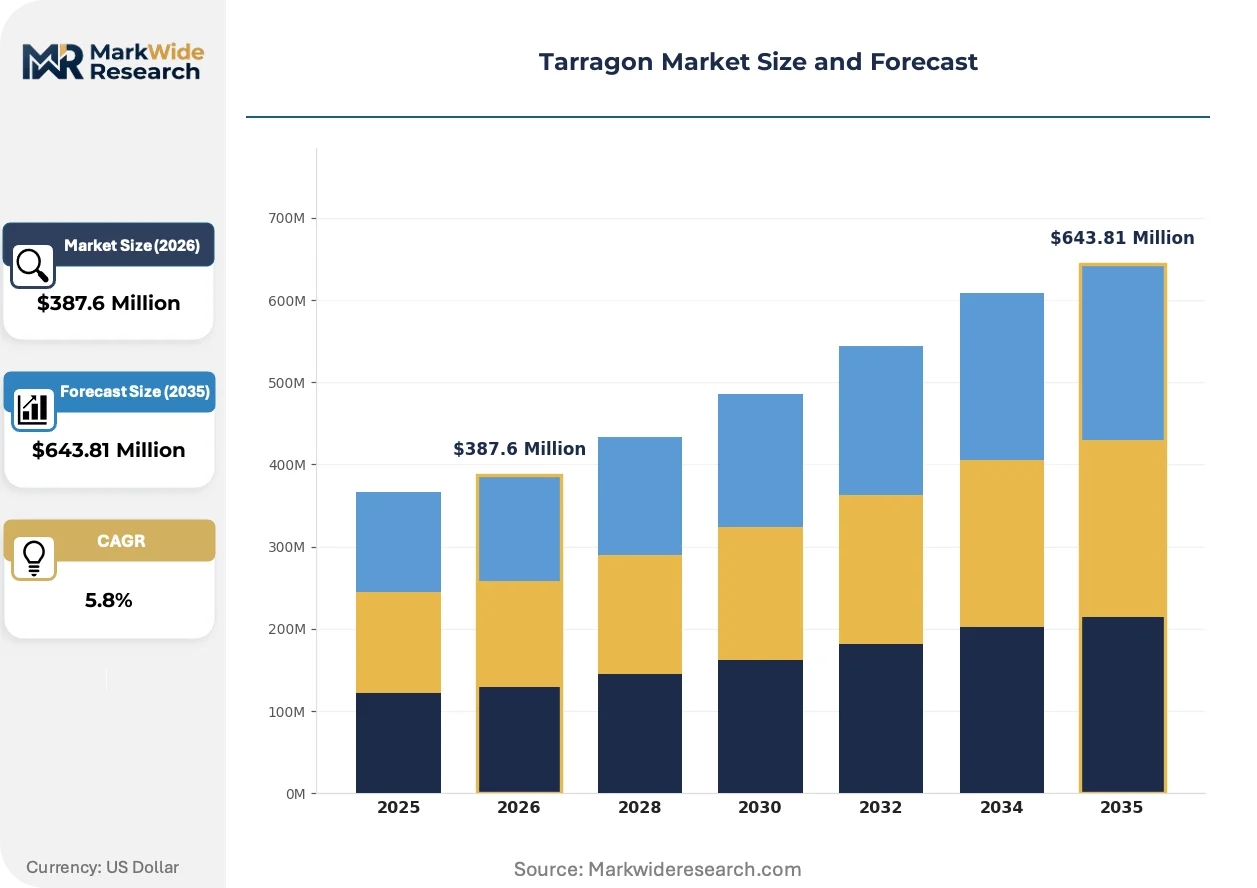
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Tarragon, Dried Tarragon, Tarragon Extract, Tarragon Powder End User: Food Industry, Beverage Industry, Culinary Professionals, Home Cooks Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Application: Seasoning, Medicinal Uses, Culinary Experiments, Beverage Enhancements |
| Companies Covered | Simply Organic, Badia Spices, McCormick & Company, Berje Inc., HillTop Foods Inc., Givaudan, Symrise AG, Watkins Incorporated, Frontier Co-op, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tarragon Market Strategic Shifts
Digital traceability infrastructure and extraction technology advances are compressing quality verification cycles while opening new application vectors for tarragon-derived compounds beyond traditional culinary use.
Supercritical CO2 extraction systems are converging with precision fermentation platforms to produce standardized tarragon oleoresin with consistent volatile compound profiles. Flavor houses serving beverage manufacturers are adopting these systems to reduce batch-to-batch variation that solvent-based methods introduced. This convergence is compressing the supplier base toward technology-integrated processors capable of pharmaceutical-grade documentation.
REACH compliance requirements for extracted botanical compounds are tightening substance registration obligations for EU market access. ECHA's updated guidance on UVCB substances is forcing non-EU extract suppliers to designate only representatives or establish EU-based formulation partnerships. The pharmaceutical and nutraceutical segments are responding by consolidating procurement relationships with REACH-registered suppliers who bear compliance burden directly.
Chef-driven preference for provenance-transparent sourcing is rotating demand toward single-origin dried herbs with documented harvest coordinates. Wholesale distributors serving white-tablecloth restaurants are replacing anonymous commodity tarragon with lot-traceable alternatives certified to specific French départements. This rotation is most visible in Paris and Lyon, where protected geographic indication documentation now appears on menu descriptions as a competitive signal.
Tarragon Market Segmentation
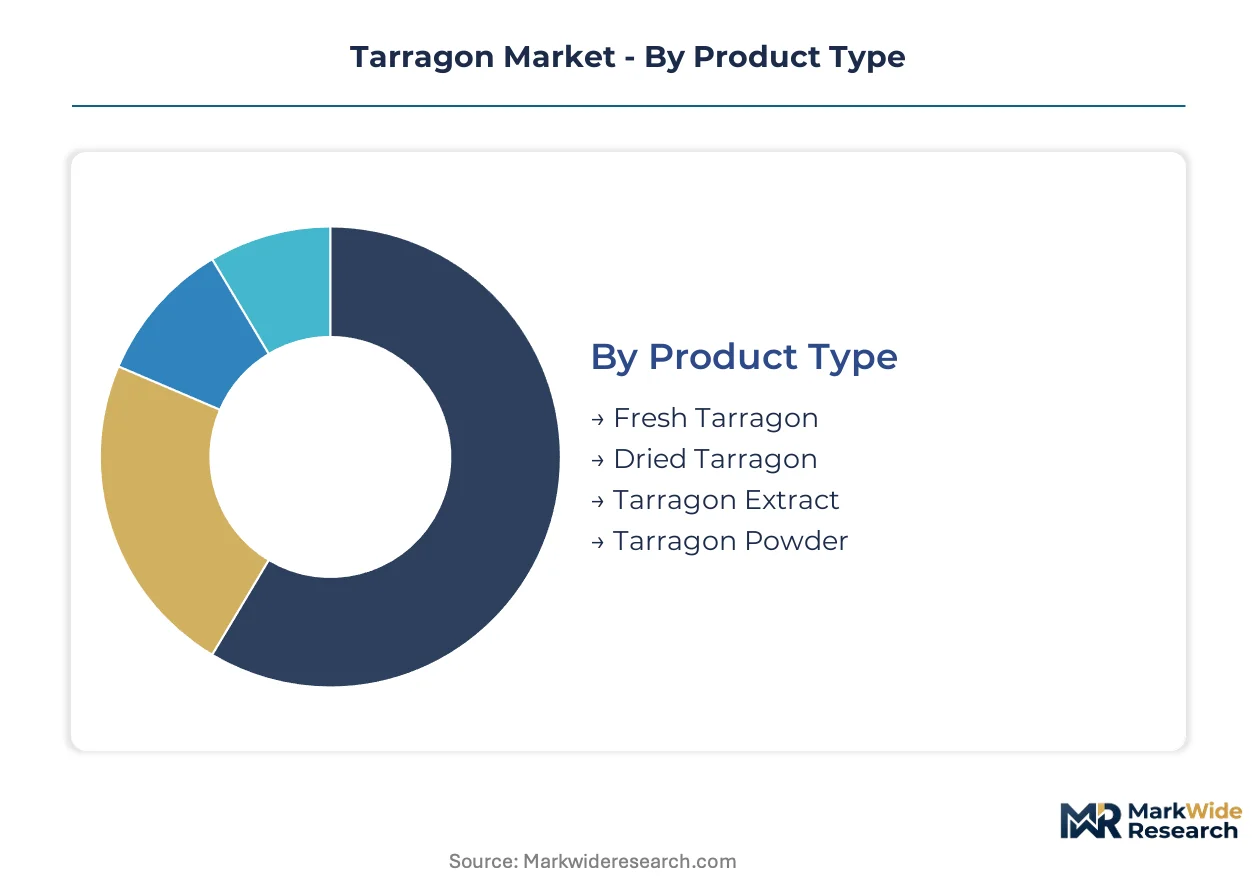
Tarragon procurement patterns diverge sharply between commodity-grade bulk purchasing and premium traceable supply chains. Buyers segment their sourcing strategies across shelf stability requirements, end-use certification standards, and channel-specific margin structures.
Product Type:
Buyers prioritize shelf stability and logistics economics when selecting among processed tarragon formats, with pharmaceutical and beverage manufacturers driving premium extract demand.
- Dried Tarragon:Dehydrated leaf material with moisture content below 10% enables ambient storage and ocean freight economics. Food manufacturers in France and Poland absorb the largest procurement volumes for seasoning blend production, constrained by energy-intensive dehydration costs.
- Tarragon Extract:Standardized oleoresin containing defined estragole and anethole concentrations serves flavor houses and pharmaceutical formulators. REACH-registered suppliers capture pharmaceutical-grade contracts requiring substance documentation under ECHA guidelines.
- Fresh Tarragon:Perishable whole herb with limited harvest windows demands cold-chain logistics and rapid turnover. Dutch hydroponic growers extend availability through controlled-environment systems.
- Tarragon Powder:Finely milled dried material offers dispersion advantages in dry seasoning applications. Industrial food processors specify particle size distribution for uniform blend integration.
Volume sits with Dried Tarragon; growth tilts toward Tarragon Extract.
End User:
End-user selection hinges on formulation complexity, batch scale, and documentation requirements for regulatory submission.
- Food Industry:Industrial seasoning manufacturers and prepared food processors constitute the largest absolute consumption channel. EFSA botanical safety assessments govern extract usage in EU-labeled products.
- Culinary Professionals:Restaurant chefs and institutional foodservice operators drive provenance-transparent sourcing with protected geographic indication documentation. Paris and Lyon wholesale distributors now stock lot-traceable single-origin material.
- Beverage Industry:Flavor houses supplying premium spirits and craft mixer manufacturers specify standardized volatile compound profiles. EU Regulation 1333/2008 estragole limits force reformulation investment.
- Home Cooks:Subscription-based replenishment services capture recurring household demand previously lost to episodic retail purchasing. McCormick's direct-to-consumer platform anchors this channel.
Absolute consumption concentrates in Food Industry; Culinary Professionals expand most quickly.
Distribution Channel:
Channel selection reflects buyer scale, certification verification needs, and inventory velocity requirements.
- Online Retail:E-commerce platforms enable subscription replenishment and direct-to-consumer traceability documentation. Specialty herb startups leverage this channel for organic-certified product lines.
- Supermarkets:Mass-market retail moves commoditized dried tarragon with limited provenance claims. Private-label penetration compresses branded margin pools.
- Specialty Stores:Gourmet retailers stock protected geographic indication-certified material with harvest documentation. Parisian épicerie fine chains anchor this channel.
- Direct Sales:Processor-to-manufacturer contracts bypass intermediaries for volume food industry procurement. REACH-registered extract suppliers consolidate pharmaceutical relationships through this channel.
Transaction volume flows through Supermarkets; margin capture concentrates in Direct Sales.
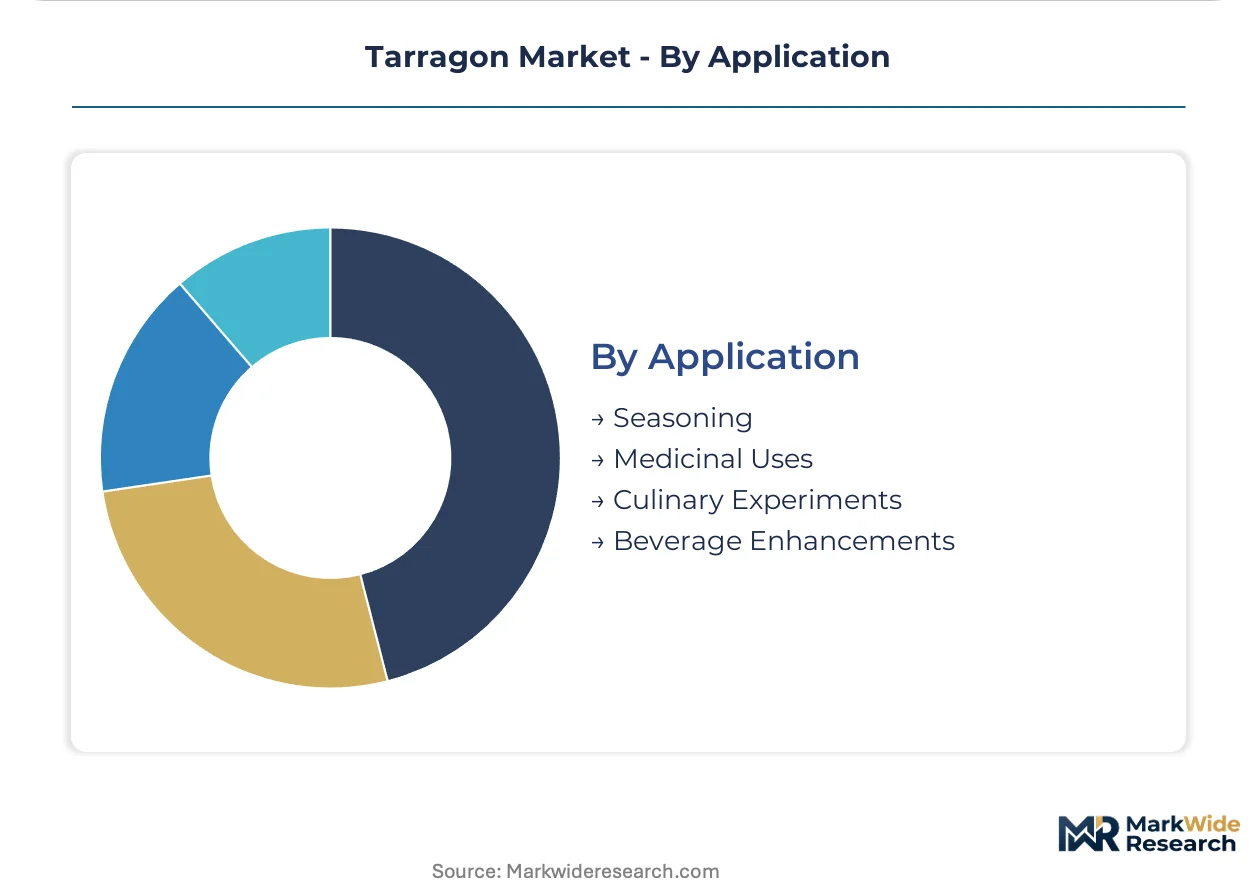
Application:
Application segmentation separates culinary tradition from emerging functional use cases with divergent regulatory pathways.
- Seasoning:Traditional culinary deployment in French cuisine drives consistent baseline demand. Estragon de Béarn protected geographic indication enforcement shapes premium pricing.
- Medicinal Uses:Botanical extract applications in digestive health formulations face EFSA novel food authorization requirements. Pre-market submission costs consolidate supplier bases.
- Beverage Enhancements:Craft spirits and non-alcoholic mixer segments adopt tarragon for signature flavor profiles. Standardized oleoresin reduces batch variation.
- Culinary Experiments:Fusion cuisine and experimental gastronomy create intermittent demand for unusual formats. Social media visibility accelerates niche ingredient discovery.
Seasoning anchors current volume; Medicinal Uses present the steepest expansion trajectory pending regulatory clearance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors tarragon commerce through its wholesale markets and protected geographic indication enforcement for Estragon de Béarn. Culinary professionals in the Île-de-France region drive premium procurement with documented provenance requirements. Regulatory frameworks and cultivation clusters across France, the Netherlands, Poland, the United States, and India shape regional supply dynamics.
France
Protected geographic indication enforcement for Estragon de Béarn concentrates supply authority among certified growers in Béarn and surrounding départements. EFSA botanical safety assessments govern extract usage in EU-labeled food products. Paris and Lyon wholesale distributors now stock lot-traceable single-origin material with harvest documentation appearing on restaurant menus.
Netherlands
Hydroponic cultivation systems in Westland and Veneto greenhouse clusters extend fresh tarragon harvest windows beyond traditional seasonal constraints. REACH compliance requirements for extracted botanical compounds shape substance registration obligations for EU market access. Dutch controlled-environment agriculture specialists supply year-round raw material to processors requiring consistent input volumes.
Poland
Natural gas price volatility for greenhouse heating squeezes margins for dried herb processors operating energy-intensive dehydration equipment. The country's national agricultural regulator monitors pesticide residue thresholds for export-bound material. Podlaskie and Mazovia cultivation zones serve as secondary supply sources for commodity-grade dried leaf material.
United States
FDA Good Manufacturing Practices for dietary supplements and EPA pesticide tolerance standards govern imported herb quality verification. McCormick & Company leverages its direct-to-consumer platform to capture recurring household demand through subscription replenishment services. California and Pacific Northwest organic certification clusters supply specialty retail channels with USDA NOP-compliant material.
India
FSSAI food safety standards and DGFT export documentation requirements frame market access for processed herb shipments. Favorable labor costs and expanding organic cultivation acreage position Indian suppliers for North American and European procurement. Gujarat and Rajasthan processing hubs concentrate dehydration capacity for export-oriented dried leaf production.
Tarragon Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the tarragon supply chain. Integrated cultivation-to-extraction operations in France and the Netherlands face competition from trading houses sourcing raw material across Eastern European and Asian origin points. Three archetypes dominate: protected geographic indication-certified growers with harvest documentation systems, commodity-grade bulk processors optimizing dehydration economics, and flavor houses deploying supercritical extraction technology. Consolidation pressures favor REACH-registered extract suppliers and subscription-platform operators with recurring revenue models.
Among North American seasoning manufacturers, McCormick & Company, Watkins Incorporated, and Frontier Co-op occupy positions spanning mass-market retail, direct-to-consumer subscription channels, and cooperative organic sourcing. McCormick exemplifies the platform-integrated archetype through its replenishment services. Watkins represents legacy brand distribution through traditional retail networks. Frontier Co-op anchors the cooperative sourcing model for fair-trade and organic-certified procurement. These three structures illustrate how channel specialization segments competitive positioning without requiring uniform vertical integration strategies.
| Leading Market Players |
|---|
| Simply Organic |
| Badia Spices |
| McCormick & Company |
| Berje Inc. |
| HillTop Foods Inc. |
| Givaudan |
| Symrise AG |
| Watkins Incorporated |
| Frontier Co-op |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between Estragon de Béarn protected geographic indication holders and commodity-grade Eastern European suppliers splits both pricing power and supply chain authority across parallel procurement channels. Premium French growers command documented provenance premiums through Paris and Lyon wholesale networks while Polish and Romanian processors absorb energy-cost compression in dehydrated bulk supply.
Pricing Analysis
Margin tightening in commodity-grade dried leaf reflects natural gas cost spikes for Polish and Romanian dehydration facilities. Three-tier pricing structure across protected geographic indication-certified, organic dual-certified, and conventional bulk grades segments buyer access. Price differentiation rests on certification documentation and harvest traceability rather than intrinsic quality metrics. Food manufacturers exhibit highest price sensitivity; pharmaceutical extract buyers demonstrate lowest elasticity due to regulatory submission requirements.
Supply Chain Analysis
Single-source vulnerability sits with French seed stock networks controlling Artemisia dracunculus varietal propagation outside certified zones. Raw material flows from France, Poland, and the Netherlands; extraction inputs draw from Indian and Chinese processing hubs. Supply chain risk centers on REACH registration bottlenecks for non-EU extract suppliers. Distribution runs through processor-to-manufacturer direct contracts for pharmaceutical-grade volumes, with wholesale foodservice channels handling fresh and dried culinary supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into seed stock and controlled-environment cultivation capacity is accelerating as incumbents seek supply security against geographic indication enforcement and genetic bottleneck exposure.
For Market Incumbents: Acquire hydroponic cultivation assets in the Netherlands to secure year-round fresh supply independent of seasonal field harvest. Consolidate procurement relationships with REACH-registered extract suppliers before ECHA substance registration deadlines eliminate non-compliant competitors. Genetic uniformity risk from narrow French breeder networks threatens long-term cultivar access. For New Entrants and Emerging Players: The premium-to-economy price gap in Nordic seasoning markets offers white-space entry below established Mediterranean brand recognition thresholds. Target Sweden and Finland through localized blend formulations adapted to regional palate profiles. Subscription-platform distribution bypasses entrenched retail slotting barriers that protect incumbent shelf presence. For Investors and Strategic Acquirers: Re-rating potential sits with dual-certified organic processors given USDA NOP and EU 2018/848 compliance arbitrage commanding specialty retail premiums. Long-term viability favors extraction technology operators with supercritical CO2 infrastructure and pharmaceutical-grade documentation capabilities. Monitor EFSA novel food authorization timelines for tarragon-derived digestive health applications as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Protected Geographic Indication Certification | Estragon de Béarn enforcement concentrates supply authority among documented French growers. |
| Controlled-Environment Cultivation Expansion | Dutch hydroponic systems reduce seasonal volatility for processors requiring consistent input. |
| Dual Organic Certification Pursuit | USDA NOP and EU 2018/848 compliance opens 35-40% price premium channels in North American specialty retail. |
| Supercritical Extraction Technology Deployment | Standardized oleoresin production reduces batch variation for beverage and pharmaceutical formulators. |
| Subscription Platform Development | Direct-to-consumer replenishment captures recurring household demand lost to episodic retail purchasing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with herb processors, wholesale distributors, flavor house procurement managers, and agricultural cooperative directors combined with EFSA guidance documents, EPA pesticide tolerance databases, and EU Novel Food Regulation submissions. Bottom-up cultivation volume estimates and top-down extract consumption figures underwent cross-validation.
Segment-level modeling tracked product type, end-user industry, distribution channel, and application across the analysis window. CAGRs derived from trend extrapolation against historical volatility patterns, with inputs including greenhouse energy cost indices, organic certification penetration curves, and restaurant recovery procurement surveys. REACH registration status and protected geographic indication enforcement timelines informed regulatory scenario weightings.
Underlying measurement precision varies by segment; pharmaceutical extract volumes carry tighter precision than culinary experiment applications given documentation requirements. Forecasts reflect assumptions on regulatory clearance timelines, energy cost normalization, and subscription adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Cage Free Eggs Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Honeysuckle Market