
 Netherlands Cashew Market | 2026-2036
Netherlands Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Cashew Market Foresight
Commodity trading margins is narrowing as processors capture more value through roasted and seasoned product lines. Nutland BV leverages its Rotterdam port proximity to control inbound African and Asian raw nut flows. Red River Foods sustains competitive differentiation through specialized roasting equipment and flavor development capabilities. Acomo anchors its position across European re-export channels with integrated sourcing from origin markets.
Netherlands cashews comprise the kidney-shaped seeds of Anacardium occidentale, typically harvested at moisture content below 8% and processed through steam-shelling or mechanical cracking to yield whole white kernels graded by size and color. Raw cashews dominate import volumes through Rotterdam, while roasted and seasoned variants command premium positioning in Dutch supermarkets and specialty retail. The snack industry segment absorbs the fastest-growing share of value-added output, with food manufacturers driving bulk procurement of paste and butter derivatives for confectionery and dairy-alternative formulations.
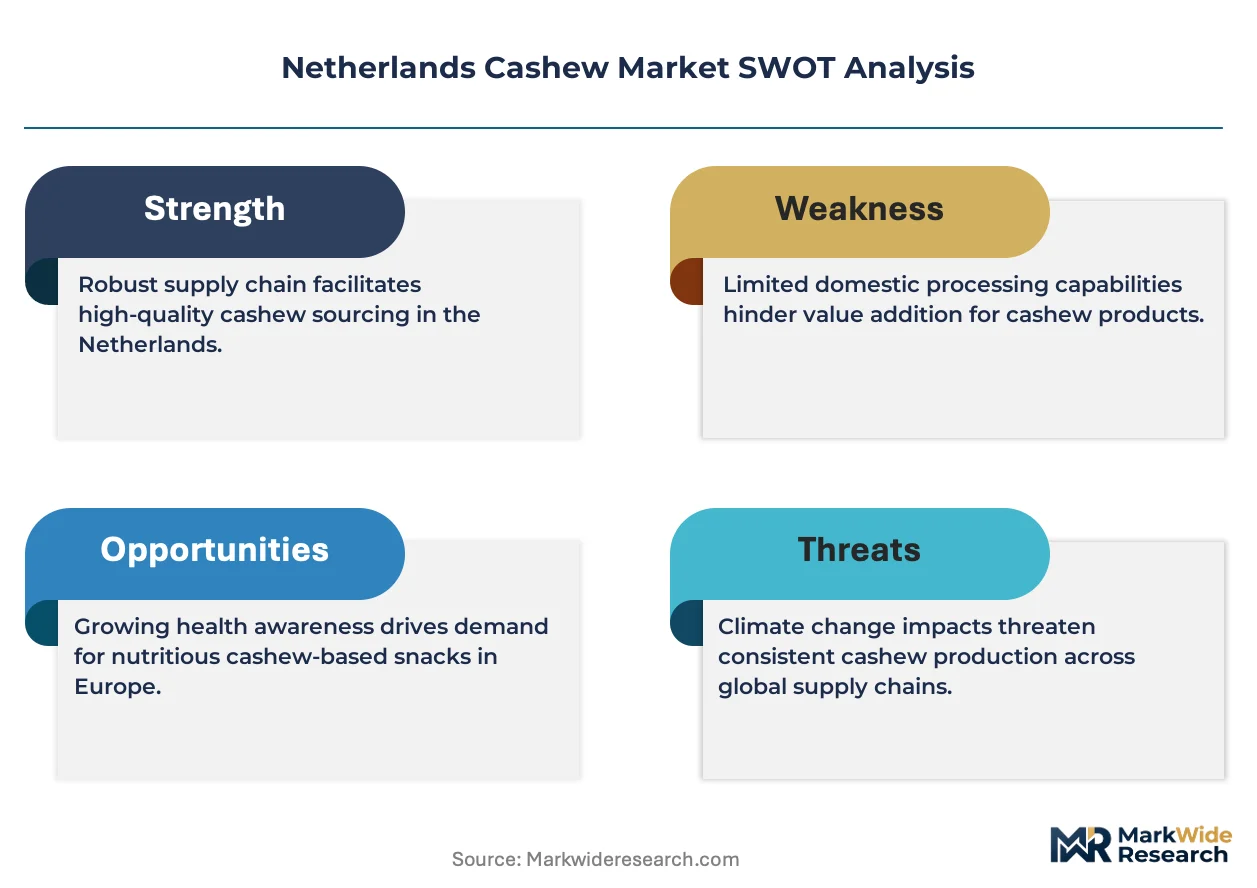
EU Deforestation Regulation due diligence obligations, EFSA food contact material standards, and Netherlands Food and Consumer Product Safety Authority import inspections collectively determine market access for non-EU suppliers. These frameworks mandate geolocation traceability for cashew orchards and restrict certain processing aids in roasted products. Stakeholders must monitor evolving EU Green Deal agricultural sourcing criteria and assess whether origin-country certification investments justify sustained Dutch market participation.
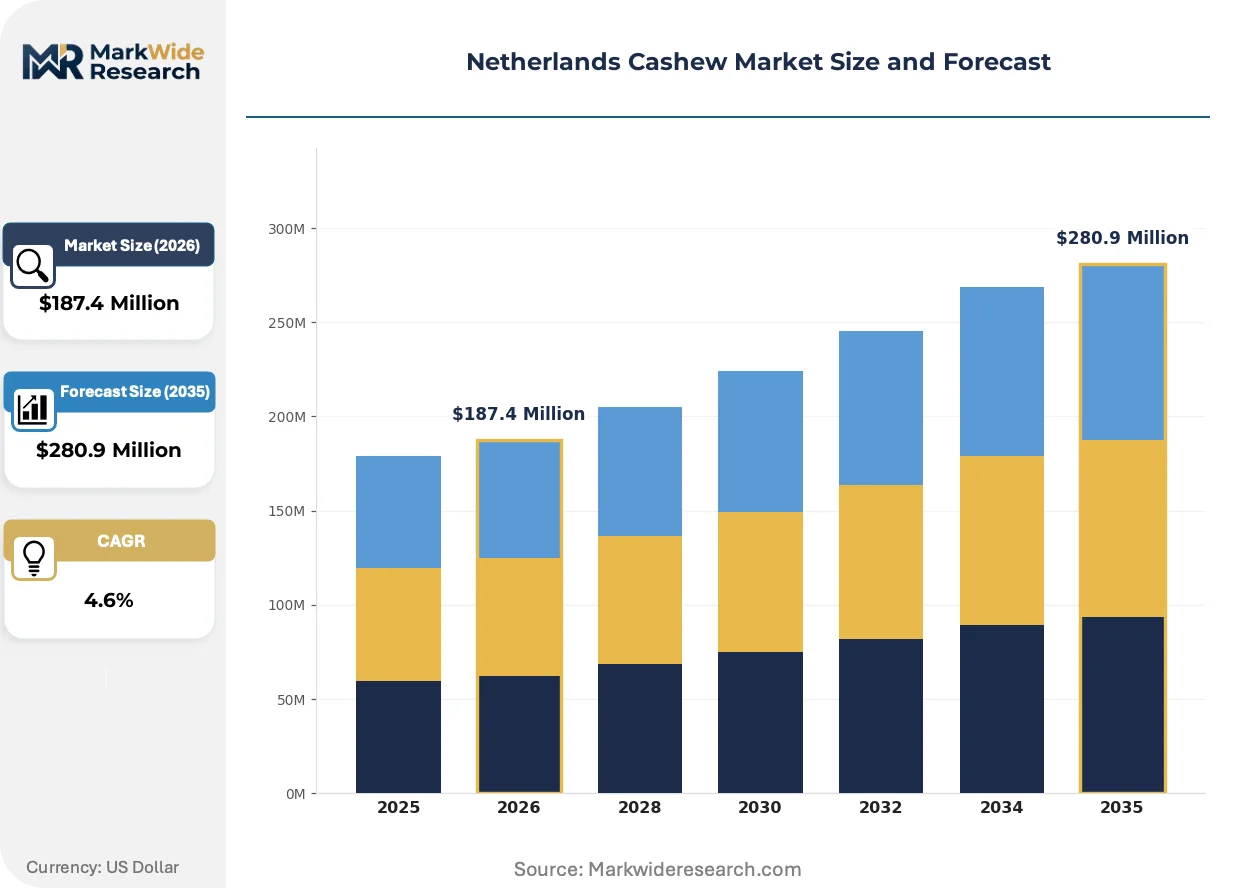
Market Dynamics
EU Deforestation Regulation geolocation traceability mandates are forcing Dutch importers to rebuild supplier verification systems from orchard documentation through Rotterdam port entry, compressing margins for traders lacking integrated African and Asian sourcing networks.
Growth Catalysts
- Plant-based protein reformulation:Dutch food manufacturers are expanding cashew paste and butter procurement for dairy-alternative and confectionery applications, driving bulk demand for processed derivatives.
- EFSA allergen labeling harmonization:Standardized disclosure requirements across EU member states reduce cross-border friction for seasoned and roasted product lines distributed through Dutch re-export channels.
- Rotterdam cold-chain infrastructure:Port-adjacent temperature-controlled storage and processing facilities enable just-in-time delivery to European snack manufacturers and retailers.
Market Restraints
- Raw nut price volatility:African and Asian origin harvest fluctuations transmit directly to Dutch processor input costs, squeezing commodity trading margins.
- Supplier concentration risk:West African and Vietnamese shelling operations control upstream kernel supply, limiting Dutch buyers' negotiating leverage on volume and quality specifications.
- EU Green Deal agricultural sourcing criteria:Evolving sustainability benchmarks threaten market access for origin-country producers unable to document carbon and water footprint compliance.
Strategic Opportunities
- Specialty retail channel expansion:Dutch supermarkets and organic food stores are creating dedicated shelf space for premium seasoned variants with origin storytelling and small-batch credentials.
- Confectionery application development:Cashew butter integration into praline fillings and chocolate spreads offers volume growth beyond traditional whole-kernel snack positioning.
- EU circular economy packaging mandates:Biodegradable and recyclable material requirements favor processors investing in sustainable packaging lines for private-label retail contracts.
Industry Challenges
- Geolocation documentation systems:EU Deforestation Regulation satellite verification and polygon mapping requirements demand IT infrastructure investments that smaller trading houses struggle to fund.
- Flavor development technical talent:Seasoned product innovation requires food technologists with spice-blend formulation expertise, a skill set scarce in traditional nut trading firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Cashew Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashews, Roasted Cashews, Seasoned Cashews, Cashew Butter Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale End User: Food Manufacturers, Retail Consumers, Food Service, Snack Industry Packaging Type: Bags, Tubs, Boxes, Bulk Packaging |
| Companies Covered | Global Trading & Agency BV, Red River Foods, Houz International BV, Nutland BV, Delinuts, Alamir Trading, Acomo, Nutco, Intersnack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Cashew Market Shifts & Advancements
Steam-shelling automation and digital traceability platforms are compressing processing economics while regulatory compliance technology absorbs an expanding share of capital deployment across Dutch cashew operations.
Advanced optical sorting systems employing hyperspectral imaging are rendering obsolete manual kernel grading for color and defect detection. Mid-sized Rotterdam processors are adopting these systems to meet supermarket private-label specifications for uniform appearance. The technology is rendering obsolete labor-intensive quality control stations that previously required 15-20 workers per shift.
EFSA food contact material standards for roasted product processing aids are tightening permissible substance lists and testing protocols. Dutch manufacturers must reformulate seasoning applications and validate new additive safety profiles through extended migration studies. Seasoned and flavored kernel segments face the steepest compliance timelines as existing product lines require reformulation or delisting.
Direct contracting between Dutch food manufacturers and African cooperative processors is shortening traditional multi-tier trading chains. Snack industry buyers are establishing volume commitments with origin-country shelling operations, bypassing Rotterdam commodity traders for core raw material supply. This pattern concentrates in organic and fair-trade certified segments where provenance verification commands price premiums.
Netherlands Cashew Market Segmentation
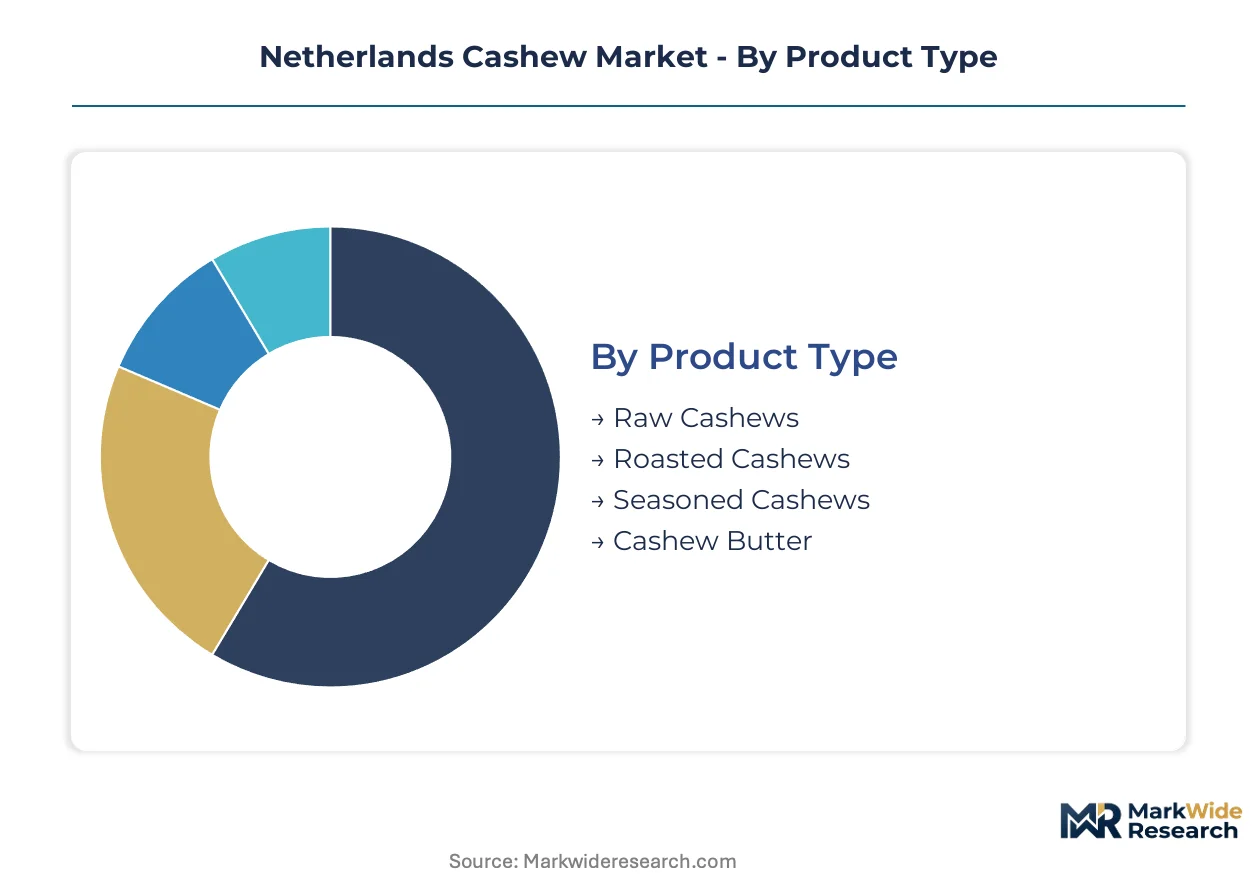
Cashew segmentation in the Netherlands reflects divergent margin profiles across processing intensity and channel access. Rotterdam port infrastructure and EFSA compliance requirements filter which product formats and distribution pathways sustain viable economics for Dutch operators.
Product Type:
Mature commodity grades coexist with emerging value-added formats as processors recapture margin from raw nut trading compression.
- Raw Cashews:Unprocessed kernels arriving through Rotterdam at moisture content below 8% for shelling and grading operations. Dutch importers concentrate procurement in West African and Vietnamese supply corridors where EUDR geolocation documentation now gates market access.
- Roasted Cashews:Heat-treated kernels processed through continuous roasting lines with oil or dry applications. Food manufacturers in the snack industry channel drive specification tightening for color uniformity and shelf-life extension.
- Seasoned Cashews:Flavor-infused variants with spice, salt, or sweet coatings requiring EFSA food contact material compliance for processing aids.
- Cashew Butter:Finely ground paste for confectionery fillings and dairy-alternative formulations, gaining formulation share from almond and peanut alternatives in Dutch plant-based product lines.
Raw Cashews retains volume leadership; Cashew Butter holds the steepest expansion curve.
Distribution Channel:
Channel economics split between high-touch specialty positioning and scale-driven wholesale throughput.
- Supermarkets:Mainstream retail commanding the largest throughput volumes with private-label and branded shelf placement. Albert Heijn and Jumbo specifications drive processor investment in optical sorting and uniform kernel grading.
- Wholesale:Bulk distribution to food service and manufacturing accounts with pallet-scale minimums. Rotterdam cold-chain facilities enable just-in-time delivery scheduling for industrial buyers.
- Specialty Stores:Organic and fair-trade focused retailers with provenance storytelling and small-batch credentials commanding price premiums.
- Online Retail:Direct-to-consumer and subscription formats bypassing traditional distributor markups for seasoned and gift-packaged variants.
Wholesale absorbs the greatest tonnage; Online Retail is climbing the fastest as direct brand relationships displace intermediary layers.
End User:
Demand concentration shifts toward formulation-intensive applications as commodity trading margins compress.
- Snack Industry:Roasted and seasoned kernel procurement for branded and private-label packaged snacks. Dutch manufacturers reformulate product lines around plant-based positioning.
- Food Manufacturers:Industrial buyers of cashew paste, butter, and broken grades for confectionery, bakery, and dairy-alternative applications.
- Food Service:Restaurants and catering operations sourcing bulk roasted kernels and ingredient formats for menu integration.
- Retail Consumers:Household purchasers of packaged whole kernels through supermarket and online channels.
Food Manufacturers dominate current procurement volumes; the Snack Industry shows the steepest upward trajectory on value-added product integration.
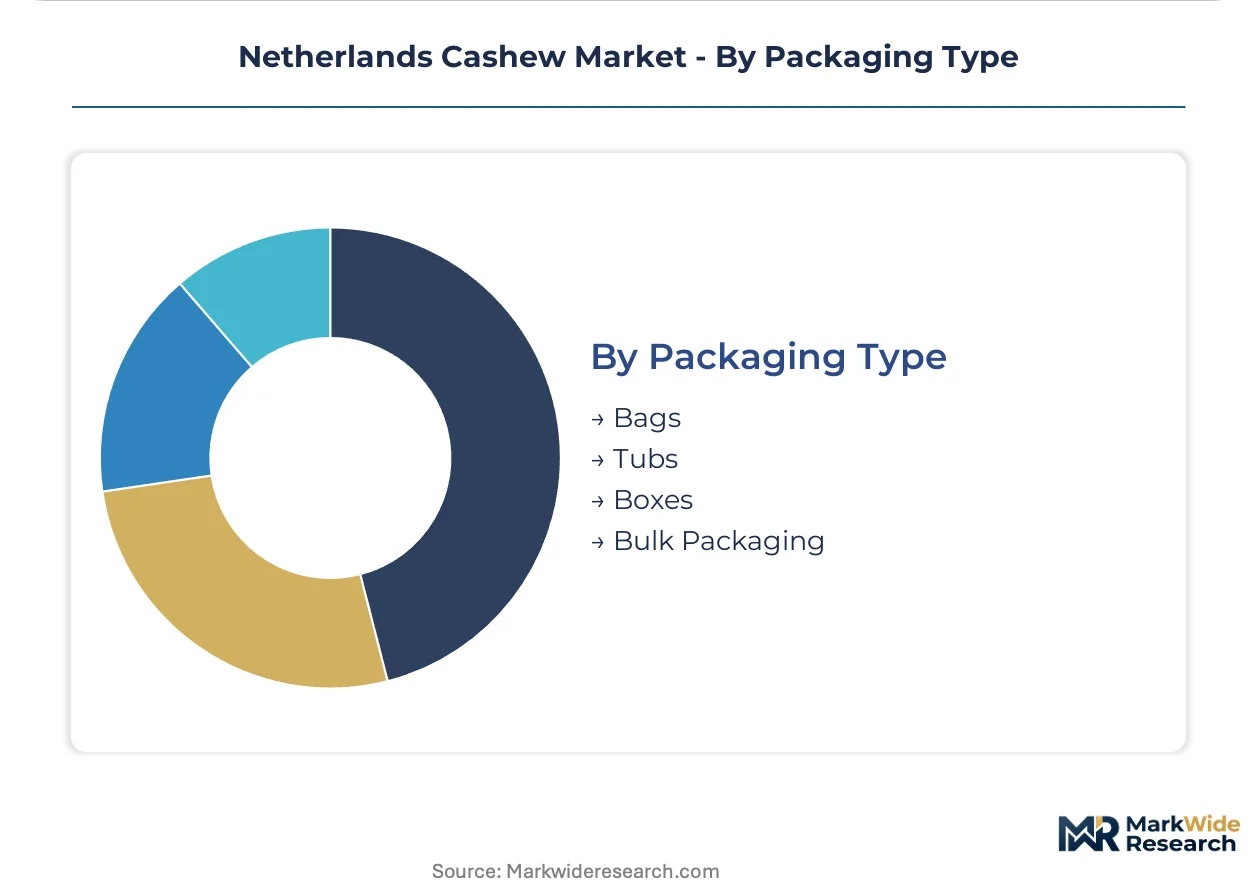
Packaging Type:
Packaging configuration tracks channel requirements and EU circular economy compliance timelines.
- Bags:Flexible retail pouches with reseal features for supermarket and convenience store placement. EU biodegradable mandates are forcing material transitions.
- Bulk Packaging:Industrial totes and sacks for food manufacturer and food service procurement. Rotterdam port-adjacent repackaging operations optimize logistics economics.
- Tubs:Rigid containers for cashew butter and paste formats requiring oxygen barrier properties.
- Boxes:Gift and premium assortments for specialty retail and seasonal demand concentration.
Bulk Packaging retains the largest shipment volumes; Bags face the steepest compliance-driven transformation curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cashew consumption patterns across Dutch provinces diverge sharply from neighboring markets, with Rotterdam's port-driven bulk handling contrasting against Randstad's premium retail concentration and southern Brabant's food manufacturing integration.
Randstad
Albert Heijn and Jumbo headquarters in Amsterdam and Utrecht drive specification tightening for optical-sorted kernels with uniform color grading. The Netherlands Food and Consumer Product Safety Authority enforces EFSA allergen labeling harmonization across this retail corridor. Cold-chain distribution hubs in Zoetermeer and Bleiswijk enable just-in-time replenishment for supermarket private-label programs.
Rotterdam Port Region
West African and Vietnamese raw nut flows enter through Europe's largest seaport for re-export across German and Belgian manufacturing channels. EU Deforestation Regulation geolocation documentation gates now filter inbound shipments at customs clearance points. Port-adjacent processors in Schiedam and Vlaardingen deploy automated steam-shelling lines to capture margin from commodity trading compression.
North Brabant
Food manufacturers in Eindhoven and Tilburg source cashew paste and butter derivatives for plant-based dairy alternatives and confectionery formulations. The province's technical universities supply food technologists for seasoned product innovation. Regional logistics parks connect to Belgian chocolate processing clusters via the A67 corridor.
Zeeland
Specialty organic and fair-trade importers concentrate in Middelburg and Vlissingen for small-batch provenance storytelling. EUDR satellite verification requirements favor established traders with documented African cooperative relationships. Cold storage facilities at the Western Scheldt port support niche re-export to Scandinavian specialty retailers.
Netherlands Cashew Market Competitive Landscape
Capability concentration sits with integrated origin-sourcing specialists; scale advantage sits with port-proximate processors with Rotterdam logistics access. The vendor base spans three tiers: African and Asian origin-integrated traders, Rotterdam-adjacent roasting and seasoning facilities, and branded snack manufacturers with private-label contracts. Dominant competitive moves include backward integration into West African shelling operations and flavor development talent acquisition from Dutch food science programs.
Within the origin-integrated tier, Nutland BV and Acomo exemplify port-proximate sourcing control, while Red River Foods occupies a position emphasizing specialized roasting equipment and flavor formulation capabilities. These three entities anchor distinct competitive vectors: inbound raw material gatekeeping, value-added processing infrastructure, and product development expertise respectively.
| Leading Market Players |
|---|
| Global Trading & Agency BV |
| Red River Foods |
| Houz International BV |
| Nutland BV |
| Delinuts |
| Alamir Trading |
| Acomo |
| Nutco |
| Intersnack |
| Others |
Supply & Pricing Matrix
Rotterdam's port-adjacent processing corridor concentrates raw nut intake capacity, translating upstream African and Vietnamese supply concentration into downstream pricing leverage for integrated traders. Dutch importers lacking captive shelling operations face margin compression as origin-country processors capture value through direct contracting with food manufacturers.
Pricing Analysis
Long-term offtake contracts dominate raw kernel procurement from West African and Vietnamese shelling operations, with spot purchases filling seasonal gaps. Three-tier pricing structure across premium, standard, and economy levels tracks kernel grade, EUDR certification status, and volume scale. Pricing pressure stems from commodity trading margin compression as direct origin-manufacturer relationships displace Rotterdam intermediaries. Private-label supermarket buyers exhibit highest price sensitivity; organic and fair-trade specialty channels absorb premiums with minimal volume elasticity.
Supply Chain Analysis
EU Deforestation Regulation geolocation traceability mandates restrict raw nut flows from non-compliant African and Vietnamese orchards, filtering Rotterdam port entry. Dutch supply chains draw from Ivorian, Ghanaian, and Vietnamese shelling capacity for raw kernel inputs, with cashew paste and butter derivatives resting on secondary processing equipment. Single-source vulnerability concentrates in West African cooperative supply where EUDR documentation gaps threaten volume continuity. Distribution runs through Rotterdam cold-chain facilities for re-export across German and Belgian manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor development services and EUDR compliance consulting represent recurring-revenue layers expanding faster than commodity kernel trading, as Dutch food manufacturers outsource technical formulation and documentation burdens.
For Market Incumbents: Harden EUDR geolocation documentation systems through satellite-verified polygon mapping investments that smaller trading houses cannot fund. Deepen backward integration into Ivorian and Ghanaian shelling cooperatives to secure origin supply against direct-manufacturer contracting. Prioritize flavor development talent acquisition from Wageningen University food science programs to defend value-added positioning. For New Entrants and Emerging Players: Establish a beachhead in cashew butter formulation for Dutch plant-based dairy alternatives, where technical barriers limit incumbent commodity traders. Target North Brabant food manufacturers with direct contracting models bypassing Rotterdam intermediaries. Lead with EUDR-compliant origin storytelling and small-batch credentials to capture specialty retail premiums. For Investors and Strategic Acquirers: Long-term, this sits as a processing-capability play because value capture is migrating from trading margins to roasting, seasoning, and derivative formulation infrastructure. Acquisition targets should emphasize Rotterdam port-proximate facilities with integrated African sourcing relationships. Watch EUDR enforcement intensity at Rotterdam customs as the signal for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shelling Operations | Ivorian and Ghanaian cooperative control secures EUDR-compliant raw kernel supply against direct-manufacturer displacement. |
| Flavor Development Laboratory Investment | Wageningen-trained food technologists enable seasoned product innovation beyond commodity kernel trading. |
| EUDR Compliance Technology Deployment | Satellite verification and polygon mapping systems filter Rotterdam port entry for integrated traders. |
| Cashew Butter Production Capacity Expansion | North Brabant food manufacturer demand for dairy-alternative formulations drives derivative volume growth. |
| Specialty Retail Channel Partnership | Albert Heijn and Jumbo private-label specifications require optical-sorted kernel uniformity investment. |
Research Methodology
Desk research of EUDR regulatory filings, EFSA food contact material standards, and Rotterdam port customs data preceded structured interviews with Dutch importers, African cooperative shelling managers, food manufacturer procurement leads, and flavor development technologists. Primary fieldwork combined with secondary validation from EU trade statistics, Netherlands Food and Consumer Product Safety Authority inspection reports, and Wageningen University food science publications. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and end-user segments.
Assumptions held EUDR geolocation traceability enforcement intensity and EFSA processing aid standards fixed across the analysis window, with African harvest yield volatility and EU Green Deal agricultural sourcing criteria treated as scenario variables. Segmentation modeling incorporated product format, channel access, and end-use application intensity dimensions. CAGRs derived from volume-weighted average growth rates across Rotterdam port throughput data and Dutch food manufacturer procurement surveys.
Sensitivities concentrate around EUDR satellite verification implementation delays, West African cooperative certification investment capacity, and EU Green Deal carbon footprint benchmarking evolution. Forecasts reflect documented assumptions on regulatory enforcement timelines and origin-country compliance investment trajectories. Material shifts in EUDR customs enforcement intensity or origin-country producer exit rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
GCC Compound Feed Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Organic Cassava Flour Market