
 Europe Guar Market | 2026-2036
Europe Guar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Guar Market Foresight
Spain's emerging guar fractionation capacity is reshaping import dependency patterns across Southern Europe. Cargill Incorporated leverages its Barcelona logistics hub to streamline Iberian distribution of food-grade guar derivatives. Nexira anchors premium pharmaceutical-grade supply through its French extraction facilities. Unipektin Ingredients AG dominates Swiss-refined guar splits for high-viscosity industrial applications.
Guar comprises the endosperm of Cyamopsis tetragonoloba seeds, yielding galactomannan polysaccharides with molecular weights exceeding 200 kDa and viscosities above 5,000 cP at one percent concentration. Food-grade guar gum functions as a stabilizer, thickener, and moisture-retention agent across bakery, dairy, and beverage formulations. Guar powder leads value capture due to pharmaceutical and food certification premiums, while guar meal expands fastest as protein-rich animal feed displaces soybean alternatives. Oil and gas applications remain structurally mature in Europe amid drilling activity constraints, though hydraulic fracturing specialty grades retain margin concentration.
EFSA purity standards and REACH registration requirements govern food-contact and industrial guar derivatives entering European customs territory. The EU Green Deal due diligence rules on deforestation-linked imports are reshaping sourcing verification for Indian and Pakistani supply chains. ECHA substance evaluation protocols are tightening residual solvent thresholds in pharmaceutical-grade fractions. Stakeholders must monitor regulatory divergence between EU-wide frameworks and member-state national enforcement practices to secure uninterrupted market access.
Market Dynamics
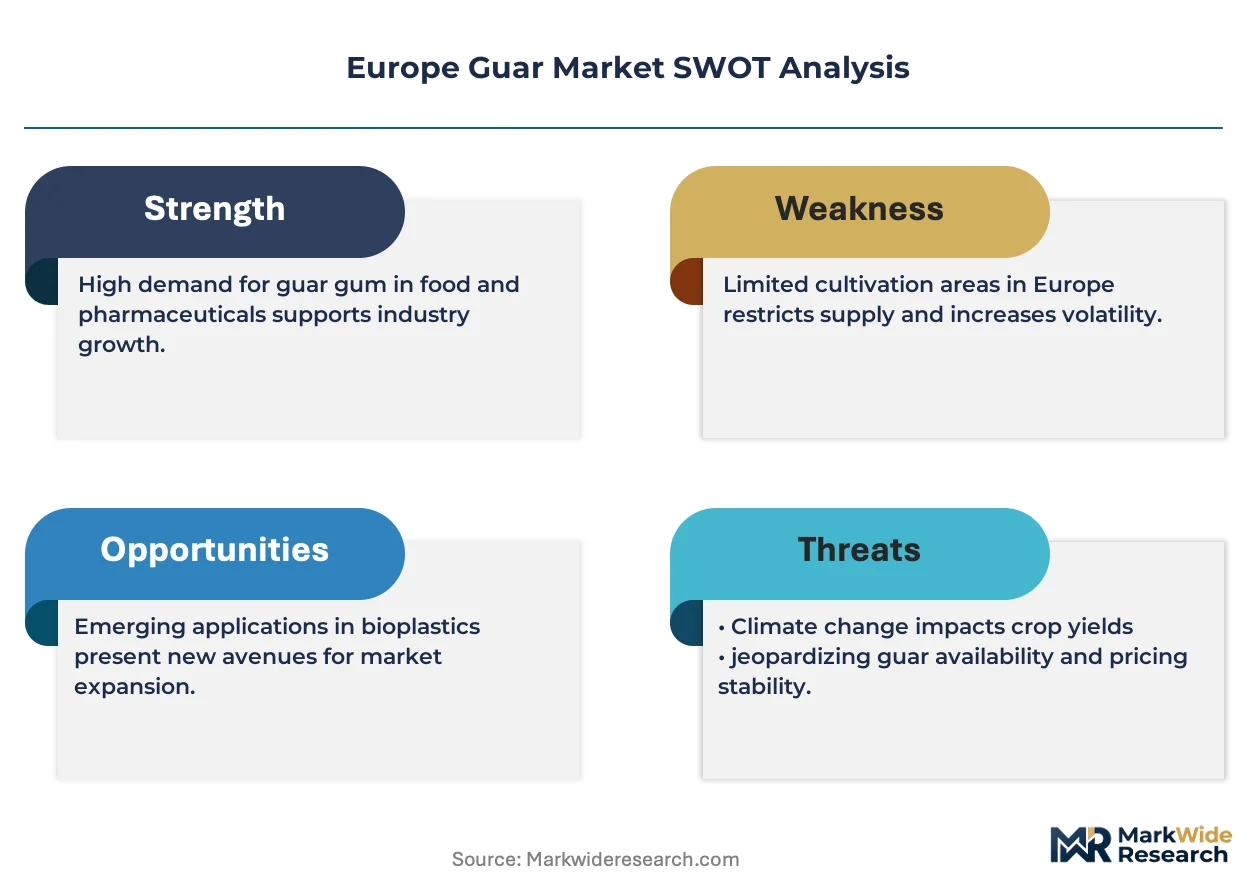
The EU Green Deal due diligence rules on deforestation-linked imports are restructuring sourcing verification requirements for Indian and Pakistani guar supply chains entering European customs territory. Food manufacturers now face mandatory traceability documentation that cascades backward through fractionation and refining stages.
Growth Catalysts
- Clean-label formulation mandates:EFSA purity standards for food-grade galactomannan derivatives are compelling bakery and dairy processors across Germany and France to expand guar gum procurement for stabilizer replacement.
- REACH registration tailwinds:Industrial-grade guar derivatives for hydraulic fracturing specialty applications benefit from streamlined substance evaluation protocols that reduce market entry friction for compliant suppliers.
- Protein displacement in feed:Guar meal is capturing volume from soybean alternatives as European livestock operations seek non-GMO, deforestation-free protein sources under CSRD supply chain disclosure rules.
Market Restraints
- Monsoon-dependent raw material concentration:Over 80 percent of global guar seed production clusters in Rajasthan and Gujarat, exposing European processors to climate volatility and freight cost spikes.
- Residual solvent threshold compression:ECHA substance evaluation protocols are tightening allowable limits in pharmaceutical-grade fractions, forcing capital-intensive extraction technology upgrades.
- Locust bean gum substitution:Mediterranean carob-derived galactomannans compete for clean-label positioning in premium dairy applications with shorter European supply chains.
Strategic Opportunities
- Iberian fractionation capacity expansion:Spain's emerging processing infrastructure is reducing Southern European dependency on Swiss and Dutch refining hubs for food-grade derivatives.
- Pharmaceutical-grade certification premiums:EMA-aligned GMP extraction capabilities command pricing multiples in oral solid dosage and controlled-release formulation segments.
- CSRD-aligned supply chain digitization:Blockchain-enabled provenance tracking satisfies EU Green Deal due diligence requirements while unlocking preferential procurement relationships with sustainability-mandated buyers.
Industry Challenges
- Galactomannan chemistry expertise scarcity:Fractionation engineers with dual competency in seed processing and pharmaceutical extraction are concentrated among Swiss and French technical institutes, constraining capacity scaling.
- Multi-jurisdictional certification timelines:Parallel EFSA food-contact approvals, REACH registrations, and national enforcement variations across member states extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Guar Market |
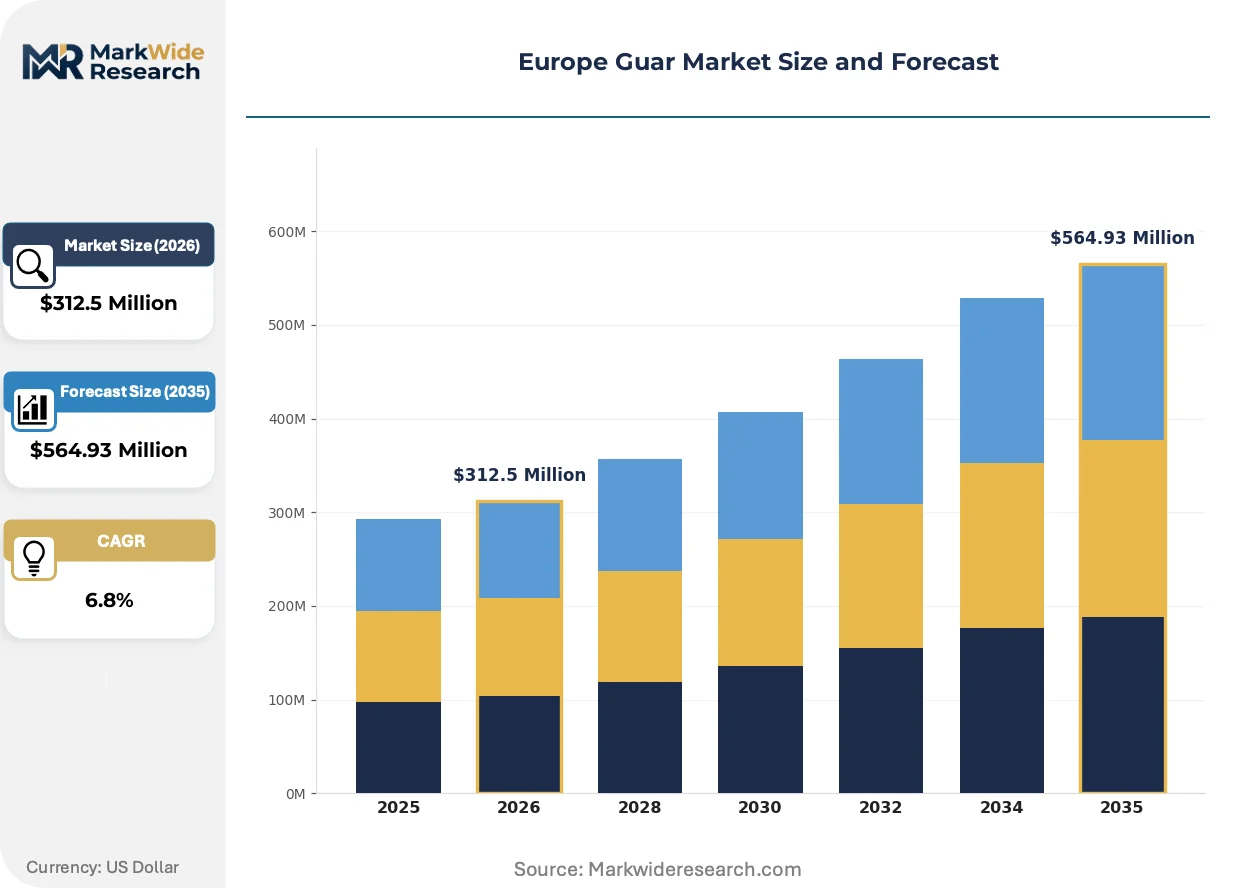
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guar Gum, Guar Meal, Guar Powder, Guar Splits Application: Food, Pharmaceuticals, Textiles, Oil & Gas End User: Food Manufacturers, Pharmaceutical Companies, Textile Industry, Energy Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DuPont de Nemours, Cargill Incorporated, Ingredion Incorporated, Nexira, ADM (Archer Daniels Midland), Ruchi Soya Industries, Unipektin Ingredients AG, Hindustan Gum & Chemicals, Jai Bharat Gum & Chemicals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Guar Market Shifts & Advancements
Digital traceability infrastructure and advanced extraction technologies are compressing the gap between raw seed procurement and certified derivative output. Regulatory alignment between EU-wide frameworks and member-state enforcement is accelerating standardization across food, pharmaceutical, and industrial grade tiers.
Enzymatic fractionation is virtualizing traditional mechanical guar split processing by replacing heat-intensive milling with targeted endosperm separation at ambient temperatures. Swiss refining specialists are adopting these biocatalytic systems to reduce solvent residues ahead of ECHA threshold tightening. The technology is compressing capital requirements for mid-scale pharmaceutical-grade capacity while enabling modular deployment closer to Iberian logistics hubs.
EU Green Deal deforestation due diligence regulations are mandating geospatial verification of guar cultivation plots down to individual farm coordinates. EFSA and national customs authorities are cross-referencing satellite imagery against import documentation, with non-compliant shipments facing detention at Rotterdam and Antwerp entry points. Food-grade importers are responding by embedding third-party audit layers into Indian and Pakistani supplier contracts.
Buyer concentration among Western European clean-label formulators is consolidating procurement leverage toward direct-offtake agreements with fractionators. Netherlands-based dairy stabilizer blenders are bypassing traditional distributor networks to secure volume commitments from Barcelona and Marseille logistics hubs. This disintermediation is most visible in bakery and beverage segments where EFSA organic certification commands sourcing exclusivity.
Europe Guar Market Segmentation
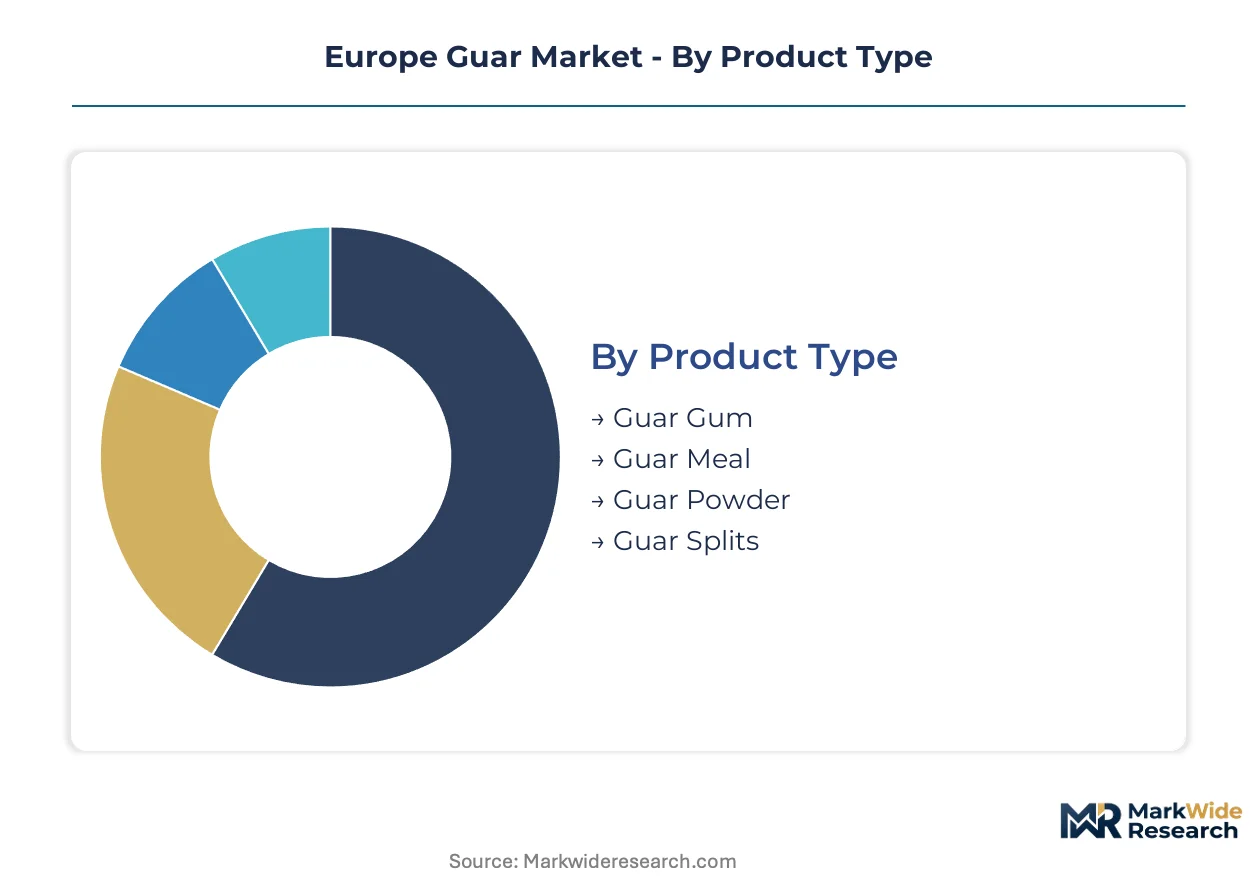
Guar derivatives exhibit divergent value capture profiles across purity grades and end-use certifications. Segmentation clarity enables processors to align fractionation investments with EFSA food-contact, EMA pharmaceutical, and REACH industrial compliance tiers.
Product Type:
Use-case spectrum spans food-grade stabilizers, pharmaceutical excipients, protein-rich feed additives, and industrial viscosity modifiers.
- Guar Gum:Refined galactomannan polysaccharide with viscosities exceeding 5,000 cP at one percent concentration. German and French dairy processors are expanding procurement for clean-label bakery and beverage stabilizer replacement under tightening EFSA purity mandates.
- Guar Powder:Micronized endosperm derivative commanding certification premiums for pharmaceutical oral solid dosage and controlled-release formulations. Swiss-refined splits dominate high-viscosity industrial applications through Unipektin Ingredients AG processing infrastructure.
- Guar Meal:Protein-rich byproduct displacing soybean alternatives in European livestock feed. CSRD supply chain disclosure rules favor non-GMO, deforestation-free sourcing verification for Indian and Pakistani origin material.
- Guar Splits:Intermediate fraction requiring further refining for food-contact or pharmaceutical-grade derivatives. Barcelona and Marseille logistics hubs concentrate Iberian and Southern European processing capacity.
Established volume favors guar gum; emerging adoption favors guar meal under protein displacement trends.
Application:
Cost tier stratification separates commodity industrial grades from premium pharmaceutical and organic-certified food segments.
- Food:Stabilizer, thickener, and moisture-retention agent across bakery, dairy, and beverage formulations. Netherlands-based dairy stabilizer blenders are bypassing distributor networks for direct offtake from fractionators.
- Pharmaceuticals:EMA-aligned GMP extraction capabilities command pricing multiples in oral solid dosage applications. ECHA solvent threshold tightening is forcing capital-intensive technology upgrades among European refiners.
- Textiles:Sizing and printing auxiliary with declining European manufacturing footprint. Regional demand concentrates in specialized technical textile operations.
- Oil & Gas:Hydraulic fracturing specialty grades retain margin concentration despite structurally mature European drilling activity. REACH registration streamlines market entry for compliant industrial suppliers.
Margin concentration sits with pharmaceuticals; volume scale remains with food applications.
End User:
Customer type fragmentation reflects divergent procurement sophistication across certification tiers.
- Food Manufacturers:Clean-label formulators in Germany and France drive EFSA organic certification sourcing exclusivity. Direct-offtake agreements are consolidating procurement leverage toward Barcelona and Dutch logistics hubs.
- Pharmaceutical Companies:Controlled-release formulation specialists require EMA-aligned GMP extraction with residual solvent documentation. Swiss and French technical institutes concentrate fractionation engineering expertise.
- Textile Industry:Technical sizing operations with declining European production base. Procurement volumes trail food and pharmaceutical segments.
- Energy Sector:Hydraulic fracturing operators facing drilling activity constraints across European shale basins. Specialty grade margins persist despite volume stagnation.
Procurement sophistication clusters with pharmaceutical companies; volume aggregation favors food manufacturers.
Distribution Channel:
Supply chain configuration shifts from traditional distributor networks toward direct fractionator relationships.
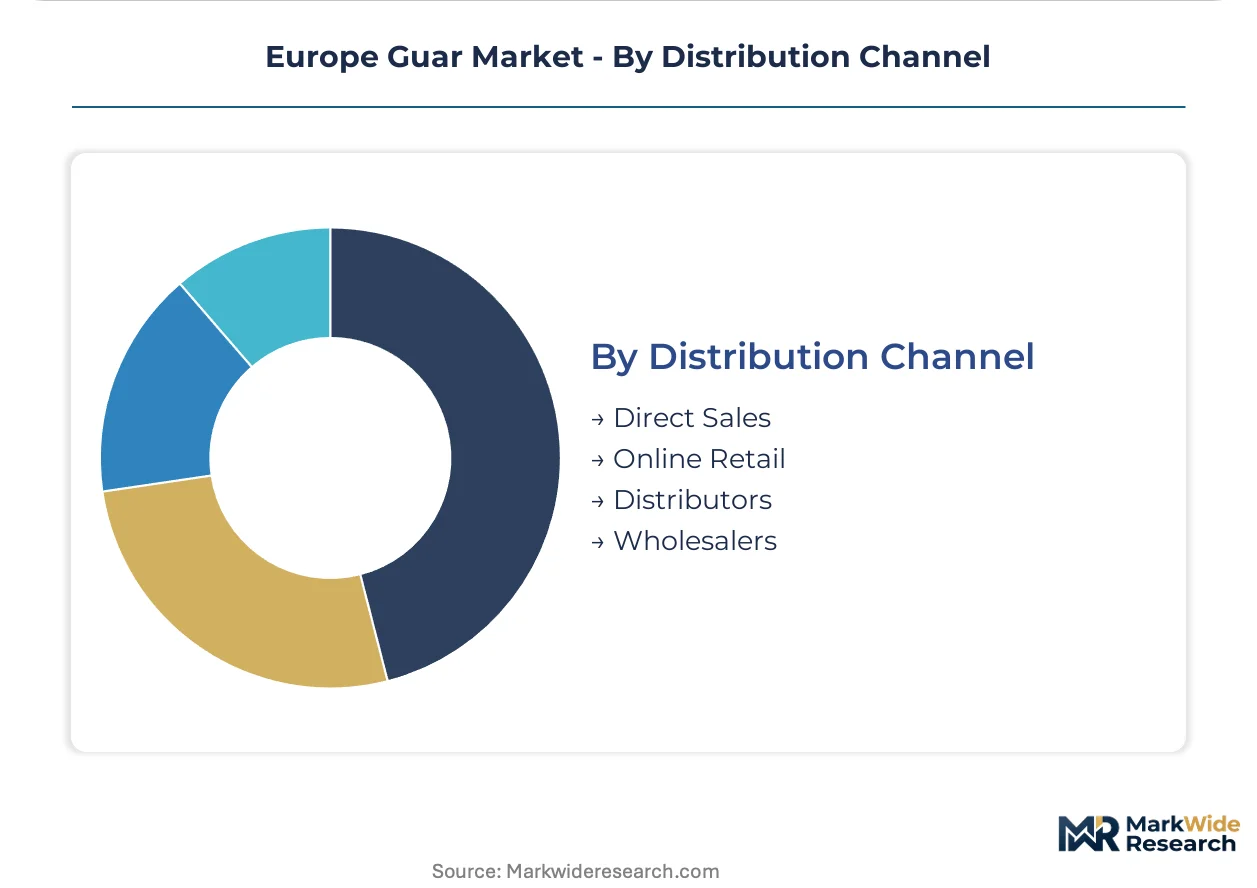
- Direct Sales:Volume commitments bypassing intermediaries for EFSA organic-certified and pharmaceutical-grade tiers. Netherlands dairy blenders and German bakery processors anchor this channel.
- Distributors:Traditional network for mid-scale food manufacturers and regional textile operations. Iberian fractionation expansion is reducing Southern European dependency on Swiss and Dutch refining hubs.
- Wholesalers:Commodity-grade industrial derivatives and feed applications. Guar meal protein displacement flows through agricultural supply wholesalers.
- Online Retail:Niche channel for small-scale food ingredient purchasers and research-grade quantities. Limited penetration in bulk industrial procurement.
Channel concentration favors direct sales for premium tiers; wholesalers retain commodity feed volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guar seed processing capacity concentrates in Swiss refining hubs and Iberian logistics centers, with Dutch and Belgian ports serving as the primary entry points for Indian and Pakistani raw material flows into European customs territory.
Germany
Bakery and dairy processors in Bavaria and North Rhine-Westphalia are expanding guar gum procurement for clean-label stabilizer replacement under tightening EFSA purity mandates. The country's national food safety authority enforces strict documentation requirements for imported galactomannan derivatives. Hamburg anchors Northern European distribution, with direct-offtake agreements consolidating procurement leverage toward fractionators.
France
Pharmaceutical excipient demand from Île-de-Paris and Auvergne-Rhône-Alpes drives premium-grade guar powder consumption for oral solid dosage formulations. ANSM pharmaceutical manufacturing standards align with EMA GMP extraction protocols for residual solvent documentation. Marseille logistics hubs concentrate Southern European refining capacity, with Nexira anchoring pharmaceutical-grade supply through French extraction facilities.
Netherlands
Dairy stabilizer blenders in Rotterdam and Amsterdam are bypassing traditional distributor networks to secure volume commitments from Barcelona and Marseille fractionators. The country's national customs authority cross-references satellite imagery against import documentation under EU Green Deal deforestation due diligence rules. Randstad processing infrastructure dominates food-grade derivative distribution across Northwestern Europe.
Spain
Emerging fractionation capacity in Catalonia and Madrid is reducing Southern European dependency on Swiss and Dutch refining hubs for food-grade derivatives. The country's national agricultural regulator enforces geospatial verification requirements for Indian and Pakistani origin material. Barcelona logistics hubs streamline Iberian distribution through Cargill Incorporated's regional infrastructure.
Switzerland
High-viscosity industrial applications and pharmaceutical-grade extraction capabilities concentrate around Swiss technical institutes in Zurich and Basel. Swissmedic pharmaceutical manufacturing standards command pricing multiples for EMA-aligned GMP certification. Unipektin Ingredients AG dominates Swiss-refined guar splits for specialized industrial and pharmaceutical segments.
Europe Guar Market Competitive Landscape
Integrated agribusiness conglomerates and specialized fractionation engineers split the market between scale-driven commodity flows and certification-premium specialty tiers. The vendor base organizes around three strategic archetypes: multinational ingredient platforms with backward integration into seed sourcing, regional refining specialists with pharmaceutical-grade extraction capabilities, and Indian-origin processors with direct farm-gate procurement relationships. Capacity expansion and supply chain digitization represent the dominant competitive moves as EU Green Deal traceability requirements reshape procurement verification.
Among multinational ingredient platforms, Cargill Incorporated and ADM exemplify scale-driven commodity distribution with logistics hub concentration in Barcelona and Rotterdam. Nexira occupies a position within the pharmaceutical-grade specialty tier, anchoring premium excipient supply through French extraction infrastructure. Unipektin Ingredients AG represents the Swiss-refined industrial specialist archetype, with technical expertise concentrated among Alpine fractionation engineers.
| Leading Market Players |
|---|
| DuPont de Nemours |
| Cargill Incorporated |
| Ingredion Incorporated |
| Nexira |
| ADM (Archer Daniels Midland) |
| Ruchi Soya Industries |
| Unipektin Ingredients AG |
| Hindustan Gum & Chemicals |
| Jai Bharat Gum & Chemicals |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors govern cost dynamics for Indian and Pakistani guar seed entering European customs territory, compressing margins for distributors while amplifying price differentiation between pharmaceutical-grade refiners and commodity feed suppliers. EFSA certification premiums and REACH compliance burdens cascade downstream, concentrating pricing power among Swiss and Dutch fractionators with established regulatory dossiers.
Pricing Analysis
EFSA purity standards dictate the pricing tier structure across food-contact, pharmaceutical, and industrial grade derivatives. Three-tier pricing separates EMA-aligned GMP extraction capabilities from standard food-grade stabilizers and commodity feed applications. Price differentiation hinges on residual solvent documentation and organic certification status, with pharmaceutical-grade splits commanding multiples over industrial viscosity modifiers. Pricing pressure stems from ECHA threshold tightening for solvent residues, forcing capital-intensive technology upgrades that squeeze mid-scale refiners. Food manufacturers exhibit highest price sensitivity due to clean-label procurement mandates, while pharmaceutical formulators absorb premium tiers for controlled-release excipient security.
Supply Chain Analysis
Extended payment terms from Rotterdam-based dairy stabilizer blenders are restructuring working capital requirements for Iberian and Swiss fractionators. Geographic supply concentration rests on Rajasthan and Gujarat seed cultivation, with secondary dependency on Pakistani Sindh harvests. Raw material inputs encompass galactomannan-rich endosperm, protein-dense germ fractions, and hull byproducts for feed applications. Single-source vulnerability pervades the monsoon-dependent cultivation belt, exposing European processors to climate-induced freight cost spikes. Distribution runs through Barcelona and Marseille logistics hubs for Southern European coverage, with Swiss refining infrastructure serving high-viscosity industrial and pharmaceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EFSA food-contact approvals and EMA GMP certification constructs formidable defensive moats for established European fractionators. Switching costs for pharmaceutical formulators and clean-label food manufacturers lock in incumbent relationships across multi-year procurement cycles.
For Market Incumbents: Entrench regulatory dossier advantages by accelerating enzymatic fractionation adoption ahead of ECHA solvent threshold compression. Expand Barcelona and Marseille logistics capacity to capture Southern European direct-offtake demand bypassing distributor networks. Deepen backward integration into Indian and Pakistani farm-gate procurement through blockchain-enabled geospatial verification contracts satisfying EU Green Deal due diligence mandates.
For New Entrants and Emerging Players: Iberian underpenetration in pharmaceutical-grade extraction presents viable white-space entry, with Madrid and Catalonia processing infrastructure still scaling toward EMA-aligned GMP capabilities. Target guar meal protein displacement in European livestock feed as the most penetrable segment, leveraging CSRD supply chain disclosure rules favoring deforestation-free sourcing verification. Pursue agricultural supply wholesaler partnerships for commodity-grade volume buildout before certifying upward into food-contact tiers.
For Investors and Strategic Acquirers: EU Green Deal deforestation due diligence implementation reshapes the acquisition landscape toward traceability-embedded targets with established Indian and Pakistani supplier audit layers. Long-term viability centers on fractionators with dual competency in seed processing and pharmaceutical extraction, capable of spanning commodity feed through premium excipient tiers. Monitor EFSA-ANSM regulatory divergence enforcement patterns as the signal indicating consolidation timing for Swiss and French refining specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Fractionation Adoption | Swiss refiners reduce solvent residues ahead of ECHA threshold tightening while compressing capital requirements. |
| Blockchain Provenance Tracking | Geospatial verification satisfies EU Green Deal mandates and unlocks preferential procurement with sustainability-mandated buyers. |
| Iberian Logistics Hub Expansion | Barcelona and Marseille capacity reduces Southern European dependency on Dutch and Swiss refining infrastructure. |
| Pharmaceutical-Grade Certification Investment | EMA-aligned GMP extraction capabilities command pricing multiples in oral solid dosage formulation segments. |
| Direct-Offtake Agreement Structuring | Netherlands dairy blenders and German bakery processors consolidate procurement leverage toward fractionator relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA guidance documents, ECHA substance evaluation protocols, and EU Green Deal regulatory filings. Primary interviews engaged fractionation engineers at Swiss technical institutes, procurement leads at Netherlands-based dairy stabilizer blenders, regulatory affairs directors at French extraction facilities, and customs compliance officers at Rotterdam and Antwerp entry points. Secondary validation drew from REACH registration databases, ANSM pharmaceutical manufacturing standards, and trade flow records through Eurostat and national customs authorities. Bottom-up volume modeling across grade tiers triangulated against top-down market sizing from import documentation and processing capacity assessments.
Forecast inputs span food-grade stabilizer replacement rates in German and French clean-label formulations, pharmaceutical excipient demand from Île-de-France and Auvergne-Rhône-Alpes manufacturing clusters, and protein displacement velocity in European livestock feed under CSRD disclosure rules. Segmentation dimensions encompass product purity grade, end-use application, customer certification requirements, and regional processing hub concentration. CAGRs derive from regression analysis of historical import volumes against regulatory milestone implementation timelines, with scenario weighting for monsoon variability in Rajasthan and Gujarat cultivation belts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Indian-origin processors with direct farm-gate procurement relationships would shift outcomes through supply concentration disruption. Macroeconomic volatility in agricultural commodity markets, regulatory divergence between EFSA and member-state enforcement practices, or technological breakthroughs in locust bean gum substitution chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
Cage Free Eggs Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
France Alfalfa Hay Market