
 Sorbitan Laurate Market | 2026-2036
Sorbitan Laurate Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbitan Laurate Market Analytics
Modular formulation kits for personal care brands is expanding as compounders seek flexible emulsifier systems that reduce R&D cycle times. Oxiteno leverages its Latin American oleochemical base to supply sorbitan ester precursors at scale. Croda sustains premium positioning through high-purity grades targeting pharmaceutical-grade applications. Solvay SA anchors European supply with integrated fatty acid chemistry operations in Belgium and France.
Sorbitan laurate is a nonionic surfactant synthesized via esterification of sorbitol with lauric acid, yielding a lipophilic emulsifier with an HLB value near 8 that stabilizes oil-in-water dispersions across pH ranges. The emulsifier segment dominates value contribution due to its ubiquity in cosmetic creams and lotions, while the surfactant category leads volume growth as agrochemical formulators replace ethoxylated alternatives. Personal care applications command the widest margin pool, though food-grade stabilizer demand is accelerating as clean-label processors reformulate under stricter additive scrutiny.
REACH registrations and ECHA substance evaluations shape European market access by mandating full toxicological dossiers for sorbitan ester imports. FDA food-contact notifications and EPA pesticide inert ingredient listings determine US qualification pathways for agricultural and food applications. India's BIS certification requirements and CDSCO excipient monographs are tightening as domestic pharmaceutical output expands. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply disqualification.
Market Dynamics
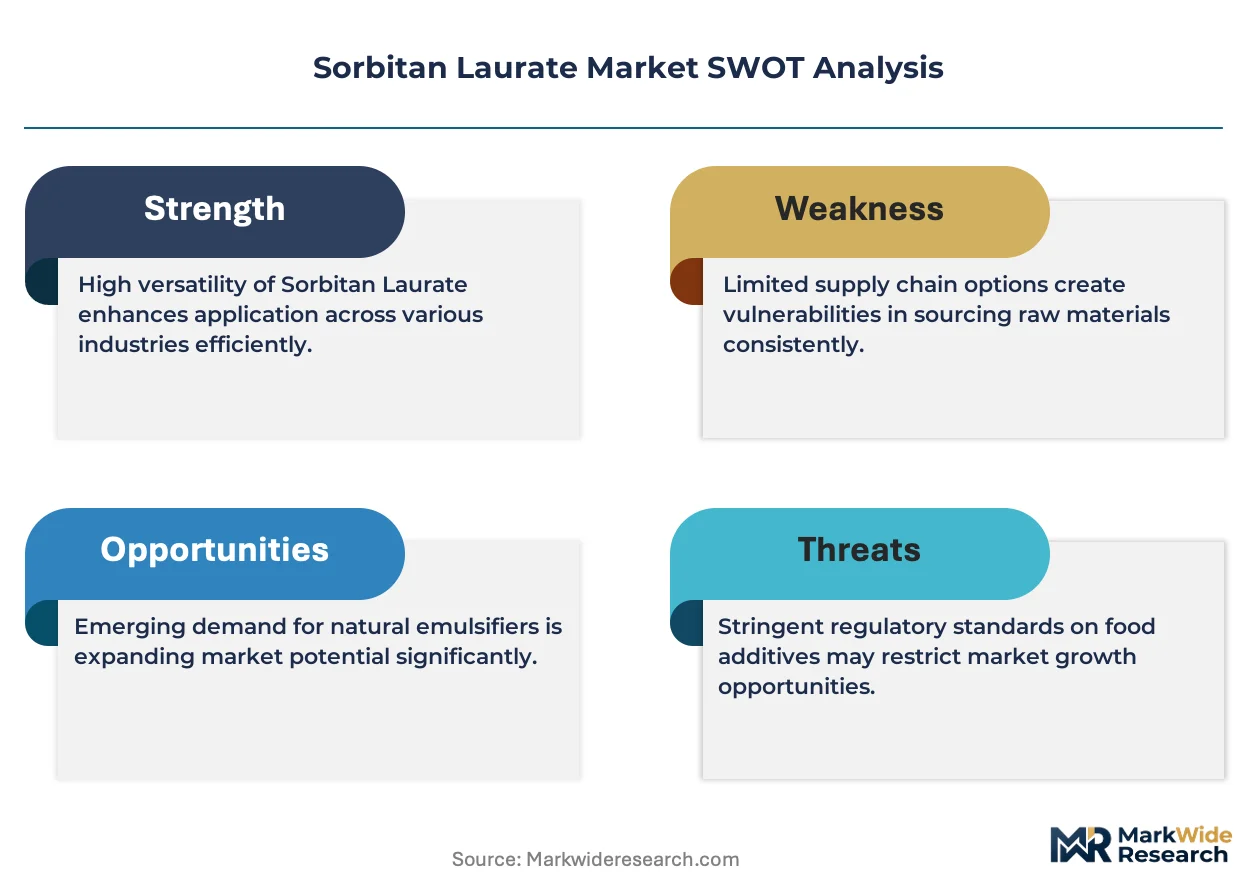
Formulation houses are consolidating their supplier bases around REACH-registered sorbitan ester producers to preempt disqualification under tightening European purity dossier requirements. This supplier rationalization is compressing margins for non-integrated compounders while favoring oleochemical operators with captive fatty acid supply.
Growth Catalysts
- Clean-label food reformulation:Processors under FDA additive scrutiny are replacing synthetic stabilizers with sorbitan laurate in bakery and confectionery applications.
- India's pharmaceutical excipient scale-up:CDSCO oversight is driving domestic production of compendial-grade emulsifiers for oral and topical drug delivery systems.
- Agrochemical formulation shift:Formulators are substituting ethoxylated surfactants with sorbitan esters to meet EPA pesticide inert ingredient listing requirements.
Market Restraints
- Lauric acid price volatility:Palm kernel and coconut oil feedstock fluctuations transmit directly to sorbitan ester production economics.
- European import dossier burden:ECHA substance evaluations impose toxicological data costs that exclude smaller Asian exporters from REACH-registered supply.
- Biobased glycolipid substitution:Rhamnolipid and sophorolipid biosurfactants are capturing niche personal care segments with superior biodegradability profiles.
Strategic Opportunities
- Indian domestic API manufacturing:PLI scheme incentives for active pharmaceutical ingredient production are expanding excipient demand in Maharashtra and Telangana.
- Veterinary pharmaceutical emulsions:Underdeveloped animal health formulations present white space for lipophilic emulsifier penetration in parenteral and pour-on products.
- Modular formulation kit channels:Direct supply to mid-tier personal care brands bypassing traditional distributor markups is emerging as a margin capture mechanism.
Industry Challenges
- Compendial certification timelines:USP-NF and Ph.Eur. monograph compliance for pharmaceutical-grade sorbitan laurate requires 18-24 month validation cycles.
- Multi-jurisdiction regulatory divergence:Formulators must maintain separate specification sheets for FDA food-contact, EPA inert, and REACH-registered chemical grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbitan Laurate Market |
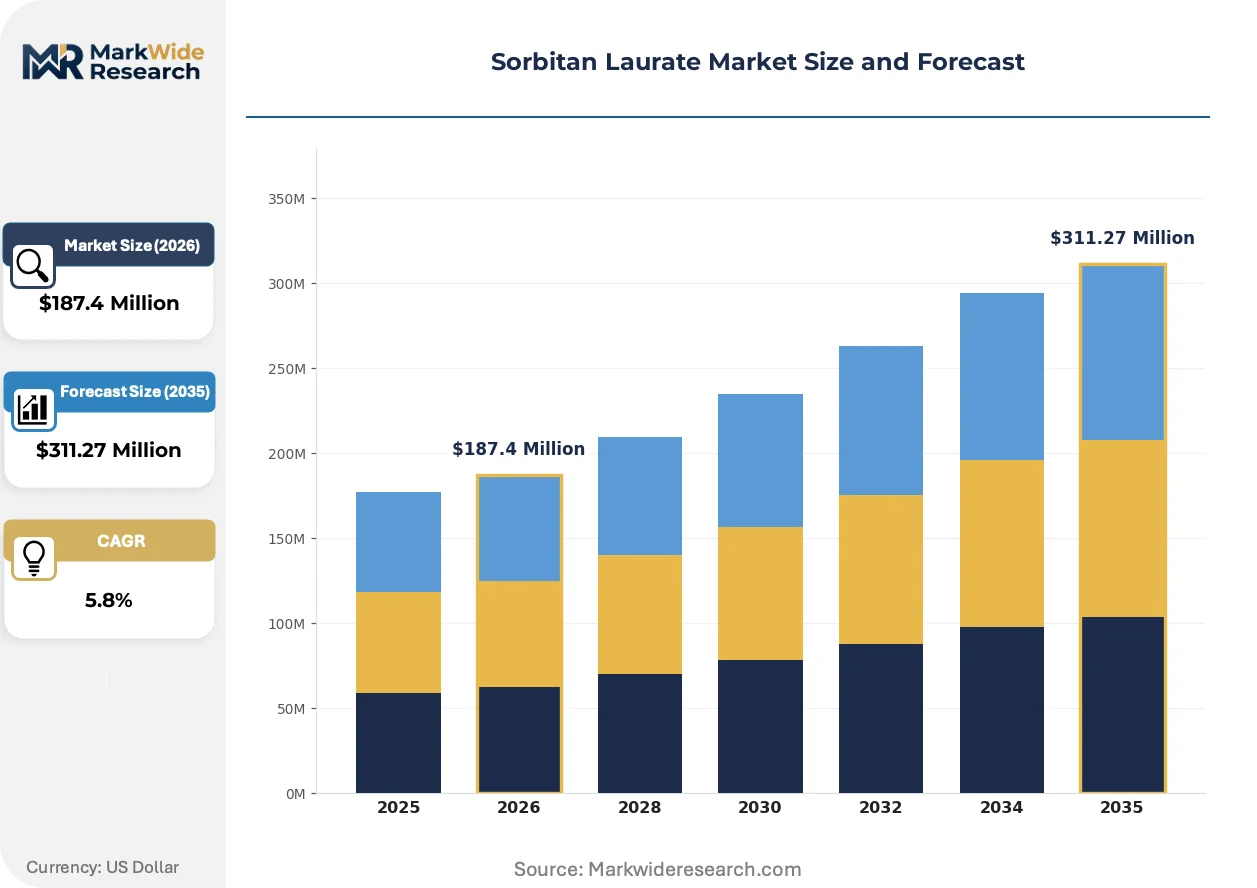
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifier, Surfactant, Stabilizer, Thickener Application: Personal Care, Food & Beverage, Pharmaceuticals, Agriculture End User: Cosmetics Manufacturers, Food Processors, Pharmaceutical Companies, Agrochemical Producers Form: Liquid, Powder, Granule, Paste |
| Companies Covered | Oxiteno, Quality Group, Lakeland Chemicals, Solvay SA, Estelle Chemicals Pvt. Ltd., Croda, Ethox Chemical, Kao Chemicals, Vantage Specialty Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbitan Laurate Market Evolving Landscape
Bio-based process innovation and regulatory compliance automation are restructuring how sorbitan ester producers compete. Technology differentiation now centers on enzymatic esterification methods and blockchain-enabled supply chain verification.
Enzymatic esterification using immobilized lipase catalysts is overtaking conventional acid-catalyzed processes in high-purity pharmaceutical-grade production. European and Indian manufacturers adopting this route achieve selective monoester formation with reduced color bodies and lower thermal degradation. The technology is compressing capital requirements for compendial certification while enabling batch-to-batch consistency that acid catalysis cannot match.
REACH Article 33 supply chain communication obligations are forcing downstream formulators to document full substance composition in cosmetic and food-contact applications. ECHA SCIP database requirements for waste framework compliance have extended disclosure burdens to finished product manufacturers. Personal care brands with European distribution are responding by mandating certificate-of-analysis automation from their sorbitan ester suppliers.
Direct procurement from oleochemical producers is displacing traditional chemical distributor intermediation among mid-scale personal care compounders. Buyers in India's Gujarat and Maharashtra clusters are establishing annual framework contracts with integrated manufacturers to secure price stability and优先 allocation. This channel shift is most visible in the 50-200 MT annual volume segment, where formulation houses previously relied on Mumbai-based trading houses for spot supply.
Sorbitan Laurate Market Segmentation
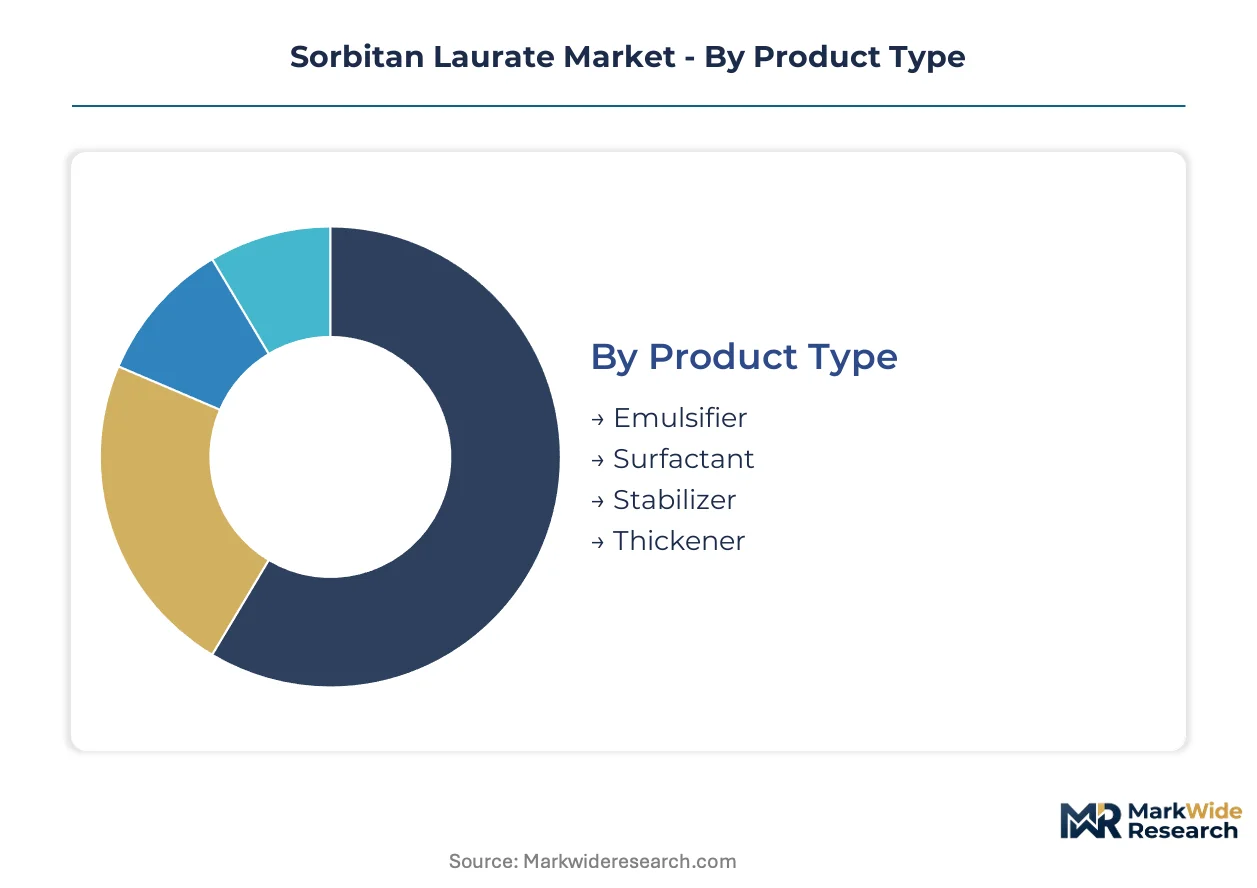
Sorbitan laurate procurement decisions hinge on functional performance specifications and regulatory certification tiers rather than commodity pricing alone. Formulators evaluate HLB values, compendial grades, and REACH dossier completeness when selecting across product type and application categories.
Product Type:
Buyers prioritize HLB matching and emulsion stability requirements when selecting functional categories for specific formulation challenges.
- Emulsifier:Lipophilic monoester with HLB near 8 stabilizes oil-in-water dispersions across broad pH ranges. Personal care formulators in Maharashtra and Gujarat specify this grade for premium skincare creams requiring batch-to-batch consistency under CDSCO excipient guidelines.
- Surfactant:Nonionic surface-active agent reduces interfacial tension in agrochemical and industrial cleaning formulations. Agrochemical producers in India's pesticide belt substitute ethoxylated alternatives to meet EPA inert ingredient listing requirements while maintaining spray droplet adhesion.
- Stabilizer:Viscosity-modifying additive prevents phase separation in food and pharmaceutical suspensions. Clean-label bakery processors reformulate under FDA additive scrutiny.
- Thickener:Rheology modifier builds viscosity in topical and oral dosage forms. Veterinary pharmaceutical emulsions represent emerging demand concentration.
Emulsifier leads on scale; surfactant leads on momentum.
Application:
End-use profitability varies sharply across regulatory burden and specification stringency tiers.
- Personal Care:Premium-margin segment commanding widest profitability pool across skincare, haircare, and color cosmetics. Formulators specify REACH-registered grades with full toxicological dossiers for European distribution.
- Food & Beverage:Clean-label stabilizer demand accelerates as processors replace synthetic additives under evolving FDA standards. Bakery and confectionery applications concentrate in domestic Indian market.
- Pharmaceuticals:Compendial-grade requirements impose 18-24 month USP-NF and Ph.Eur. validation cycles. CDSCO oversight drives domestic excipient scale-up in Telangana and Maharashtra clusters.
- Agriculture:Pesticide inert ingredient applications expand as formulators exit ethoxylated surfactants. EPA listing compliance determines supplier qualification.
Personal care dominates margin capture; food and beverage climbs fastest.
End User:
Procurement sophistication stratifies by technical capability and regulatory exposure.
- Cosmetics Manufacturers:Most demanding specification requirements with mandatory certificate-of-analysis automation and blockchain-enabled supply chain verification for REACH Article 33 compliance.
- Food Processors:Volume buyers prioritizing price stability through annual framework contracts with integrated oleochemical producers.
- Pharmaceutical Companies:Compendial certification timelines and multi-jurisdiction dossier maintenance create high switching costs.
- Agrochemical Producers:EPA inert ingredient listing and state-level registration requirements shape supplier selection.
Cosmetics manufacturers set specification benchmarks; food processors drive volume consolidation.
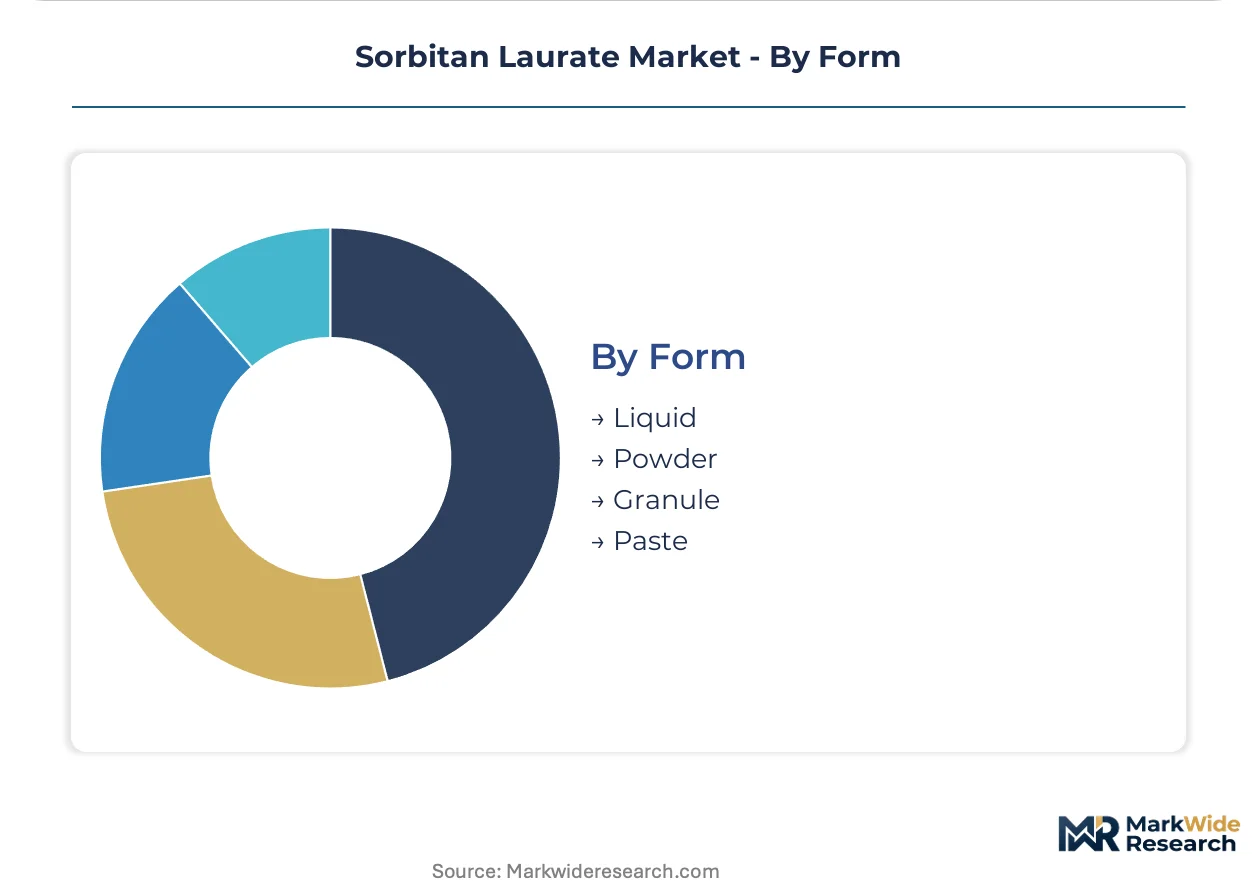
Form:
Physical state selection reflects handling economics and dissolution kinetics for target formulations.
- Liquid:Ready-to-disperse format preferred by high-throughput personal care compounders seeking reduced processing time. Direct pump transfer eliminates dust exposure.
- Powder:Extended shelf stability and reduced transportation costs favor this format for food and agrochemical applications. Mumbai-based trading houses historically spot-supplied this grade.
- Granule:Controlled particle size distribution enables precise dosing in pharmaceutical tableting operations. Reduced caking versus powder grades.
- Paste:Pre-hydrated format suits small-batch cosmetic formulators with limited heating capacity. Niche positioning in modular formulation kit channels.
Liquid commands operational preference; powder retains cost advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sorbitan laurate production originated in European oleochemical hubs during the mid-20th century, with Belgian and French integrated fatty acid operations establishing the foundational supply architecture. Manufacturing subsequently dispersed to Asia-Pacific and Latin America as palm kernel and coconut oil feedstock access reshaped cost economics.
Germany
Specialty chemical demand from pharmaceutical formulators in Ludwigshafen and Leverkusen clusters sustains premium-grade consumption. ECHA REACH enforcement mandates complete toxicological dossiers for all sorbitan ester imports, disqualifying non-registered Asian suppliers. The Rhineland-Palatinate chemical corridor hosts compendial-grade validation facilities serving European pharmaceutical manufacturers.
United States
Clean-label food processors in Chicago and Minneapolis metropolitan areas accelerate sorbitan laurate substitution for synthetic stabilizers. FDA food-contact notification requirements and EPA pesticide inert ingredient listings create dual regulatory qualification pathways. New Jersey and Pennsylvania chemical distribution hubs manage specification differentiation between food-grade and pharmaceutical-grade material flows.
India
Domestic pharmaceutical excipient manufacturing scales rapidly under CDSCO oversight in Telangana and Maharashtra clusters. PLI scheme incentives for active pharmaceutical ingredient production expand captive emulsifier demand. Gujarat-based oleochemical producers establish backward integration into palm kernel fatty acid supply to reduce import dependency.
Brazil
Oleochemical feedstock abundance from domestic palm and coconut oil processing anchors Latin American supply. ANVISA pharmaceutical excipient regulations tighten import specifications for oral and topical drug formulations. São Paulo state cosmetic formulators specify REACH-registered grades for export-oriented personal care production.
China
Surfactant manufacturing concentration in Jiangsu and Zhejiang provinces supplies agrochemical formulators replacing ethoxylated alternatives. NMPA pharmaceutical-grade registration timelines extend 24-36 months for imported excipients, favoring domestic producers. Yangtze River Delta chemical parks integrate enzymatic esterification capacity for high-purity monoester output.
Sorbitan Laurate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade and REACH-registered producers capturing profitability pools unavailable to standard-grade compounders. The competitive map separates into three archetypes: integrated oleochemical operators with captive fatty acid supply, specialty chemical houses with compendial certification capabilities, and regional compounders serving spot-market demand. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with producers securing long-term feedstock agreements and downstream formulation house relationships.
Within the integrated oleochemical tier, Oxiteno and Solvay SA exemplify geographic anchoring strategies—Oxiteno leveraging Latin American feedstock proximity and Solvay SA maintaining European chemical corridor positioning. Croda occupies a position in the specialty-grade segment where pharmaceutical and personal care certification requirements create defensive moats. These three entities represent the structural segmentation between feedstock-integrated, certification-premium, and scale-commodity positioning that defines competitive interaction in sorbitan ester supply.
| Leading Market Players |
|---|
| Oxiteno |
| Quality Group |
| Lakeland Chemicals |
| Solvay SA |
| Estelle Chemicals Pvt. Ltd. |
| Croda |
| Ethox Chemical |
| Kao Chemicals |
| Vantage Specialty Ingredients |
| Others |
Value Network & Pricing Analysis
REACH-registered grade procurement mandates from European cosmetics formulators are compressing supplier pools and forcing non-integrated compounders toward either certification investment or exit. This buyer-driven consolidation elevates pricing power for oleochemical operators with captive fatty acid supply while squeezing margins on standard-grade spot material.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certified material from food-grade and industrial-grade supply. Price differentiation rests on compendial certification status and REACH dossier completeness, with pharmaceutical buyers showing lowest sensitivity. Cost compression in standard-grade segments is intensifying because Asian exporters face ECHA toxicological data burdens that exclude them from premium-tier qualification.
Supply Chain Analysis
Specialized chemical engineering talent shortages in Jiangsu and Gujarat chemical parks are constraining enzymatic esterification capacity expansion timelines. Manufacturing concentrates in China, India, and Belgium, with feedstock supply drawing from Malaysian and Indonesian palm kernel oil estates. Single-source vulnerability runs through the Strait of Malacca shipping corridor. Distribution runs through integrated oleochemical producers selling direct to formulation houses, displacing Mumbai-based trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in compendial-grade certification and enzymatic process technology, with enzymatic esterification capex running 40% below acid-catalysis for equivalent purity output.
For Market Incumbents: Deploy enzymatic esterification capacity additions in Telangana and Maharashtra to capture CDSCO-driven pharmaceutical excipient demand. Secure long-term palm kernel fatty acid offtake agreements with Malaysian suppliers to neutralize lauric acid price volatility. Rhamnolipid biosurfactant substitution in personal care segments demands defensive REACH-registered grade positioning. For New Entrants and Emerging Players: Modular formulation kit distributors represent the most accessible channel for bypassing established Mumbai trading house relationships. Veterinary pharmaceutical emulsions in parenteral and pour-on applications offer underpenetrated white space with limited incumbent certification presence. Direct annual framework contracts with mid-tier personal care brands in Gujarat bypass traditional distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated oleochemical operators possessing captive fatty acid supply and existing REACH registrations. Long-term viability favors producers with backward integration into palm kernel processing and enzymatic technology adoption. Watch for CDSCO pharmaceutical excipient import substitution inflection as domestic Indian production scales.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Esterification Capacity Expansion | Reduces pharmaceutical-grade validation cycles from 24 months toward 18 months while improving batch consistency. |
| Backward Integration into Palm Kernel Processing | Secures lauric acid supply against Malaysian and Indonesian feedstock price volatility. |
| REACH Dossier Completion for Asian Exporters | Unlocks European cosmetics formulator procurement pools currently closed to non-registered supply. |
| Modular Formulation Kit Channel Development | Captures margin pool from Mumbai-based trading house displacement in 50-200 MT volume segments. |
| CDSCO Compendial Certification Investment | Positions for PLI scheme-driven API manufacturing expansion in Telangana and Maharashtra clusters. |
Research Methodology
Coverage spans European chemical corridors, Indian pharmaceutical clusters, and Latin American oleochemical hubs, with primary inputs from each. Plant managers at integrated fatty acid operations, procurement leads at personal care formulators, distribution channel partners, and technical R&D directors at enzymatic catalyst suppliers provided operational data. Secondary validation drew from ECHA REACH registrations, CDSCO excipient monographs, SEC 10-K filings, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Granularity extended to grade tier, end-use industry, packaging format, and regional production hub for each forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro oleochemical demand drivers. Enzymatic technology adoption curves and REACH registration completion timelines served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when ECHA substance evaluation timelines extend, Malaysian palm kernel oil export policies shift, or CDSCO domestic excipient mandates accelerate. Forecasts reflect assumptions about regulatory stability and feedstock supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Calcium Formate Market
Additives
Performance Minerals Additives Market
Additives
Additives for Floor Coatings Market
Additives
Anti-Wear Additives Market
Additives
North America Pectin Market
Additives
Potting Mix Additives Market
Additives
Carboxymethyl Cellulose Market
Additives
Global Propyl Acetate Market
Additives
Global Scale Inhibitors Market
Additives
Micronized Powder Market
Additives
Anti-Slip Additives Market
Additives
Phthalate Plasticizer Market
Additives
Choline Chloride Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Global Glass Additives Market
Additives
Global Coalescing Agent Market