
 Global Caprylhydroxamic Acid Market | 2026-2036
Global Caprylhydroxamic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Caprylhydroxamic Acid Market Analysis
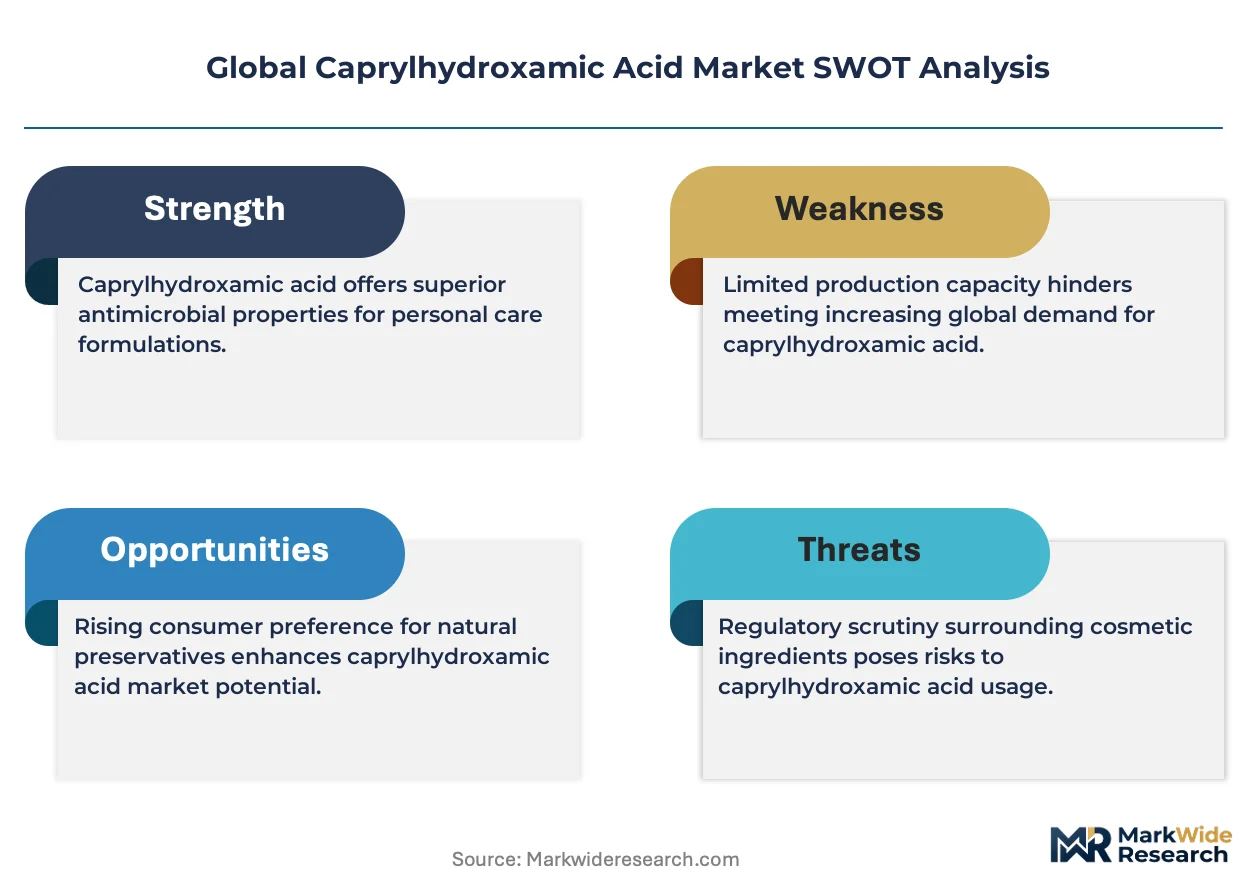
A shortage of organic synthesis chemists with hydroxamic acid expertise is unwinding capacity expansion timelines across specialty chemical suppliers. INOLEX leverages its Philadelphia-based technical team to sustain leadership in amino acid-derived chelating agents. Croda International Plc anchors European supply through its UK manufacturing footprint, while BASF SE competes on global distribution scale.
Caprylhydroxamic acid is an eight-carbon hydroxamic acid compound synthesized via amidation of caprylic acid derivatives, functioning primarily as a metal-chelating agent and preservative booster in pH-neutral formulations. The cosmetics application segment leads value generation due to clean-label positioning and paraben replacement demand. Liquid form dominates volume as manufacturers favor pump-dispense integration, while powder grades occupy niche positions in solid detergent tablets where stability requirements are stringent.
FDA oversight of cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act intersects with REACH substance evaluation in Europe and China's GB standards for cosmetic raw materials, collectively elevating documentation burdens for market entry. The EU Green Deal chemical sustainability targets are forcing reformulation timelines that favor hydroxamic acid alternatives over traditional chelators. Stakeholders must monitor regulatory divergence between FDA notification requirements and EU hazard classification updates to anticipate compliance-driven demand shifts.
Market Dynamics
Caprylhydroxamic acid supply chains are tightening around organic synthesis expertise shortages, forcing formulators to lock multi-year contracts with Philadelphia and UK-based manufacturers while EU Green Deal timelines accelerate chelator replacement cycles.
Growth Catalysts
- REACH substance evaluation:European formulators are substituting traditional chelators with hydroxamic acid derivatives to meet hazard classification deadlines.
- South Korean cosmetics manufacturing:K-beauty exporters are scaling amino acid-derived preservative booster procurement to satisfy US FDA notification requirements under MoCRA.
- Paraben replacement chemistry:Clean-label positioning in pH-neutral personal care formulations is pulling eight-carbon hydroxamic acid volumes.
Market Restraints
- Caprylic acid feedstock volatility:Palm kernel and coconut oil derivative prices fluctuate with Southeast Asian agricultural yields.
- Specialty chemist scarcity:Hydroxamic acid synthesis expertise concentrates in Philadelphia and UK technical clusters, limiting capacity expansion velocity.
- EDTA substitution economics:Lower-cost traditional chelators retain share in industrial cleaning applications where clean-label positioning carries no premium.
Strategic Opportunities
- China GB standard alignment:Domestic cosmetic raw material safety documentation is converging with international norms, opening import pathways for REACH-compliant suppliers.
- Solid detergent tablet formats:Powder-grade stability requirements in concentrated laundry applications represent underpenetrated demand.
- Biotechnology-derived caprylic acid:Fermentation-based feedstock production is reducing agricultural dependency for sustainability-positioned brands.
Industry Challenges
- Organic synthesis talent pipeline:Universities are graduating fewer amidation specialists than specialty chemical employers require.
- Dual regulatory documentation:Simultaneous FDA notification and REACH dossier preparation stretches technical affairs teams at mid-size suppliers.
- Pump-dispense formulation integration:Liquid-grade viscosity specifications demand equipment retrofits at contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Caprylhydroxamic Acid Market |
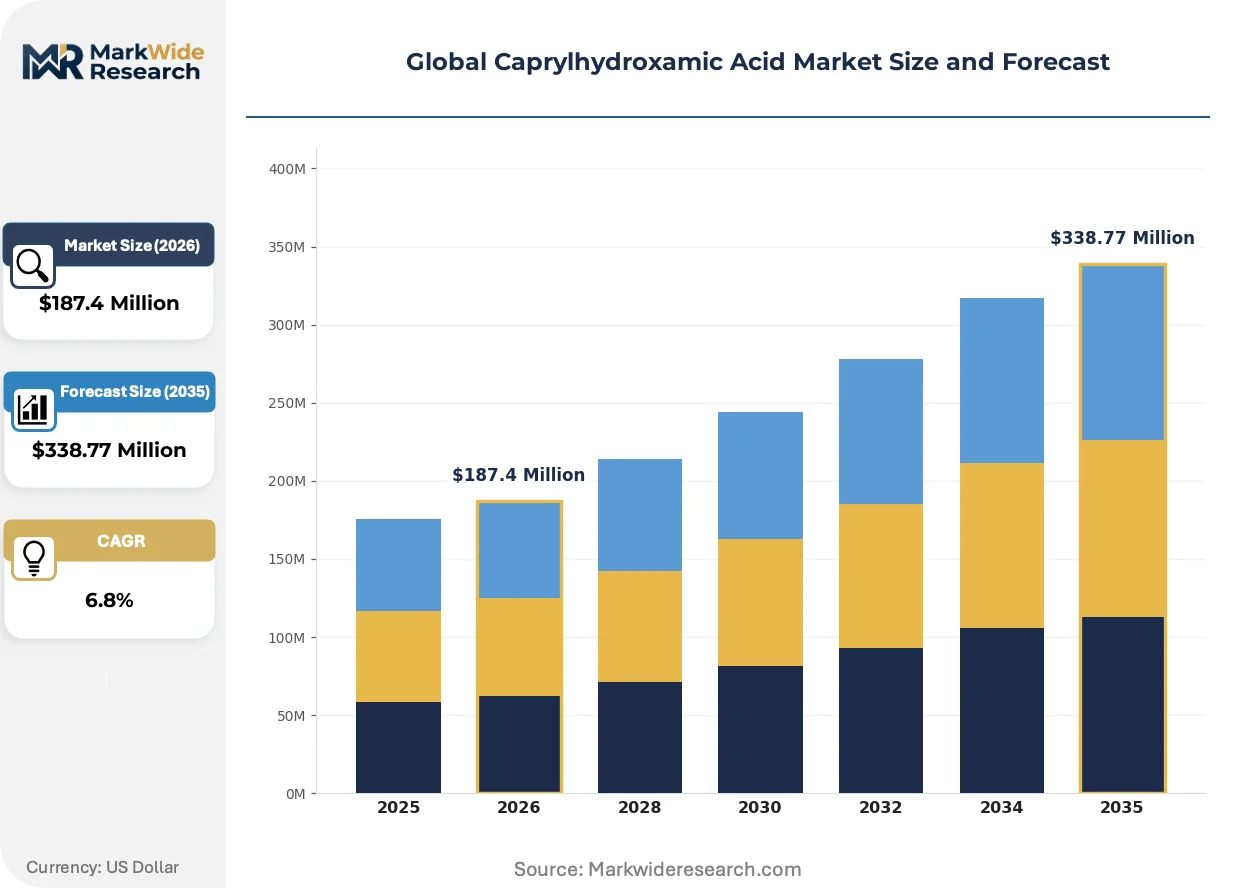
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Household Products, Industrial Applications End User: Consumers, Manufacturers, Retailers, Distributors Form: Liquid, Powder, Cream, Gel Application: Personal Care, Cleaning Agents, Food Preservation, Agriculture |
| Companies Covered | INOLEX, BASF SE, Ashland Global Holdings Inc., Clariant AG, Croda International Plc, Evonik Industries AG, TCI Chemical, Hangzhou Lingeba Technology, Ark Pharm Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Caprylhydroxamic Acid Market Emerging Trajectories
Amino acid-derived chelating agents are displacing petrochemical alternatives as formulators redesign preservative systems around biobased feedstocks and metal-sequestration performance.
Enzymatic amidation processes are displacing traditional chemical synthesis routes in caprylhydroxamic acid production. German and Dutch contract manufacturers are piloting lipase-catalyzed conversion to reduce solvent waste. This biotechnology shift is compressing capital requirements for new entrants while raising purity specifications that incumbent chemical routes struggle to match economically.
The EU Green Deal chemical sustainability targets are forcing reformulation timelines across European personal care brands. ECHA substance evaluation deadlines are accelerating hazard classification reviews for traditional chelators. Cosmetic formulators in Germany and France are responding by qualifying hydroxamic acid alternatives ahead of 2027 regulatory milestones.
Direct procurement relationships between personal care brands and specialty chemical suppliers are consolidating distributor intermediaries. Large K-beauty and German cosmetics houses are establishing technical partnerships with amino acid derivative manufacturers. This channel compression is most visible in South Korea and Germany, where formulators prioritize green chemistry credentials and supply security over distributor breadth.
Global Caprylhydroxamic Acid Market Segmentation
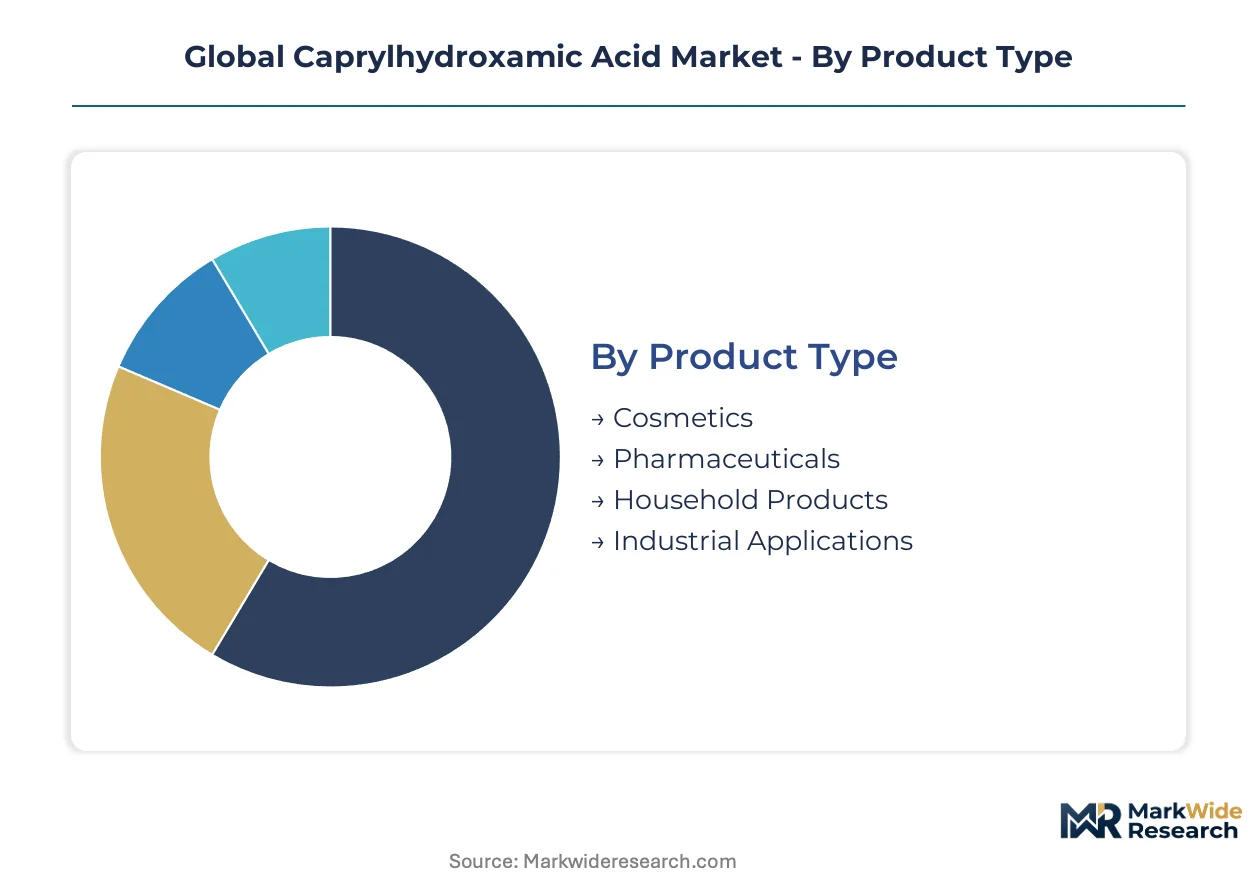
Caprylhydroxamic acid market segmentation reveals how regulatory pressure and formulation requirements fragment demand across distinct technical specifications and end-use channels. Understanding these divisions exposes where substitution economics and clean-label positioning create margin differentiation.
Product Type:
REACH substance evaluation and FDA notification requirements under MoCRA split demand across applications with divergent documentation burdens and hazard classification thresholds.
- Cosmetics:Eight-carbon hydroxamic acid serves as a paraben replacement in pH-neutral personal care formulations, with K-beauty exporters in South Korea scaling procurement to satisfy US FDA notification requirements. Clean-label positioning drives premium pricing for amino acid-derived chelating agents in skin and hair care.
- Pharmaceuticals:Metal-sequestration applications in drug formulations face stringent purity specifications that enzymatic amidation processes are beginning to satisfy. German and Dutch contract manufacturers are piloting lipase-catalyzed production to meet documentation standards for active pharmaceutical ingredient adjuvants.
- Household Products:Concentrated laundry and surface cleaning applications favor cost-efficient chelation performance over biobased positioning.
- Industrial Applications:Metalworking fluids and water treatment systems employ caprylhydroxamic acid where traditional EDTA substitution economics remain unfavorable.
Established volume favors Cosmetics; emerging adoption favors Pharmaceuticals.
End User:
Channel compression between personal care brands and specialty chemical suppliers is redistributing purchasing power away from traditional distribution intermediaries.
- Consumers:Direct-to-consumer clean beauty brands are qualifying hydroxamic acid alternatives ahead of EU Green Deal reformulation timelines, prioritizing supply security over distributor breadth.
- Manufacturers:Large cosmetics houses in Germany and South Korea are locking multi-year contracts with Philadelphia and UK-based producers to secure amino acid-derived preservative booster supply.
- Retailers:Mass-market personal care chains are consolidating ingredient sourcing through private-label formulators with REACH-compliant documentation.
- Distributors:Specialty chemical intermediaries are losing share to technical partnerships as formulators prioritize green chemistry credentials.
Procurement concentration favors Manufacturers; channel fragmentation challenges Distributors.
Form:
Equipment integration requirements and stability specifications divide demand between pump-dispense liquid systems and solid-format concentrated applications.
- Liquid:Dominates volume as manufacturers favor pump-dispense integration in personal care formulations, though viscosity specifications demand equipment retrofits at contract manufacturing organizations.
- Powder:Occupies niche positions in solid detergent tablets where stability requirements are stringent and concentrated laundry applications represent underpenetrated demand.
- Cream:Emulsion-based delivery systems in cosmetic formulations require compatibility testing with amino acid-derived chelating agents.
- Gel:Thickened aqueous systems for topical applications impose solubility constraints on hydroxamic acid loading levels.
Manufacturing scale favors Liquid; formulation innovation favors Powder.
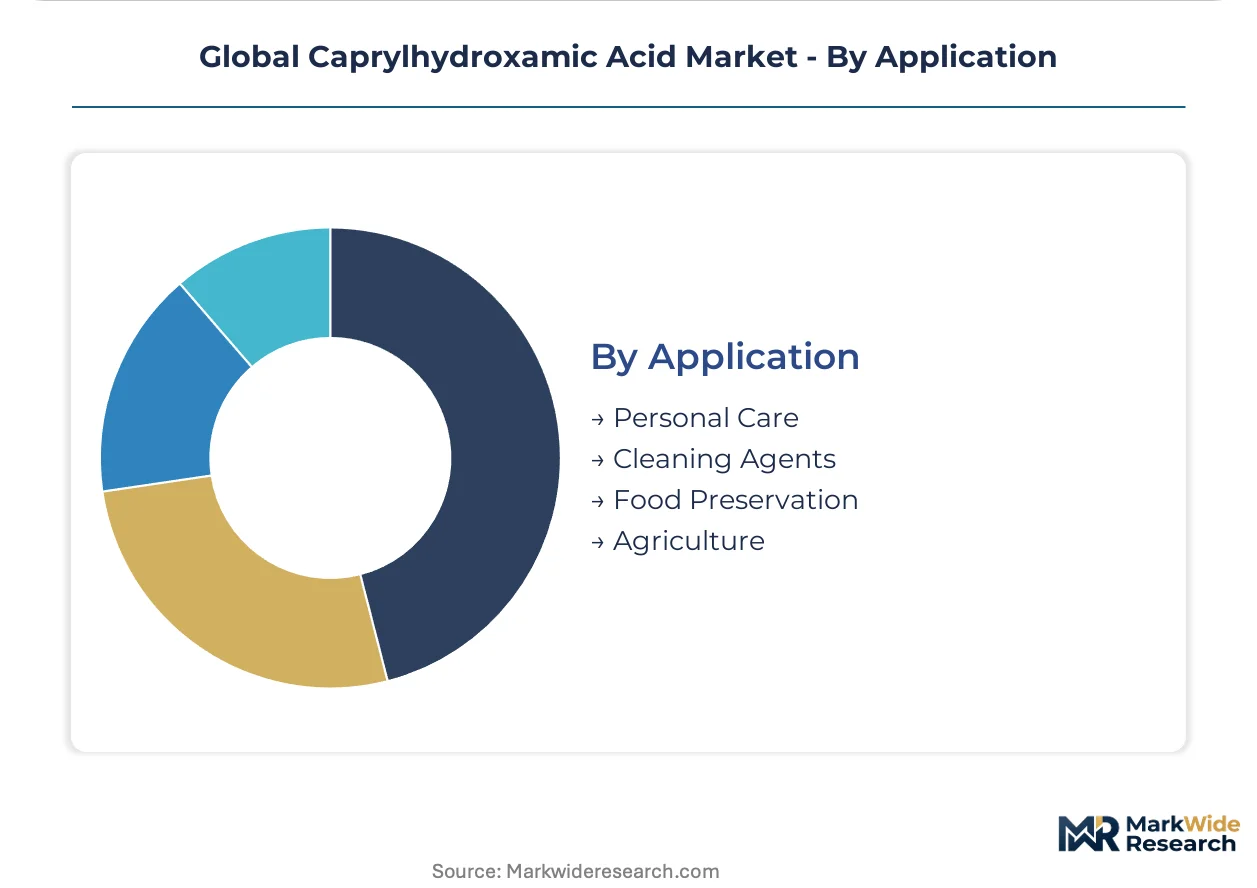
Application:
End-use differentiation separates premium personal care positioning from industrial cleaning applications where clean-label carries no pricing power.
- Personal Care:Skin, hair, and oral care formulations are climbing the fastest as paraben replacement chemistry accelerates across pH-neutral product lines in Germany, France, and South Korea.
- Cleaning Agents:Surface and fabric care applications retain traditional chelator share where EDTA substitution economics disadvantage hydroxamic acid alternatives.
- Food Preservation:Regulatory approval constraints limit caprylhydroxamic acid penetration relative to established antimicrobial systems.
- Agriculture:Micronutrient chelation in fertilizer formulations represents speculative demand contingent on agricultural yield optimization priorities.
Margin expansion favors Personal Care; cost competition dominates Cleaning Agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance evaluation deadlines anchor European demand for hydroxamic acid chelators. German cosmetics houses are accelerating reformulation timelines ahead of ECHA hazard classification reviews.
United States
FDA notification requirements under MoCRA are pulling amino acid-derived preservative boosters into domestic formulations. Philadelphia-based technical clusters supply K-beauty exporters seeking US market entry. Contract manufacturers in New Jersey are retrofitting pump-dispense equipment for liquid-grade viscosity specifications.
Germany
ECHA substance evaluation deadlines are forcing substitution of traditional chelators ahead of 2027 milestones. EU Green Deal chemical sustainability targets are compressing reformulation windows for personal care brands. Manufacturing concentration in North Rhine-Westphalia anchors European supply security for hydroxamic acid derivatives.
South Korea
MFDS cosmetic raw material standards are converging with international documentation norms for K-beauty exporters. Seoul Capital Area formulators are locking multi-year contracts with specialty chemical suppliers to secure preservative booster supply. Busan-Ulsan manufacturing corridors are scaling amino acid-derived chelating agent procurement for US-bound shipments.
China
NMPA and GB standards for cosmetic raw materials are elevating safety documentation burdens for import pathways. Yangtze River Delta chemical clusters are domesticating hydroxamic acid production to reduce dependency on European supply. Shanghai-based formulators are qualifying REACH-compliant suppliers for premium personal care lines.
United Kingdom
Post-Brexit regulatory divergence from EU REACH is creating dual dossier preparation requirements for chemical suppliers. Croda International Plc's UK manufacturing footprint anchors European supply for amino acid-derived chelating agents. Southeast England technical teams are navigating parallel FDA notification and UK REACH compliance for transatlantic cosmetics trade.
Global Caprylhydroxamic Acid Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the specialty chelating agent sector. The vendor base concentrates around Philadelphia and UK technical clusters where hydroxamic acid synthesis expertise pools. Three archetypes dominate: amino acid-derived specialists, global diversified chemical conglomerates, and regional fermentation-based producers. Competitive moves center on multi-year supply contracts with cosmetics houses and enzymatic amidation process licensing.
Within the amino acid-derived specialist tier, INOLEX occupies a position anchored by its Philadelphia-based technical team. BASF SE and Croda International Plc exemplify the global diversified archetype, with the former representing scale-driven distribution capabilities and the latter sitting within European manufacturing concentration. These three companies collectively illustrate how geographic clustering around synthesis expertise is reshaping supply security negotiations with formulators.
| Leading Market Players |
|---|
| INOLEX |
| BASF SE |
| Ashland Global Holdings Inc. |
| Clariant AG |
| Croda International Plc |
| Evonik Industries AG |
| TCI Chemical |
| Hangzhou Lingeba Technology |
| Ark Pharm Inc |
| Others |
Supply Flow & Price Mechanics
Enzymatic amidation displacing traditional chemical synthesis is redrawing manufacturing geography toward German and Dutch contract manufacturers while compressing capital barriers for new entrants and intensifying price competition in liquid-grade supply. This biotechnology shift simultaneously elevates purity specifications that incumbent chemical routes struggle to match economically, fragmenting pricing power across synthesis-method tiers.
Pricing Analysis
Price spreads between Philadelphia-based amino acid-derived supply and UK-manufactured volumes reflect certification-grade differentiation rather than feedstock cost alone. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels anchors the market, with FDA notification and REACH dossier preparation costs embedded in premium tiers. Cost compression in standard-grade liquid formulations is intensifying as enzymatic producers achieve scale, while powder-grade stability premiums remain insulated. Small cosmetics houses exhibit highest price sensitivity, whereas K-beauty exporters with locked multi-year contracts demonstrate lowest elasticity.
Supply Chain Analysis
Inventory lead times for caprylic acid derivatives have extended as Southeast Asian agricultural yield volatility disrupts palm kernel and coconut oil derivative planning. Supply concentrates in the United States, Germany, and the United Kingdom, with Philadelphia and North Rhine-Westphalia anchoring hydroxamic acid synthesis expertise. Feedstock dependency on palm kernel oil, coconut oil derivatives, and fermentation-based caprylic acid creates agricultural commodity exposure. Single-source vulnerability concentrates in amidation specialist talent pools. Distribution runs through direct technical partnerships between specialty chemical suppliers and cosmetics houses, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the cyclical trough of specialty chemist scarcity, with enzymatic biotechnology adoption providing the demand stimulus for capacity normalization.
For Market Incumbents: Secure multi-year supply contracts with K-beauty and German cosmetics houses before enzymatic competitors achieve pharmaceutical-grade purity certification. Lock Philadelphia and UK-based technical talent through competitive compensation structures. Backward integration into fermentation-based caprylic acid production hedges agricultural feedstock volatility. Defend amino acid-derived positioning against petrochemical substitute encroachment in industrial cleaning applications. For New Entrants and Emerging Players: REACH-compliant documentation fast-track offers the most penetrable entry pathway for mid-size suppliers targeting South Korean and Chinese cosmetic raw material markets. Solid detergent tablet powder grades remain underpenetrated relative to liquid formulation saturation. Biotechnology-derived feedstock positioning unlocks sustainability-premium pricing with European personal care brands. Direct technical partnership models bypass distributor margin capture. For Investors and Strategic Acquirers: ECHA 2027 hazard classification deadlines reshape the acquisition landscape toward enzymatic amidation capability and REACH dossier completeness. Five-to-ten year viability favors suppliers with dual US-EU regulatory documentation infrastructure. Acquisition target archetype: mid-cap enzymatic specialists with cosmetic-grade purity achievement and pending pharmaceutical qualification. Signal to watch: MFDS-GB standard convergence accelerating in Seoul Capital Area procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Amidation Scale-Up | German and Dutch pilot facilities are validating lipase-catalyzed production for pharmaceutical-grade purity thresholds. |
| Backward Integration into Fermentation Feedstock | Biotechnology-derived caprylic acid reduces agricultural commodity exposure for sustainability-positioned brands. |
| REACH Dossier Completion | ECHA substance evaluation deadlines are accelerating qualification timelines for hydroxamic acid alternatives. |
| Multi-Year Supply Agreement | K-beauty exporters are locking Philadelphia and UK-based capacity to satisfy US FDA notification requirements. |
| Direct Technical Partnership | Channel compression between specialty chemical suppliers and cosmetics houses is eliminating distributor intermediaries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic formulators, specialty chemical procurement leads, enzymatic process engineers, regulatory affairs directors, and contract manufacturing executives. Secondary validation drew from ECHA substance evaluation databases, FDA MoCRA notification filings, customs trade data for hydroxamic acid derivatives, and SEC disclosures from diversified chemical conglomerates. Bottom-up volume modeling across grade tiers and end-use segments was triangulated against top-down market sizing from feedstock consumption patterns.
Across the analysis window, forecasts were constructed through segmented modeling of cosmetics, pharmaceutical, household product, and industrial application demand. Grade tier, synthesis method, regional regulatory cluster, and end-use industry dimensions structured the projection framework. CAGRs were derived from substitution elasticity modeling for traditional chelator displacement and enzymatic capacity expansion curves. Forecast inputs included palm kernel oil price volatility indices and ECHA hazard classification review schedules.
Underlying assumptions cover enzymatic purity achievement timelines, regulatory documentation convergence, and agricultural yield stability, with deviation risk concentrated in specialty chemist availability and feedstock commodity swings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sorbitan Laurate Market
Additives
Calcium Tartrate Market
Additives
Sodium Benzoate Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Sodium Citrate Anhydrous Market
Additives
Global Corrosion Inhibitor Market
Additives
Sodium Diacetate Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Chemical Silage Additives Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Drilling Fluid Additives Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Rheological Additives Market
Additives
Green Polymer Additive Market
Additives
Plasticizers Market
Additives
Tamarind Gum Derivatives Market