
 Additives for Floor Coatings Market | 2026-2036
Additives for Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Additives for Floor Coatings Market Outlook
Buyer concentration in the industrial flooring segment is consolidating around large-scale warehouse operators and third-party logistics providers with standardized facility specifications. BASF SE leverages its integrated polyurethane precursor chain to supply high-performance additives for epoxy and polyurethane floor systems across European industrial parks. Dow Inc. sustains technology leadership in water-based dispersant chemistries that enable low-VOC compliance without sacrificing abrasion resistance. Clariant AG specializes in colorant and filler formulations tailored to the aesthetic and functional demands of commercial retail environments.
Additives for floor coatings comprise functional chemicals and particulate materials blended into resin matrices to modify rheology, cure kinetics, surface hardness, color stability, or slip resistance, typically dosed at 0.5-15% by weight depending on the target performance profile. These additives serve primarily to extend coating service life in high-traffic environments and to meet safety standards for slip and chemical resistance in industrial, commercial, and transportation settings. Polymeric additives dominate value capture due to their direct impact on mechanical durability and cure behavior, while water-based technology represents the fastest-expanding formulation platform as regulatory pressure on solvent emissions intensifies across construction end uses. Anti-slip agents command premium positioning in sports flooring and marine deck applications where coefficient-of-friction specifications are stringently enforced.
REACH and the EU Green Deal constrain solvent-based additive formulations in Europe, while EPA VOC regulations and OSHA slip-resistance standards shape product development priorities in the United States. China's GB standards and dual carbon goals from MEE are pushing domestic manufacturers toward waterborne epoxy and polyurethane additive packages with lower embodied carbon. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and secure multi-region product registrations ahead of tightening compliance deadlines.
Market Dynamics
Water-based polyurethane technology is displacing solvent-borne systems across industrial flooring as REACH VOC restrictions tighten formulation standards in Europe and EPA regulations extend compliance burdens in the United States.
Growth Catalysts
- Warehouse automation:Third-party logistics providers in Germany and the United States are specifying high-performance anti-slip floor systems for robotic traffic environments. This specification pull is accelerating additive adoption for abrasion resistance.
- REACH Phase 2 restrictions:ECHA's tightening limits on solvent emissions are forcing reformulation toward waterborne epoxy and polyurethane additive packages across European industrial parks.
- China's dual carbon goals:MEE mandates on embodied carbon are redirecting domestic manufacturers toward low-VOC waterborne systems in industrial construction clusters.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate precursor costs fluctuate with crude oil indices, compressing margin stability for polyurethane additive formulators.
- Specialized dispersant supply:Water-based dispersant chemistries rely on concentrated European and North American specialty chemical production, creating geographic supply risk.
- Cure kinetics limitation:Waterborne systems exhibit slower ambient cure rates than solvent-borne counterparts, restricting application windows in temperature-variable climates.
Strategic Opportunities
- India industrial corridor expansion:BIS standards adoption in warehousing and manufacturing infrastructure is opening specification channels for slip-resistant and chemical-resistant floor systems.
- Marine deck applications:Coefficient-of-friction specifications in commercial shipping and offshore platforms are creating premium positioning for specialized anti-slip additive formulations.
- EU Green Deal procurement:Public infrastructure tenders with embedded carbon thresholds are mandating low-VOC floor coating systems, accelerating waterborne technology penetration.
Industry Challenges
- Formulation chemist scarcity:Expertise in waterborne polyurethane rheology modification is concentrated among aging specialists in European and North American technical centers.
- Multi-jurisdiction registration:Divergent VOC limits between EPA, REACH, and China's GB standards require parallel compliance documentation, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additives for Floor Coatings Market |
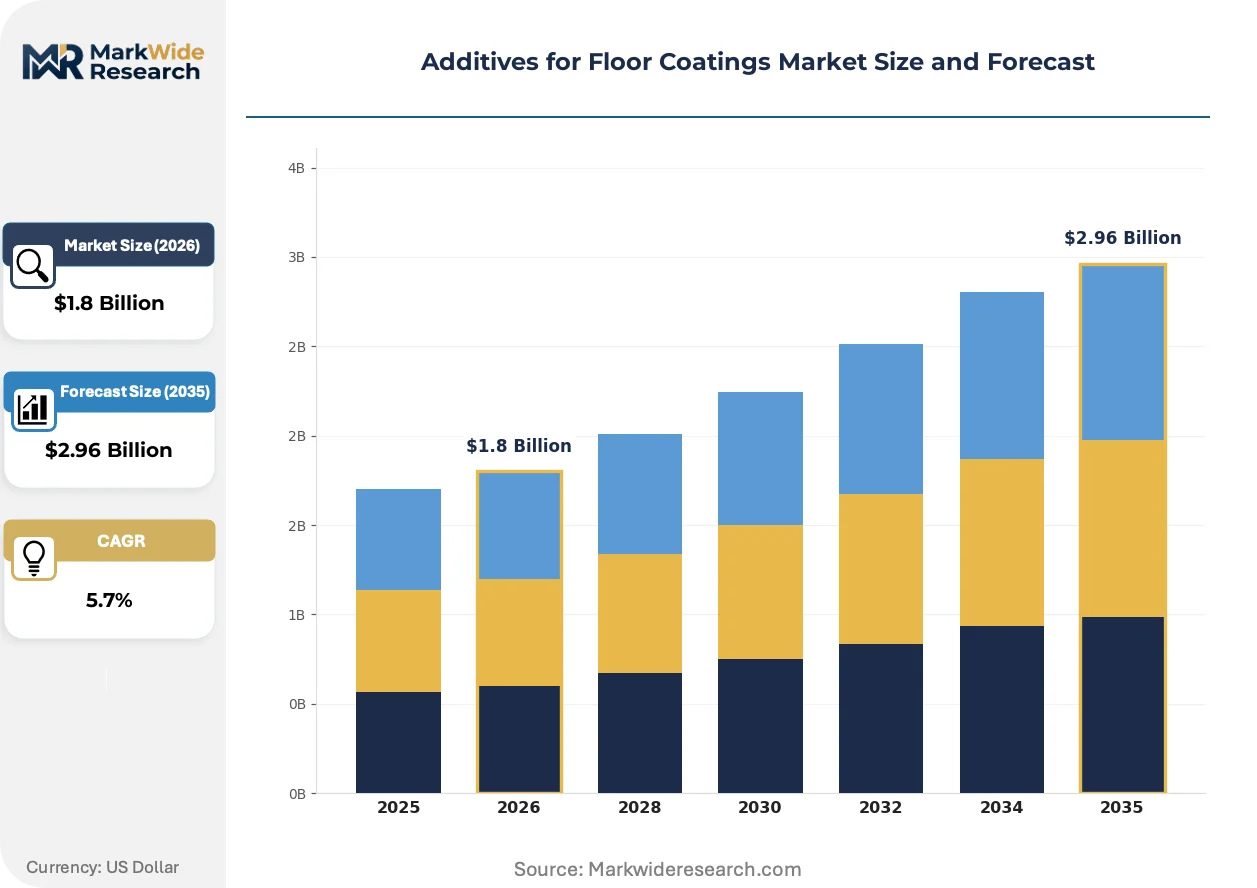
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Additives, Fillers, Colorants, Anti-Slip Agents Application: Industrial Flooring, Residential Flooring, Commercial Flooring, Sports Flooring End Use Industry: Construction, Automotive, Aerospace, Marine Technology: Solvent-Based, Water-Based, Polyurethane, Epoxy |
| Companies Covered | Dow Inc., Clariant AG, BASF SE, Nouryon, The Lubrizol Corporation, ALTANA AG, Arkema, Eastman Chemical Company, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additives for Floor Coatings Market Strategic Shifts
Digital specification platforms and automated facility management systems are reshaping how industrial buyers source and validate floor coating performance, compressing traditional distributor relationships.
Bio-based polyol feedstocks derived from agricultural waste streams are entering commercial-scale production for polyurethane floor coating formulations. European industrial flooring contractors in the Netherlands and Belgium are piloting these systems for carbon-accounting compliance. This feedstock transition is decentralizing petrochemical dependency in resin precursor supply chains.
EPA VOC regulations under the Clean Air Act are tightening permissible solvent content in architectural and industrial maintenance coatings. Manufacturers serving the United States market are accelerating waterborne additive package development to maintain product registration validity. Warehouse and logistics end-uses in California and Texas are experiencing the most acute reformulation pressure due to state-level air quality implementation plans.
Facility operators are consolidating procurement around performance-based specifications rather than brand-centric purchasing. Large-scale third-party logistics providers in Germany and the United States are issuing unified technical standards across their property portfolios. This consolidation is compressing regional formulation variation and favoring additive suppliers with multi-site qualification capabilities.
Additives for Floor Coatings Market Segmentation
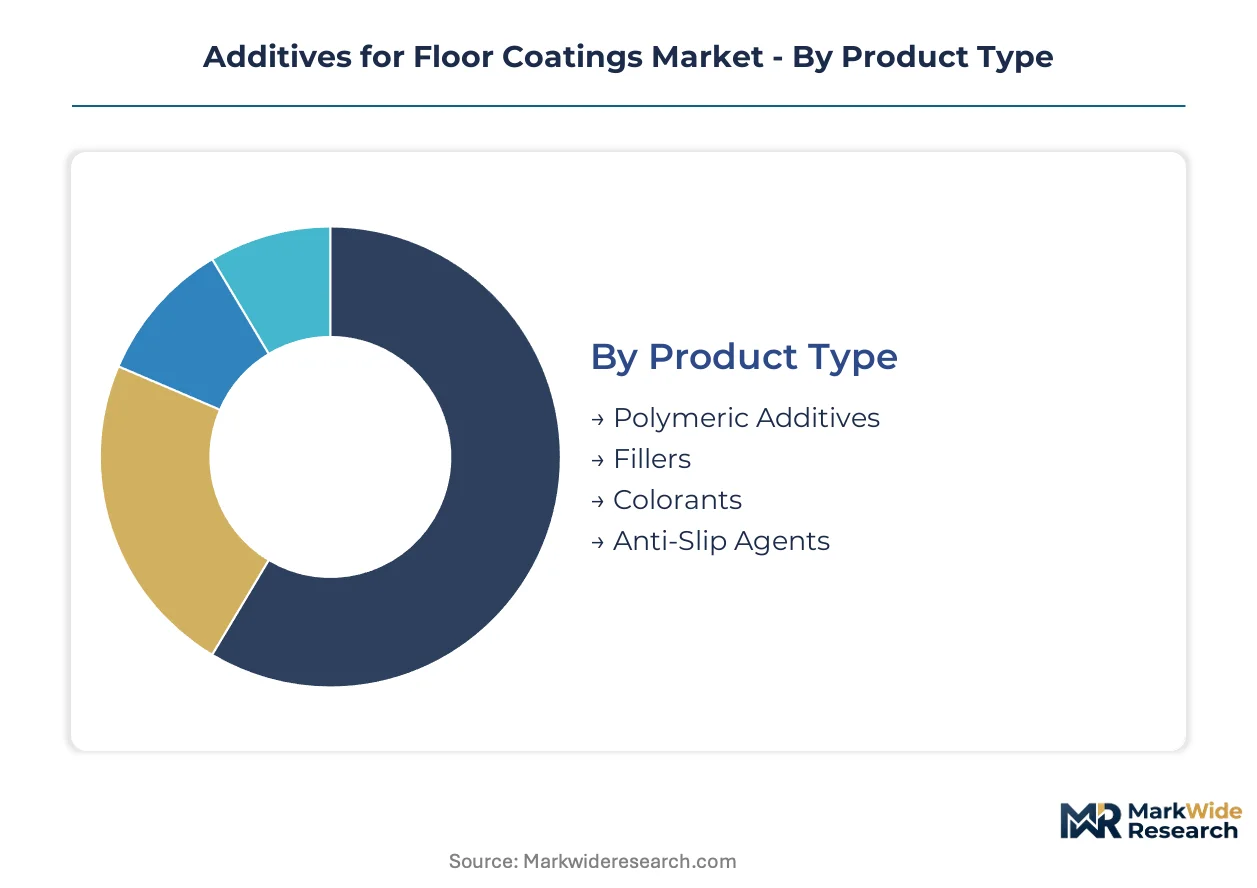
Additives for floor coatings serve distinct performance requirements across resin chemistries and installation environments. Specification standards vary sharply between industrial safety mandates and aesthetic commercial demands.
Product Type:
Buyers differentiate primarily by whether the additive modifies mechanical durability, surface finish, or safety compliance.
- Polymeric Additives:Reactive oligomers and chain extenders that control cure kinetics and final film hardness in polyurethane and epoxy matrices. Demand concentrates in German automotive manufacturing facilities where robotic traffic necessitates extreme abrasion resistance. REACH Phase 2 restrictions are accelerating waterborne-compatible polyol development.
- Fillers:Particulate extenders including calcium carbonate, silica, and alumina trihydrate that reduce raw material costs and modify surface texture. Chinese industrial construction clusters absorb the highest volumes as domestic manufacturers prioritize cost-efficient high-build systems.
- Colorants:Pigment dispersions and dye concentrates providing UV stability and batch consistency for commercial retail environments. Clariant AG maintains specialized formulation capabilities for this segment.
- Anti-Slip Agents:Surface-modifying particulates that elevate coefficient-of-friction values for safety compliance. Marine deck applications in North Sea offshore platforms command premium positioning due to stringent slip-resistance standards.
Polymeric additives lead volumes today; anti-slip agents are gaining share fastest.
Application:
Performance specifications diverge between high-traffic industrial zones and aesthetic-driven commercial spaces.
- Industrial Flooring:Heavy-duty systems requiring chemical resistance, impact tolerance, and rapid cure for minimal downtime. Third-party logistics providers in the United States are standardizing specifications across distribution networks. OSHA slip-resistance standards and EPA VOC regulations shape product selection.
- Commercial Flooring:Decorative finishes balancing durability with visual appeal for retail and hospitality environments. Color stability and gloss retention drive additive selection.
- Sports Flooring:Specialized surfaces demanding precise shock absorption and traction coefficients. Indoor athletic facilities in Germany specify certified systems for competitive play.
- Residential Flooring:Cost-sensitive decorative coatings with moderate durability requirements. Water-based technologies dominate due to interior air quality concerns.
Industrial flooring anchors current demand; sports flooring shows the steepest expansion trajectory.
End Use Industry:
Regulatory exposure and performance thresholds separate construction-driven volume from specialized industrial applications.
- Construction:The dominant consumption channel spanning new build and refurbishment across commercial, institutional, and residential structures. China's dual carbon goals from MEE are redirecting specification toward low-embodied-carbon waterborne systems.
- Automotive:Manufacturing plant flooring subjected to chemical exposure, thermal cycling, and heavy equipment loads. Just-in-time production schedules demand rapid-cure systems with minimal installation windows.
- Marine:Deck and hold coatings requiring saltwater corrosion resistance and crew safety compliance. Offshore platform operators in the North Sea enforce stringent coefficient-of-friction specifications.
- Aerospace:Hangar and maintenance facility floors exposed to hydraulic fluids, fuel residues, and specialized cleaning protocols. Cleanroom-compatible formulations command technical premiums.
Construction absorbs the highest volumes; marine applications expand most quickly on specialized specification pull.
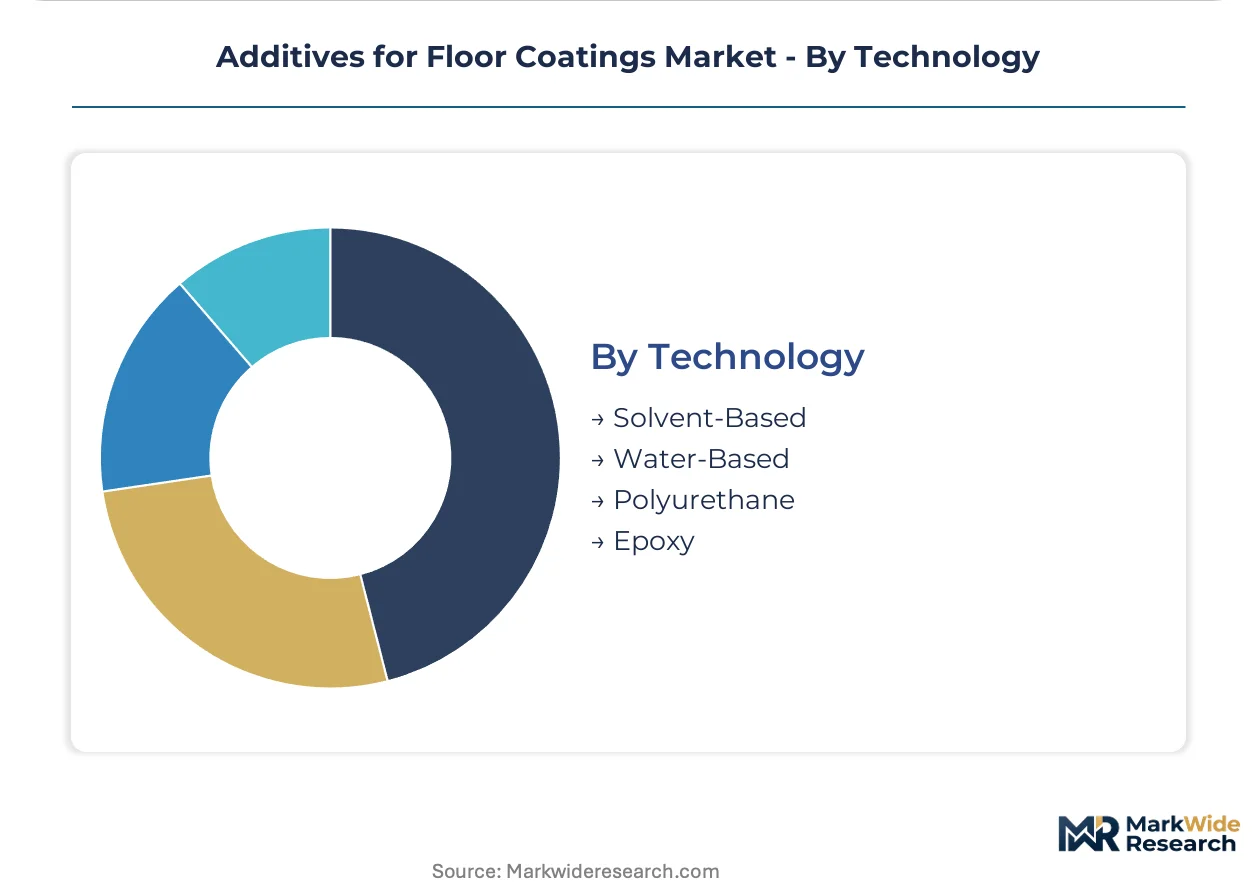
Technology:
Formulation platforms separate on regulatory compliance capability and performance envelope.
- Water-Based:Dispersions and emulsions achieving low-VOC compliance without sacrificing mechanical properties. Dow Inc. sustains leadership in dispersant chemistries enabling this transition. EPA regulations and REACH restrictions are accelerating displacement of solvent alternatives.
- Solvent-Based:Traditional systems offering rapid ambient cure and broad substrate compatibility. Regulatory pressure is compressing addressable market scope to jurisdictions with permissive VOC limits.
- Polyurethane:Two-component systems delivering exceptional abrasion resistance and chemical tolerance. BASF SE leverages integrated precursor supply for European industrial park deployments.
- Epoxy:Amine-cured systems dominating heavy-duty industrial applications with superior adhesion and hardness. Slower cure kinetics limit application in temperature-variable climates.
Polyurethane systems lead installed base; water-based technologies climb the fastest on regulatory mandate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China diverge sharply in their regulatory acceleration timelines, with REACH Phase 2 restrictions already compressing solvent-based formulations across European industrial parks while China's MEE dual carbon goals phase in more gradually through 2030. These contrasting enforcement calendars are reshaping supplier qualification requirements and reformulation investment priorities across both markets.
United States
Third-party logistics providers operating distribution centers in California and Texas are standardizing anti-slip floor specifications across their property portfolios. EPA VOC regulations under the Clean Air Act are tightening permissible solvent content, forcing additive formulators toward waterborne polyurethane packages. The Southeast industrial corridor spanning Georgia and South Carolina is absorbing concentrated warehouse construction investment.
Germany
Automotive manufacturing facilities in Bavaria and Baden-Württemberg specify extreme abrasion-resistant floor systems for robotic traffic environments. ECHA's REACH Phase 2 restrictions on solvent emissions are accelerating waterborne-compatible polyol development among domestic formulators. The Rhine-Ruhr industrial cluster is deploying high-performance epoxy and polyurethane floor systems across refurbished logistics infrastructure.
China
Industrial construction clusters in the Yangtze River Delta and Pearl River Delta are prioritizing cost-efficient high-build filler systems for manufacturing flooring. MEE mandates on embodied carbon are redirecting domestic manufacturers toward waterborne epoxy additive packages. The Beijing-Tianjin-Hebei corridor is implementing stricter VOC enforcement for warehouse refurbishment projects.
India
BIS standards adoption in warehousing and manufacturing infrastructure is opening specification channels for slip-resistant floor systems. The national building code regulator is aligning industrial flooring requirements with international safety benchmarks. The Maharashtra-Gujarat industrial belt is experiencing concentrated demand from third-party logistics facility expansion.
Netherlands
Industrial flooring contractors in the Randstad region are piloting bio-based polyol feedstocks derived from agricultural waste streams for carbon-accounting compliance. The EU Green Deal is embedding carbon thresholds into public infrastructure tenders for low-VOC floor coating systems. The Eindhoven-Brainport technology corridor is qualifying high-performance polyurethane systems for cleanroom manufacturing environments.
Additives for Floor Coatings Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the additive supply chain, creating a tiered competitive structure where scale advantages in precursor integration clash with formulation agility in niche applications. The market fragments across three strategic archetypes: integrated chemical majors controlling polyurethane precursor supply, specialty dispersant developers enabling waterborne transitions, and regional formulators serving localized compliance requirements. Capacity expansion in water-based dispersant production and strategic partnerships for bio-based feedstock sourcing represent the dominant competitive moves reshaping supplier positioning.
Within the integrated chemical major tier, BASF SE and Dow Inc. anchor competitive dynamics through their respective positions in polyurethane precursor chains and water-based dispersant chemistries. Clariant AG occupies a distinct specialization vector in colorant and filler formulations. These three entities exemplify how geographic origin and corporate structure—German AG status for BASF SE and Clariant AG, US Inc. incorporation for Dow Inc.—correlate with divergent strategic postures toward regulatory compliance and technology platform development.
| Leading Market Players |
|---|
| Dow Inc. |
| Clariant AG |
| BASF SE |
| Nouryon |
| The Lubrizol Corporation |
| ALTANA AG |
| Arkema |
| Eastman Chemical Company |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty additive formulators in Germany and the United States are consolidating regional production footprints while tightening pricing discipline on standardized waterborne polyurethane packages. This ownership concentration feeds directly into supply behavior, as portfolio companies prioritize margin recovery over volume capture in reformulation-heavy regulatory environments.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for filler-grade additives across Asia-Pacific industrial construction clusters. Three-tier pricing structure across premium, standard, and economy levels separates marine-certified anti-slip formulations from warehouse-standard dispersant packages and commodity filler blends. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are absorbing volume share with aggressive localization. Third-party logistics providers in Germany exhibit the lowest price sensitivity due to specification lock-in for robotic traffic environments, while Indian warehousing contractors remain highly price-sensitive as BIS standards adoption lags.
Supply Chain Analysis
Single-source vulnerability sits with European specialty dispersant production concentrated in the Netherlands and Belgium for waterborne polyurethane rheology modifiers. Raw material flows draw from German polyol precursors, Chinese alumina trihydrate fillers, and Indian calcium carbonate extenders. Tariff exposure on isocyanate imports from the United States into Europe is elevating working capital requirements for polyurethane additive formulators. Distribution runs through regional chemical distributors with technical service capabilities, bypassing commodity traders for specification-heavy industrial flooring projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier displacement of solvent-borne systems, as REACH Phase 2 and EPA compliance deadlines force specification upgrades toward waterborne additive packages with embedded technical service.
For Market Incumbents: Deepen backward integration into bio-based polyol feedstocks to capture carbon-accounting premiums from EU Green Deal procurement. Expand captive dispersant production in the Randstad region to neutralize single-source vulnerability. Defend against specialty chemical entrants from Asia-Pacific by accelerating multi-jurisdiction registration ahead of China's GB standard convergence. For New Entrants and Emerging Players: Regional formulators with MEE compliance documentation should target the Maharashtra-Gujarat industrial belt before BIS standards fully mature. Marine deck applications in the North Sea offer the most penetrable premium segment due to stringent coefficient-of-friction specifications and limited qualified suppliers. Partner with industrial flooring contractors piloting carbon-accounting systems to bypass established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European dispersant specialists with stranded solvent-borne technology portfolios. Long-term viability hinges on successful waterborne transition completion and qualification with consolidated third-party logistics providers. Watch for EPA state implementation plan acceleration in California and Texas as the inflection signal for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyols | Captures EU Green Deal carbon-accounting premiums in Dutch industrial flooring pilots. |
| Capacity Expansion in Water-Based Dispersants | Neutralizes single-source vulnerability from concentrated European specialty chemical production. |
| Multi-Jurisdiction Registration Acceleration | Secures product validity ahead of REACH Phase 2 and China's GB standard convergence deadlines. |
| Long-Term Supply Agreement with 3PL Providers | Locks in standardized specifications across German and US distribution network rollouts. |
| Joint Venture for Indian Market Entry | Combines MEE-compliant technology with local BIS certification capabilities in the Maharashtra-Gujarat corridor. |
Study Parameters
Coverage spans Germany, China, the United States, India, and the Netherlands, with primary inputs from each market. The research combines structured interviews with plant managers at automotive manufacturing facilities, procurement leads at third-party logistics providers, distribution channel partners in industrial chemical supply, and technical R&D directors at polyurethane formulators. Secondary validation draws from ECHA REACH filings, EPA Clean Air Act implementation plans, MEE dual carbon policy documents, and customs trade data on polyol and isocyanate flows. Bottom-up volume estimates triangulate against top-down construction spending allocations.
Granularity-level modeling extends to product type, application environment, end-use industry, and technology platform across the projection horizon. Segmentation dimensions include resin chemistry compatibility, performance tier, and regional regulatory cluster. CAGRs derive from installed base turnover analysis and specification shift elasticity. Industry-specific forecast inputs incorporate warehouse automation penetration rates and marine deck safety standard adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical input volatility and regulatory enforcement calendar shifts. Forecasts reflect documented assumptions on reformulation timelines and buyer consolidation trajectories. Specific risks that could revise projections include accelerated MEE enforcement in China, REACH restriction scope expansion, and breakthrough cure-kinetics technology for waterborne systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Alginic Acid Market
Additives
Engine Oil Additive Market
Additives
Global Metal Scavenging Agents Market
Additives
Pearlizers Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Potassium Nitrate Market
Additives
Gluconic Acid and Derivatives Market
Additives
Choline Chloride Market
Additives
Tricalcium Citrate Market
Additives
Triazine UV Absorber Market
Additives
Inorganic Filler Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Glycol Acetate Market
Additives
Chitosan Powder Market
Additives
Global Propyl Acetate Market
Additives
Calcium Tartrate Market