
 Implantable Drug Delivery Devices Market | 2026-2036
Implantable Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Drug Delivery Devices Market Outlook
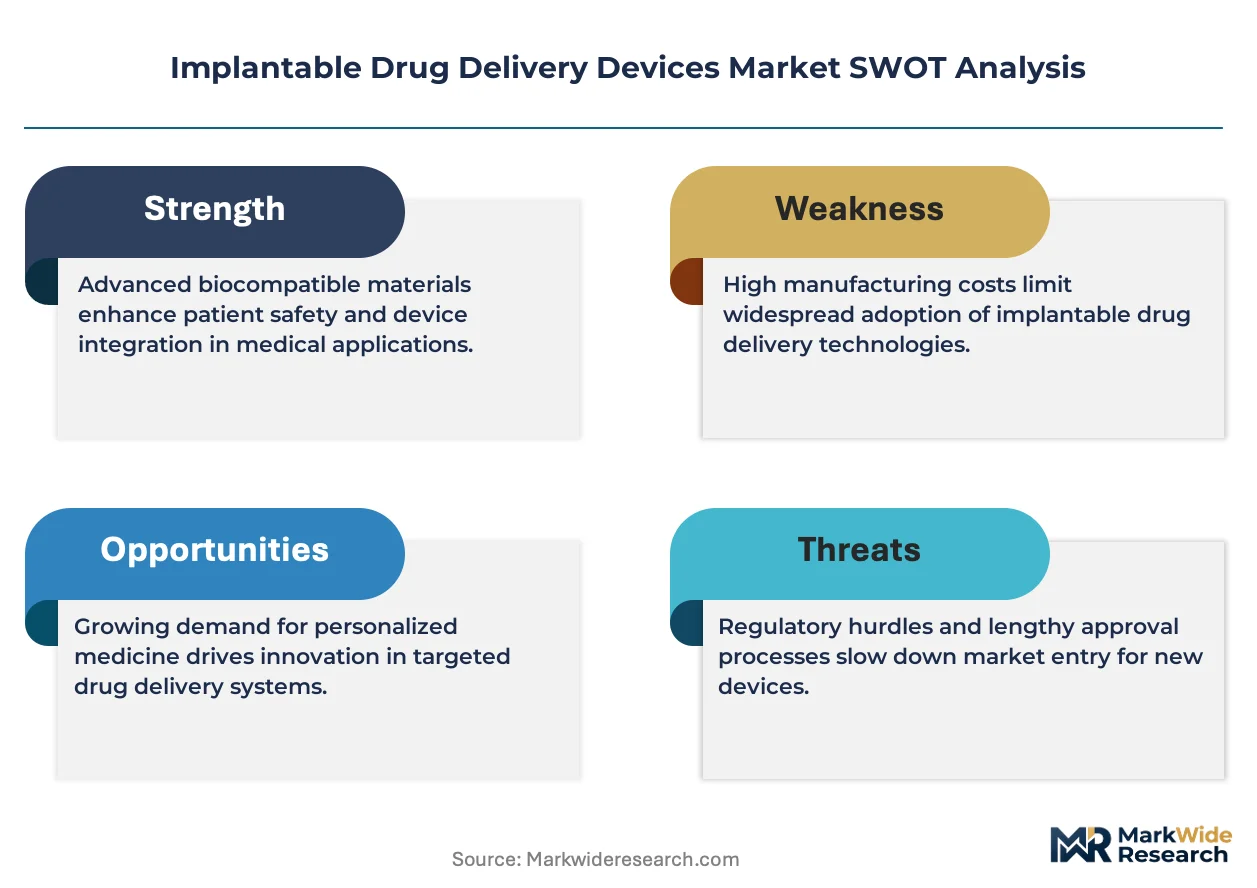
The EU Medical Device Regulation (MDR) is repositioning compliance requirements for long-acting implantable systems entering European markets. Medtronic leverages its neurostimulation infrastructure to extend into drug-device combination platforms. Abbott Laboratories anchors its portfolio through polymer-based biodegradable depot programs. Boston Scientific Corporation competes on interventional delivery expertise across oncology and pain management segments.
Implantable drug delivery devices are sealed, biocompatible reservoirs or pumps surgically placed within body cavities or subcutaneous tissue, engineered from silicone elastomers or biodegradable polyesters to release therapeutic agents at programmed rates via osmotic pressure, electrokinetic force, or polymer erosion. These systems serve chronic conditions requiring sustained plasma levels that oral or injectable regimens cannot maintain. Infusion pumps occupy the largest revenue pool due to established reimbursement in pain management and spasticity, while biodegradable implants represent the fastest-expanding category as polymer science enables tunable erosion kinetics for hormone therapy and vaccination protocols. Electrode-integrated electrokinetic platforms lead technology differentiation, though osmotic systems dominate manufacturing scale.
The FDA's Quality System Regulation and the EU MDR's clinical evidence requirements shape premarket submission strategies and post-market surveillance obligations for all manufacturers. ISO 10993 biocompatibility standards and ASTM F748 testing protocols govern material selection and leachable assessment across regulatory jurisdictions. Stakeholders must monitor evolving FDA guidance on combination product designation and the EU's impending EUDAMED database mandates to preserve market access trajectories.
Market Dynamics
Biodegradable polymer erosion kinetics are displacing osmotic pump dominance as the primary mechanism for sustained-release therapeutics, compressing development timelines for hormone therapy and oncology applications while forcing incumbent manufacturers to retool reservoir architectures.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated review pathway compresses commercialization timelines for novel reservoir technologies, enabling faster patient access to next-generation implantable infusion systems.
- Chronic Disease Management Programs:Hospital systems in the United States are scaling long-term supply contracts for implantable infusion systems as value-based care models reward sustained therapeutic outcomes.
- Electrokinetic Force Mechanisms:Electrode-integrated platforms enable programmable dose modulation for pain management, differentiating device portfolios against fixed-rate osmotic alternatives.
Market Restraints
- Silicone Elastomer Supply Concentration:Medical-grade silicone feedstock production clusters in Northeast Asia, exposing device manufacturers to geopolitical disruption and input cost volatility.
- EU MDR Clinical Evidence Requirements:The expanded post-market surveillance obligations and notified body capacity constraints extend certification timelines for long-acting implantable systems entering European markets.
- Oral Long-Acting Formulations:Monthly and quarterly injectable depot therapies for schizophrenia and addiction medicine compete directly with implantable alternatives on convenience and reversibility.
Strategic Opportunities
- Pediatric Oncology Applications:Biodegradable implants with tunable erosion profiles address unmet needs for sustained chemotherapy delivery in children where repeated surgical access carries elevated risk.
- India's PLI Scheme for Medical Devices:Production-linked incentives attract contract manufacturing investment for polymer-based depot programs targeting domestic and export markets.
- Remote Patient Monitoring Convergence:Integration of implantable reservoirs with Bluetooth-enabled adherence tracking creates subscription revenue streams for integrated delivery networks.
Industry Challenges
- ISO 10993 Biocompatibility Testing Bottlenecks:Extended cytotoxicity and sensitization study timelines delay premarket submissions as contract research organization capacity fails to match application volume.
- Combination Product Designation Complexity:FDA's evolving guidance on primary mode of action determinations forces manufacturers to maintain parallel regulatory strategies for drug and device lead jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Drug Delivery Devices Market |
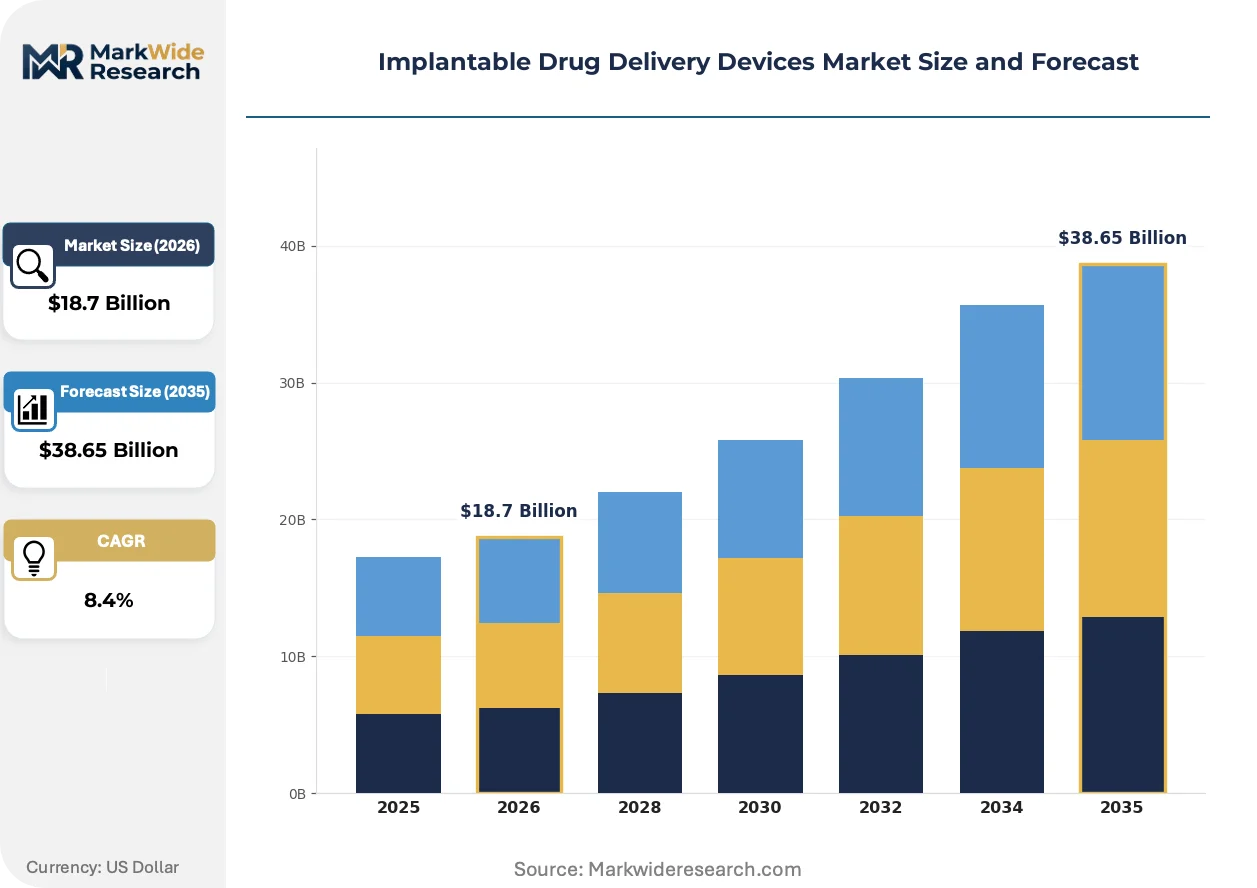
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Biodegradable Implants, Reservoirs, Microneedles Technology: Electrokinetic, Polymer-Based, Pulsatile, Osmotic End User: Clinics, Hospitals, Research Laboratories, Homecare Providers Application: Pain Management, Cancer Treatment, Hormone Therapy, Vaccination |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Bausch & Lomb, Bayer, Allergan, Merck & Co., Johnson & Johnson, Flowonix Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Drug Delivery Devices Market Strategic Shifts
Polymer science advances and regulatory pathway refinements are compressing the gap between bench-scale erosion kinetics and commercial-scale manufacturing, while procurement models in integrated delivery networks reward devices with embedded adherence verification.
Biodegradable polyester matrices with tunable molecular weight distributions are rewriting the competitive landscape for sustained-release hormone therapy. Women's health clinics and fertility centers in the United States are adopting these systems at twice the rate of traditional osmotic alternatives. The technology is rewriting pricing structures by eliminating explantation surgery costs and reducing long-term complication liability.
The EU Medical Device Regulation's post-market clinical follow-up requirements are mandating real-world evidence generation for all Class III implantable drug delivery systems. Manufacturers must now budget for five-year surveillance studies and periodic safety update reports as standard commercialization costs. Pain management devices with established European market presence face the steepest compliance burden as legacy clinical data packages rarely meet MDR sufficiency standards.
Integrated delivery networks are consolidating vendor contracts around devices with embedded dose verification and remote monitoring capabilities. Hospital procurement committees in the United States now require Bluetooth-enabled reservoir telemetry as a baseline specification, displacing standalone mechanical pumps. Oncology infusion centers demonstrate the most aggressive adoption curves as value-based reimbursement ties physician compensation to treatment adherence metrics.
Implantable Drug Delivery Devices Market Segmentation
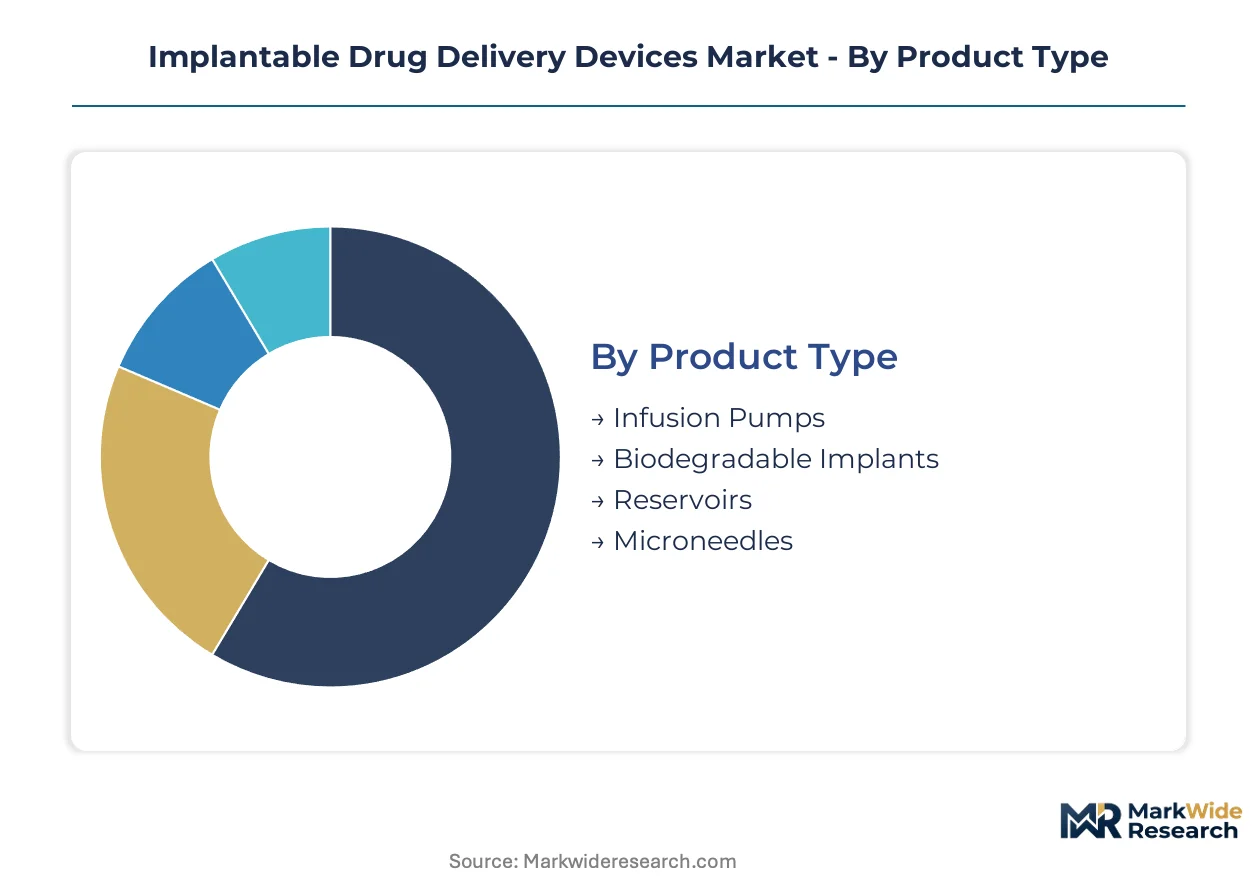
Segmentation in the implantable drug delivery devices market reveals divergent commercial strategies across mechanism complexity and care setting economics. Manufacturers must calibrate reservoir architectures, release kinetics, and connectivity features to match reimbursement pathways and surgical workflow requirements.
Product Type:
Standardized pump platforms dominate procurement volumes while biodegradable systems command premium positioning through elimination of explantation procedures.
- Infusion Pumps:Programmable reservoirs with peristaltic or piston-driven mechanisms deliver precise flow rates for intrathecal and intravascular applications. United States hospital systems concentrate demand through integrated delivery network contracts that prioritize established reimbursement codes for pain management and spasticity.
- Biodegradable Implants:Polyester or polyanhydride matrices erode via hydrolysis to release therapeutic payloads without surgical retrieval. Fertility clinics and women's health centers in the United States adopt these at accelerated rates as polymer science enables tunable erosion profiles matching hormone therapy protocols.
- Reservoirs:Passive diffusion chambers store liquid or gel formulations for localized release.
- Microneedles:Miniaturized projection arrays enable transdermal or intradermal depot formation.
Leading the category by volume: Infusion Pumps. Growing fastest: Biodegradable Implants.
Technology:
Cost tiers separate precision-controlled electrokinetic platforms from passive osmotic systems with minimal electronic content.
- Electrokinetic:Electrode-integrated architectures modulate drug release via iontophoretic or electroosmotic force, enabling patient-controlled dosing adjustments. Pain management applications in the United States drive adoption as Bluetooth-enabled platforms support remote adherence monitoring required by value-based reimbursement models.
- Polymer-Based:Biodegradable matrices rely on molecular weight distribution and crystallinity to program erosion kinetics. Oncology and vaccination protocols in research-intensive geographies favor these systems for tunable release windows spanning weeks to months.
- Pulsatile:Mechanically triggered reservoirs release discrete boluses in response to physiological sensors or external activation.
- Osmotic:Semi-permeable membranes generate constant release rates through water influx and hydrostatic pressure differentials.
Highest margin concentration: Electrokinetic. Steepest expansion trajectory: Polymer-Based.
End User:
Application maturity determines whether procurement flows through centralized hospital systems or dispersed outpatient channels.
- Hospitals:Surgical implantation of infusion pumps and complex reservoir systems occurs in tertiary care centers with neurosurgical and interventional radiology capabilities. United States integrated delivery networks negotiate multi-year supply agreements that bundle device procurement with adherence monitoring services.
- Clinics:Outpatient facilities specializing in pain management, fertility, or oncology administer biodegradable implants and microneedle systems. Reimbursement simplicity accelerates adoption for procedures not requiring general anesthesia or overnight admission.
- Homecare Providers:Post-implantation monitoring and patient education services support long-term therapy adherence.
- Research Laboratories:Preclinical and clinical trial operations test novel reservoir materials and release mechanisms.
Primary procurement volume: Hospitals. Fastest channel growth: Clinics.
Application:
Regulatory pathway complexity and reimbursement stability separate established therapeutic areas from emerging indications.
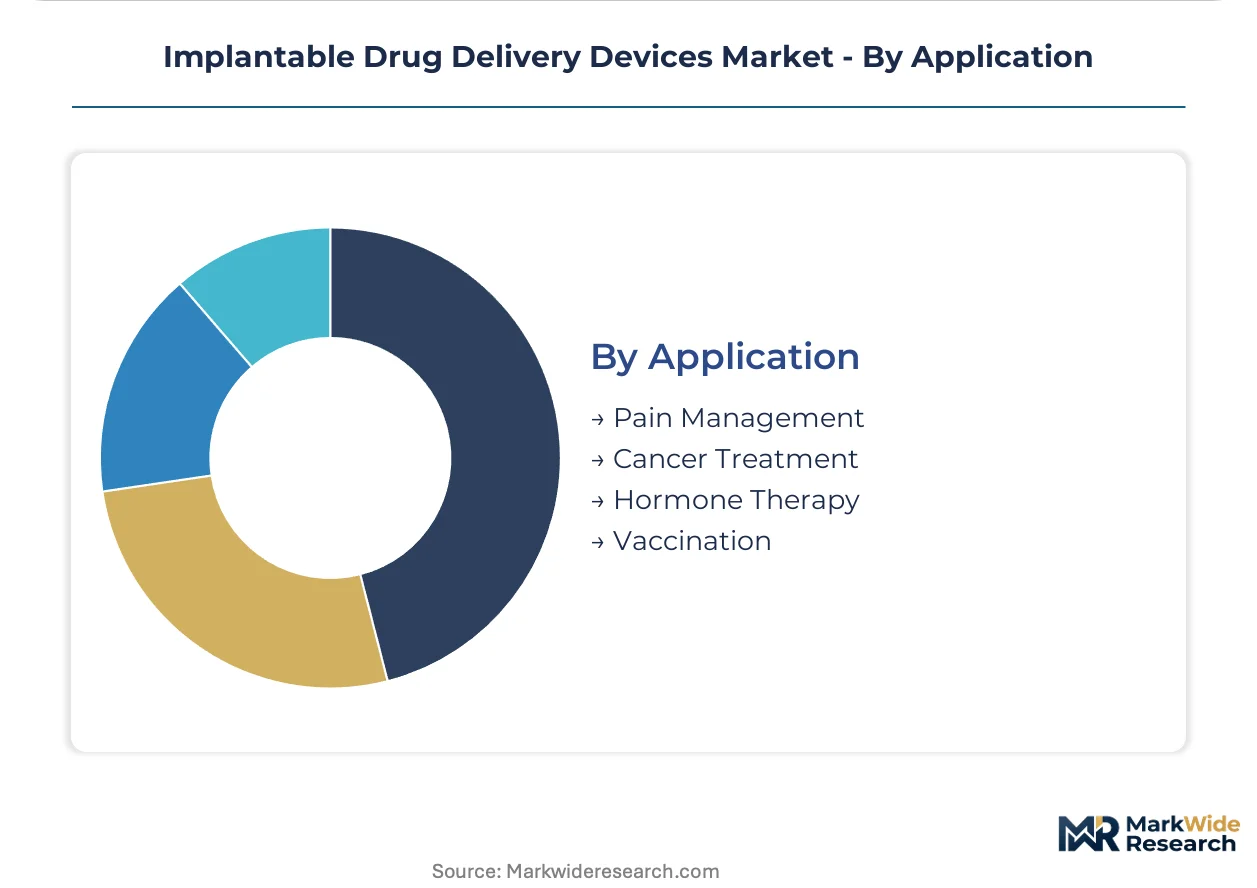
- Pain Management:Intrathecal opioid and local anesthetic delivery via implantable pumps represents the most mature reimbursement category. FDA breakthrough device designations for novel reservoir technologies concentrate in this segment as manufacturers seek accelerated pathways for next-generation systems.
- Cancer Treatment:Biodegradable implants enable localized chemotherapy delivery with reduced systemic toxicity. Pediatric oncology demonstrates particular unmet need as tunable erosion profiles eliminate repeated surgical access in vulnerable patient populations.
- Hormone Therapy:Sustained-release testosterone, estrogen, and fertility agents leverage polymer erosion kinetics.
- Vaccination:Single-administration depot formulations target adherence challenges in immunization programs.
Revenue concentration: Pain Management. Fastest indication expansion: Cancer Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Northeast Asia for medical-grade silicone feedstock, while consumption tilts toward United States hospital systems negotiating integrated delivery network contracts. European certification timelines extend under MDR post-market surveillance mandates. India's production-linked incentive scheme attracts contract manufacturing for polymer-based depot programs.
United States
FDA breakthrough device designations accelerate commercialization timelines for novel reservoir technologies. Integrated delivery networks in Texas, California, and the Northeast Corridor bundle device procurement with adherence monitoring services. Value-based reimbursement models reward sustained therapeutic outcomes in pain management and spasticity segments.
Germany
Notified body capacity constraints under EU MDR extend certification timelines for Class III implantable systems. The country's national pharmaceutical regulator enforces expanded post-market clinical follow-up requirements. Industrial clusters in Baden-Württemberg and Bavaria host precision polymer processing facilities serving biodegradable implant manufacturers.
China
Domestic demand for implantable infusion systems expands through hospital tier-upgrading programs. NMPA streamlines combination product review pathways for drug-device platforms. Manufacturing gravity centers on the Yangtze River Delta, where silicone elastomer compounders feed medical device assemblers.
India
CDSCO harmonizes quality standards with ISO 10993 biocompatibility protocols for imported and domestic devices. The PLI scheme for medical devices attracts investment in polymer-based depot manufacturing for export markets. Karnataka and Maharashtra host emerging contract research organizations supporting premarket submission strategies.
Switzerland
Swissmedic maintains stringent clinical evidence requirements for long-acting implantable systems entering European markets. Precision polymer science capabilities in the Basel region support tunable erosion kinetics development. The country's regulatory framework attracts manufacturers seeking parallel FDA-EMA submission efficiencies.
Implantable Drug Delivery Devices Market Competitive Environment
The competitive structure tilts toward diversified medtech conglomerates with neurostimulation infrastructure. Market concentration reflects high barriers from ISO 10993 biocompatibility testing and FDA Quality System Regulation compliance. Three archetypes dominate: diversified healthcare conglomerates extending into combination products, interventional device specialists, and pharmaceutical companies integrating delivery mechanisms. Dominant competitive moves include strategic partnerships for polymer science capabilities and portfolio diversification into biodegradable depot programs.
Among diversified healthcare conglomerates, Medtronic leverages neurostimulation infrastructure to extend into drug-device combination platforms. Abbott Laboratories anchors polymer-based biodegradable depot positioning. Boston Scientific Corporation occupies interventional delivery expertise across oncology and pain management segments.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Bausch & Lomb |
| Bayer |
| Allergan |
| Merck & Co. |
| Johnson & Johnson |
| Flowonix Medical |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FDA breakthrough-designated electrokinetic platforms and commodity osmotic pumps manifests in divergent margin structures and procurement pathways across United States integrated delivery networks. Premium tiers command three-year subscription contracts bundling device telemetry with adherence monitoring, while standard reservoirs compete on per-unit procurement through group purchasing organizations.
Pricing Analysis
Margin tightening in biodegradable implant tiers reflects polymer feedstock volatility and extended ISO 10993 testing timelines that compress development budgets. Three-tier pricing structure across premium electrokinetic, standard osmotic, and economy passive reservoir levels differentiates on Bluetooth connectivity and explantation avoidance. Cost-down pressure on standard pumps accelerates because oral long-acting formulations compete on reversibility. Hospital procurement committees demonstrate lowest price sensitivity for pediatric oncology applications where surgical risk premiums dominate.
Supply Chain Analysis
Specialized polymer chemist availability in Switzerland and Germany constrains capacity expansion for tunable erosion kinetics development. Medical-grade silicone compounding concentrates in China's Yangtze River Delta, Japan's Kansai region, and the United States Gulf Coast. Raw material dependencies span platinum-cured silicone elastomers, biodegradable polyesters, and electrode-grade titanium. Single-source vulnerability in Northeast Asian silicone feedstock exposes manufacturers to geopolitical disruption. Distribution runs through integrated delivery network contracting offices in Texas, California, and the Northeast Corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU MDR clinical evidence requirements and ISO 10993 testing bottlenecks force subscale manufacturers toward strategic exits or acquisition.
For Market Incumbents: Extend polymer science capabilities through captive erosion kinetics laboratories in Basel and Boston to defend against biodegradable implant commoditization. Deepen backward integration into medical-grade silicone compounding to offset Northeast Asian supply concentration. Secure multi-year GPO contracts embedding remote monitoring subscriptions before value-based reimbursement fully matures. For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for contract manufacturing entry serving export markets with polymer-based depot programs. Target pediatric oncology applications where tunable erosion profiles address unmet surgical risk needs. Pursue CDSCO harmonization pathways as the fastest regulatory route to commercial proof points. For Investors and Strategic Acquirers: Re-rating potential sits with electrokinetic platform specialists given FDA breakthrough device designation acceleration and Bluetooth-enabled adherence tracking convergence. Five-to-ten-year viability favors manufacturers with parallel FDA-EMA submission capabilities and established neurostimulation infrastructure. Watch notified body capacity constraints in Germany as the signal for European certification timeline inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses commercialization timelines for novel reservoir technologies in pain management. |
| CE Marking Pathway Under MDR | Expanded post-market surveillance obligations extend certification timelines for Class III implantable systems entering European markets. |
| Hospital System Partnership | Integrated delivery network contracts bundle device procurement with adherence monitoring services in United States value-based care models. |
| Software Companion Development | Bluetooth-enabled reservoir telemetry creates subscription revenue streams linking device performance to reimbursement metrics. |
| Reimbursement Strategy | Established coding for intrathecal opioid delivery anchors infusion pump demand in United States pain management segments. |
Study Parameters
Independent corroboration across FDA 510(k) filings, EU MDR notified body certificates, and hospital procurement databases underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, GPO contracts managers, regulatory affairs leads, and interventional pain specialists combined with secondary validation from ClinicalTrials.gov, CMS Medicare reimbursement data, and ISO 10993 testing protocols. Bottom-up segment sizing and top-down market triangulation cross-checked manufacturer capacity disclosures against integrated delivery network contract volumes.
Comparable-period anchoring to historical reservoir adoption curves in pain management and spasticity segments established the forecast baseline across the projection horizon. Segmentation modeling spanned mechanism type, release kinetics architecture, connectivity tier, end-user setting, and regional regulatory cluster. CAGRs derived from polynomial trend fitting to procedural volume data and reimbursement code utilization. Forecast inputs incorporated polymer erosion kinetics development timelines and notified body capacity constraints.
Caveats apply where EU MDR post-market clinical follow-up requirements or silicone elastomer supply disruptions could materially shift the outlook. Forecasts reflect assumptions around FDA breakthrough designation throughput and value-based reimbursement penetration. Material deviation in notified body capacity or polymer feedstock availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Needle-Free Injectors Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Europe Ventilator Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Australia Medtech Market
Medical Devices
Medical Pendant Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Pocket Otoscope Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Non-Destructive Medical Technologies Market