
 Medical Smart Wearable Devices Market | 2026-2036
Medical Smart Wearable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Smart Wearable Devices Market Insights
Software-defined health analytics is broadening what medical smart wearable vendors monetize beyond hardware shipments. Apple leverages its ecosystem control to anchor recurring revenue through subscription health services integrated with device sensors. Samsung Electronics competes by extending its Galaxy Watch platform into clinical-grade monitoring partnerships with healthcare systems. Dexcom specializes in continuous glucose monitoring technology, dominating the diabetes wearable segment through precision biosensor calibration.
Medical smart wearable devices combine semiconductor-based biosensors, wireless communication modules, and algorithmic health analytics into body-worn form factors designed for continuous physiological monitoring and data transmission to clinical or consumer platforms. These systems typically integrate photoplethysmography, accelerometry, and electrochemical sensing with Bluetooth Low Energy or NFC protocols to achieve real-time vital signs capture with power budgets under 100 milliwatts. Smartwatches and ECG monitors command the largest installed base, while pulse oximeters represent the fastest-expanding category as post-acute care models prioritize respiratory tracking. Biosensor technology underpins margin concentration because proprietary optical and electrochemical designs create differentiation barriers that RFID or standard Bluetooth modules cannot replicate.
FDA software-as-medical-device regulations and HIPAA data governance requirements shape product development timelines and liability exposure for US-market wearables, while the EU Medical Device Regulation and GDPR impose parallel conformity and privacy obligations across European distribution channels. Japan's PMDA streamlines approval for designated remote monitoring devices, creating regulatory arbitrage opportunities for manufacturers with multi-market submission capabilities. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring, as payer decisions will determine which wearable applications transition from consumer wellness to billable clinical services.
Market Dynamics
FDA software-as-medical-device validation requirements are compressing product development timelines while hospital procurement committees now mandate clinical-grade algorithmic outputs before contract approval.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:Medicare CPT codes for continuous physiologic monitoring create direct revenue pathways for US health systems deploying body-worn biosensors.
- Photoplethysmography Miniaturization:Advances in optical heart rate sensing enable medical-grade accuracy in consumer form factors, expanding addressable use cases beyond acute care.
- Japan PMDA Streamlined Pathways:Designated remote monitoring device approvals accelerate market entry for manufacturers with multi-regulatory submission capabilities.
Market Restraints
- Specialized Semiconductor Supply Concentration:Foundry capacity for ultra-low-power biosensor ASICs concentrates in Taiwan, creating single-source vulnerability for optical sensing modules.
- FDA Algorithm Validation Burden:Software-as-medical-device predicate requirements extend development cycles by 18-24 months for machine learning-driven diagnostic features.
- Disposable Electrochemical Sensor Costs:Continuous glucose monitoring strips and calibration membranes rely on platinum and glucose oxidase enzymes with volatile commodity pricing.
Strategic Opportunities
- Germany DiGA Fast-Track:Digital Health Applications approval pathways enable prescription reimbursement for validated wearable therapeutics within 90 days of submission.
- Post-Acute Respiratory Monitoring:Pulse oximetry integration with hospital-at-home programs addresses CMS readmission penalty incentives for COPD and pneumonia recovery protocols.
- Bluetooth Low Energy 5.3 Convergence:Mesh networking with ambient IoT sensors enables whole-home health monitoring without smartphone tethering.
Industry Challenges
- Firmware-Hardware Co-Validation:FDA requires simultaneous verification of sensor hardware and algorithmic outputs, doubling documentation burden for iterative software updates.
- Clinical Data Science Talent Scarcity:Wearable manufacturers compete with pharmaceutical and health IT sectors for algorithm validation specialists with regulatory submission experience.
- Legacy EHR Integration Friction:HL7 FHIR interoperability gaps force custom API development for each hospital system deployment, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Smart Wearable Devices Market |
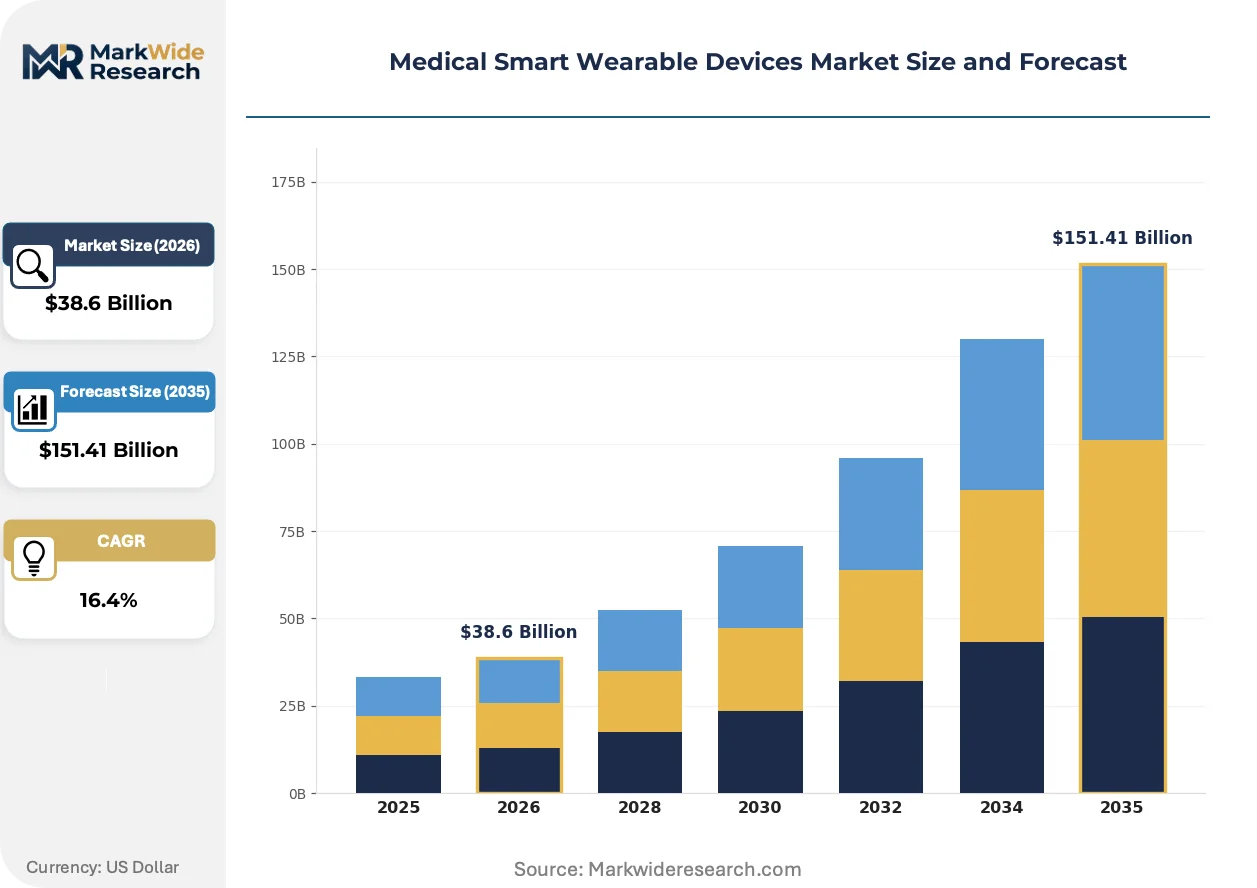
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, ECG Monitors, Pulse Oximeters Technology: Biosensors, RFID, Bluetooth, NFC Application: Chronic Disease Management, Vital Signs Monitoring, Health Tracking, Telemedicine End User: Patients, Healthcare Providers, Fitness Enthusiasts, Researchers |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Fitbit, Abbott, Medtronic, Dexcom, Inc., OMRON Healthcare, Inc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Smart Wearable Devices Market Trends and Innovations
Edge computing architectures are redistributing analytic workloads from cloud servers to body-worn processors, enabling real-time clinical decision support without connectivity dependency.
Photoplethysmography signal processing is decentralizing cardiovascular monitoring from clinic-based electrocardiography to continuous wrist-worn detection. Cardiology departments at US academic medical centers now prescribe Apple Watch and Samsung Galaxy Watch ECG features for atrial fibrillation surveillance. This shift compresses diagnostic latency from symptomatic episodes to subclinical arrhythmia capture.
The EU Medical Device Regulation (MDR) Class IIa reclassification of software-driven diagnostic wearables imposes notified body conformity assessment on previously self-certified devices. Manufacturers must submit clinical evaluation reports and post-market surveillance protocols before CE marking. German and French distributors report 12-18 month approval delays for glucose monitoring patches that previously entered under general wellness exemptions.
Hospital procurement committees now require outcome-based contracting for remote patient monitoring deployments, tying vendor payments to readmission reduction metrics rather than device shipment volumes. US health systems in Texas and Florida pilot risk-sharing arrangements where wearable manufacturers bear financial exposure for failed clinical endpoints. This restructures RFP evaluation criteria toward algorithmic accuracy guarantees and integration service capabilities.
Medical Smart Wearable Devices Market Segmentation
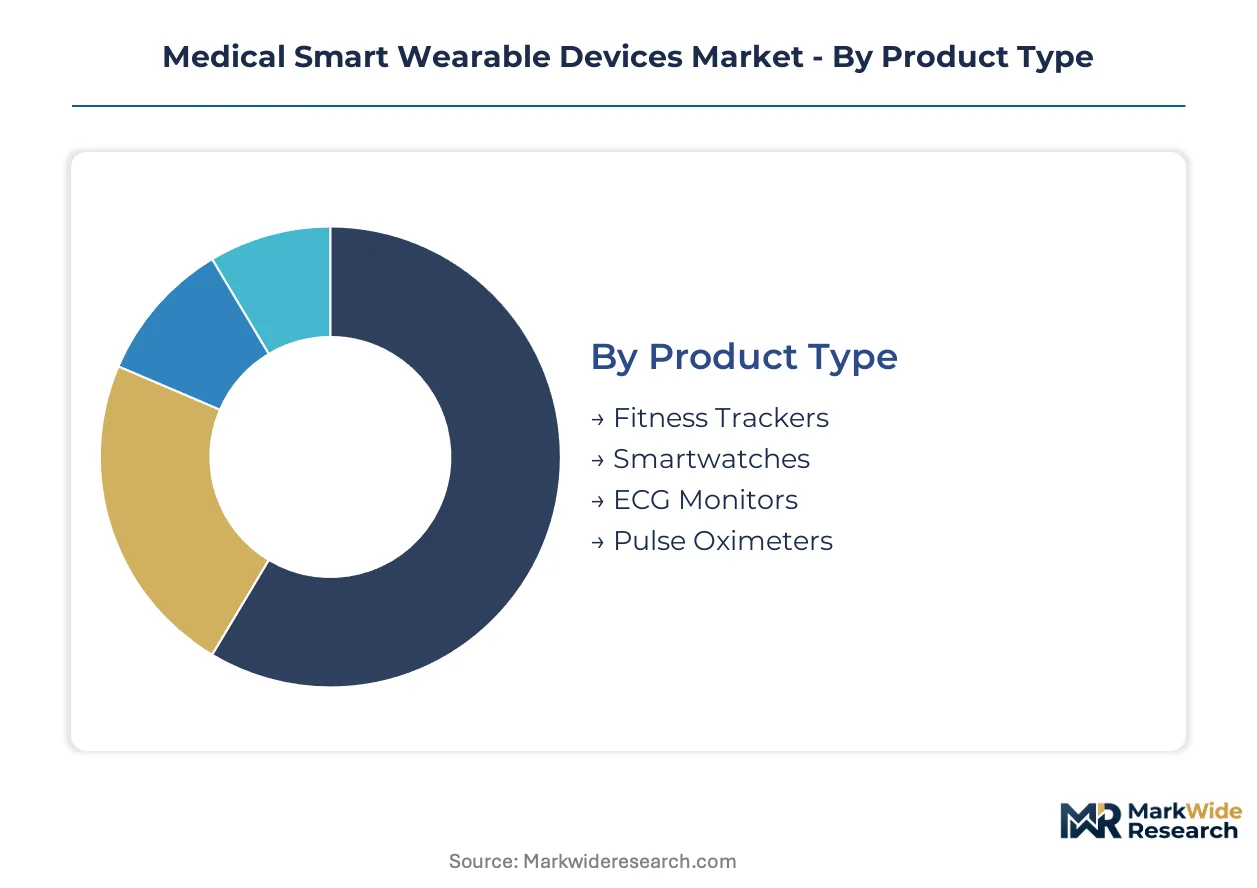
Medical smart wearable segmentation reveals how hardware form factors, wireless protocols, clinical applications, and user populations create distinct monetization pathways. Each axis carries different regulatory burdens, reimbursement eligibility, and margin profiles that shape vendor portfolio strategy.
Product Type:
Form factor specifications determine power budgets, sensor payload capacity, and FDA classification pathways.
- Smartwatches:Multi-sensor platforms integrate photoplethysmography, accelerometry, and ECG electrodes within 100-milliwatt power envelopes. US health systems in Texas and Florida now prescribe Apple Watch and Samsung Galaxy Watch for atrial fibrillation surveillance, with Medicare CPT codes creating direct reimbursement pathways.
- ECG Monitors:Single-lead and multi-lead chest-worn devices capture diagnostic-grade electrical signals exceeding wrist-worn accuracy thresholds. Hospital procurement committees mandate clinical-grade algorithmic outputs before contract approval, compressing vendor margins through outcome-based contracting requirements.
- Fitness Trackers:Accelerometer-dominant devices target step counting and sleep staging with minimal regulatory overhead.
- Pulse Oximeters:Photoplethysmography-based SpO2 monitoring addresses post-acute respiratory tracking for COPD and pneumonia recovery protocols.
Smartwatches lead on scale; pulse oximeters lead on momentum.
Technology:
Communication and sensing protocols create differentiation barriers that standard modules cannot replicate.
- Biosensors:Proprietary optical and electrochemical designs using photoplethysmography and glucose oxidase enzymes underpin margin concentration. Dexcom dominates diabetes wearables through precision calibration of continuous glucose monitoring strips, though platinum and enzyme commodity pricing introduces cost volatility.
- Bluetooth:Low Energy 5.3 mesh networking enables whole-home health monitoring without smartphone tethering, expanding addressable use cases beyond acute care.
- RFID:Passive and active radio-frequency identification supports inventory tracking and patient identification in clinical workflows.
- NFC:Near-field communication protocols facilitate secure pairing and payment integration in consumer-facing devices.
Biosensors command premium pricing; Bluetooth expands fastest through interoperability mandates.
Application:
Clinical use case intensity determines regulatory classification and reimbursement eligibility.
- Chronic Disease Management:Continuous physiologic monitoring for diabetes, heart failure, and hypertension now embeds wearable-generated data into hospital care protocols. FDA software-as-medical-device validation requirements extend development cycles by 18-24 months for algorithm-driven diagnostic features.
- Vital Signs Monitoring:Real-time capture of heart rate, blood pressure, respiratory rate, and temperature supports early warning systems in hospital-at-home programs.
- Health Tracking:Consumer wellness applications operate under general wellness exemptions with minimal regulatory burden.
- Telemedicine:Remote consultation platforms integrate biometric streams to support virtual clinical encounters.
Chronic disease management captures the highest reimbursement rates; vital signs monitoring shows steepest expansion trajectory.
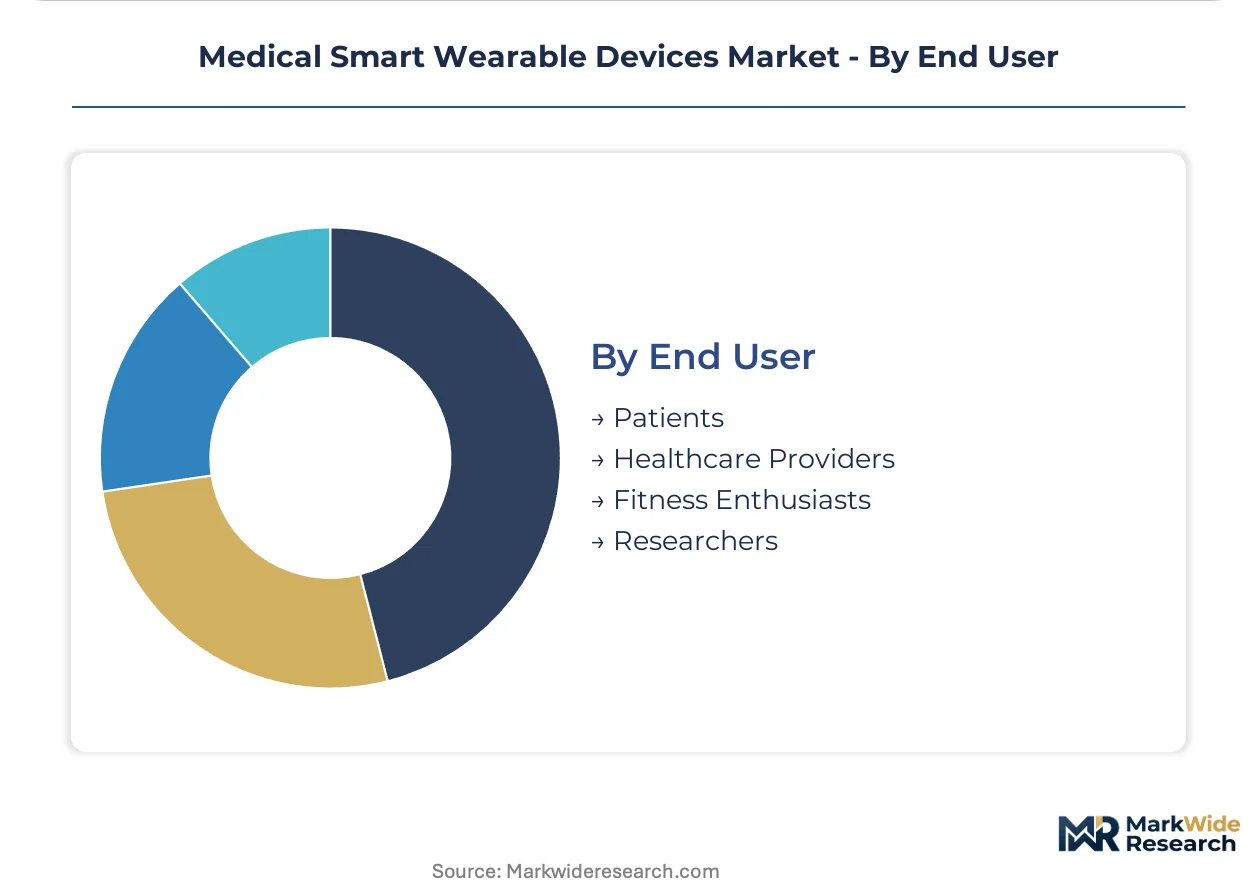
End User:
Customer type dictates purchasing authority, price sensitivity, and data governance requirements.
- Healthcare Providers:Hospital systems and physician groups drive procurement of clinical-grade devices with outcome-based contracting. HL7 FHIR interoperability gaps force custom API development for each deployment, inflating implementation costs.
- Patients:Direct-to-consumer purchases concentrate in the United States, Germany, and Japan where reimbursement frameworks for remote patient monitoring have matured.
- Fitness Enthusiasts:Wellness-oriented consumers prioritize form factor and battery life over clinical accuracy.
- Researchers:Academic medical centers and pharmaceutical sponsors demand raw data access and protocol flexibility for clinical trial endpoints.
Healthcare providers dominate contract value; patients represent the largest installed base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's DiGA fast-track pathway accelerates prescription reimbursement faster than FDA validation timelines in the United States. Japan's PMDA streamlines approvals for designated remote monitoring devices, creating regulatory arbitrage opportunities for multi-market manufacturers.
United States
Medicare CPT codes for continuous physiologic monitoring create direct revenue pathways for health systems deploying body-worn biosensors. FDA software-as-medical-device regulations tighten validation requirements for algorithm-driven diagnostics, extending development cycles. Texas and Florida health systems pilot outcome-based contracting where wearable manufacturers bear financial exposure for failed clinical endpoints.
Germany
The DiGA fast-track approval enables prescription reimbursement for validated wearable therapeutics within 90 days of submission. EU Medical Device Regulation Class IIa reclassification imposes notified body conformity assessment on previously self-certified devices. Berlin and Munich host hospital procurement committees mandating clinical-grade algorithmic outputs before contract approval.
Japan
Designated remote monitoring device approvals accelerate market entry for manufacturers with multi-regulatory submission capabilities. METI frameworks support aging population monitoring through streamlined PMDA pathways. Tokyo and Osaka medical centers integrate wearable-generated data into chronic disease management protocols for diabetes and heart failure surveillance.
United Kingdom
NHS long-term plan commitments embed remote patient monitoring into chronic disease management pathways. MHRA post-Brexit regulatory divergence creates submission complexity for EU-registered devices. London and Cambridge clusters concentrate health tech startups developing photoplethysmography signal processing for atrial fibrillation detection.
China
NMPA Class II medical device registrations expand for continuous glucose monitoring and ECG wearable systems. MIIT standards for wearable device data security impose localization requirements for cloud-connected health analytics. Shenzhen and Beijing manufacturing hubs concentrate optical biosensor foundry capacity for domestic and export markets.
Medical Smart Wearable Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated technology companies commanding consumer-facing channels while medical device incumbents dominate clinical procurement. Market structure concentrates around three strategic archetypes: consumer technology platforms leveraging hardware-software integration, specialized biosensor manufacturers with proprietary calibration IP, and diversified medical device conglomerates with hospital system relationships. Competitive moves center on algorithm validation partnerships with academic medical centers and outcome-based contracting pilots with Medicare Advantage plans.
Among ecosystem-integrated technology platforms, Apple Inc. and Samsung Electronics occupy positions spanning consumer wellness through clinical-grade monitoring, while Dexcom, Inc. exemplifies specialized biosensor dominance through precision calibration capabilities in diabetes management. These three anchors represent distinct competitive vectors: consumer platform scale, semiconductor-biosensor integration, and disease-specific therapeutic focus.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Fitbit |
| Abbott |
| Medtronic |
| Dexcom, Inc. |
| OMRON Healthcare, Inc. |
| Koninklijke Philips N.V. |
| Others |
Pricing and Supply Chain Analysis
Platinum spot prices and glucose oxidase enzyme commodity benchmarks cascade through continuous glucose monitoring strip manufacturing into tiered device economics, compressing margins for electrochemical sensor producers while concentrating pricing power with vertically integrated biosensor foundries in Taiwan and South Korea.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for ultra-low-power biosensor ASICs. Three-tier pricing structure across premium clinical-grade, standard wellness, and economy fitness bands separates FDA-cleared diagnostic outputs from general wellness exemptions. Cost compression in the standard tier intensifies because photoplethysmography modules commoditize faster than electrochemical glucose sensors. Hospital procurement committees exhibit the lowest price sensitivity due to outcome-based contracting mandates, while direct-to-consumer fitness enthusiasts drive the steepest discounting pressure.
Supply Chain Analysis
Biomedical engineering talent scarcity in Shenzhen and Taipei strains foundry expansion timelines for optical sensing module production. Taiwan, South Korea, and China anchor semiconductor fabrication for photoplethysmography chips, electrochemical glucose sensors, and Bluetooth Low Energy controllers. Raw material flows draw from platinum catalyst suppliers, indium gallium arsenide photodetectors, and glucose oxidase enzyme refiners. Single-source vulnerability concentrates in Taiwan's 12-inch specialty foundry capacity for ultra-low-power biosensor ASICs. Distribution runs through hospital GPO contracts, direct-to-consumer e-commerce platforms, and pharmacy retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA software-as-medical-device validation timelines and Medicare CPT code expansions create accelerating returns for algorithm-validated vendors.
For Market Incumbents: Hedge against algorithm commoditization by deepening proprietary calibration IP for electrochemical biosensors while securing multi-year platinum supply agreements to buffer commodity volatility. FDA predicate pathway extensions threaten machine-learning diagnostic feature roadmaps; defend through pre-submission meetings and simulated clinical validation cohorts. Vertical integration into Taiwan foundry partnerships reduces single-source ASIC exposure. For New Entrants and Emerging Players: Launch via Germany's DiGA fast-track pathway to capture prescription reimbursement within 90-day regulatory windows, bypassing FDA's 18-24 month software validation cycles. White-space concentrates in post-acute respiratory monitoring for hospital-at-home programs and Bluetooth Low Energy 5.3 mesh-enabled whole-home health ecosystems. Target academic medical center algorithm co-development partnerships to establish clinical credibility before enterprise sales. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized biosensor manufacturers possessing proprietary optical calibration IP and multi-regulatory submission capabilities. Five-to-ten year viability favors vendors with locked hospital system relationships and recurring SaaS revenue from algorithm-driven diagnostic outputs. Watch FDA breakthrough device designation grants for atrial fibrillation and glucose prediction algorithms as inflection signals for reimbursement velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Unlocks Medicare CPT reimbursement pathways for algorithm-driven diagnostic wearables in US health systems. |
| CE Marking Pathway Under EU MDR | Enables German DiGA fast-track access and prescription reimbursement across European hospital networks. |
| Hospital System Partnership | Secures outcome-based contracting pilots with readmission reduction guarantees in Texas and Florida markets. |
| Software Companion Development | Integrates HL7 FHIR-compliant analytics platforms with Epic and Cerner EHR deployments. |
| Reimbursement Strategy | Aligns wearable therapeutic claims with CMS remote therapeutic monitoring code expansions for chronic disease management. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement committees, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR notified body registers; plus customs trade data for biosensor component flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured algorithm validation timelines, foundry capacity constraints, and health system integration cost structures. Secondary sources included hospital procurement databases, PMDA approval tracking, and semiconductor equipment capex disclosures from Taiwan and South Korea.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including device form factor, biosensor technology type, clinical application intensity, and end-user purchasing authority. CAGRs were derived from installed base expansion rates, reimbursement code adoption curves, and foundry capacity buildout schedules. Industry-specific forecast inputs incorporated photoplethysmography accuracy validation studies, platinum price volatility scenarios, and HL7 FHIR interoperability penetration across US health systems.
Several conditions sit outside the modeled scope, including sudden FDA guidance revisions for machine-learning diagnostic algorithms, Taiwan semiconductor export restrictions, and platinum supply disruptions from South African mining operations. Forecasts reflect documented assumptions regarding reimbursement code stability and foundry yield improvements. Material deviation in FDA validation timelines, CMS remote monitoring coverage decisions, or Taiwan specialty foundry capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Centesis Catheters Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Laryngoscopes Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Spinal Implant Market
Medical Devices
Asthma Device Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
3D Medical Imaging Devices Market