
 Global Hammertoe Market | 2026-2036
Global Hammertoe Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hammertoe Market Foresight
ISO 13485 certification is redrawing competitive boundaries in hammertoe device manufacturing, forcing smaller suppliers to upgrade quality management systems or exit. Stryker Corporation leverages its orthopedic implant infrastructure to dominate premium fixation hardware. Integra LifeSciences Corporation anchors its position through specialized soft-tissue repair matrices for toe deformity correction. Arthrex, Inc. competes by extending its sports medicine distribution network into podiatric surgery centers.
Hammertoe refers to a flexion deformity of the proximal interphalangeal joint, typically treated through proximal interphalangeal joint arthroplasty or arthrodesis using titanium or stainless steel implants with specific thread pitches for cortical bone engagement. The condition arises from intrinsic muscle imbalance and progressive MTP joint instability, driving clinical intervention across corrective surgery and conservative management pathways. Corrective surgery commands the highest value per procedure, while preventive care through orthotic inserts captures the largest patient volume base. Rehabilitation applications are expanding fastest as postoperative protocols standardize across podiatry centers and sports medicine providers.
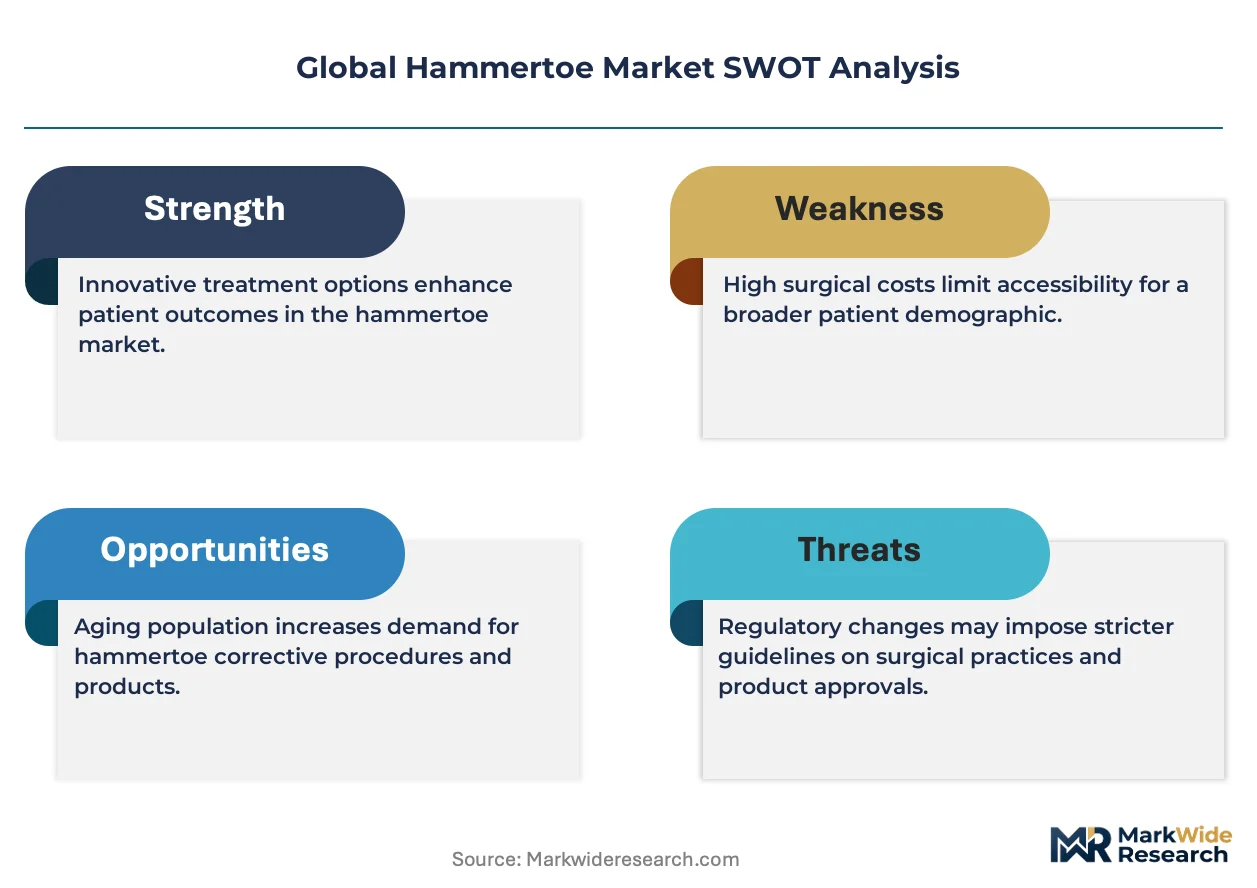
FDA premarket notification requirements and the EU Medical Device Regulation (MDR) are elevating clinical evidence thresholds for hammertoe implants, extending development timelines and favoring established manufacturers with regulatory affairs capacity. The European Medicines Agency (EMA) and notified body oversight under MDR Article 52 are reshaping market access for Class IIa and IIb orthopedic devices. Stakeholders must monitor evolving reimbursement codes for minimally invasive toe procedures and position portfolio investments around ambulatory surgery center adoption curves.
Market Dynamics
FDA premarket notification pathways and EU MDR Article 52 requirements are compressing development timelines for implantable toe fixation devices, forcing manufacturers to front-load clinical evidence generation or cede position to established orthopedic conglomerates.
Growth Catalysts
- EU MDR compliance deadlines:Class IIa and IIb orthopedic device reclassification is accelerating consolidation toward ISO 13485-certified manufacturers with notified body relationships.
- Ambulatory surgery center expansion:United States podiatric procedure migration to outpatient settings is driving demand for single-use disposable fixation kits and streamlined instrument trays.
- Titanium porous coating advances:Enhanced osseointegration surfaces are extending implant longevity and expanding arthrodesis candidacy to younger patient demographics.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese raw material dominance creates input cost volatility for implant-grade titanium billet.
- Technical limitation in soft-tissue balancing:Persistent recurrence rates following proximal interphalangeal joint arthroplasty limit conservative-to-surgical conversion rates.
- Reimbursement compression:CMS physician fee schedule adjustments for CPT 28285 are narrowing procedure margins in United States Medicare populations.
Strategic Opportunities
- German orthopedic clinic networks:Minimally invasive hammertoe correction service expansion in Bavaria and Baden-Württemberg creates premium positioning for fixation hardware with reduced soft-tissue trauma profiles.
- Patient-specific instrumentation:3D-printed surgical guides converging with preoperative CT planning are enabling reproducible joint preparation in community hospital settings.
- Japan PMDA fast-track pathway:Breakthrough designation for novel implantable devices with superior biomechanical performance is accelerating market access for innovative fixation constructs.
Industry Challenges
- Podiatric surgical training pipeline:Fellowship slot scarcity in United States academic medical centers is constraining qualified surgeon availability for complex deformity reconstruction.
- ISO 13485 certification timeline:Notified body backlog extending quality management system audit intervals is delaying product launch schedules for emerging manufacturers.
- Legacy implant retrieval:Revision surgery instrumentation incompatibility with first-generation stainless steel constructs complicates salvage procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hammertoe Market |
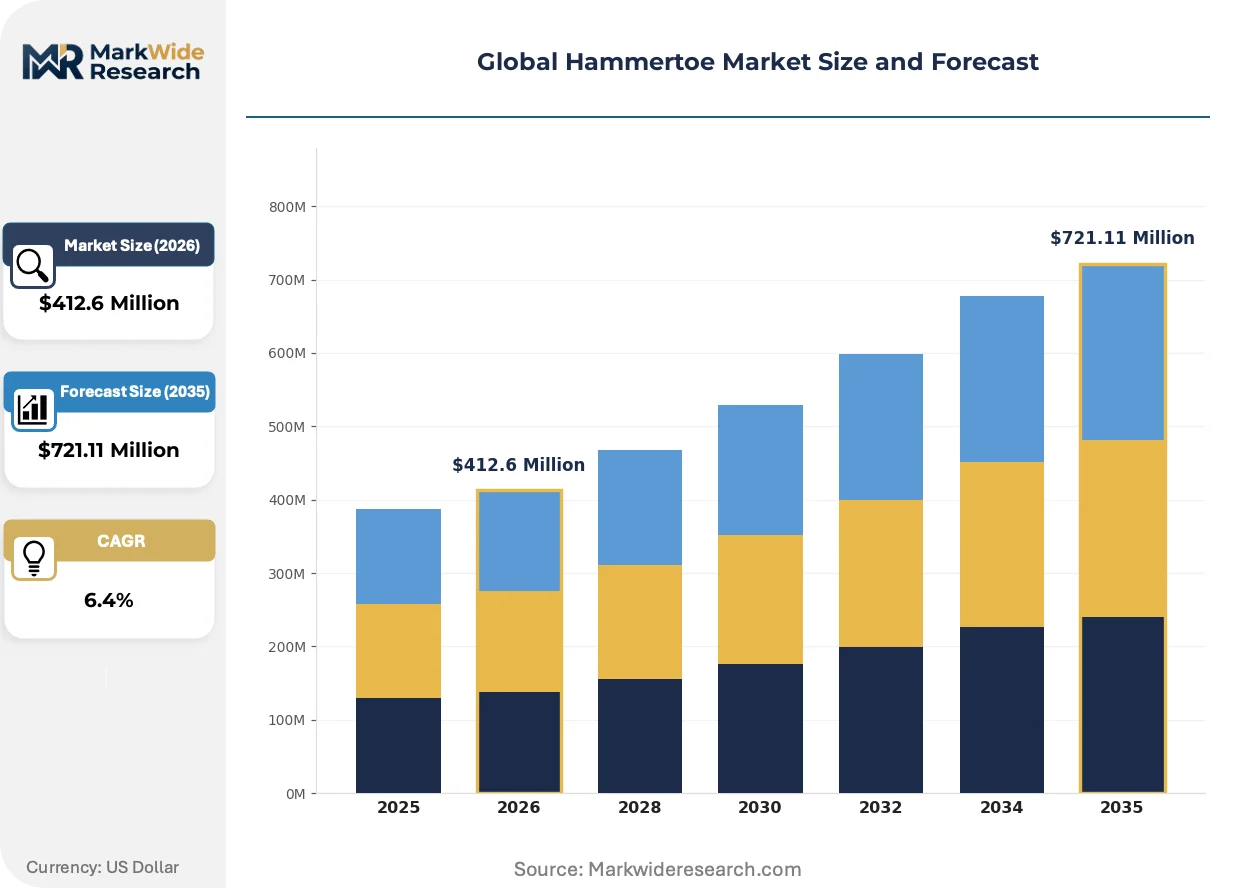
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Inserts, Toe Caps, Splints, Exercise Bands, Support Braces Application: Corrective Surgery, Physical Therapy, Pain Management, Rehabilitation, Preventive Care End User: Specialty Clinics, Podiatry Centers, Rehabilitation Facilities, Sports Medicine Providers Distribution Channel: Online Retailers, Medical Device Distributors, Pharmacies, Orthopedic Stores, Direct Hospital Supply |
| Companies Covered | Arthrex, Inc., Wright Medical Group N.V., Stryker Corporation, Extremity Medical LLC, Integra LifeSciences Corporation, Smith+Nephew Plc, Paragon 28, Inc., Nextremity Solutions, Inc., Zimmer Biomet Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hammertoe Market Shifts & Advancements
Implantable fixation technology is converging with digital surgical planning and disposable instrumentation, compressing traditional hardware-instrument service models while elevating precision requirements.
Smart compression screw systems with integrated strain sensors are miniaturizing real-time biomechanical feedback into implantable toe fixation hardware. Podiatric surgery centers in the United States are piloting these devices for immediate postoperative load-bearing protocols. The technology is miniaturizing the gap between arthrodesis and arthroplasty outcomes by enabling personalized fixation tensioning.
EMA notified body oversight under EU MDR Article 52 is elevating clinical evidence thresholds for Class IIb orthopedic implants entering European markets. Manufacturers must now submit prospective registry data rather than predicate-device equivalency for novel fixation geometries. German and French orthopedic distributors are prioritizing suppliers with established MDR technical documentation to secure supply continuity.
Direct-to-facility procurement of sterile-packed procedure kits is displacing traditional instrument tray reprocessing models in United States ambulatory surgery centers. Podiatric service lines are unbundling implant costs from facility fees to capture transparent pricing advantages. This shift is most visible in Texas and Florida markets where surgery center joint ventures dominate outpatient foot and ankle volumes.
Global Hammertoe Market Segmentation
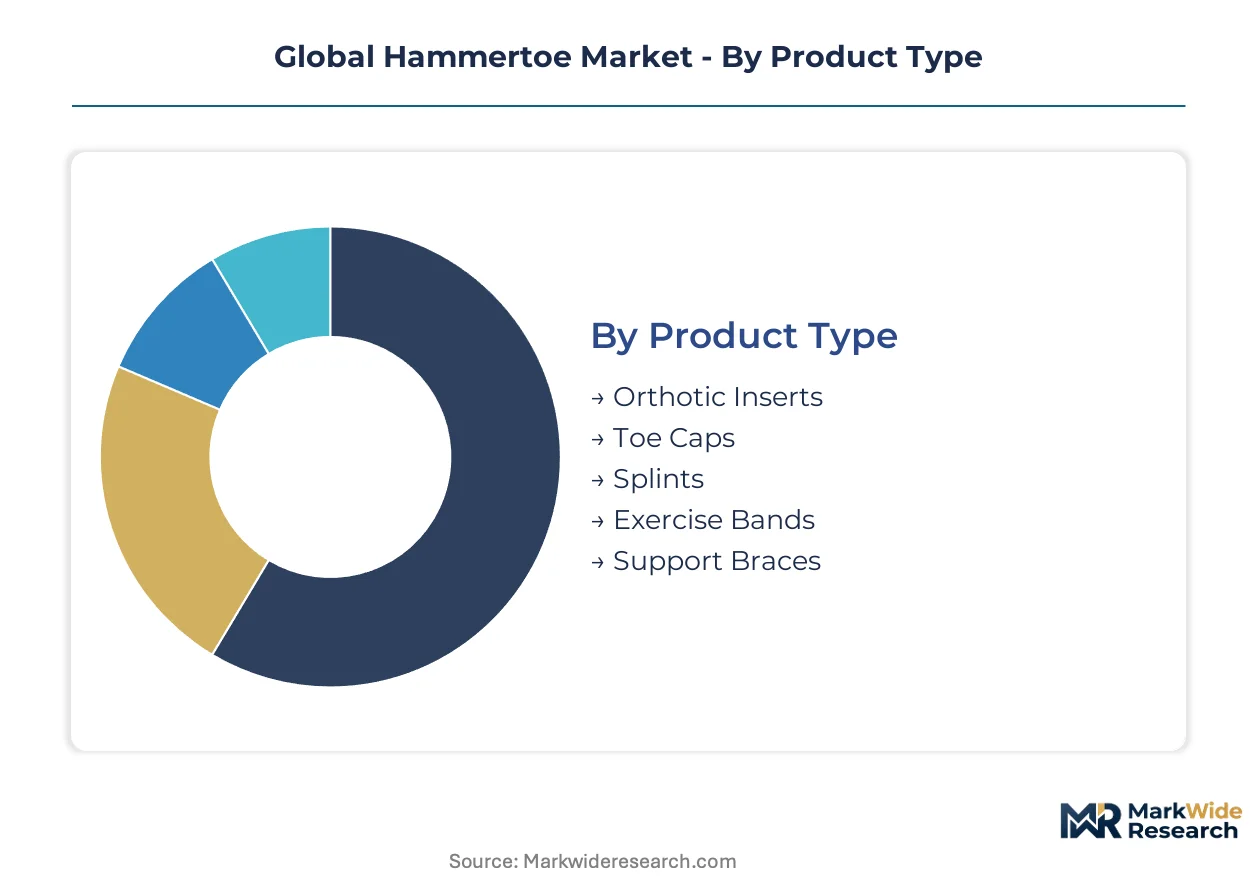
Segmentation in hammertoe care separates commodity consumables from premium implantable hardware, with distribution channel choices determining margin capture and regulatory burden. Product type and application splits reveal where orthopedic conglomerates concentrate versus where generic suppliers compete.
Product Type:
Channel-mix patterns diverge sharply: retail-accessible segments flow through pharmacies and online retailers, while implantable fixation hardware moves exclusively through medical device distributors with ISO 13485-certified supply chains.
- Orthotic Inserts:Custom-molded and prefabricated polypropylene or EVA devices redistribute plantar pressure and delay surgical progression. German orthopedic clinics and United States podiatry centers drive demand for prescription-grade variants with biomechanical posting. Retail pharmacy chains capture volume for off-the-shelf versions.
- Support Braces:Dynamic splinting systems with adjustable tension mechanisms maintain corrected toe alignment postoperatively. Sports medicine providers in Japan and rehabilitation facilities across Texas and Florida are standardizing procurement of disposable brace kits for ambulatory surgery center discharge protocols.
- Toe Caps:Silicone gel sleeves protect dorsal prominences from footwear friction in mild deformity stages.
- Splints:Rigid and semi-rigid aluminum or foam positioning devices maintain extension during conservative treatment windows.
- Exercise Bands:Latex resistance bands target intrinsic muscle strengthening for early-stage deformity management.
Orthotic Inserts dominate installed base. Support Braces are where expansion concentrates.
Application:
Cost tier stratification places Corrective Surgery at premium pricing with implantable hardware, while Preventive Care operates at economy margins with high turnover of consumable devices.
- Corrective Surgery:Proximal interphalangeal joint arthrodesis and arthroplasty procedures utilizing titanium or stainless steel implants command highest value per intervention. United States ambulatory surgery centers and German orthopedic clinic networks are the primary demand concentrations, with CMS reimbursement codes and statutory health insurance coverage determining access.
- Preventive Care:Early intervention through orthotic devices and footwear modification captures the largest patient volume base. Retail pharmacy chains in Japan and direct-to-consumer online channels in the United States are expanding access points for prefabricated solutions.
- Physical Therapy:Structured mobilization protocols address postoperative stiffness and intrinsic muscle retraining.
- Pain Management:Topical and oral analgesic adjuncts support conservative treatment pathways.
- Rehabilitation:Postoperative protocol standardization across podiatry centers is accelerating demand for coordinated brace and therapy device procurement.
Corrective Surgery anchors revenue concentration. Preventive Care is climbing the fastest in patient touchpoints.
End User:
Customer type fragmentation shows Specialty Clinics and Podiatry Centers demanding premium fixation hardware, while Rehabilitation Facilities prioritize cost-efficient consumable bundles.
- Podiatry Centers:United States-based surgical practices perform the highest volumes of implantable toe procedures, with fellowship-trained specialists driving adoption of patient-specific instrumentation. Texas and Florida markets show particular concentration of ambulatory surgery center joint ventures.
- Specialty Clinics:German orthopedic clinic networks in Bavaria and Baden-Württemberg are expanding minimally invasive hammertoe correction services, creating premium positioning for reduced soft-tissue trauma hardware profiles.
- Rehabilitation Facilities:Postoperative care standardization is expanding fastest as protocols converge across sports medicine and podiatric discharge planning.
- Sports Medicine Providers:Athletic patient demographics with early-onset deformities drive demand for motion-preserving arthroplasty over arthrodesis.
Podiatry Centers dominate procedural volume. Specialty Clinics are gaining share fastest in premium hardware adoption.
Distribution Channel:
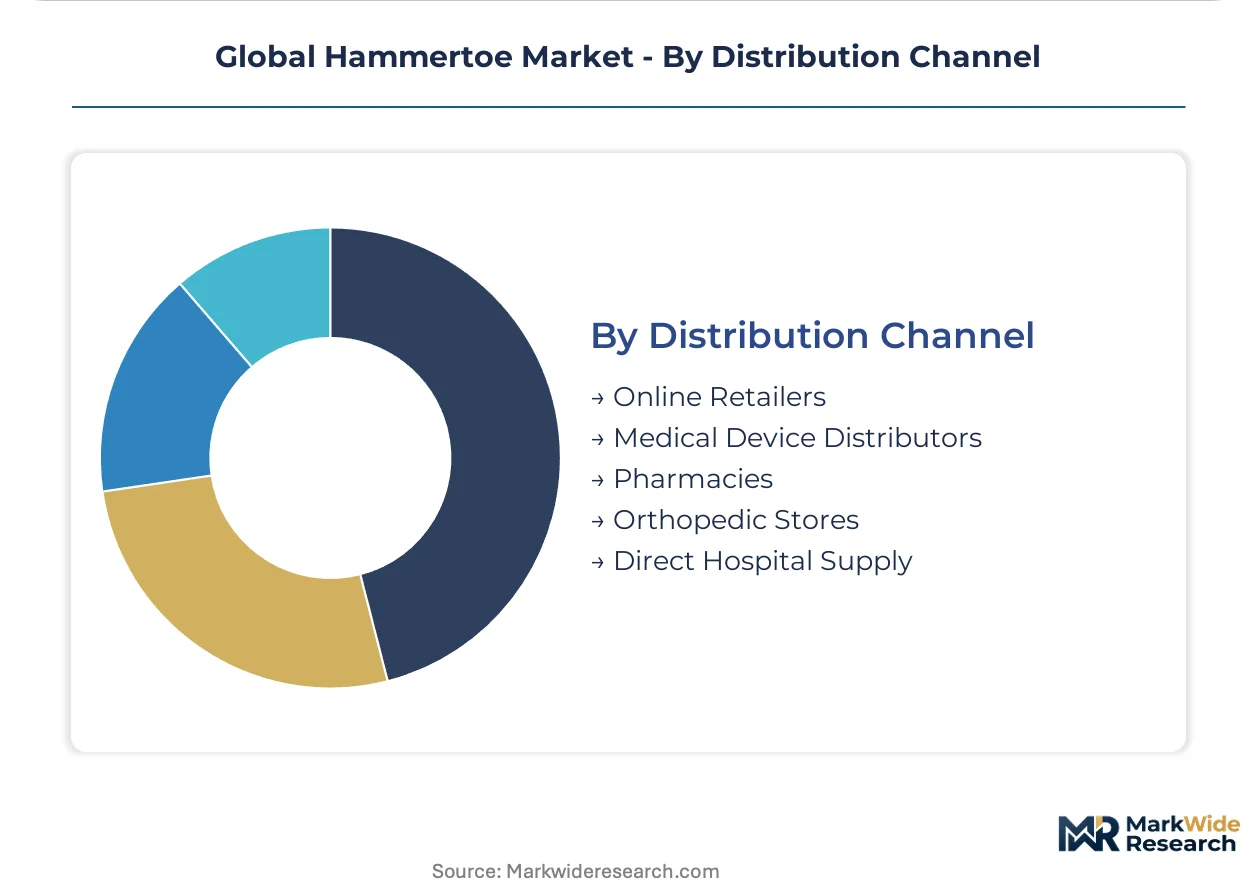
Supply concentration favors established medical device distributors with ISO 13485 certification and notified body relationships, while direct hospital supply contracts are displacing traditional instrument tray reprocessing.
- Medical Device Distributors:Specialized orthopedic supply networks with EMA notified body relationships and FDA establishment registration dominate implantable hardware flow. German and French distributors are prioritizing MDR technical documentation completeness to secure supply continuity.
- Direct Hospital Supply:Sterile-packed procedure kits are unbundling implant costs from facility fees in United States ambulatory surgery centers, with Texas and Florida markets leading transparent pricing adoption.
- Online Retailers:Direct-to-consumer channels capture preventive care device volume with minimal regulatory overhead.
- Pharmacies:Retail chains stock prefabricated orthotic and toe cap solutions for early-stage patient self-selection.
- Orthopedic Stores:Specialty retail provides fitting services for custom-molded orthotic devices.
Medical Device Distributors dominate implantable hardware flow. Direct Hospital Supply is where procurement pattern disruption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Podiatric surgery volumes concentrate in the United States, where ambulatory surgery center joint ventures in Texas and Florida drive implantable hardware procurement. German orthopedic clinic networks in Bavaria and Baden-Württemberg are expanding minimally invasive correction services. Japanese sports medicine providers and rehabilitation facilities are standardizing postoperative brace protocols.
United States
Fellowship-trained specialists in Texas and Florida perform the highest volumes of implantable toe procedures, with ambulatory surgery center joint ventures capturing transparent pricing advantages. FDA premarket notification pathways for Class II orthopedic devices are tightening clinical evidence requirements. Dallas-Fort Worth and Miami-Dade surgical corridors are unbundling implant costs from facility fees to secure supply chain leverage.
Germany
Orthopedic clinic networks in Bavaria and Baden-Württemberg are expanding minimally invasive hammertoe correction services, creating premium positioning for reduced soft-tissue trauma hardware. EU MDR Article 52 reclassification of Class IIa and IIb devices is accelerating consolidation toward ISO 13485-certified manufacturers. Munich and Stuttgart surgical centers are prioritizing suppliers with established EMA notified body relationships to secure supply continuity.
Japan
Sports medicine providers in Kanto and Kansai regions are driving demand for motion-preserving arthroplasty over arthrodesis in athletic patient demographics. PMDA fast-track pathways for novel implantable devices with superior biomechanical performance are accelerating market access for innovative fixation constructs. Tokyo and Osaka rehabilitation facilities are standardizing procurement of disposable brace kits for postoperative discharge protocols.
United Kingdom
Podiatric surgery centers in London and the Southeast are migrating procedures to outpatient settings, compressing traditional hardware-instrument service models. MHRA convergence with EU MDR technical documentation requirements is elevating quality management system standards for imported fixation devices. Greater Manchester and West Midlands NHS trusts are piloting patient-specific instrumentation with 3D-printed surgical guides.
France
Orthopedic distributors in Île-de-France are prioritizing MDR technical documentation completeness to secure supply continuity for implantable hardware. ANSM oversight of Class IIb orthopedic devices is reshaping market access pathways for novel fixation geometries. Paris and Lyon surgical networks are converging digital surgical planning with disposable instrumentation to elevate precision requirements.
Global Hammertoe Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with established regulatory affairs capacity and ISO 13485-certified supply chains. Consolidation pressure is compressing development timelines for emerging manufacturers unable to front-load clinical evidence generation. Three strategic archetypes dominate: premium fixation hardware specialists, soft-tissue repair matrix providers, and sports medicine distribution extenders. Dominant competitive moves include strategic partnerships with ambulatory surgery center networks and portfolio diversification into patient-specific instrumentation.
Within the premium-tier vector, Stryker Corporation and Zimmer Biomet Holdings, Inc. occupy positions anchored by orthopedic implant infrastructure and scale-driven manufacturing capacity. Integra LifeSciences Corporation exemplifies the soft-tissue specialization archetype, while Arthrex, Inc. represents distribution network extension into podiatric surgery centers. Smith+Nephew Plc and Wright Medical Group N.V. sit within the mid-tier consolidation zone, with Extremity Medical LLC and Paragon 28, Inc. occupying positions as extremity-focused specialists. Nextremity Solutions, Inc. represents the emerging manufacturer archetype navigating ISO 13485 certification timelines and notified body backlogs.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Wright Medical Group N.V. |
| Stryker Corporation |
| Extremity Medical LLC |
| Integra LifeSciences Corporation |
| Smith+Nephew Plc |
| Paragon 28, Inc. |
| Nextremity Solutions, Inc. |
| Zimmer Biomet Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at ISO 13485-certified titanium forging facilities in Germany and the United States shapes price floors across implantable fixation hardware, concentrating supply leverage among orthopedic conglomerates with captive billet sourcing while compressing margins for second-tier manufacturers dependent on spot-market titanium sponge.
Pricing Analysis
Long-term cost-plus contracts with London Metal Exchange-linked titanium sponge indexation dominate procurement between implant manufacturers and raw material suppliers. Three-tier pricing structure across premium, standard, and economy levels separates arthrodesis implants with porous-coated surfaces from bare titanium constructs and stainless steel legacy systems. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification status. Pricing pressure stems from CMS reimbursement compression on CPT 28285 procedures, with Medicare populations showing highest price sensitivity while private-pay ambulatory surgery centers absorb premium hardware premiums.
Supply Chain Analysis
Inventory buffers for implant-grade titanium billet stretch lead times when Russian and Chinese sponge supply faces export restrictions. Manufacturing concentrates in Germany, the United States, and Switzerland for precision-machined fixation hardware. Raw material dependencies center on titanium sponge from Eastern suppliers, surgical-grade stainless steel from European mills, and biocompatible polymer overmolding compounds. Single-source vulnerability in titanium sponge refining creates supply chain risk. Distribution runs through specialized orthopedic distributors with EMA notified body relationships and FDA establishment registration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 52 reclassification of Class IIb orthopedic devices constitutes a regulatory inflection compressing development timelines and elevating clinical evidence thresholds, creating high-growth disruption favoring manufacturers with pre-loaded regulatory affairs capacity.
For Market Incumbents: Compound defensive positioning through backward integration into titanium billet sourcing and accelerated MDR technical documentation investment. Threat from emerging patient-specific instrumentation specialists demands capacity expansion in Bavaria and Baden-Württemberg surgical corridors. Certification leverage serves as the primary consolidation lever against ISO 13485 audit backlog delays. For New Entrants and Emerging Players: Anchor in Japan's PMDA fast-track pathway for novel implantable devices with superior biomechanical performance, the most penetrable regulatory corridor for breakthrough fixation constructs. White-space targets include disposable brace kit standardization in Texas and Florida ambulatory surgery centers. Go-to-market angle centers on direct-to-facility sterile-packed procedure kit procurement bypassing traditional distributor markups. For Investors and Strategic Acquirers: Extremity-focused specialists with established EMA notified body relationships and ambulatory surgery center network partnerships represent the priority acquisition archetype. Long-term viability frames around consolidation into three-pillar orthopedic conglomerates, soft-tissue matrix providers, and sports medicine distribution extenders. Signal to watch is PMDA breakthrough designation velocity as inflection indicator for innovative fixation construct market access.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EMA notified body relationships secure supply continuity for Class IIb orthopedic implants entering German and French markets. |
| Patient-Specific Instrumentation Development | 3D-printed surgical guides with preoperative CT planning enable reproducible joint preparation in community hospital settings. |
| Ambulatory Surgery Center Partnership | Direct-to-facility procurement of sterile-packed kits unbundles implant costs from facility fees in Texas and Florida. |
| Titanium Sponge Backward Integration | Captive billet sourcing insulates against Russian and Chinese raw material supply volatility. |
| Smart Compression Screw Pilot Programs | Integrated strain sensors enable immediate postoperative load-bearing protocols in United States podiatric surgery centers. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings across the hammertoe device landscape. Stakeholder consultations included orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and EMA regulatory affairs specialists. Secondary sources encompass FDA 510(k) premarket notification databases, EMA MDR technical documentation filings, CMS physician fee schedule releases, and hospital procurement contract repositories. Bottom-up procedure volume modeling triangulates against top-down implant manufacturer revenue segmentation.
Sensitivity analysis around titanium sponge price volatility and CMS reimbursement adjustment scenarios frames the forecast envelope. Segmentation dimensions span product type, application pathway, end-user facility category, and distribution channel structure across the projection horizon. CAGRs derive from logistic adoption curve fitting for minimally invasive technique penetration and linear extrapolation for mature arthrodesis hardware replacement cycles. Procedure migration rates to ambulatory surgery centers and ISO 13485 certification timeline assumptions serve as key forecast inputs.
Material uncertainties — EU MDR notified body audit backlog duration, titanium sponge export restriction severity, and fellowship-trained podiatric surgeon pipeline constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and reimbursement stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Pharyngitis Treatment Market