
 Global Neurotrophic Keratitis Treatment Market | 2026-2036
Global Neurotrophic Keratitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurotrophic Keratitis Treatment Market Foresight
Specialty pharmacy distribution for biologic ophthalmic therapies is reshaping how neurotrophic keratitis treatments reach end users, with cold-chain logistics and compounding requirements favoring consolidated channel partners over general retail. Dompé Farmaceutici leverages its European manufacturing base to sustain supply continuity for recombinant protein formulations across EMA-regulated markets. Bausch + Lomb Incorporated competes through its established relationships with corneal specialists and integrated eye health platforms. Santen Pharmaceutical anchors its position in Asia-Pacific through localized regulatory filings and dedicated ophthalmology sales infrastructure.
Neurotrophic keratitis treatment encompasses pharmacological and surgical interventions designed to restore corneal innervation, promote epithelial regeneration, and prevent stromal melting in patients with trigeminal nerve damage or systemic neuropathies. Recombinant human nerve growth factor eye drops, administered at concentrations of 20 mcg/mL, stimulate corneal epithelial cell proliferation and nerve fiber regrowth through TrkA receptor activation, representing the first targeted biologic approved for this indication. Eye drops dominate current prescription volumes due to non-invasive administration and outpatient compatibility, while amniotic membrane grafts command premium positioning in severe neurotrophic ulcers requiring surgical intervention. Sustained release devices represent the fastest-growing delivery mode segment as manufacturers address compliance limitations of frequent topical dosing regimens.
FDA oversight through the Center for Drug Evaluation and Research governs biologic ophthalmic approvals, while EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states, with both agencies mandating rigorous corneal toxicity and sterility standards. Japan's PMDA imposes additional local clinical trial requirements that extend timelines for foreign sponsors seeking access to the world's third-largest pharmaceutical market. Stakeholders must monitor evolving reimbursement coding for neurotrophic keratitis as a distinct indication versus bundled dry eye management, since payer classification decisions will determine commercial viability of premium biologic therapies against established lubricant standards.
Market Dynamics
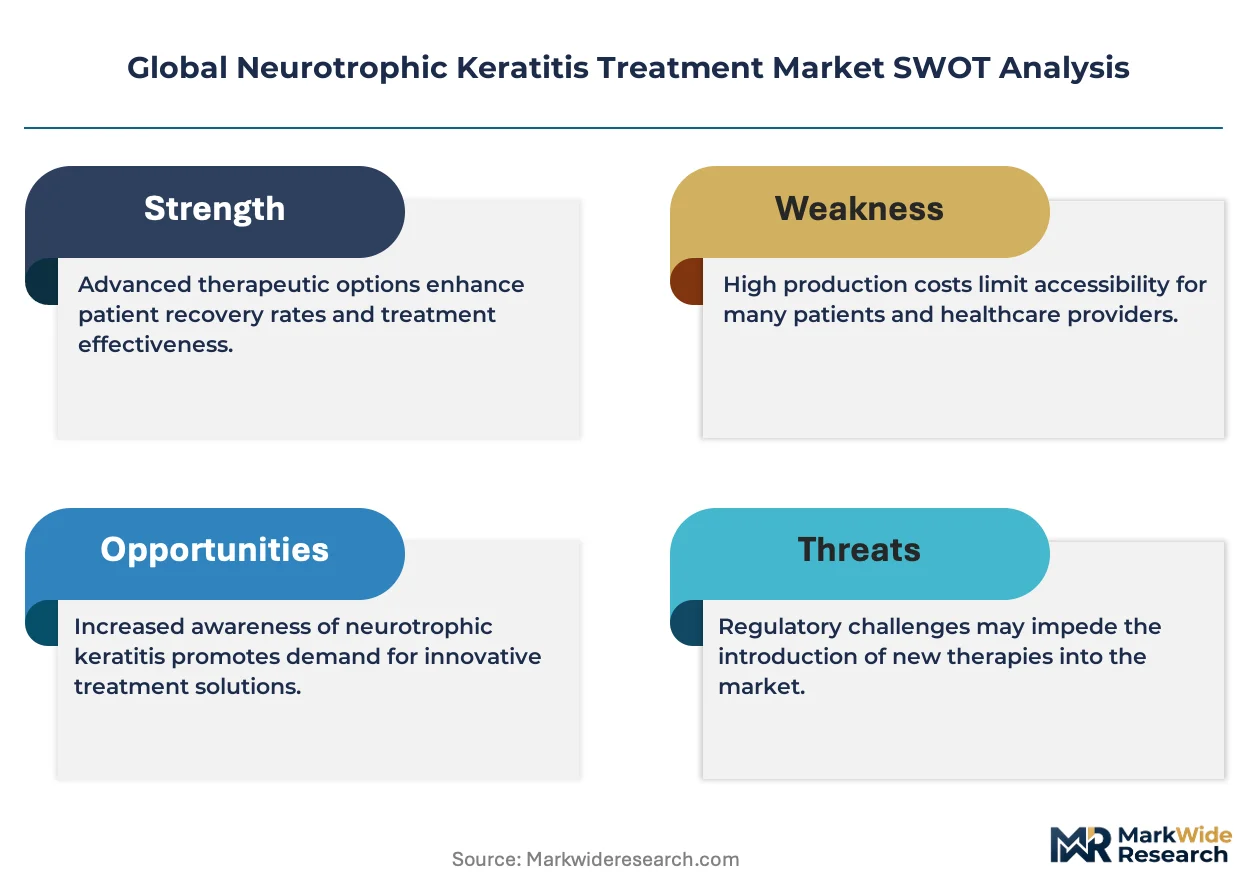
Recombinant biologic therapies are displacing preservative-based lubricants as first-line therapy in Western markets, forcing manufacturers to reconfigure supply chains around cold-chain distribution and specialty pharmacy networks.
Growth Catalysts
- EMA centralized marketing authorizations:Streamlined approval pathways for biologic ophthalmic therapies accelerate patient access across EU member states.
- Diabetic corneal neuropathy:Expanding diabetic patient cohorts create sustained demand for nerve regeneration therapies in tertiary eye centers.
- TrkA receptor activation science:Validated mechanisms of action drive prescriber confidence and payer acceptance of targeted biologics over symptomatic treatments.
Market Restraints
- Recombinant protein production costs:Mammalian cell culture manufacturing for nerve growth factor concentrates supply in limited European facilities.
- PMDA local trial mandates:Japan's requirement for domestic clinical data extends market entry timelines by 24-36 months for foreign sponsors.
- Autologous serum drops:Compounded patient-derived alternatives compete on cost in markets with limited biologic reimbursement.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Emerging market access for biologic ophthalmics remains underpenetrated relative to patient disease burden.
- Sustained-release ocular implants:Convergence of polymer science and microfabrication enables compliance-driven dosing interval extension.
- Teleophthalmology screening networks:Remote corneal sensation testing expands diagnostic reach in rural United States markets.
Industry Challenges
- Corneal toxicology assessment capacity:Specialized preclinical testing facilities face bottlenecks as biologic ophthalmic pipelines expand.
- Cold-chain integrity validation:Temperature excursion documentation requirements complicate multi-modal distribution to satellite clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurotrophic Keratitis Treatment Market |
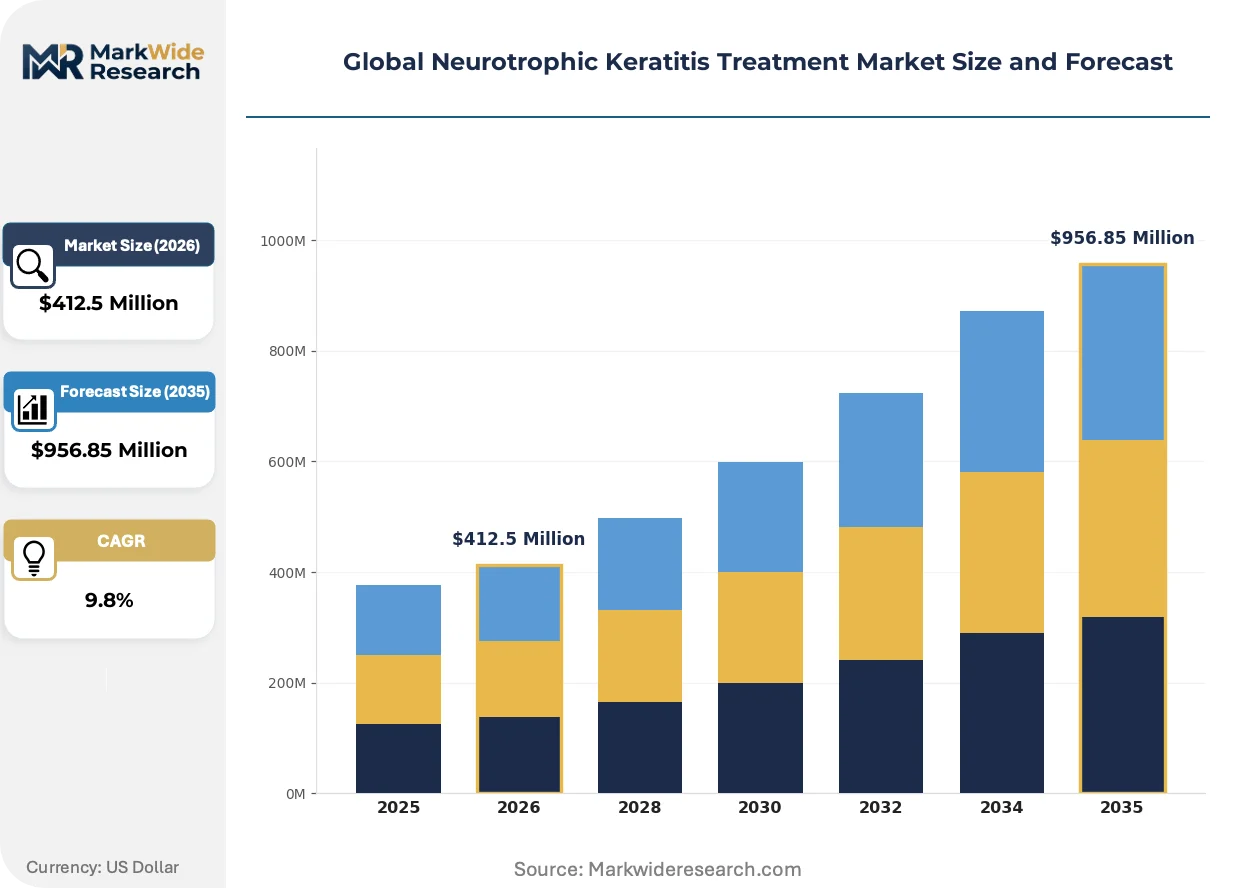
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Drops, Ointments, Contact Lenses, Amniotic Membrane Grafts, Surgical Devices Therapy Area: Corneal Healing, Lacrimal Secretion Enhancement, Neuroregeneration, Inflammation Control, Epithelial Protection End User: Ophthalmology Clinics, Specialty Eye Hospitals, Research Institutes, Ambulatory Surgical Centers Delivery Mode: Topical Administration, Surgical Implantation, Injectable Formulations, Sustained Release Devices |
| Companies Covered | Dompé Farmaceutici, Bausch + Lomb Incorporated, Santen Pharmaceutical, Recordati Rare Diseases, Oyster Point Pharma, ReGenTree, Alcon, Johnson & Johnson Vision, KALA BIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurotrophic Keratitis Treatment Market Shifts & Advancements
Biologic ophthalmic manufacturing is converging with precision medicine platforms, reshaping how therapies are formulated, delivered, and reimbursed across patient risk strata.
Sustained-release ocular inserts combining biodegradable polymers with recombinant protein stabilization are hybridizing conventional drop therapy with implantable delivery. Corneal specialists in German university hospitals are piloting these devices for Stage 2 neurotrophic keratitis patients. This convergence is compressing the boundary between pharmacologic and surgical intervention categories.
EMA's Medical Device Regulation (MDR) reclassification of certain drug-device combination products is triggering additional conformity assessment requirements for novel delivery systems. Manufacturers must now navigate parallel CE marking and pharmaceutical authorization pathways. Combination product sponsors are responding by front-loading clinical evidence generation to support dual regulatory submissions.
Corneal centers are consolidating procurement authority through group purchasing organizations, displacing individual physician prescribing autonomy. Specialty pharmacy networks are capturing patient flow through exclusive distribution agreements with academic medical centers. This concentration is most visible in the United States, where integrated delivery networks now control biologic ophthalmic formulary placement.
Global Neurotrophic Keratitis Treatment Market Segmentation
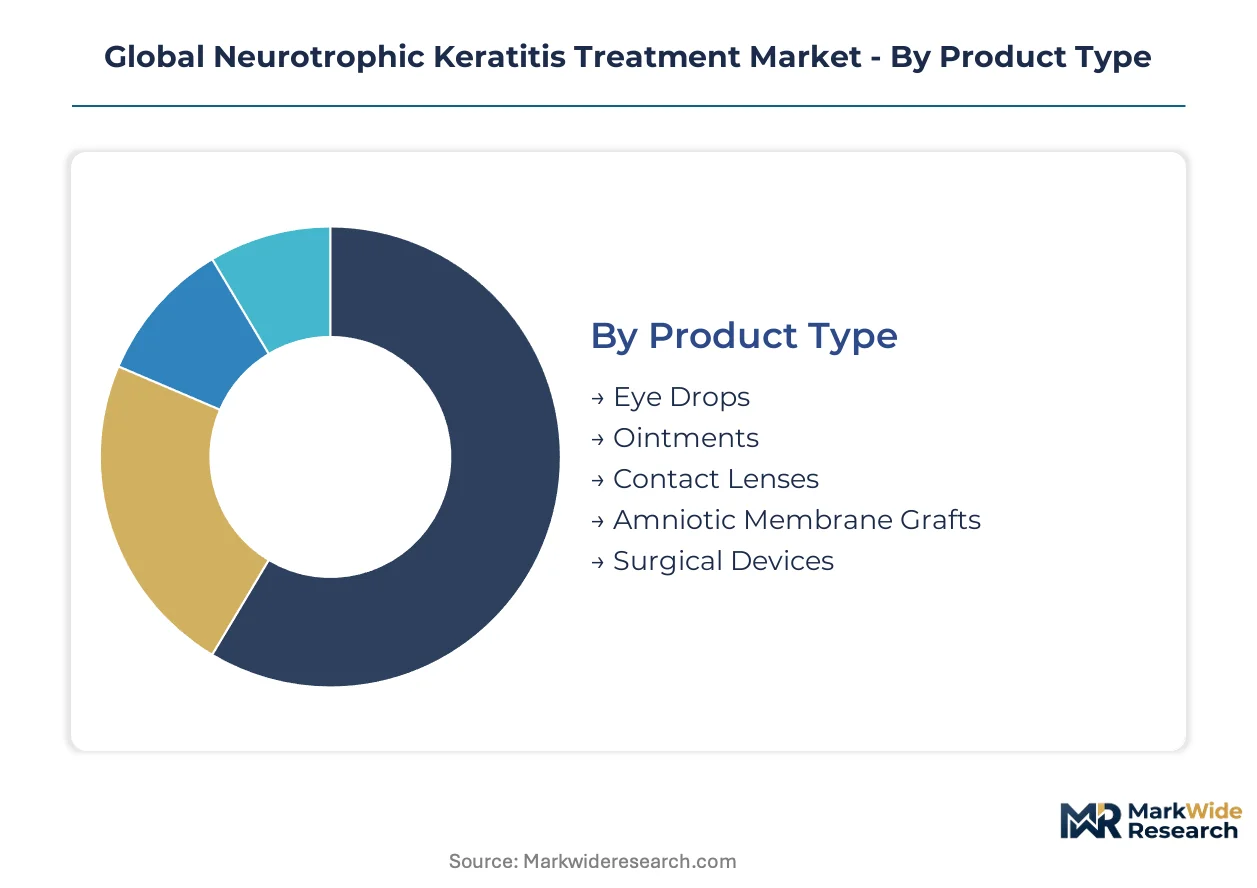
Segmentation in neurotrophic keratitis treatment reveals how clinical severity, reimbursement pathways, and delivery complexity fragment demand across patient cohorts. Each dimension carries distinct regulatory, pricing, and channel implications for manufacturers positioning biologic versus surgical solutions.
Product Type:
The use-case spectrum spans outpatient self-administration through operating-room intervention, with reimbursement intensity climbing alongside invasiveness.
- Eye Drops:Recombinant human nerve growth factor formulations at 20 mcg/mL concentration activate TrkA receptors to stimulate epithelial proliferation and nerve fiber regrowth. Demand concentrates in United States and German tertiary corneal centers where FDA and EMA approvals enable favorable reimbursement coding for biologic therapy over compounded alternatives.
- Amniotic Membrane Grafts:Dehydrated or cryopreserved placental tissue applied during keratoplasty or as standalone patch grafts provides anti-inflammatory cytokines and basement membrane scaffolding for Stage 3 ulcers. Japanese university hospitals and United States academic medical centers drive procurement through specialized corneal surgery units managing refractory neurotrophic defects.
- Ointments:Petrolatum-based vehicles with preservative-free formulations serve nighttime lubrication protocols in mild neuropathy cases.
- Contact Lenses:Bandage and scleral lens designs protect compromised epithelium from mechanical trauma and desiccation.
- Surgical Devices:Tarsorrhaphy instruments and amniotic membrane ring implants address structural lid abnormalities and persistent epithelial defects.
The dominant share belongs to Eye Drops, while Amniotic Membrane Grafts is closing the gap fastest.
Therapy Area:
Cost tier stratification separates premium biologic interventions from commodity symptomatic management, with payer classification determining access velocity.
- Neuroregeneration:TrkA-targeted biologics and emerging gene therapies aim to restore corneal innervation rather than mask neuropathy symptoms. German and United States corneal specialists prioritize these interventions for diabetic and post-herpetic etiologies where nerve fiber regrowth determines long-term visual outcomes.
- Corneal Healing:Growth factor formulations and extracellular matrix substitutes accelerate epithelial defect closure in Stage 2 disease. Demand clusters in Japan's specialized eye hospitals where PMDA-approved therapies command premium pricing against autologous serum alternatives.
- Lacrimal Secretion Enhancement:Secretagogues and punctal plug combinations address aqueous deficiency complicating neuropathic surface disease.
- Inflammation Control:Corticosteroid and calcineurin inhibitor protocols manage immune-mediated components of neurotrophic keratitis.
- Epithelial Protection:Osmoprotective agents and matrix metalloproteinase inhibitors prevent stromal melting in advanced disease.
Neuroregeneration commands the highest reimbursement tier, though Corneal Healing delivers the broadest addressable volume.
End User:
Customer type concentration reflects where diagnostic capability, surgical infrastructure, and biologic formulary access intersect.
- Ophthalmology Clinics:Private and group practice settings manage Stage 1 and early Stage 2 disease through topical therapy protocols. United States metropolitan markets show dense clustering where specialty pharmacy networks enable cold-chain distribution to satellite locations.
- Specialty Eye Hospitals:Academic and dedicated ophthalmology centers perform amniotic membrane grafting and tarsorrhaphy for Stage 3 disease. German university hospitals and Japanese national centers concentrate surgical volume and clinical trial enrollment for novel delivery systems.
- Research Institutes:Phase II and III trial sites generate evidence for regulatory submissions across FDA, EMA, and PMDA pathways.
- Ambulatory Surgical Centers:Outpatient facilities in United States markets handle bandage contact lens fitting and minor procedural interventions.
Specialty Eye Hospitals capture the highest per-patient revenue, yet Ophthalmology Clinics generate the largest prescription volume base.
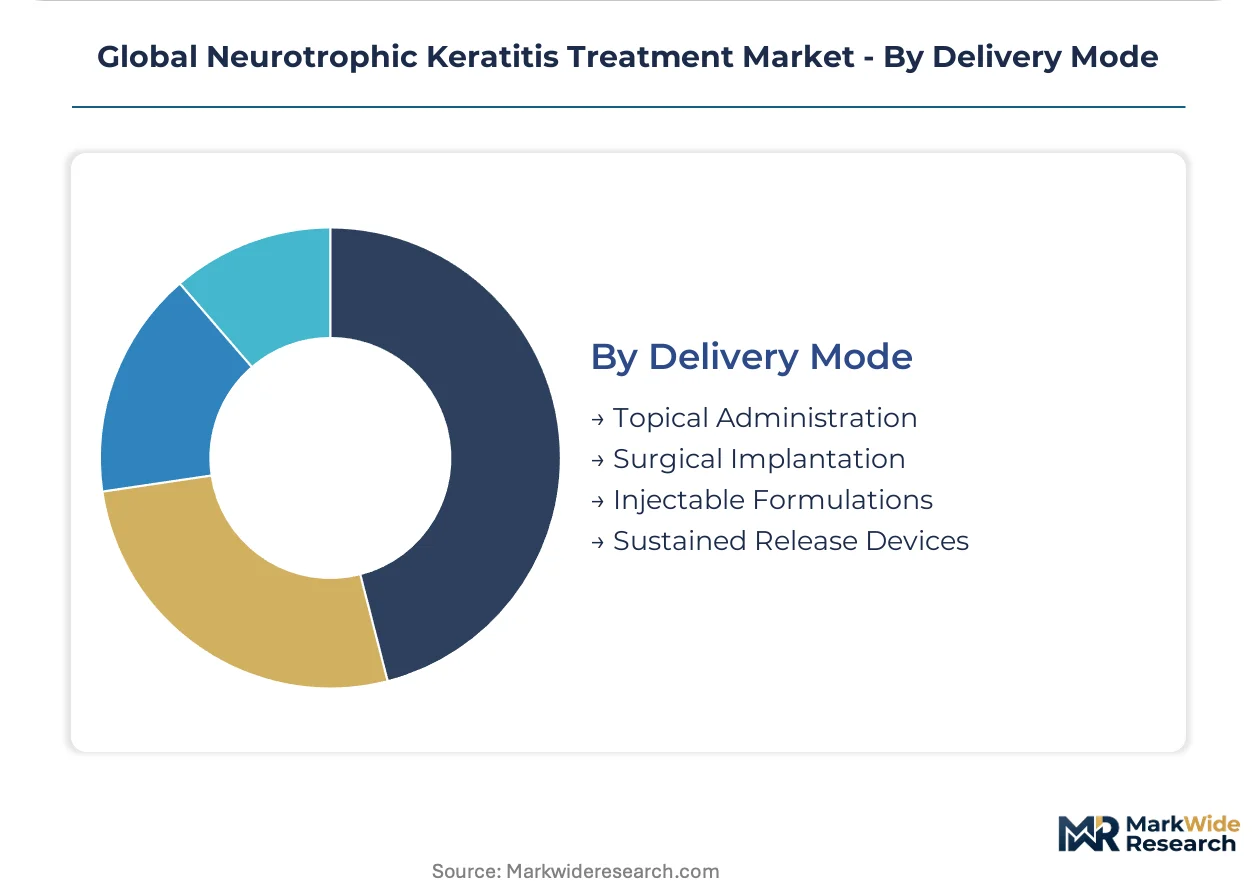
Delivery Mode:
Supply concentration favors modalities compatible with existing ophthalmic distribution infrastructure and cold-chain capabilities.
- Sustained Release Devices:Biodegradable ocular inserts and punctal plugs extend dosing intervals from daily to monthly or quarterly administration. German corneal specialists pilot these hybrid drug-device combinations for compliance-challenged diabetic patients.
- Topical Administration:Drop and ointment formulations dominate current prescribing through established pharmacy channels and patient familiarity.
- Surgical Implantation:Amniotic membrane rings and nerve growth factor depots require operating-room infrastructure and specialized surgical training.
- Injectable Formulations:Subconjunctival and intrastromal delivery routes remain experimental with limited commercial penetration.
Topical Administration maintains installed base dominance, while Sustained Release Devices is expanding most quickly through polymer stabilization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight through the Center for Drug Evaluation and Research anchors the United States as the dominant geography, while EMA centralized pathways and PMDA local mandates shape access velocity across Western Europe and Japan.
United States
Diabetic corneal neuropathy and post-surgical nerve damage expand the addressable patient base for tertiary eye centers. Medicare reimbursement coding for biologic ophthalmic therapies determines commercial viability against compounded alternatives. The Boston-Worcester corridor and Manhattan academic medical centers concentrate specialized corneal surgery volume and clinical trial enrollment.
Germany
German university hospitals prioritize TrkA-targeted biologics for diabetic and post-herpetic etiologies where nerve fiber regrowth determines visual outcomes. EMA centralized marketing authorizations streamline patient access across EU member states. The Rhine-Main cluster around Frankfurt and Heidelberg anchors corneal research infrastructure and specialized procurement networks.
Japan
PMDA requirements for domestic clinical trial data extend market entry timelines by 24-36 months for foreign sponsors seeking access. Specialized eye hospitals in Tokyo and Osaka command premium pricing for approved therapies against autologous serum alternatives. The Kanto region concentrates surgical volume and regulatory expertise for novel delivery systems.
United Kingdom
NHS England specialized commissioning frameworks determine access to premium biologic therapies versus standard lubricant protocols. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for innovative ophthalmic medicines. Moorfields Eye Hospital in London and the Manchester Royal Eye Hospital anchor national referral networks for neurotrophic keratitis.
Brazil
ANVISA regulatory pathways for biologic ophthalmics remain underpenetrated relative to patient disease burden from diabetes and leprosy-related neuropathy. Public health system procurement through SUS creates volume opportunities for cost-optimized formulations. São Paulo and Rio de Janeiro concentrate private ophthalmology practice and diagnostic capability.
Global Neurotrophic Keratitis Treatment Market Competitive Landscape
European biologic specialists and integrated eye health platforms split the market between recombinant protein innovation and established distribution infrastructure. Consolidation around specialty pharmacy networks and cold-chain logistics favors players with captive manufacturing or exclusive channel partnerships. Three archetypes dominate: mammalian cell culture manufacturers, integrated eye care conglomerates, and regional ophthalmology specialists. Competitive moves center on EMA/FDA dual-track regulatory submissions and exclusive distribution agreements with academic medical centers.
Among European-based biologic developers, Dompé Farmaceutici exemplifies the recombinant protein manufacturing archetype, while Bausch + Lomb Incorporated occupies a position within integrated eye health platforms. Santen Pharmaceutical anchors the Asia-Pacific specialist tier through localized regulatory infrastructure. These three represent distinct strategic postures: European manufacturing base leverage, corneal specialist relationship depth, and dedicated ophthalmology sales infrastructure.
| Leading Market Players |
|---|
| Dompé Farmaceutici |
| Bausch + Lomb Incorporated |
| Santen Pharmaceutical |
| Recordati Rare Diseases |
| Oyster Point Pharma |
| ReGenTree |
| Alcon |
| Johnson & Johnson Vision |
| KALA BIO |
| Others |
Supply & Pricing Matrix
The Rhine-Main manufacturing cluster around Frankfurt anchors European recombinant protein supply, with Dompé Farmaceutici's mammalian cell culture capacity constraining downstream availability of nerve growth factor formulations and amplifying pricing power for EMA-approved biologics against compounded alternatives.
Pricing Analysis
United States-Germany-Japan price spreads exceed threefold across equivalent recombinant human nerve growth factor therapies, reflecting reimbursement divergence rather than manufacturing cost differentials. Three-tier pricing structure across premium biologic, standard compounded, and economy lubricant levels stratifies by FDA/EMA/PMDA approval status and corneal center tier affiliation. Pricing pressure stems from autologous serum drop compounding in markets with limited biologic reimbursement, squeezing mid-tier formulations. Academic medical centers exhibit lowest price sensitivity due to dedicated ophthalmology budgets, while private ophthalmology clinics in United States metropolitan markets face highest sensitivity from Medicare reimbursement constraints.
Supply Chain Analysis
Cold-chain integrity failures between Italian manufacturing sites and United States specialty pharmacy networks dominate supply risk exposure for temperature-sensitive biologic ophthalmics. Production concentrates in Italy, Germany, and Japan, with mammalian cell culture capacity drawing from fetal bovine serum, recombinant protein media, and single-use bioreactor systems. Single-source vulnerability characterizes nerve growth factor active pharmaceutical ingredient supply, with European facilities producing exclusively for global markets. Distribution runs through consolidated specialty pharmacy networks with exclusive academic medical center agreements, displacing general retail channels for biologic eye therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in cold-chain logistics and patient compliance monitoring expand faster than pharmaceutical manufacturing, with specialty pharmacy networks capturing recurring revenue through exclusive distribution agreements and adherence program administration.
For Market Incumbents: Entrench formulary position through backward integration into mammalian cell culture capacity and captive cold-chain distribution infrastructure. Gene therapy pipeline entrants threaten recombinant protein franchises; defend through TrkA receptor activation patent estates and EMA/FDA dual-track regulatory exclusivity extensions. For New Entrants and Emerging Players: Pursue sustained-release ocular implant white space in German university hospital pilot programs and Brazil's ANVISA pathway for cost-optimized biologic formulations. Brazil's public health procurement through SUS represents most penetrable geography; enter through localized compounding partnerships and SUS volume contracting. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management play because diabetic corneal neuropathy incidence trajectories anchor durable demand for nerve regeneration therapies. Acquisition target archetype: European biologic manufacturers with EMA centralized marketing authorizations and captive mammalian cell culture assets. Signal to watch: PMDA accelerated assessment pathway adoption rates for foreign sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| EMA/FDA Dual-Track Regulatory Submission | Parallel approval pathways compress market entry timelines across United States and EU member states. |
| Sustained-Release Ocular Implant Development | Biodegradable polymer stabilization extends dosing intervals and captures compliance-challenged diabetic patient segments. |
| Specialty Pharmacy Network Exclusive Agreement | Cold-chain distribution partnerships with academic medical centers lock out retail pharmacy competitors. |
| Autologous Serum Alternative Formulation | Cost-optimized positioning targets Brazil SUS procurement and United States Medicare reimbursement constraints. |
| Teleophthalmology Diagnostic Partnership | Remote corneal sensation testing expands rural United States patient identification and referral funnel. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with corneal specialists and specialty pharmacy operators combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical market sizing triangulated volume estimates across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across treatment line, dosage form, administration route, and regional regulatory cluster informing projection outputs. CAGRs derived from epidemiological trend extrapolation, therapy penetration curve analysis, and pricing trajectory modeling. Forecast inputs incorporated diabetic population growth projections and biologic reimbursement coding evolution across Medicare, NHS England, and Japan's universal health coverage.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility, healthcare budget austerity, or biologic manufacturing input costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and payer classification decisions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market