
 Solid Bleached Board Market | 2026-2036
Solid Bleached Board Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Bleached Board Market Analytics
Digital printing integration is fragmenting traditional long-run SBB procurement into shorter, customized campaigns. Stora Enso leverages its Nordic pulp infrastructure to secure cost-advantaged virgin fiber supply. International Paper Company anchors North American folding box board capacity through integrated mill networks. Mondi Group differentiates via lightweight SBB grades that reduce material intensity for e-commerce pharma shipments.
Solid bleached board is a multi-ply paperboard product manufactured from bleached chemical pulp, typically featuring a mineral pigment coating that yields brightness levels exceeding 80% ISO and superior fold endurance for high-definition printing. Its primary purpose centers on premium packaging applications where structural rigidity, surface smoothness, and food-contact compliance converge. Folding box board dominates volume flows into pharmaceutical and cosmetics packaging, where print fidelity and crease performance command margin premiums. Coated board variants capture growth in luxury goods segments where tactile finish and visual depth drive brand differentiation. Uncoated grades retain cost-sensitive stationery and general printing applications where brightness thresholds remain moderate.
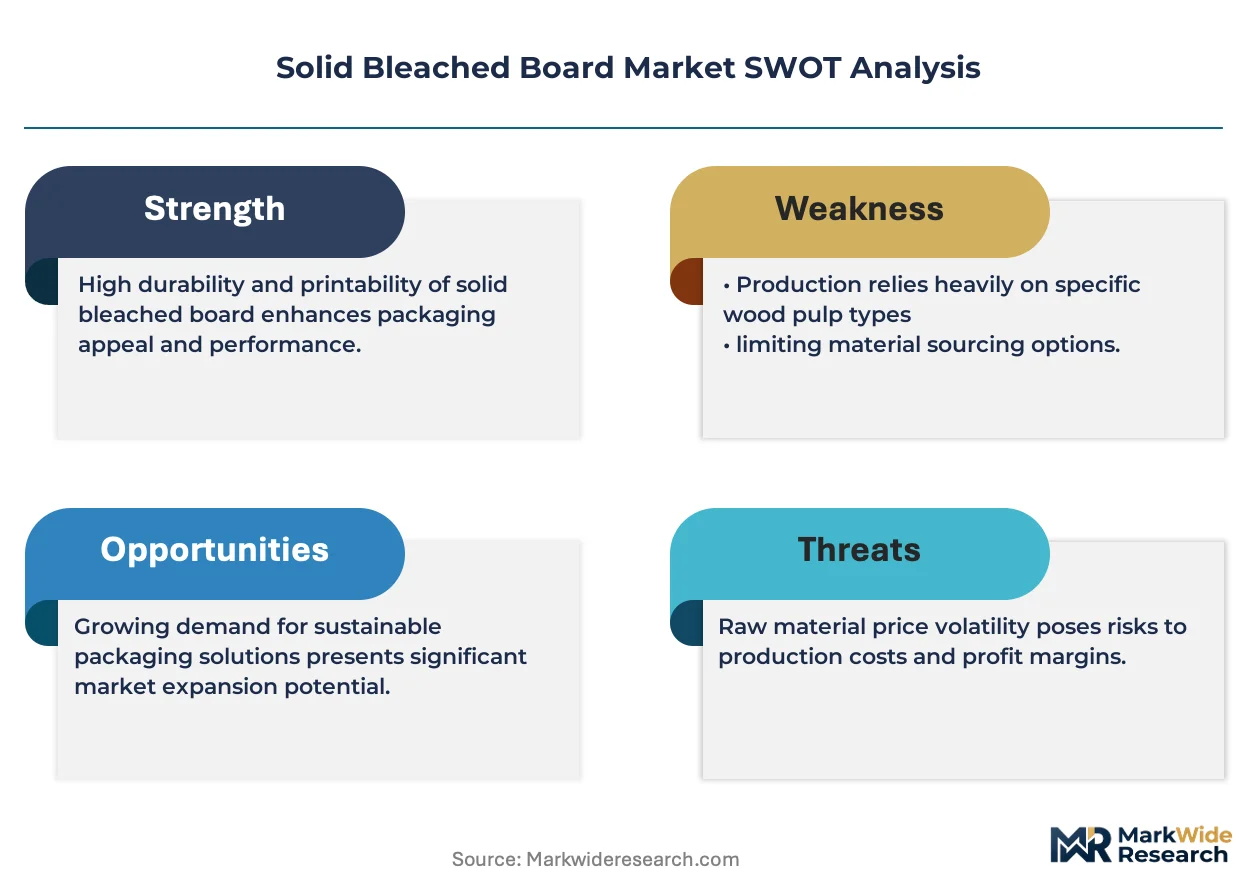
FDA food-contact substance regulations govern SBB migration limits for direct food packaging in the United States, while REACH compliance in the European Union restricts coating chemistries and recycled fiber integration thresholds. The EU Green Deal packaging requirements are tightening recycled content mandates, forcing virgin-fiber-dependent producers to reconfigure furnish strategies or absorb certification costs. Stakeholders must monitor pulp cost volatility and regulatory divergence between North American and European sustainability frameworks to calibrate capacity allocation and product mix decisions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing virgin-fiber-dependent SBB producers to reconfigure furnish strategies around traceability mandates and recycled content thresholds, compressing margins for integrated mills while advantaging certified circular suppliers.
Growth Catalysts
- REACH compliance thresholds:Chemical coating restrictions in the European Union are accelerating demand for compliant high-barrier SBB grades in pharmaceutical primary packaging.
- Tamper-evident carton solutions:Brand owners in cosmetics and OTC healthcare are specifying fold-resistant SBB with embedded authentication features.
- Rhine-Ruhr industrial corridor:Concentrated folding carton production around Düsseldorf and Cologne creates captive demand for just-in-time SBB delivery.
Market Restraints
- Softwood pulp cost volatility:Nordic kraft pulp price swings transmit directly into SBB mill operating margins, squeezing converters on quarterly contract resets.
- Recycled fiber integration limits:FDA food-contact substance regulations cap post-consumer content in direct-food SBB applications below pharmaceutical-grade thresholds.
- Folding box board substitution:Uncoated recycled board and liquid packaging board are capturing cost-sensitive stationery and beverage carton volumes.
Strategic Opportunities
- Lightweight SBB grades:Grammage reduction below 250 gsm for e-commerce pharmaceutical shipments cuts dimensional weight charges and material intensity.
- Digital print compatibility:Short-run, versioned carton campaigns for clinical trial packaging and personalized medicine are opening premium SBB niches.
- EU Green Deal packaging requirements:Extended producer responsibility schemes and carbon border adjustments are creating certification premiums for verifiable low-carbon SBB.
Industry Challenges
- Coating chemistry reformulation:Replacing fluorinated barriers with mineral-based alternatives requires multi-year validation cycles with pharmaceutical sponsors.
- Migration testing protocols:Demonstrating compliance with FDA food-contact substance regulations demands specialized analytical capacity that smaller converters lack.
- Mill asset reconfiguration:Retrofitting bleached board machines for furnish flexibility carries high capital intensity and extended downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Bleached Board Market |
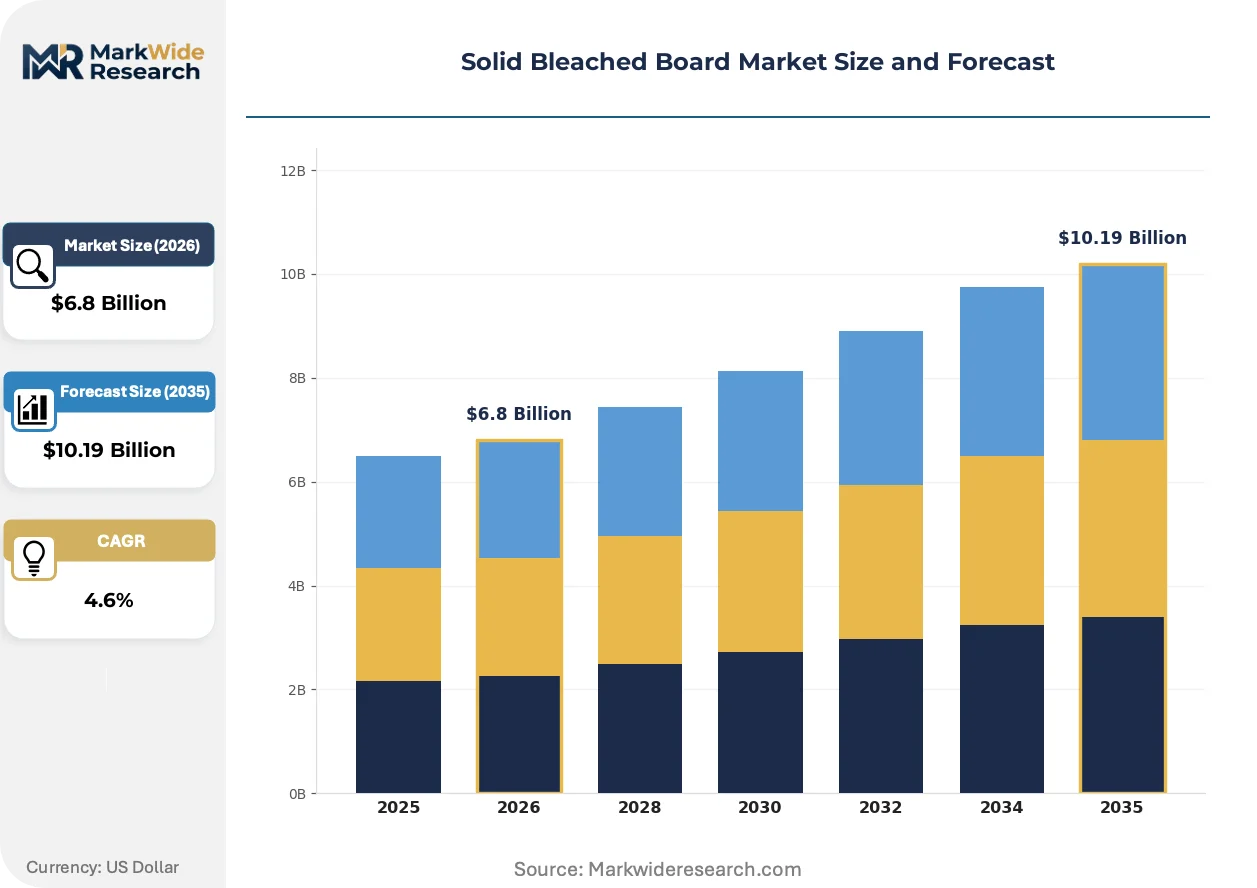
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
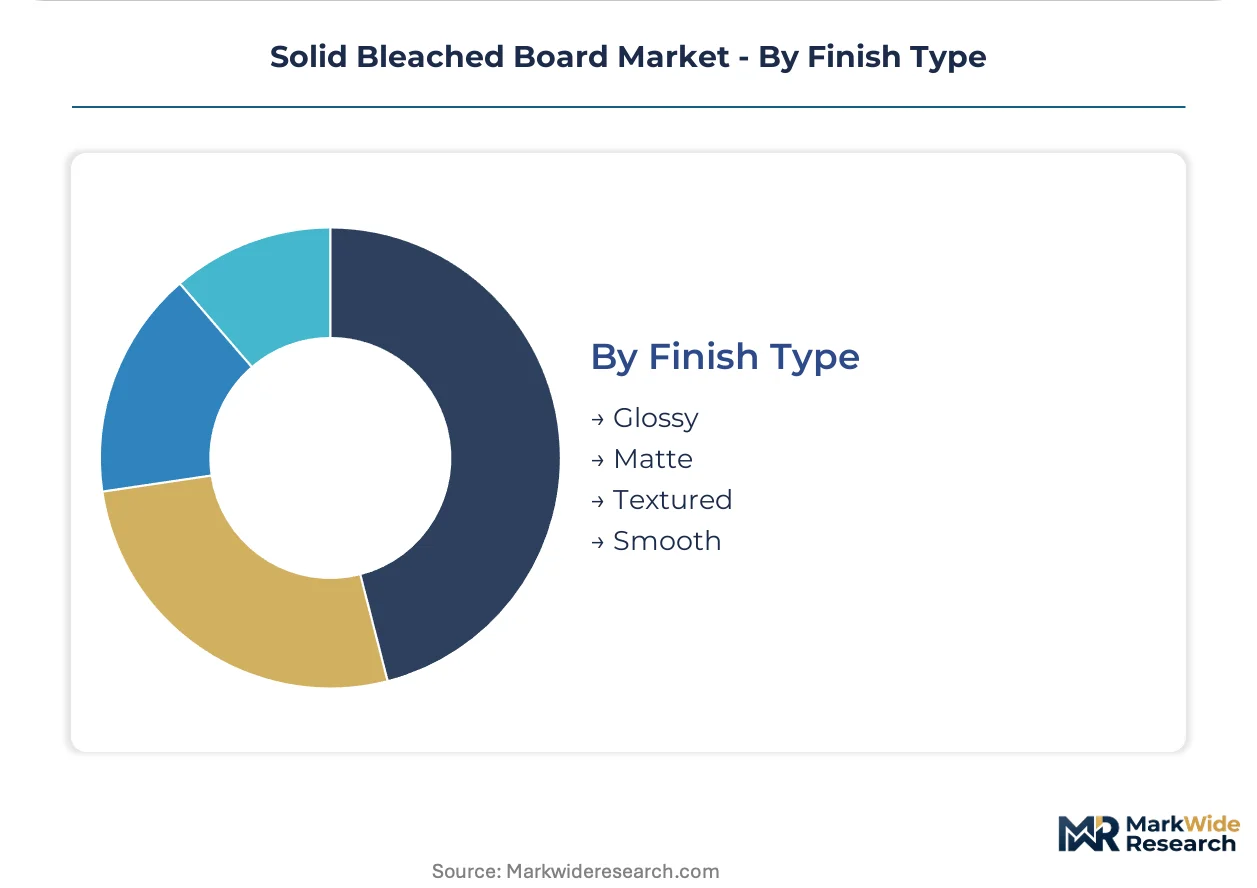
| Segmentation | Product Type: Coated Board, Uncoated Board, Folding Box Board, Graphics Board End Use: Packaging, Printing, Stationery, Food Service Thickness: Lightweight, Medium Weight, Heavyweight, Ultra Heavyweight Finish Type: Glossy, Matte, Textured, Smooth |
| Companies Covered | Stora Enso, International Paper Company, WestRock Company, Smurfit Kappa Group, Sappi Limited, Georgia-Pacific, Mondi Group, Nippon Paper Industries, Clearwater Paper Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Bleached Board Market Evolving Landscape
Digital printing integration and barrier coating chemistry advances are fragmenting traditional long-run procurement while tightening performance specifications for pharmaceutical and luxury packaging segments.
Water-based barrier coatings with mineral micro-laminate structures are rendering obsolete solvent-based polyethylene extrusion for high-moisture pharmaceutical blister card backing. Mid-size folding carton converters in Germany and Switzerland are adopting these coatings to secure EU MDR-compliant medical device packaging contracts. The shift is compressing demand for legacy extrusion-coated SBB while expanding addressable share in moisture-sensitive diagnostics.
REACH restrictions on per- and polyfluoroalkyl substances are prohibiting oil-grease-barrier chemistries previously standard in food-contact SBB. European folding box board producers are accelerating pilot programs with bio-based wax emulsions and nanocellulose layers to maintain grease resistance. Pharmaceutical packaging lines are least affected due to existing non-fluorinated specifications, while ready-meal and bakery segments face urgent material transitions.
Brand owners are consolidating carton specification authority at headquarters level while fragmenting order quantities across regional production sites. This centralization of design decisions with decentralization of fulfillment is compressing run lengths and demanding inventory-light supply chain configurations. The pattern is most pronounced in cosmetics and premium spirits, where German and French headquarters teams specify identical SBB grades for local conversion in multiple countries.
Solid Bleached Board Market Segmentation
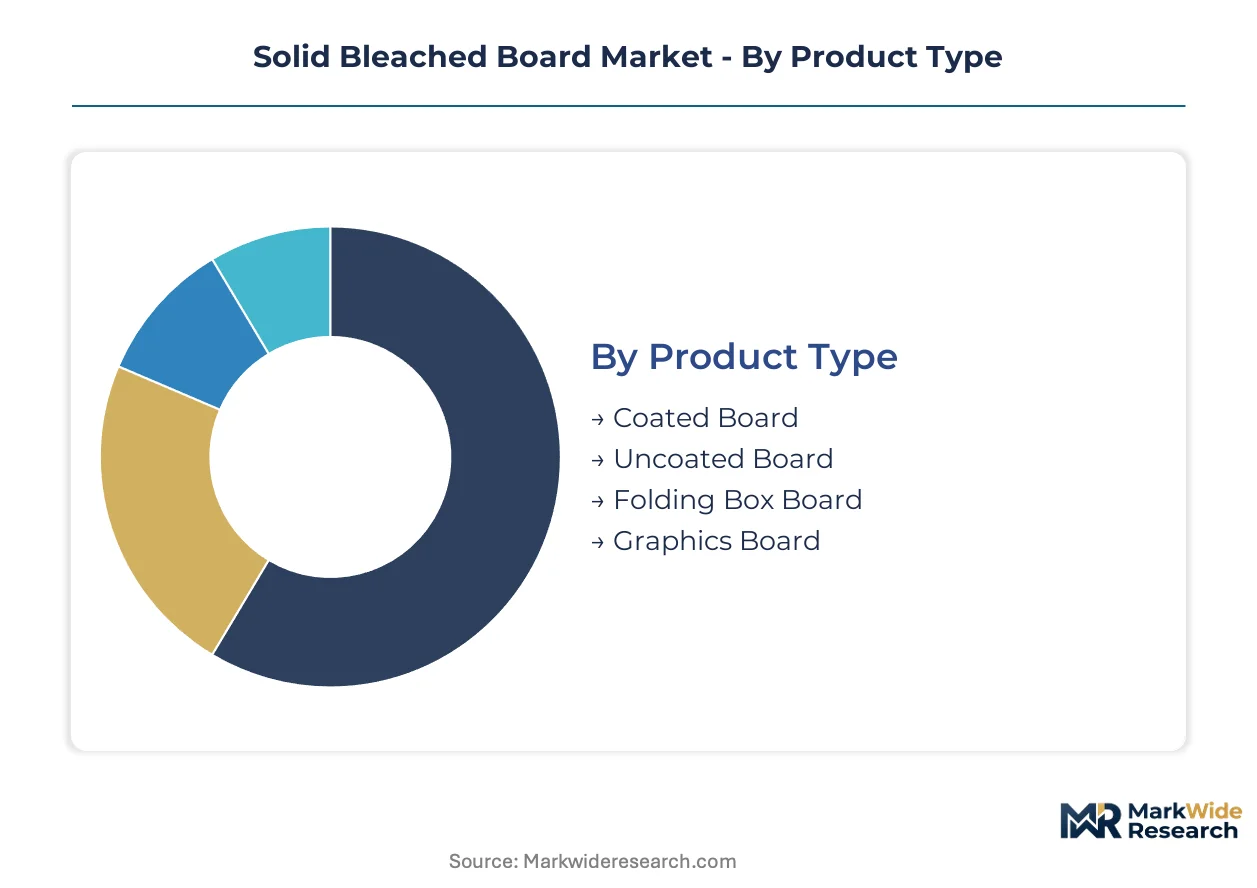
Segmentation in solid bleached board reveals divergent margin profiles and specification requirements across pharmaceutical, cosmetics, and food-contact applications. Procurement cycles vary dramatically by end-use, with clinical trial packaging demanding rapid turnaround while luxury spirits cartons operate on seasonal long-run schedules.
Product Type:
Folding box board turns inventory fastest through pharmaceutical just-in-time contracts, while graphics board sits longest awaiting brand approval cycles. Coated and uncoated variants split between premium visual requirements and cost-driven applications.
- Folding Box Board:Multi-ply construction with mineral-pigment coating delivers ISO brightness above 80% and superior crease recovery for automated erecting lines. Demand concentrates in Germany's Rhine-Ruhr corridor where folding carton producers cluster around Düsseldorf and Cologne, driven by EU MDR compliance requirements for medical device packaging.
- Coated Board:Kaolin or calcium carbonate surface treatments enable high-definition gravure and offset reproduction for luxury cosmetics and premium spirits. Swiss and French brand owners specify identical grades across regional production sites, fragmenting order quantities while centralizing design authority.
- Uncoated Board:Retains cost-sensitive stationery and general printing applications where brightness thresholds remain moderate and post-consumer fiber integration faces fewer regulatory barriers.
- Graphics Board:Specialized stiffness-to-weight ratios support display and point-of-sale applications with extended design validation timelines and lower volume velocity.
Folding box board anchors the volume base while coated board gains share at the steepest rate.
End Use:
Margin tiers separate pharmaceutical primary packaging from commoditized printing applications, with food service occupying a compliance-heavy middle position.
- Packaging:Pharmaceutical and cosmetics cartons command specification premiums through tamper-evident folding performance and barrier coating compatibility. REACH-compliant high-barrier grades for moisture-sensitive diagnostics are displacing legacy extrusion-coated alternatives in German and Swiss converting facilities.
- Food Service:FDA food-contact substance regulations cap post-consumer fiber content below pharmaceutical thresholds, forcing virgin-fiber-dependent furnish strategies for direct-contact applications. Ready-meal segments face urgent coating chemistry transitions as ECHA restrictions eliminate per- and polyfluoroalkyl substance barriers.
- Printing:General commercial applications tolerate lower brightness specifications and accept higher recycled content, compressing margins for bleached pulp-dependent producers.
- Stationery:Uncoated grades dominate correspondence and document covers where tactile feel matters less than unit cost.
Packaging captures the margin premium while food service absorbs the steepest compliance cost inflation.
Thickness:
Grammage selection directly determines dimensional weight charges in pharmaceutical e-commerce fulfillment, creating divergent total-cost economics.
- Lightweight:Sub-250 gsm grades reduce material intensity and shipping costs for clinical trial kits and personalized medicine shipments. Mondi Group and comparable suppliers engineer specific calipers for automated pharmacy dispensing systems.
- Medium Weight:Standard pharmaceutical blister card backing and cosmetics folding cartons balance rigidity with converting efficiency.
- Heavyweight:Structural applications including rigid box sets and premium spirits packaging where tactile heft signals quality.
- Ultra Heavyweight:Specialized display and luxury packaging with extended production lead times and lower velocity.
Lightweight grades are climbing the fastest as e-commerce pharmaceutical distribution expands.
Finish Type:
Surface treatment selection separates mass-market cosmetics from ultra-premium positioning, with tactile finish driving brand differentiation in saturated categories.
- Glossy:High-reflectance coatings maximize color saturation for shelf impact in competitive retail environments. Premium spirits and skincare brands specify identical gloss levels across German, French, and Italian production sites.
- Matte:Soft-touch finishes signal understated luxury in boutique cosmetics and artisanal food positioning. Surface chemistry must maintain fold endurance without cracking.
- Textured:Embossed linen or leather-grain patterns create tactile differentiation for limited-edition releases and gift packaging with lower volume rotation.
- Smooth:Neutral surface accepts diverse post-print processes including foil stamping and spot UV, preferred for versioning campaigns with short lead times.
Matte finishes are expanding most quickly in premium skincare while glossy retains mass-market dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German folding carton exports flow predominantly into Swiss pharmaceutical packaging facilities and French cosmetics assembly plants, establishing a Rhine-centered trade corridor that dictates regional inventory positioning and just-in-time delivery schedules.
Germany
Pharmaceutical blister card demand and EU MDR compliance requirements for medical device packaging drive specification premiums for high-barrier grades. REACH restrictions on per- and polyfluoroalkyl substances force coating chemistry transitions across the value chain. The Rhine-Ruhr industrial corridor around Düsseldorf and Cologne hosts concentrated folding carton production, with converters clustering near integrated SBB mills to minimize logistics costs.
United States
FDA food-contact substance regulations govern migration limits for direct-food packaging applications, creating compliance-heavy procurement cycles distinct from pharmaceutical grades. E-commerce pharmaceutical distribution expansion is accelerating lightweight SBB adoption for clinical trial kits. The Southeast region, particularly Georgia and the Carolinas, anchors integrated folding box board capacity with proximity to major pharmaceutical distribution hubs.
Switzerland
Swissmedic medical device packaging standards and precision pharmaceutical manufacturing create demand for tamper-evident, high-crease-recovery carton solutions. The country's central European location positions it as a conversion hub for German SBB supply. Basel and Zurich host specialized folding carton facilities serving global pharmaceutical headquarters with stringent traceability requirements.
China
SAMR food-contact material regulations and dual carbon goals are tightening recycled content mandates and carbon intensity disclosures for packaging materials. Domestic pharmaceutical packaging growth is absorbing premium SBB imports despite local folding box board expansion. The Yangtze River Delta region concentrates converting capacity near Shanghai pharmaceutical manufacturing clusters.
France
Cosmetics and premium spirits packaging specifications centralize at Paris headquarters while fragmenting order quantities across regional production sites. ANSM pharmaceutical packaging requirements align with broader EU MDR frameworks. The Île-de-France region hosts brand owner specification authority, while conversion occurs in Auvergne-Rhône-Alpes and Hauts-de-France production facilities.
Solid Bleached Board Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pulp-to-board producers with captive fiber supply and multi-machine mill networks capable of grade flexibility. Nordic and North American players dominate virgin-fiber sourcing positions, while European converters face margin compression from regulatory compliance costs. Three archetypes define competitive positioning: integrated forest products groups with backward pulp control, specialty paperboard divisions of diversified packaging conglomerates, and regional folding box board specialists with pharmaceutical certification depth. Capacity expansion and barrier coating technology partnerships represent the dominant competitive moves, as producers seek to secure pharmaceutical-grade validation cycles and lightweight grade development.
Within the integrated forest products tier, Stora Enso anchors Nordic virgin-fiber supply positions, while International Paper Company represents North American folding box board capacity concentration. Mondi Group occupies a differentiated position through lightweight grade engineering for e-commerce pharmaceutical applications. These three exemplify the strategic divide between fiber-cost-advantaged producers and specification-driven specialists competing on compliance depth rather than scale economies.
| Leading Market Players |
|---|
| Stora Enso |
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| Sappi Limited |
| Georgia-Pacific |
| Mondi Group |
| Nippon Paper Industries |
| Clearwater Paper Corporation |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr industrial corridor around Düsseldorf and Cologne concentrates integrated SBB mill capacity, creating asymmetric pricing power where captive pulp supply translates into quarterly contract leverage over downstream folding carton converters.
Pricing Analysis
Barrier-coating technology generations create distinct pricing tiers: legacy fluorinated-barrier SBB commands residual premiums in validated pharmaceutical lines, mineral-micro-laminate grades capture mid-tier positioning, and next-generation bio-based wax emulsions trade at nascent premiums pending ECHA compliance confirmation. Three-tier pricing structure across pharmaceutical-certified, food-contact-compliant, and general-printing grades separates specification depth from volume scale. Pricing pressure stems from Nordic softwood pulp cost volatility transmitting directly into mill operating margins. Clinical trial packaging converters exhibit highest price sensitivity due to fragmented order quantities, while luxury spirits brand owners absorb premiums for tactile finish differentiation.
Supply Chain Analysis
Tariff exposure between Nordic pulp producers and German converting facilities dominates supply chain risk assessment, compounded by carbon border adjustment mechanisms under EU Green Deal implementation. Geographic supply concentration centers on Finland, Sweden, and Germany for virgin-fiber SBB, with North American integrated mills serving as swing capacity. Raw material dependencies draw from bleached chemical pulp, mineral pigment coatings, and barrier chemistry inputs. Single-source vulnerability persists for pharmaceutical-grade validation cycles where multi-year sponsor approvals lock converters to specific mill qualifications. Distribution runs through mill-direct contracts to large folding carton producers, with regional distributors serving smaller converting facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital print compatibility and lightweight grade standardization create interoperability layers that favor ecosystem orchestrators over standalone producers.
For Market Incumbents: Build certification moats by accelerating FDA food-contact substance and EU MDR validation cycles for barrier coating chemistries before ECHA restrictions harden. Secure backward integration into Nordic pulp supply through long-term offtake agreements to neutralize cost volatility. Defend against lightweight grade specialists by engineering sub-250 gsm calipers for automated pharmacy dispensing systems. For New Entrants and Emerging Players: Establish a beachhead in clinical trial packaging where short-run digital print campaigns and rapid turnaround requirements favor agile converters over integrated mill networks. Target Swiss and French cosmetics assembly plants with inventory-light supply chain configurations that mirror German brand owner specifications. Pursue white-label barrier coating partnerships with mid-size German converters lacking in-house R&D capacity. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory divergence between FDA and REACH frameworks creates persistent certification premiums for dual-qualified producers. Acquisition targets should display pharmaceutical-grade validation depth and digital print line integration. The signal to watch is ECHA acceleration of per- and polyfluoroalkyl substance prohibitions forcing urgent coating chemistry transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Chemistry Partnership | Secures ECHA-compliant validation cycles with pharmaceutical sponsors before fluorinated barriers phase out. |
| Lightweight Grade Engineering Program | Reduces dimensional weight charges for Mondi Group and comparable suppliers in e-commerce pharma distribution. |
| Digital Print Line Integration | Captures fragmented order quantities from cosmetics brand owners centralizing design authority at Paris headquarters. |
| Nordic Pulp Supply Agreement | Locks in cost-advantaged virgin fiber for Stora Enso and integrated mill competitors amid price volatility. |
| EU MDR Certification Investment | Opens medical device packaging contracts in Germany's Rhine-Ruhr corridor with tamper-evident fold requirements. |
Research Methodology
Initial hypotheses were tested against primary input from folding carton procurement directors, pharmaceutical packaging engineers, and barrier coating R&D leads and refined through secondary validation. Mill operations managers, EU regulatory affairs specialists, and brand owner sustainability officers contributed operational perspective. Secondary sources included ECHA restriction dossiers, FDA food-contact substance notifications, EU MDR technical documentation, and Nordic pulp futures pricing data. Bottom-up volume estimates from converting facility throughput were triangulated against top-down pulp consumption models.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for pharmaceutical, cosmetics, and food-contact applications. Segmentation dimensions included product type, end-use industry, grammage tier, and surface finish specification. CAGRs were derived from elasticity-adjusted volume projections and value-per-ton trends. Industry-specific forecast inputs incorporated ECHA regulatory timelines and digital print adoption rates in clinical trial packaging.
Stress conditions across softwood pulp price bands, recycled content mandate stringency, and coating chemistry transition speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and sponsor validation cycle durations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Saturated Kraft Paper Market
Paper Products
Drum Pulper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Carbonless Paper Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Printing Paper Market
Paper Products
Africa Tissue Paper Market
Paper Products
Pigmented Paper Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Insulation Paper Market