
 Carbonless Paper Market | 2026-2036
Carbonless Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonless Paper Market Analysis
Logistics sector form consumption is decoupling from traditional financial services demand as e-commerce fulfillment scales. Koehler Paper leverages its European coating expertise to supply multi-part grades for parcel documentation. Oji Holdings Corporation anchors Asia-Pacific supply through integrated pulp-to-paper operations. Pixelle Specialty Solutions competes on narrow-web customization for regional courier networks.
Carbonless paper consists of a coated sheet system where microencapsulated dye precursors rupture under pressure to transfer an image to an underlying receiver sheet, typically manufactured in 40–80 gsm basis weights for reliable impression transfer without carbon interleaving. The primary commercial purpose remains generation of instant duplicate or triplicate records in settings where digital infrastructure is absent or where physical audit trails are mandated. Self-contained grades command premium positioning in compact portable printers, while three-part forms retain volume dominance in government and logistics procurement. Adhesive-backed variants represent the fastest-growing configuration as warehouse labeling and field-service ticketing expand. Direct sales channels capture the largest margin pools through mill-branded contract supply to institutional buyers.
EPA guidelines in the United States govern volatile organic compound emissions from coating operations, while REACH in the European Union restricts certain formaldehyde-releasing resin systems used in capsule wall formation. BIS certification requirements in India create compliance barriers for imported coated reels, favoring domestic converters. Stakeholders must monitor evolving e-invoicing mandates country by country to calibrate carbonless inventory against projected document-form obsolescence curves.
Market Dynamics
Logistics documentation requirements are fragmenting carbonless paper demand across e-commerce fulfillment networks, while REACH dye restrictions force coating chemistry reformulation at European mills.
Growth Catalysts
- E-commerce logistics documentation:Parcel carriers require multi-part delivery receipts for signature capture at drop-off points where mobile connectivity fails. India and Southeast Asian markets drive volume.
- REACH reformulation:European mills developing formaldehyde-free microcapsule wall systems unlock continued access to EU institutional procurement channels.
- Field-service ticketing:Adhesive-backed carbonless rolls enable technicians to generate customer copies without portable printers. Utility and telecom maintenance crews adopt widely.
Market Restraints
- Phenol derivative input costs:Dye precursor synthesis depends on petrochemical feedstocks subject to refinery output volatility. Margin compression hits specialty coating operations.
- Supply concentration in integrated pulp-to-paper groups:Asia-Pacific production clusters around Japanese and Indonesian integrated mills. Converter access to coated reels narrows during capacity tightness.
- Digital invoice mandates:India's GST e-invoicing rollout and Brazil's Nota Fiscal Eletrônica reduce triplicate form requirements in tax documentation.
Strategic Opportunities
- Last-mile administrative gaps in Indian states:Bihar and Uttar Pradesh digitization lags sustain demand for land-record and ration-card duplicate forms. Domestic converters expand regional distribution.
- Warehouse labeling convergence:Carbonless-adhesive hybrid stocks merge picking-list generation with carton labeling. Third-party logistics operators trial single-pass systems.
- Self-contained portable printer grades:Compact CB-coated sheets eliminate need for matching CF stock in mobile inspection units. Railway and highway maintenance departments specify.
Industry Challenges
- Microencapsulation technician scarcity:Coating line operation requires precise control of capsule size distribution and wall thickness. European mills poach skilled operators from declining graphic paper sectors.
- BIS certification timeline for imported reels:Indian customs hold coated stocks for laboratory testing of dye migration limits. Working capital gets trapped for 8-14 weeks.
- Legacy form inventory obsolescence:Government procurement shifts to pre-printed security-featured stocks render standard multi-part inventories unsellable. Converters face write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonless Paper Market |
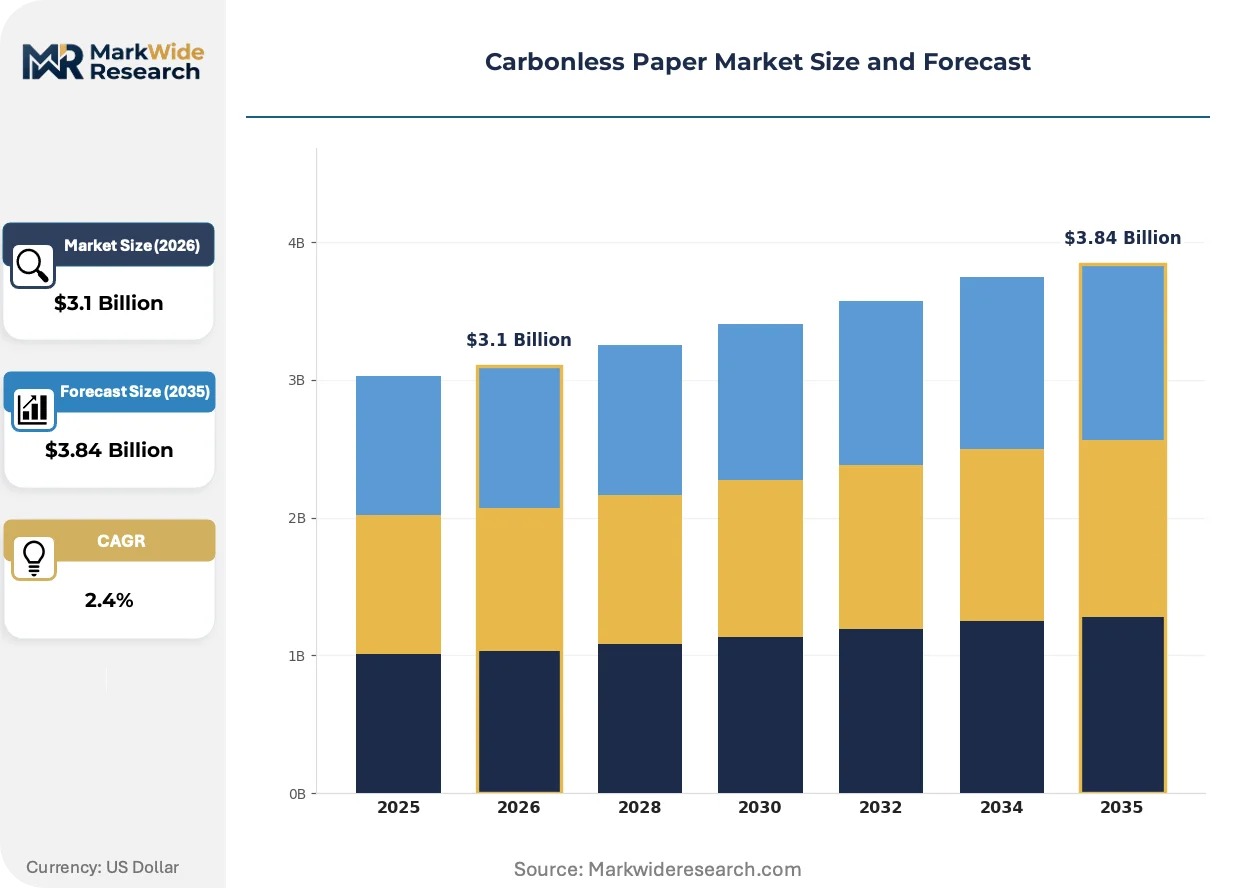
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Contained, Two-Part, Three-Part, Adhesive End User: Educational Institutions, Financial Services, Logistics, Government Agencies Application: Invoices, Receipts, Delivery Notes, Purchase Orders Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Jianghe Paper, Oji Holdings Corporation, Appvion Paper, Golden Paper Group, Pixelle Specialty Solutions, Koehler Paper, Mitsubishi HiTec Paper, Stora Enso Oyj, Lecta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonless Paper Market Emerging Trajectories
Coating chemistry advancement and procurement digitization are splitting carbonless paper evolution into parallel tracks: regulatory-compliant reformulation for established markets, and format innovation for logistics applications.
Pressure-responsive microcapsule systems are converging with thermal-sensitive dye technologies to create hybrid recording media. Cold-chain logistics operators in pharmaceutical distribution pilot these stocks for temperature-excursion documentation alongside standard delivery receipts. The convergence enables single-form compliance with dual regulatory audit requirements.
REACH restrictions on formaldehyde-releasing resins are eliminating legacy capsule wall chemistries from EU supply chains. German and French mills accelerate urea-formaldehyde replacement with polyurethane and melamine alternatives. Self-contained grades for portable printers face reformulation cost premiums that compress converter margins.
Direct mill contracting is displacing distributor intermediation in institutional procurement. Indian state government stationery departments negotiate multi-year supply agreements with domestic coating operations. Tamil Nadu and Karnataka tender processes now specify local BIS-certified production, excluding imported reel competition.
Carbonless Paper Market Segmentation
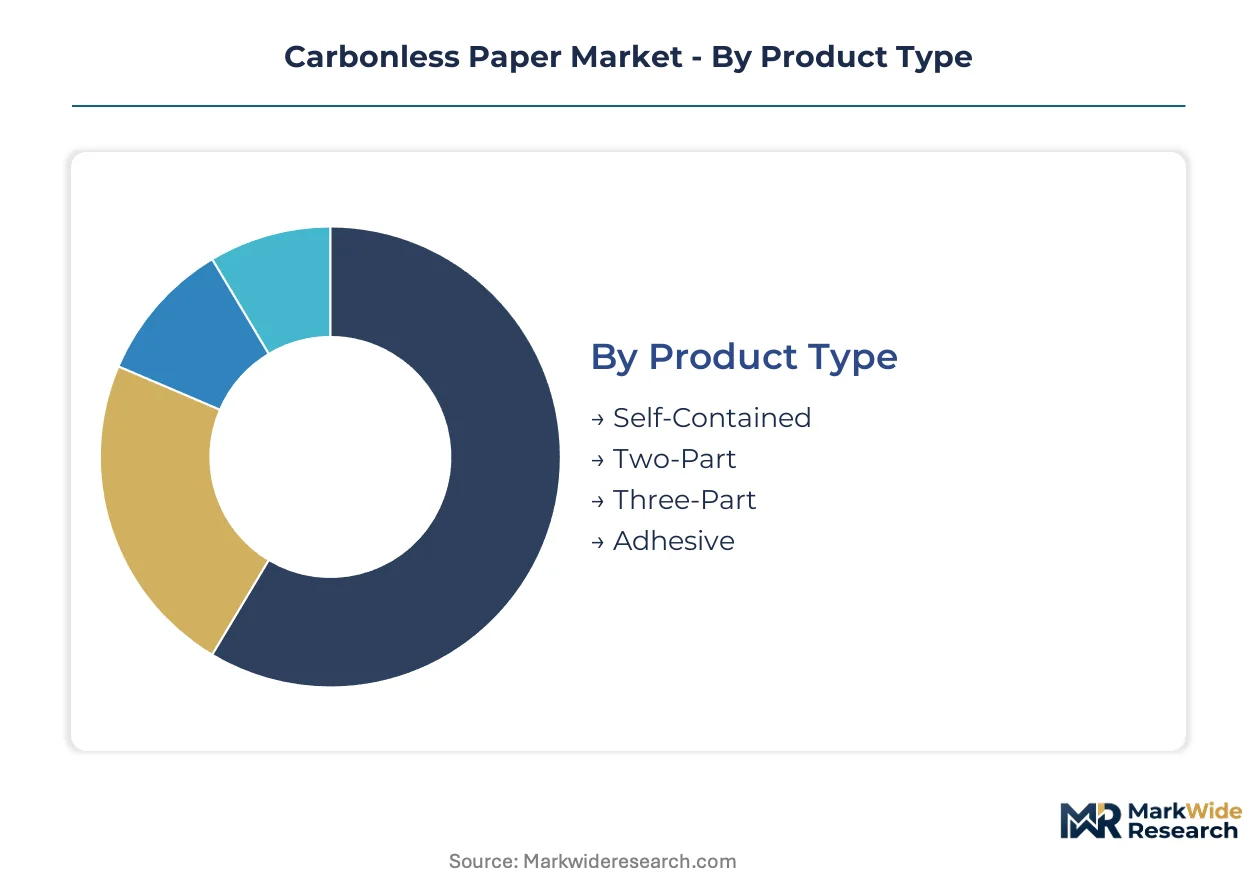
Carbonless paper segmentation reveals divergent technical requirements across standalone portable applications versus embedded multi-part form systems. Procurement patterns split between institutional bulk contracting and fragmented logistics spot purchasing.
Product Type:
Integration depth separates self-contained grades designed for standalone thermal-mechanical printing from multi-part systems requiring matched CB-CF sheet pairing.
- Three-Part:CB-CFB-CF sheet assemblies generate instant triplicate records through sequential pressure transfer. Government agencies in India specify these for land-registry and ration-card documentation where physical audit trails remain mandatory. BIS certification requirements favor domestic mill supply.
- Adhesive:Pressure-sensitive backing merges carbonless imaging with direct label application. Warehouse operators in third-party logistics networks trial single-pass picking-list and carton-label generation. E-commerce fulfillment scaling drives procurement expansion.
- Self-Contained:Single-sheet CB coating eliminates CF receiver matching for compact field printers.
- Two-Part:Standard CB-CF pairing dominates legacy invoice and receipt applications.
Volume placements concentrate in Three-Part; the faster expansion belongs to Adhesive.
End User:
Cost tier stratification separates premium-specification institutional procurement from price-sensitive logistics spot buying.
- Logistics:Parcel carriers and third-party fulfillment operators consume multi-part delivery receipts for signature capture at connectivity-limited drop points. India's e-commerce corridor expansion sustains regional converter demand. Last-mile documentation gaps resist full digitization.
- Government Agencies:State stationery departments mandate security-featured pre-printed stocks with standardized form factors. Tamil Nadu and Karnataka tender specifications require BIS-certified domestic production, excluding import competition.
- Financial Services:Banking and insurance operations transition duplicate documentation toward digital workflows.
- Educational Institutions:Examination boards and administrative offices maintain modest carbonless consumption for record generation.
Procurement scale peaks with Government Agencies; Logistics climbs fastest as e-commerce penetration deepens.
Application:
Application segmentation tracks document workflow integration from point-of-sale generation through back-office archival retention.
- Delivery Notes:Multi-part forms capture consignee acknowledgment across fragmented transportation handoffs. Indian courier networks deploy these across state border checkpoints where electronic tracking infrastructure remains incomplete. Regulatory mandates for physical proof-of-delivery sustain demand.
- Invoices:Tax documentation requirements formerly drove triplicate form consumption. India's GST e-invoicing rollout and Brazil's Nota Fiscal Eletrônica displace carbonless duplication in statutory compliance. Residual demand concentrates in informal economy transactions.
- Receipts:Point-of-sale duplicate generation persists in cash-dominant retail environments.
- Purchase Orders:Procurement documentation retains carbonless workflow in supplier quality-audit chains.
Shipment documentation dominates current volumes; field-service ticketing applications gain share fastest.
Distribution Channel:
Channel structure reflects margin capture stratification between mill-direct institutional contracting and distributor-intermediated spot supply.
- Direct Sales:Mill-branded contract supply to state governments and large logistics operators captures premium margin pools. Indian state stationery departments negotiate multi-year agreements with domestic coating operations. Converter working capital avoids distributor markup.
- Wholesalers:Regional paper merchants aggregate fragmented demand from small-format printers and independent courier services. Inventory positioning near consumption points reduces logistics operator procurement lead times. Credit terms differentiate competitive positioning.
- Online:E-procurement platforms serve mid-size converter spot purchasing with transparent pricing.
- Retail:Stationery and office supply channels address incidental consumer and small-business demand.
Contract volume concentrates in Direct Sales; channel expansion runs fastest through Online platform aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-paper mills in Japan and Germany supply coated reels to converters worldwide, while demand concentrates in Indian states where last-mile digitization lags persist. Regulatory divergence across REACH, EPA, and BIS frameworks fragments supply chain compliance requirements.
United States
Parcel carriers deploy multi-part delivery receipts across rural delivery zones with intermittent mobile coverage. EPA guidelines govern volatile organic compound emissions from coating operations, forcing mill investment in capture systems. Regional converters in the Midwest and Southeast aggregate demand from third-party logistics operators.
Germany
REACH restrictions on formaldehyde-releasing resins drive coating chemistry reformulation at specialty paper mills. State procurement offices in Bavaria and North Rhine-Westphalia specify security-featured pre-printed stocks for administrative documentation. The country's coating expertise supports export supply to EU institutional buyers.
India
E-commerce fulfillment networks in Maharashtra and Karnataka sustain demand for triplicate delivery forms despite GST e-invoicing rollout. BIS certification requirements create compliance barriers for imported coated reels, favoring domestic converters in Tamil Nadu. Last-mile administrative gaps in Bihar and Uttar Pradesh sustain land-record and ration-card form consumption.
Japan
Oji Holdings Corporation anchors Asia-Pacific supply through integrated pulp-to-paper operations serving regional courier networks. METI industrial standards govern microencapsulated coating quality specifications. Mill clusters in the Kanto region export coated reels to Southeast Asian converters.
Brazil
Nota Fiscal Eletrônica mandates displace carbonless duplication in statutory tax documentation, compressing formal economy demand. Residual consumption concentrates in informal retail and cash-dominant service sectors. Regional paper merchants in São Paulo and Rio de Janeiro aggregate spot demand from independent logistics operators.
Carbonless Paper Market Vendor Landscape
Top-tier vendors anchor integrated pulp-to-paper supply, while regional converters and specialty coating operations occupy mid-tier and niche positions. European and Japanese mills concentrate coating expertise and captive chemical synthesis capabilities. Strategic archetypes span integrated chemical-paper groups, specialty coating converters, and adhesive-hybrid format innovators. Competitive moves center on REACH-compliant reformulation partnerships and direct mill contracting with state procurement offices.
Within the integrated supply tier, Oji Holdings Corporation and Koehler Paper exemplify geographic anchoring strategies—Japanese and German operations respectively—while Pixelle Specialty Solutions occupies a specialist position in narrow-web customization. Mitsubishi HiTec Paper and Stora Enso Oyj represent European coating expertise applied to institutional procurement channels. Jianghe Paper and Golden Paper Group anchor Chinese supply to domestic and export converter networks. These six names illustrate how competitive positioning fragments across integrated chemical control, regional distribution depth, and format specialization.
| Leading Market Players |
|---|
| Jianghe Paper |
| Oji Holdings Corporation |
| Appvion Paper |
| Golden Paper Group |
| Pixelle Specialty Solutions |
| Koehler Paper |
| Mitsubishi HiTec Paper |
| Stora Enso Oyj |
| Lecta |
| Others |
Supply Flow & Price Mechanics
Microencapsulation technician scarcity in Germany's Rhineland chemical corridor widens labor-cost spreads between European coating operations and Asian integrated mills, compressing converter margins on REACH-compliant grades while sustaining three-tier pricing differentiation across premium-certified, standard-domestic, and economy-import tiers.
Pricing Analysis
Margin tightening in standard-grade multi-part forms reflects phenol derivative feedstock volatility from refinery output fluctuations. Contract-based long-term offtake dominates institutional procurement, with price differentiation resting on BIS certification grade and volume scale. Cost-down pressure on economy imports accelerates because Indian customs hold coated reels for 8-14 week laboratory testing cycles. Logistics operators show highest price sensitivity due to fragmented spot purchasing; government stationery departments demonstrate lowest sensitivity through multi-year mill-direct agreements.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Indonesian integrated pulp-to-paper groups controlling Asia-Pacific coated reel supply. Raw material dependencies draw from petrochemical dye precursors, formaldehyde-releasing resin systems, and hardwood pulp feedstocks. Regulatory restriction through REACH formaldehyde bans and BIS import certification creates supply chain risk. Distribution runs through direct mill contracting for institutional buyers and regional wholesaler aggregation for logistics spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbonless paper competitive positioning is becoming a vertical-integration race, with coating chemistry control and captive microencapsulation expertise emerging as the decisive upstream lever separating margin-sustainable players from converter-margin casualties.
For Market Incumbents: To counter REACH-compliant reformulation cost premiums, German and Japanese mills should deepen backward integration into formaldehyde-free capsule wall chemistry synthesis. Securing BIS certification for Indian subsidiary operations defends against domestic converter competition in Tamil Nadu and Karnataka tender processes. For New Entrants and Emerging Players: Adhesive-backed carbonless hybrid technology offers entry into warehouse labeling convergence applications where third-party logistics operators trial single-pass picking-list and carton-label systems. Targeting Bihar and Uttar Pradesh state government contracts exploits last-mile digitization gaps with regional distribution partnerships. For Investors and Strategic Acquirers: The window for entry favors specialty coating converters with existing BIS-certified Indian production assets and established logistics channel relationships. Watch India's GST e-invoicing enforcement velocity as the inflection indicator for triplicate form demand compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Capsule Chemistry | REACH-compliant formaldehyde-free wall systems unlock continued EU institutional procurement access. |
| BIS Certification Investment | Domestic Indian coating operations bypass 8-14 week customs hold cycles for imported reels. |
| Adhesive-Hybrid Format Development | Warehouse labeling convergence merges picking-list generation with carton labeling for 3PL operators. |
| Direct Mill Contracting Expansion | Multi-year agreements with state stationery departments capture premium margin pools and working capital efficiency. |
| Field-Service Ticketing Partnership | Utility and telecom maintenance crew adoption of adhesive-backed rolls builds recurring consumables demand. |
Methodological Framework
Independent corroboration across mill coating operations, logistics procurement directors, and government stationery department tenders underwrites the qualitative findings in this analysis. Primary fieldwork engaged microencapsulation line technicians, converter plant managers, and regulatory compliance officers at European and Asian coating facilities. Secondary validation drew from customs trade data, BIS certification registries, and EPA emission disclosure filings. Bottom-up demand modeling triangulated against top-down pulp-to-paper capacity assessments.
Rate-of-change decomposition across product type, end-user vertical, application workflow, and distribution channel dimensions structured the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by pricing-tier spreads. Industry-specific forecast inputs incorporated e-commerce fulfillment network expansion rates and country-by-country e-invoicing mandate enforcement schedules throughout the projection horizon.
Several conditions sit outside the modeled scope, including potential breakthroughs in fully digital proof-of-delivery systems, abrupt shifts in Indian state-level digitization timelines, and unforeseen relaxations of REACH dye chemistry restrictions. Forecasts reflect documented assumptions about logistics infrastructure buildout pacing and regulatory enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Writing Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Paper Core Market
Paper Products
Wood-Based Panel Market
Paper Products
White Top Testliner Market
Paper Products
Stone Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Photographic Paper Market
Paper Products
Decor Paper Market
Paper Products
Thermal Paper Market
Paper Products
Filtration Paper Market
Paper Products
Pulp and Paper Market
Paper Products
Global Paperboard Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Pulp Market