
 Drum Pulper Market | 2026-2036
Drum Pulper Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Pulper Market Foresight
Recycling industry demand is pivoting toward higher-capacity drum pulpers as post-consumer fiber recovery becomes central to mill economics. Valmet Oyj leverages its installed base across Nordic pulp mills to sustain aftermarket revenue streams. Andritz AG anchors its position through integrated fiberline solutions that span pulping through drying. Kadant Inc. differentiates via roll cleaning and doctoring technologies that complement pulper throughput optimization.
A drum pulper is a cylindrical pulping vessel that rotates at controlled speeds to separate fibers from contaminants using mechanical agitation and water circulation, typically processing recovered paper at consistencies between 14% and 18%. Its primary purpose is to defiber raw material while preserving fiber length and rejecting plastics, adhesives, and other non-pulp debris. Continuous pulpers command the largest installed footprint due to their compatibility with high-volume linerboard and corrugated medium lines. Mechanical pulping technology retains cost advantages in recycled furnish applications where chemical treatment adds unnecessary expense. Fiber recovery applications attract capital allocation as mills pursue yield improvements that reduce virgin pulp dependency.
EPA effluent guidelines in the United States limit wastewater discharge from pulping operations, pushing mills toward closed-loop drum pulper designs that reduce water consumption. REACH and the EU Green Deal in Europe impose chemical restriction and carbon accounting requirements that shape equipment specification and supplier qualification. China's MEE enforces emission intensity targets that favor energy-efficient pulping configurations. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions alter recovered paper availability and quality specifications.
Market Dynamics
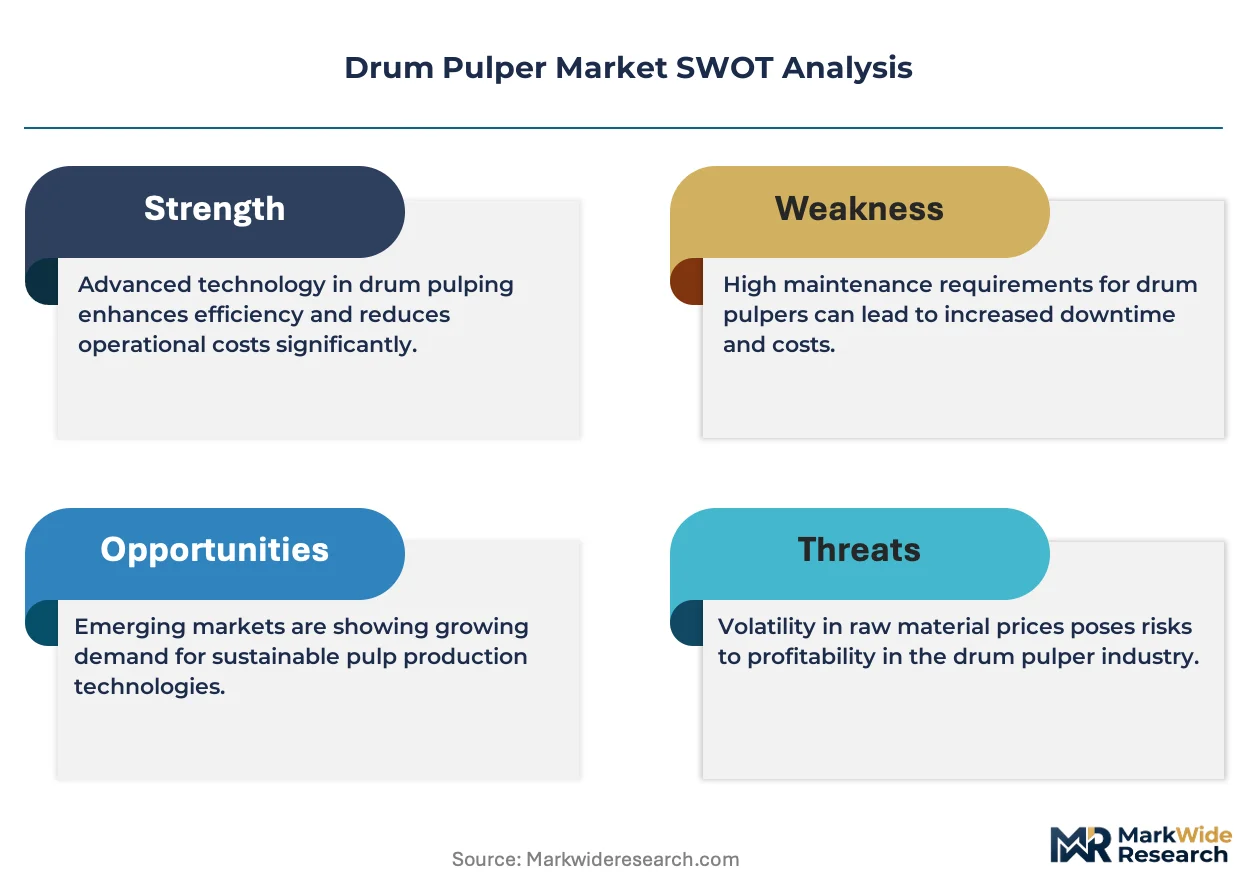
Post-consumer fiber recovery mandates across multiple jurisdictions are forcing mills to reconfigure pulping lines for higher contamination tolerance and lower water intensity, compressing equipment replacement cycles and reshaping supplier qualification criteria.
Growth Catalysts
- China's dual carbon goals:Beijing's emission intensity targets under MEE oversight accelerate mill upgrades toward energy-efficient drum pulper configurations that reduce thermal load per ton of recovered fiber processed.
- Linerboard capacity expansion:Southeast Asian packaging mills are commissioning high-volume continuous pulpers to serve e-commerce corrugated demand, drawing equipment orders from European and Japanese suppliers.
- Closed-loop water systems:EPA effluent guidelines in the United States restrict wastewater discharge, pushing brownfield mills toward drum pulper retrofits that enable water recirculation rates above 85 percent.
Market Restraints
- Stainless steel input volatility:Drum shell fabrication depends on austenitic grades whose nickel and molybdenum content exposes OEMs to London Metal Exchange price swings that compress fabrication margins.
- European supplier concentration:Precision gearbox and bearing assemblies for high-torque drum drives concentrate among German and Austrian component houses, creating single-source exposure for non-European pulper builders.
- Contaminant heterogeneity:Rising adhesive and plastic loading in post-consumer mixed paper reduces pulper throughput consistency and accelerates wear on screening and cleaning downstream, degrading fiber yield economics.
Strategic Opportunities
- India's packaging board modernization:Domestic containerboard capacity additions under BIS quality enforcement create first-mover positioning for suppliers offering 500+ tonne per day drum pulper installations with integrated reject handling.
- Digital twin integration:Convergence of vibration monitoring with machine learning-based predictive maintenance enables remote optimization of drum speed and consistency profiles, opening subscription revenue streams for OEMs.
- EU Green Deal carbon accounting:CSRD disclosure requirements favor pulping equipment with documented embodied carbon and operational efficiency metrics, creating specification advantages for suppliers with lifecycle data transparency.
Industry Challenges
- Rotary seal technician scarcity:Specialized knowledge for high-pressure stuffing box maintenance and hydrodynamic seal refurbishment concentrates among aging workforces in Nordic pulp clusters, constraining service response times for greenfield installations.
- Legacy DCS integration:Brownfield mills running proprietary distributed control systems from the 1990s face protocol incompatibility with modern drum pulper automation, extending commissioning timelines and requiring custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Pulper Market |
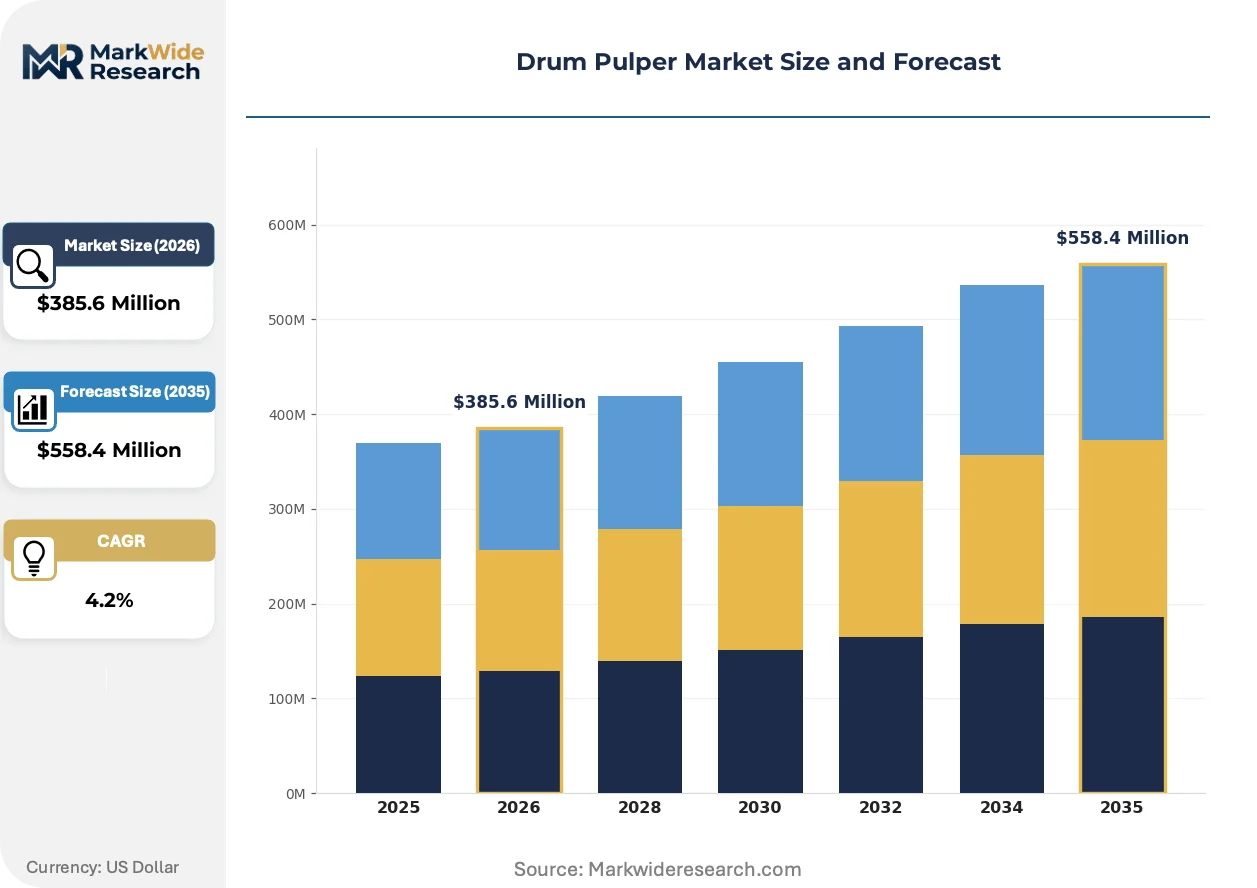
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Pulper, Continuous Pulper, High-Consistency Pulper, Low-Consistency Pulper End User: Pulp Mills, Recycling Industry, Paper Manufacturing, Waste Management Services Technology: Mechanical, Chemical, Thermo-Mechanical, Bio-Pulping Application: Pulping Process, Papermaking, Waste Treatment, Fiber Recovery |
| Companies Covered | Valmet Oyj, Andritz AG, Voith GmbH & Co. KGaA, Kadant Inc., BHS-Sonthofen GmbH, Somerville Machinery Company, Pallmann Maschinenfabrik GmbH, GL&V Inc., Parason Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Pulper Market Shifts & Advancements
Electrification of mechanical drive systems and sensor-based process control are compressing the performance gap between drum pulpers and more capital-intensive alternative pulping technologies, enabling broader application across furnish grades.
High-torque permanent magnet synchronous motor retrofits are electrifying the drum drive architecture, replacing traditional gearbox-and-VFD arrangements with direct-drive configurations that cut maintenance intervals and enable finer speed modulation for sensitive furnish types. Nordic linerboard producers are piloting these systems at 15 percent consistency to extend fiber length preservation. The technology is electrifying competitive positioning by allowing mid-capacity pulpers to match the energy efficiency curves previously exclusive to 1,000+ tonne per day installations.
REACH chemical restriction enforcement through ECHA is tightening allowable formulations for pulping aids and defoamers, compelling mills to qualify bio-based alternatives that perform across variable water chemistries. The industrial consequence is extended trial periods and higher formulation switching costs for integrated mills running multiple furnish lines. Containerboard producers in Germany and the Netherlands are most affected, responding by consolidating chemical supplier panels to reduce qualification burden.
Buyer preference is hardening around total cost of ownership contracting that bundles equipment, consumables, and remote monitoring into per-tonne service agreements rather than capital purchase. This displaces traditional EPC procurement through engineering firms with direct OEM relationships and long-term performance guarantees. The shift is most visible in Japanese packaging mills, where METI energy efficiency benchmarking creates transparency that supports outcome-based vendor selection.
Drum Pulper Market Segmentation
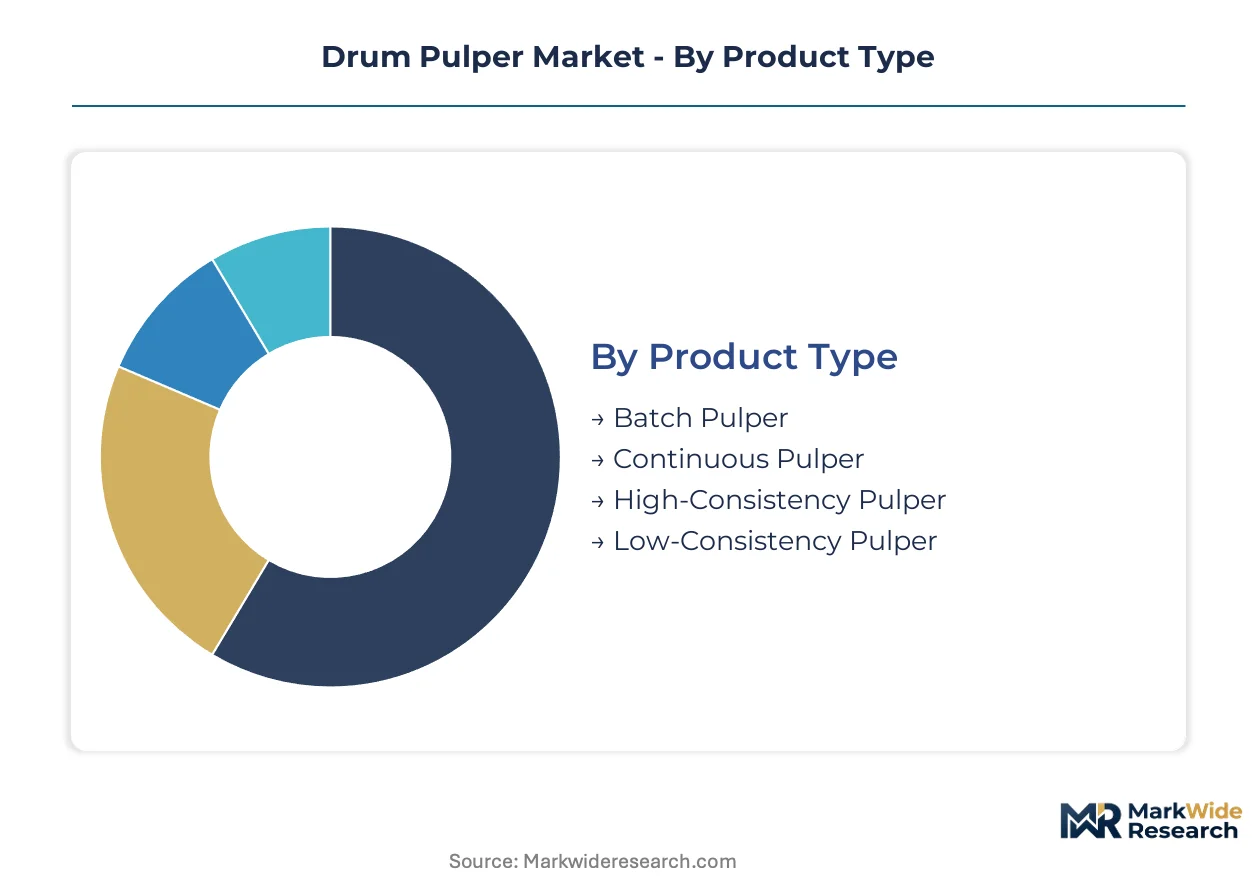
Equipment configuration in the drum pulper market hinges on mill throughput requirements, furnish contamination profiles, and water recirculation mandates. Buyers prioritize total cost of ownership over capital expenditure, shifting procurement toward performance-guaranteed service contracts.
Product Type:
Capacity planning drives pulper selection more than any other factor, with continuous operation commanding premium positioning for high-volume corrugated producers.
- Continuous Pulper:These systems operate without batch cycles, maintaining steady fiber flow through rotating drum architecture at 14-18% consistency. Southeast Asian linerboard mills favor continuous configurations for e-commerce packaging lines running above 500 tonnes daily. Energy efficiency curves and reduced labor intervention sustain their commercial dominance.
- High-Consistency Pulper:Operating at 15-20% fiber consistency, these units minimize water heating loads and enable compact equipment footprints. Nordic mills piloting permanent magnet direct-drive retrofits at elevated consistency target fiber length preservation for specialty paper grades. The configuration attracts sustainability-focused producers under EU Green Deal carbon accounting frameworks.
- Batch Pulper:Intermittent operation suits smaller mills with variable furnish mixes and lower capital budgets.
- Low-Consistency Pulper:Dilute slurry processing at 4-8% consistency serves integrated mills with extensive downstream screening capacity.
Continuous Pulper leads on scale; High-Consistency Pulper leads on momentum.
End User:
Customer type determines specification rigor, with virgin pulp producers demanding precision engineering that recycled fiber processors trade for contamination tolerance.
- Paper Manufacturing:Containerboard and corrugated medium producers constitute the dominant installed base, specifying drum pulpers with integrated reject handling for adhesive-laden post-consumer furnish. Indian packaging board modernization under BIS quality enforcement is drawing 500+ tonne per day installations toward this segment. The sector's capital allocation favors bundled service agreements over equipment-only procurement.
- Recycling Industry:Dedicated recovered fiber processors operate drum pulpers as front-end defibering before sorting and cleaning circuits. China's dual carbon goals and MEE emission intensity targets are accelerating mill upgrades toward energy-efficient configurations that reduce thermal load per ton processed. Yield optimization and virgin pulp substitution drive capital commitment here.
- Pulp Mills:Virgin fiber operations require gentler pulping action to preserve fiber length for premium paper grades.
- Waste Management Services:Municipal and industrial waste processors deploy drum pulpers for fiber extraction from mixed waste streams.
Paper Manufacturing dominates volume; Recycling Industry expands most quickly.
Technology:
Process chemistry selection reflects furnish economics, with mechanical methods retaining cost advantage where chemical treatment adds unnecessary expense.
- Mechanical:Physical fiber separation through controlled drum rotation and hydraulic shear dominates recycled furnish applications. The technology avoids chemical input costs and simplifies effluent compliance under EPA guidelines limiting wastewater discharge. Brownfield mills favor mechanical pulping for closed-loop water system retrofits achieving above 85% recirculation rates.
- Chemical:Alkaline or neutral sulfite cooking softens lignin bonds for virgin hardwood pulping. REACH enforcement through ECHA is tightening allowable formulations for pulping aids, compelling extended trial periods for bio-based alternatives.
- Thermo-Mechanical:Steam pre-treatment combined with mechanical refining serves integrated mills producing newsprint and directory papers.
- Bio-Pulping:Fungal enzyme pre-treatment remains experimental, constrained by consistency control and batch variability.
Mechanical leads on installed base; Chemical retains niche premium positioning.
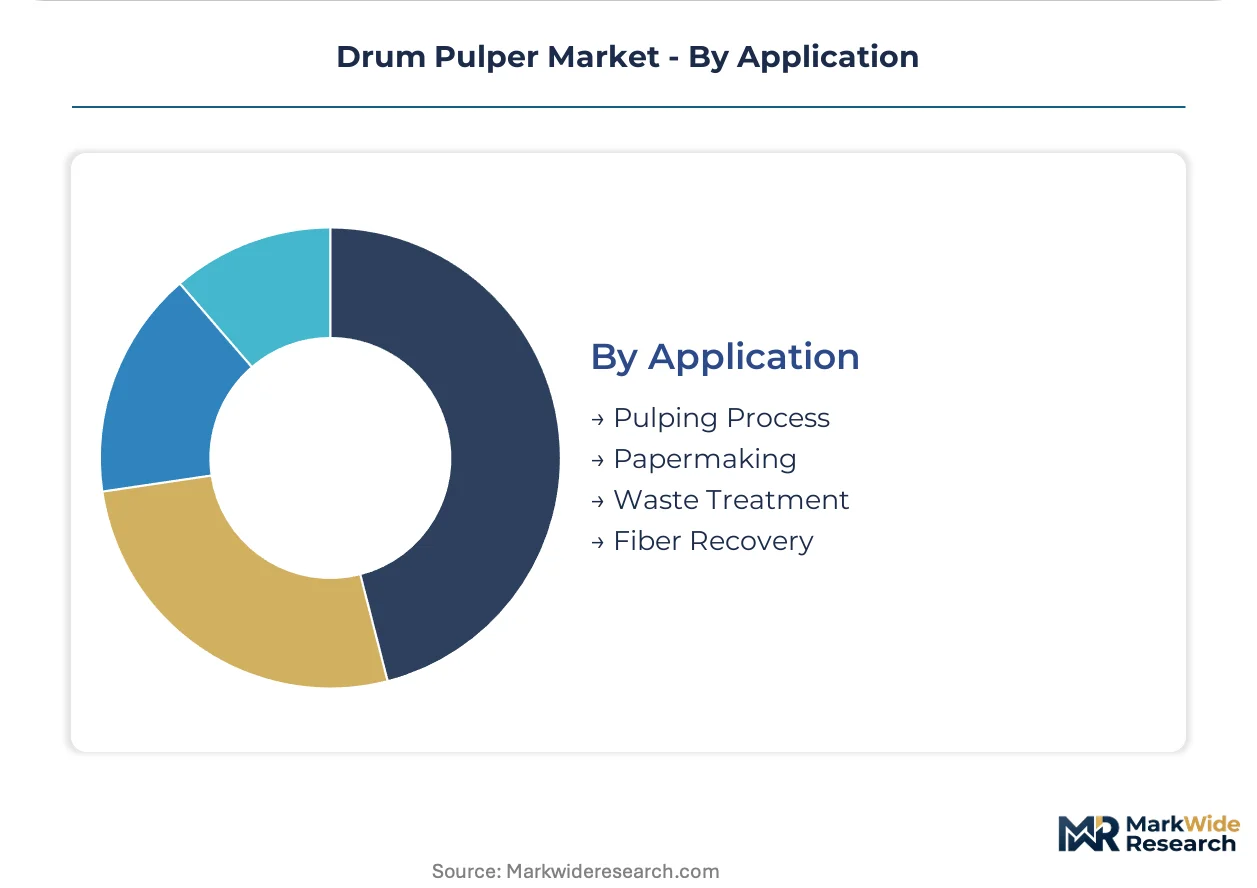
Application:
Downstream integration depth shapes pulper specification, with fiber recovery applications attracting capital as mills pursue yield improvements.
- Fiber Recovery:Extracting usable fiber from mixed waste streams and process residues has become central to mill economics. Drum pulpers in this application tolerate higher contaminant loads while preserving fiber length for re-entry to papermaking furnish. Extended producer responsibility frameworks across multiple jurisdictions are altering recovered paper availability and quality specifications.
- Pulping Process:Primary defibering of raw material represents the core drum pulper function, with continuous operation enabling integration into high-speed linerboard lines.
- Papermaking:Integrated mills specify pulpers matched to specific paper machine furnish requirements.
- Waste Treatment:Contaminant rejection and sludge reduction applications serve mills facing stringent effluent guidelines.
Pulping Process anchors volume; Fiber Recovery gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic pulp clusters anchor drum pulper demand through their concentration of high-volume linerboard producers and established equipment service networks. Regulatory pressure on emission intensity and water recirculation is reshaping procurement patterns across major paper-producing jurisdictions. Equipment orders increasingly favor configurations that balance throughput scale with closed-loop environmental compliance.
China
Containerboard mills in Shandong and Jiangsu provinces are scaling drum pulper capacity to process rising post-consumer fiber volumes. The Ministry of Ecology and Environment enforces dual carbon emission intensity targets that accelerate upgrades toward energy-efficient pulping configurations. Zhejiang's packaging corridor hosts multiple brownfield retrofits integrating high-consistency pulpers with reject handling systems.
Germany
Corrugated medium producers in the Rhineland and Bavaria specify drum pulpers with integrated fiber recovery to meet EU Green Deal carbon accounting requirements. ECHA's REACH enforcement tightens allowable formulations for pulping aids, compelling extended qualification trials for bio-based alternatives. The Hamburg-Bremen port cluster processes substantial recovered paper imports through modernized continuous pulper installations.
United States
Southeastern linerboard mills from Georgia to the Carolinas commission high-volume continuous pulpers to serve e-commerce packaging demand. EPA effluent guidelines limit wastewater discharge, pushing brownfield facilities toward retrofits achieving above 85 percent water recirculation rates. The Pacific Northwest pulp corridor maintains specialized technician pools for high-pressure rotary seal maintenance.
India
Domestic containerboard capacity additions in Maharashtra and Gujarat under BIS quality enforcement create demand for 500-plus tonne per day drum pulper installations. Central Electricity Authority efficiency benchmarking shapes vendor selection toward equipment with documented energy consumption metrics. The Tamil Nadu packaging belt attracts first-mover suppliers offering bundled service agreements with integrated reject handling.
Japan
Packaging mills in the Kanto and Kansai regions pilot permanent magnet direct-drive retrofits at elevated consistency under METI energy efficiency benchmarking. Outcome-based procurement is displacing traditional EPC contracting through direct OEM relationships with long-term performance guarantees. The Chubu industrial corridor concentrates technician expertise for hydrodynamic seal refurbishment and predictive maintenance integration.
Drum Pulper Market Competitive Landscape
Technology licensing dominates the current landscape as specialized component suppliers extend their influence across drum drive architectures and sealing systems. The vendor base organizes around three strategic archetypes: integrated fiberline solution providers, precision component specialists, and regional fabrication houses serving emerging market price points. Consolidation pressure concentrates among mid-cap European builders seeking scale to match aftermarket service networks. Geographic expansion and portfolio diversification represent the dominant competitive vectors as suppliers position for India's packaging board modernization and Southeast Asian linerboard capacity additions.
Within the integrated solution tier, Valmet Oyj and Andritz AG occupy positions defined by fiberline breadth from pulping through drying. Kadant Inc. exemplifies the precision component archetype through its specialization in roll cleaning and doctoring technologies that complement pulper throughput optimization. Among German-based fabricators, BHS-Sonthofen GmbH and Pallmann Maschinenfabrik GmbH represent regional engineering depth in mechanical processing equipment. Voith GmbH & Co. KGaA anchors the premium-tier segment through its concentration of gearbox and bearing assembly expertise. Parason Machinery and GL&V Inc. sit within the emerging market specialist tier, with Parason's Indian base positioning it for domestic containerboard expansion and GL&V's North American footprint serving EPA-driven retrofit demand.
| Leading Market Players |
|---|
| Valmet Oyj |
| Andritz AG |
| Voith GmbH & Co. KGaA |
| Kadant Inc. |
| BHS-Sonthofen GmbH |
| Somerville Machinery Company |
| Pallmann Maschinenfabrik GmbH |
| GL&V Inc. |
| Parason Machinery |
| Others |
Supply & Pricing Matrix
Austenitic stainless steel grades containing nickel and molybdenum cascade from London Metal Exchange volatility through drum shell fabrication costs into tiered equipment pricing for Southeast Asian linerboard mills and Nordic pulp clusters.
Pricing Analysis
Distributor margins of 12-18 percent separate OEM direct pricing from mill procurement through engineering firms, with direct relationships commanding 8-15 percent discounts for bundled service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects gearbox precision grades and energy efficiency certification tiers. Cost compression in standard-tier configurations intensifies because German and Austrian component houses concentrate high-torque bearing assembly supply. Recycling industry buyers exhibit highest price sensitivity due to yield-margin pressure, while virgin pulp mills prioritize fiber length preservation over capital cost.
Supply Chain Analysis
Regional distribution centers in Germany, Austria, and Japan anchor hub-and-spoke patterns for precision gearbox and hydrodynamic seal components serving drum drive architectures. Fabrication draws from Chinese stainless steel mills, Finnish specialty steel producers, and Japanese bearing manufacturers. Single-source vulnerability concentrates in German-Austrian precision component houses for high-torque drum drives. Distribution runs through OEM direct channels for integrated fiberline solutions and regional fabrication houses for emerging market price points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where post-consumer fiber recovery mandates force mills toward contamination-tolerant, energy-efficient drum pulper specifications that command premium positioning.
For Market Incumbents: Anticipate margin compression from emerging Asian fabrication houses by deepening captive supply of precision gearbox assemblies and securing long-term austenitic steel offtake agreements. Prioritize certification investment for EU Green Deal carbon accounting transparency to defend specification advantages against mid-cap European builders consolidating for scale.
For New Entrants and Emerging Players: The 15-20 percent price-point gap between premium European integrated solutions and economy-tier regional fabricators opens white-space positioning for Indian packaging board modernization and Southeast Asian linerboard capacity additions. Target 500-plus tonne per day continuous pulper installations with bundled reject handling and remote monitoring subscriptions as the most penetrable segment.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap European fabricators lack aftermarket service networks to match Valmet Oyj and Andritz AG installed base coverage. Five-to-ten year viability favors acquisition targets with permanent magnet direct-drive retrofit capabilities and documented lifecycle carbon metrics. Watch for MEE emission intensity enforcement acceleration as inflection signal for energy-efficient configuration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Gearbox Manufacturing | Reduces single-source exposure to German-Austrian component houses for high-torque drum drives. |
| Permanent Magnet Direct-Drive Retrofit Program | Enables Nordic and Japanese mills to achieve fiber length preservation at elevated consistency under METI benchmarking. |
| Digital Twin Integration with Predictive Maintenance | Opens subscription revenue streams through vibration monitoring and machine learning-based remote optimization. |
| Long-Term Service Agreement Bundling | Displaces traditional EPC procurement through per-tonne performance guarantees in Japanese packaging mills. |
| EU Green Deal Carbon Accounting Certification | Creates specification advantages for suppliers with documented embodied carbon and operational efficiency metrics. |
Research Methodology
Multiple input streams — maintenance directors at Nordic linerboard mills, OEM procurement teams, aftermarket service heads, and plant engineers at Southeast Asian packaging facilities — were reconciled with customs trade data, SEC equipment supplier filings, and MEE emission intensity enforcement records. Secondary validation drew from pulp and paper industry association capacity databases, BIS quality enforcement documentation, and METI energy efficiency benchmarking disclosures. Bottom-up equipment shipment analysis and top-down mill capacity modeling were triangulated to establish market sizing.
Data-stream reconciliation across the analysis window applied segmentation dimensions of pulper configuration type, end-user industry, process technology, and regional regulatory framework. CAGRs were derived from installed base replacement cycles, brownfield retrofit timelines, and greenfield capacity commissioning patterns. Forecast inputs incorporated stainless steel price volatility indices and extended producer responsibility framework adoption trajectories.
Caveats apply where MEE enforcement intensity, REACH chemical restriction expansion, or London Metal Exchange nickel price spikes could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
North America Specialty Paper Market
Paper Products
Paper Pigment Market
Paper Products
Thermal Paper Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Household Paper Market
Paper Products
Solar Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
Printing Paper Market