
 Solar Trash Compactors Market | 2026-2036
Solar Trash Compactors Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Trash Compactors Market Intelligence
A shift from single-source procurement to multi-vendor strategies is broadening the supplier base for municipal and commercial buyers. This transition allows public works departments and facility managers to select best-fit technologies for specific locations rather than standardizing on one provider. Bigbelly Inc. leverages its established footprint in North American and European smart city deployments. Ecube Labs competes on the basis of its cloud-based data analytics and fleet management platform, while Waste Management Inc. integrates these technologies into its broader service offerings for large commercial clients.
A solar trash compactor is a self-contained waste receptacle that uses photovoltaic panels to power an internal ram, which compacts refuse and increases bin capacity. Its primary purpose is to reduce collection frequency and associated operational costs in high-traffic public spaces. Smart, sensor-based units represent the fastest-growing technology segment, offering real-time fill-level data and collection route optimization. Demand from urban areas and commercial facilities significantly outpaces that from other end-user segments due to higher waste volumes and clear return on investment calculations.
Regulations such as the EU Green Deal and RoHS directive influence component selection and product lifecycle management. In the United States, EPA guidelines on waste reduction encourage municipal adoption, while China's dual carbon goals support investments in energy-efficient urban infrastructure. Stakeholder decisions will increasingly center on integrating compactor data into wider smart city platforms to optimize logistics and labor. The ability to demonstrate total cost of ownership savings is critical for securing public and private sector contracts.
Market Dynamics
The convergence of urban densification and stringent sustainability mandates, particularly within the European Union, is the central force compelling municipal adoption. This dynamic creates a clear operational need for technologies that enhance waste collection efficiency while meeting green public procurement standards.
Growth Catalysts
- Smart City Initiatives:Public sector investment in smart city infrastructure, especially in Germany and the Nordic states, creates dedicated funding streams and integration pathways for connected waste management solutions.
- Sustainability Mandates:Regulations like the EU Green Deal pressure public and private entities to reduce the carbon footprint of their operations, favoring solutions that lower vehicle emissions from collection fleets.
- IoT Integration:The maturity of low-power wireless networks and sensor technology enables real-time data analytics, providing a clear return on investment through optimized collection routes and labor allocation.
Market Restraints
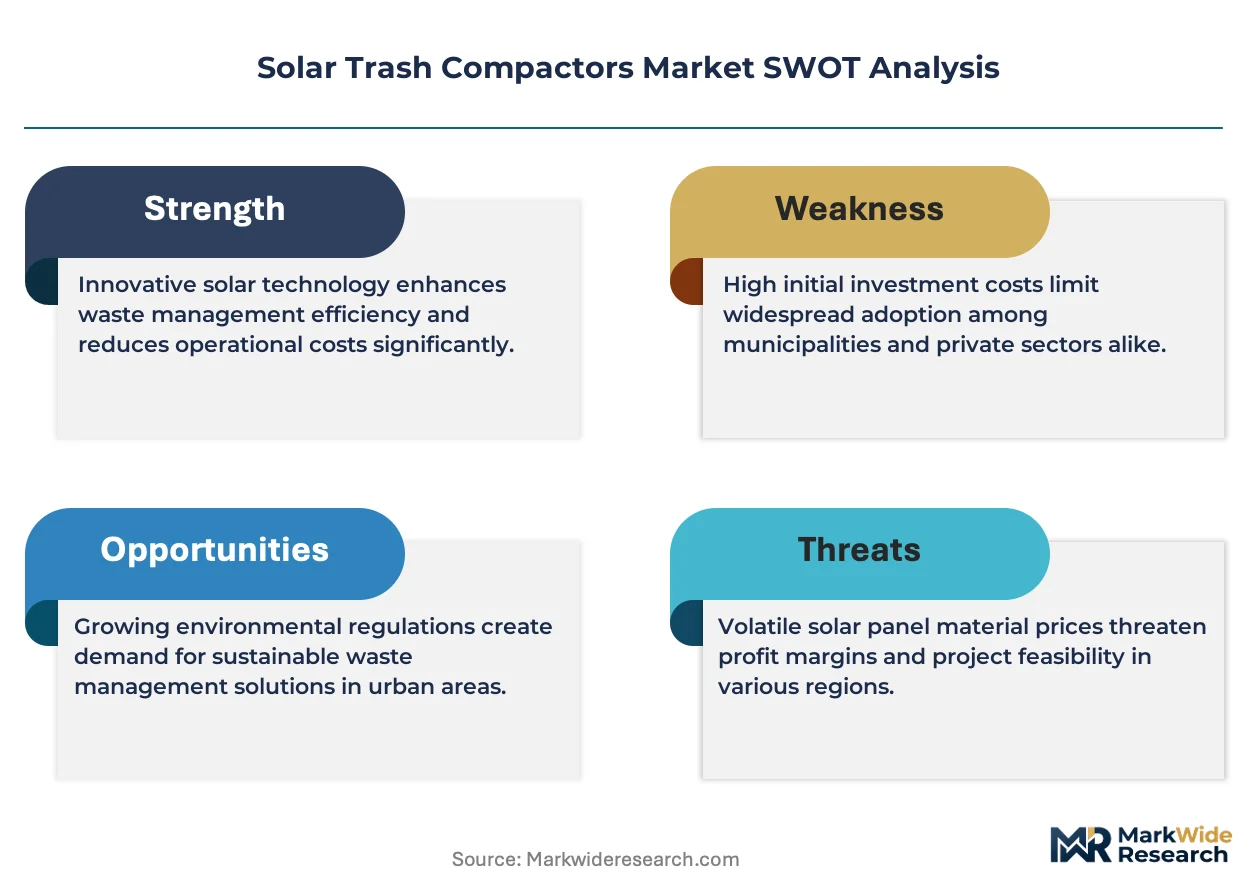
- High Initial Capital Outlay:The upfront cost of solar compactors is significantly higher than traditional bins, creating a budget hurdle for smaller municipalities or commercial entities without clear long-term financing.
- Solar Irradiation Dependency:Performance is contingent on adequate sunlight, posing a limitation in dense urban canyons, northern latitudes with limited winter daylight, or heavily shaded public spaces.
- Component Sourcing:The supply chain for specialized components, including durable photovoltaic panels and ruggedized electronic controllers, is concentrated and can be subject to price volatility or disruptions.
Strategic Opportunities
- Expanded End-Use Verticals:Untapped demand exists in large-scale private venues such as university campuses, theme parks, and major transportation hubs seeking to optimize waste handling and improve aesthetics.
- Data Monetization:The aggregation of fill-level and usage data offers opportunities to develop secondary services, such as predictive analytics for municipal planning or advertising on digital bin displays.
- Circular Economy Integration:Future designs can incorporate features for waste sorting at the point of disposal, aligning with circular economy goals and supporting cleaner recycling streams.
Industry Challenges
- Integration with Legacy Systems:Connecting new compactor data streams with outdated municipal software platforms for work orders and fleet management presents a significant technical and operational hurdle.
- Maintenance and Vandalism:Ensuring the long-term operational integrity of units in public spaces requires robust designs and a responsive service infrastructure to address both mechanical wear and public misuse.
- Data Standardization:A lack of interoperability standards across different vendor platforms complicates data aggregation for municipalities pursuing multi-vendor procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Trash Compactors Market |
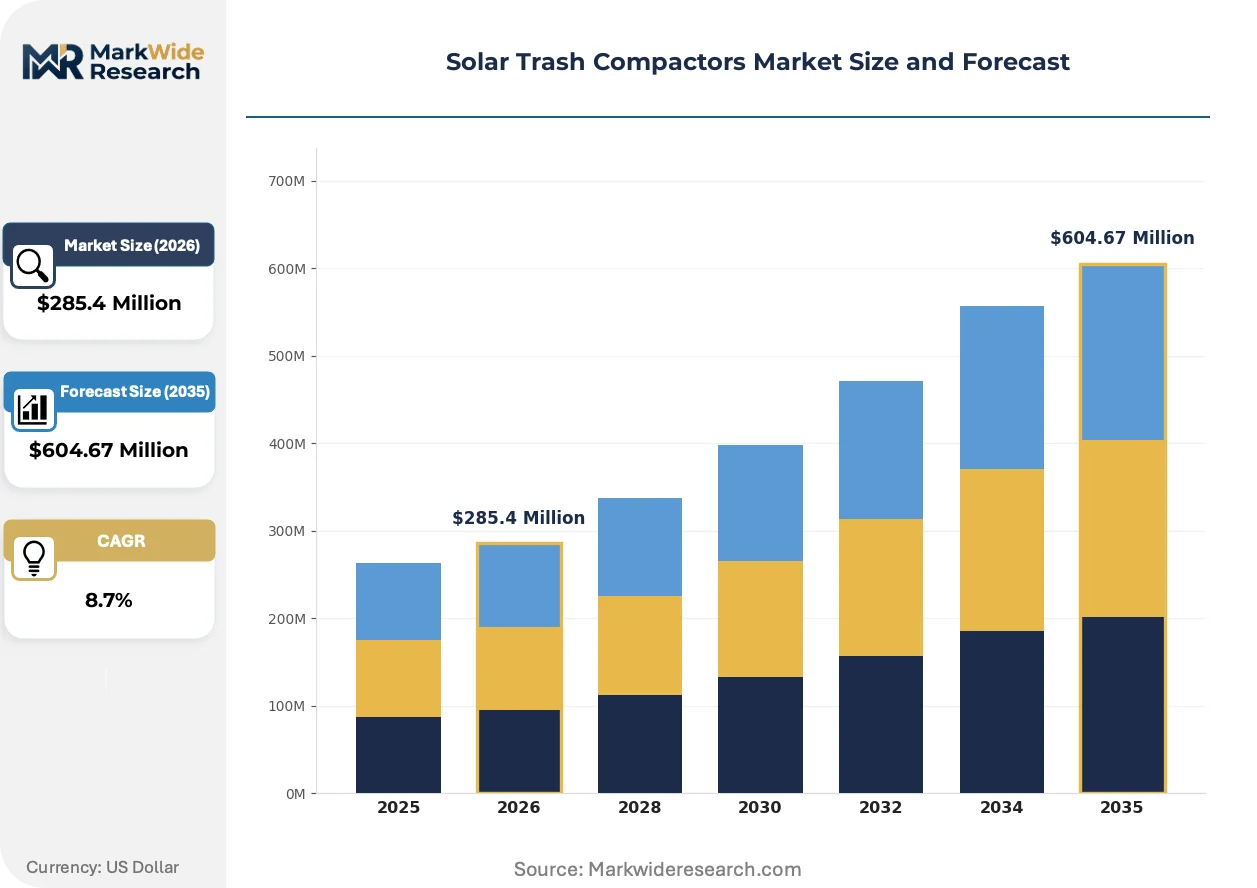
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary, Mobile, Smart, Traditional Technology: Solar-Powered, Sensor-Based, Manual, Automated End User: Parks, Urban Areas, Beaches, Commercial Facilities Installation: Ground-Mounted, Wall-Mounted, Integrated, Standalone |
| Companies Covered | Bigbelly Inc., Ecube Labs, Bay Area Trash Compactor, Dacheng Machinery Make Co. Ltd., Shanghai Jiajing Machinery Ltd., SP Industries Inc., Bluestream, Waste Management Inc., Wastecare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Trash Compactors Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards greater operational intelligence and hardware adaptability. This shift prioritizes data-driven decision-making for waste logistics over simple volume reduction, fundamentally altering the value proposition for municipal and commercial buyers.
Advanced sensor packages combining fill-level measurement with environmental monitoring are becoming standard. Municipal and large-scale commercial facility managers are the primary adopters, seeking more granular operational data. This trend is modularizing the compactor itself, allowing buyers to customize sensor and communication capabilities based on location-specific needs rather than purchasing a one-size-fits-all unit.
European Union directives like RoHS directly influence product design and manufacturing. The regulation restricts the use of specific hazardous materials in electronic equipment, forcing a re-evaluation of component supply chains. Manufacturers and their suppliers are most affected, investing in compliance testing and sourcing alternative materials for circuit boards, sensors, and power systems.
A transition from single-provider contracts to multi-vendor procurement strategies is accelerating among public works departments. This change disrupts the model of standardizing on one supplier, favoring a best-fit approach where different technologies are deployed based on specific site requirements. This pattern is most pronounced in North American and European cities with established smart city frameworks and diverse operational needs.
Solar Trash Compactors Market Segmentation
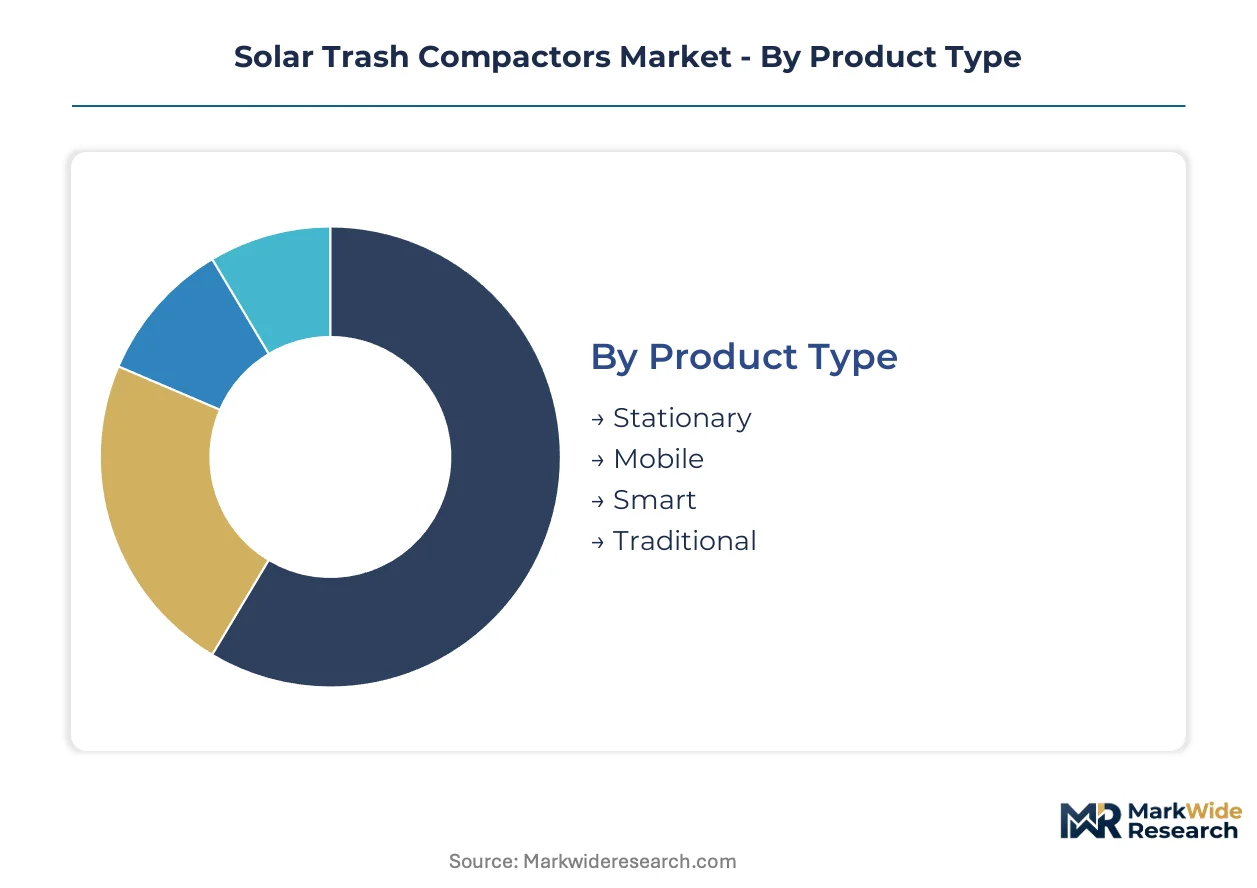
The Solar Trash Compactors Market segmentation reveals distinct operational requirements and technological preferences across various applications. Understanding these segments helps stakeholders identify specific demand pockets and tailor product development or deployment strategies. This detailed analysis highlights the diverse needs influencing compactor design and adoption.
Product Type:
Segments within product type often face varying certification burdens, particularly for electronic components and safety standards. Smart compactors, with their advanced sensing and communication capabilities, frequently require compliance with electronics directives like RoHS in Europe or FCC guidelines in the United States.
- Smart:These compactors integrate sensors for fill-level monitoring and communication modules for remote data transmission, optimizing collection routes. Demand concentrates in European smart cities and North American urban centers, driven by efficiency mandates and IoT integration.
- Stationary:Designed for fixed locations, these units typically offer larger capacities and robust construction, suitable for high-traffic public areas. Urban municipalities and large commercial facilities prioritize stationary models for their durability and consistent waste management.
- Mobile:Mobile compactors provide flexibility for deployment in temporary event spaces or areas with fluctuating waste generation.
- Traditional:These units primarily offer compaction without advanced sensor technology or connectivity, appealing to budget-conscious buyers in less regulated environments.
Stationary compactors sit at the top of the volume ranking, with Smart units climbing the fastest in terms of market penetration.
Technology:
The cost tier for solar compactors varies significantly based on the integrated technologies, with sensor-based and automated systems commanding higher initial investments due to their advanced features. Manual systems offer a lower entry point but sacrifice operational intelligence.
- Solar-Powered:These compactors utilize photovoltaic panels to generate electricity for the internal ram and smart features, reducing reliance on grid power. Public sector entities in Germany and Nordic states increasingly adopt solar-powered units for their energy independence and sustainability benefits.
- Sensor-Based:Integrating fill-level sensors and real-time data transmission, these compactors enable optimized collection schedules and dynamic route planning. Urban areas and large commercial facilities widely adopt sensor-based technology to achieve significant operational cost savings.
- Manual:Manual compactors require human intervention for activation, offering a simple and cost-effective solution for basic waste volume reduction.
- Automated:Automated systems operate on pre-programmed schedules or respond to sensor inputs for compaction, minimizing manual oversight in waste management.
Solar-Powered technology forms the foundational layer for most advanced units, while Sensor-Based solutions are experiencing the steepest expansion trajectory due to their data capabilities.
End User:
End-user segments exhibit diverse waste volumes and operational priorities, directly influencing the type and scale of compactor deployment. Urban areas and commercial facilities generate substantial waste, requiring robust and efficient solutions.
- Urban Areas:Municipalities deploy compactors in city centers, public squares, and transit hubs to manage high waste volumes and reduce collection frequency. Smart city initiatives in Berlin and Stockholm drive significant procurement in this segment.
- Commercial Facilities:Large commercial properties like shopping malls, corporate campuses, and stadiums use compactors to streamline waste handling and improve site aesthetics. Waste Management Inc. integrates these solutions into broader service offerings for its clients.
- Parks:Public parks utilize compactors to maintain cleanliness and reduce overflowing bins, particularly in high-visitation recreational zones.
- Beaches:Coastal communities deploy compactors to manage seasonal waste surges and prevent litter accumulation in environmentally sensitive areas.
Urban Areas represent the largest demand segment for solar compactors, with Commercial Facilities increasingly prioritizing these investments for clear return on investment calculations.
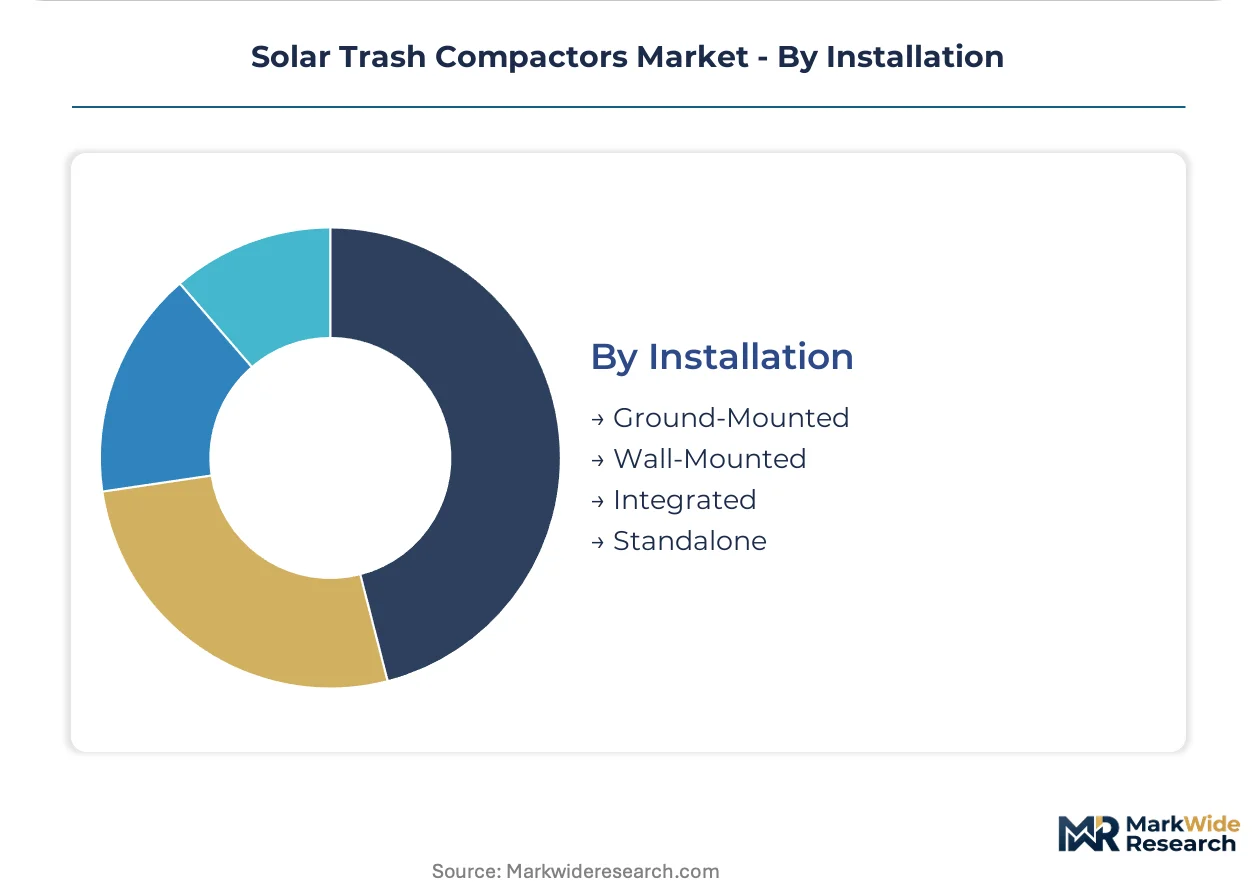
Installation:
Installation methods for solar trash compactors vary based on site-specific flexibility requirements and aesthetic considerations. Standalone units offer maximum adaptability, while integrated solutions require more planning for seamless incorporation into existing infrastructure.
- Ground-Mounted:These compactors are secured directly to the ground, providing stability and resistance to vandalism in public spaces. This installation type is prevalent in city parks and street environments across the United States and Europe.
- Standalone:Standalone units are self-contained and do not require external infrastructure, offering ease of relocation and deployment flexibility. University campuses and event venues favor standalone models for their adaptable waste management.
- Wall-Mounted:Wall-mounted compactors conserve ground space and are often used in confined urban settings or specialized commercial facilities.
- Integrated:Integrated compactors are built into existing structures or street furniture, providing a discreet and aesthetically pleasing waste solution for smart city projects.
Ground-Mounted installations remain the most common deployment, while Integrated solutions are gaining share for their aesthetic and functional integration into urban designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks increasingly influence manufacturing and deployment decisions for solar trash compactors, creating a compliance-driven landscape. Areas with stringent environmental mandates and green public procurement policies attract investment, while regions with less defined regulations may see slower adoption. This divergence impacts material sourcing and technological integration across different markets.
Germany
Public sector investment in smart city infrastructure drives demand for connected waste management solutions in Germany. The EU Green Deal heavily influences procurement, favoring solutions that reduce carbon emissions from collection fleets. Cities like Berlin and Hamburg are actively integrating smart compactors into their urban planning initiatives to optimize resource allocation.
Sweden
Sustainability mandates and IoT integration accelerate the adoption of solar compactors across Sweden. Nordic states prioritize energy independence, leading to widespread deployment of solar-powered units in public spaces. Stockholm's smart city projects exemplify the trend of integrating real-time fill-level data into broader municipal management platforms.
United States
EPA guidelines on waste reduction encourage municipal adoption of advanced compaction technologies in the United States. Multi-vendor procurement strategies allow public works departments to select best-fit technologies for specific locations. Urban centers like New York City and San Francisco are investing in sensor-based units to achieve operational cost savings.
China
China's dual carbon goals support investments in energy-efficient urban infrastructure, including solar trash compactors. Large-scale urban densification projects create significant operational needs for enhanced waste collection efficiency. Major cities such as Shanghai and Shenzhen are implementing smart waste solutions as part of their environmental protection strategies.
France
French municipalities are increasingly adopting solar compactors to manage high waste volumes in city centers and public squares. Environmental regulations and a focus on sustainable urban development drive demand for solutions that lower collection frequency. Paris and Lyon are deploying compactors to improve site aesthetics and reduce the carbon footprint of waste logistics.
Solar Trash Compactors Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-based data analytics and fleet management platforms. The market structure exhibits a tiered consolidation, where larger entities offer integrated service portfolios alongside specialized technology providers. Strategic partnerships and technology licensing agreements represent dominant competitive moves among market participants.
Within the integrated service provider archetype, Waste Management Inc. leverages its broad commercial client base to offer comprehensive waste solutions. Ecube Labs exemplifies the technology-focused specialist, competing on the basis of its cloud-based data analytics platform. Bigbelly Inc. anchors the smart city deployment segment, utilizing its established footprint in North American and European urban environments.
| Leading Market Players |
|---|
| Bigbelly Inc. |
| Ecube Labs |
| Bay Area Trash Compactor |
| Dacheng Machinery Make Co. Ltd. |
| Shanghai Jiajing Machinery Ltd. |
| SP Industries Inc. |
| Bluestream |
| Waste Management Inc. |
| Wastecare Corporation |
| Others |
Cost & Logistics Intelligence
Multi-vendor procurement strategies, a form of horizontal integration for public works departments, anchor buyer pricing power. This approach broadens the supplier base, allowing municipalities to select best-fit technologies and fostering competitive pricing.
Pricing Analysis
Distributor margins for solar trash compactors reflect the value of localized support and installation services. Pricing operates on a project-based model for large deployments, with differentiation driven by integrated technology features like advanced sensors and bundled data analytics services. Pricing softness emerges from multi-vendor procurement strategies, increasing competition among suppliers. Smaller municipalities and commercial entities exhibit higher price sensitivity compared to large urban areas prioritizing long-term operational savings.
Supply Chain Analysis
Dual-sourcing requirements for specialized components are becoming more common among public sector buyers. Geographic supply for solar compactors centers on China for electronic controllers and photovoltaic panels, with Germany contributing precision engineering. The supply chain relies on durable photovoltaic panels and ruggedized electronic controllers, facing risk from component sourcing concentration and potential price volatility. Distribution runs through direct sales channels to urban municipalities and large commercial facilities, often supported by regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar Trash Compactors Market acts as a stable compounder, driven by the persistent global trends of urban densification and stringent sustainability mandates. This creates a consistent operational need for efficient waste management solutions.
For Market Incumbents: To counter the threat of commoditization from multi-vendor procurement strategies, incumbents should deepen their vertical integration into cloud-based data analytics platforms. Investing in advanced sensor packages that offer environmental monitoring beyond fill levels will differentiate offerings. Strategic partnerships with smart city platform providers can secure long-term integration pathways, defending market share against specialized technology entrants.
For New Entrants and Emerging Players: A price-point gap exists between premium, feature-rich smart compactors and basic traditional units, offering an entry point. New entrants can target underpenetrated segments such as university campuses, theme parks, and smaller transportation hubs. Go-to-market strategies should emphasize clear total cost of ownership (TCO) savings and rapid deployment for these specific verticals. Offering modular solutions that allow buyers to customize sensor capabilities also presents an opportunity.
For Investors and Strategic Acquirers: Roll-up economics work for technology-focused specialists because of fragmented data platforms and multi-vendor procurement strategies. The market offers long-term viability, driven by perpetual waste management needs and smart city evolution. Acquisition targets should include firms with robust cloud-based data analytics capabilities or strong regional deployment footprints. The signal to watch is the successful integration of compactor data into broader municipal smart city platforms, indicating ecosystem maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Advanced Sensor Packages | This enhances data granularity for municipal managers, improving operational efficiency and decision-making. |
| Strategic Partnership: Smart City Platform Integration | This embeds compactor data into broader urban management systems, optimizing logistics for cities. |
| Geographic Expansion: Untapped End-Use Verticals | This opens new revenue streams in large private venues like university campuses and theme parks. |
| Acquisition of Specialist Firm: Data Analytics Platform | This consolidates technical expertise and expands service offerings for comprehensive waste solutions. |
| Green Manufacturing Transition: RoHS Compliance | This ensures product adherence to European environmental directives, securing market access. |
Research Approach
Coverage spans Europe, North America, and Asia, with primary inputs from each region. This approach combines in-depth interviews with public works directors, smart city planners, and compactor manufacturers. Secondary validation draws from government waste management reports, smart city project documentation, and environmental regulations like the EU Green Deal. Both bottom-up and top-down triangulation methods ensured data accuracy.
Rate-of-change decomposition analyzes growth across the analysis window by volume, price, and product mix effects. The model segments the market by Product Type, Technology, End User, and Installation method. Compound annual growth rates are derived from historical trends and projected future drivers. Key forecast inputs include urbanization rates, smart city investment levels, and municipal waste generation volumes.
Caveats apply where regulatory changes or significant shifts in public sector investment could materially shift the outlook. Forecasts reflect assumptions documented through primary and secondary research. Deviation in smart city funding or component supply stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Smart Waste Management Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market