
 Sustainable Palm Oil Market | 2026-2036
Sustainable Palm Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Palm Oil Market Outlook
Smallholder farmer training capacity is unwinding supply chain traceability ambitions across Southeast Asia. Unilever leverages its direct smallholder partnership programs to secure segregated certified volumes. Wilmar International anchors its position through plantation-to-refinery infrastructure across Indonesia and Malaysia. Cargill competes by extending its European crushing and refining footprint to meet corporate NDPE commitments.
Sustainable palm oil denotes crude and refined oils plus derivatives produced under third-party certification schemes that prohibit deforestation, peatland conversion, and forced labor while tracking mass-balance or segregated supply chains. Refiners achieve olein and stearin fractions through fractionation at 20-25°C, yielding tailored melting profiles for confectionery and personal care formulations. Refined palm oil dominates value capture due to downstream formulation flexibility in food and cosmetics, while palm oil derivatives represent the fastest-expanding margin pool as surfactant and emulsifier demand intensifies. RSPO-certified volumes still occupy the largest certification share, though ISCC-certified streams are gaining traction in EU biofuel blending mandates.
The EU Deforestation Regulation and REACH compliance requirements now shape market access for Asian-origin shipments into European food and chemical sectors. Indonesia's Ministry of Environment and Forestry and Malaysia's Malaysian Sustainable Palm Oil certification scheme enforce national sustainability benchmarks that parallel private standards. Stakeholders must monitor how divergent national traceability systems interface with EU customs verification infrastructure before committing to long-term supply contracts.
Market Dynamics
The EU Deforestation Regulation now mandates satellite-verified geolocation data for every palm oil shipment entering European customs, forcing upstream consolidation among Indonesian and Malaysian suppliers who must retrofit traceability infrastructure or lose market access.
Growth Catalysts
- EU Deforestation Regulation:The EUDR's traceability requirements are pulling certified mass-balance volumes into European food and oleochemical supply chains, rewarding early-compliant plantation groups with preferential offtake terms.
- India:The country's packaged food sector is absorbing refined palm olein at accelerating rates as urbanization shifts cooking oil preferences toward stable, cost-competitive frying media.
- Fatty acid methyl ester (FAME) blending:ISCC certification streams are capturing biofuel offtake under Germany's greenhouse gas reduction quota system, redirecting crude palm oil flows from food to energy applications.
Market Restraints
- Smallholder fragmentation:Indonesia's four million independent smallholders operate outside plantation company traceability systems, creating certification coverage gaps that block segregated supply chain ambitions.
- Peatland conversion legacy:Malaysia's historical drainage of carbon-rich peat soils triggers ongoing EU customs scrutiny and compliance cost inflation for Sarawak and Sabah origin shipments.
- Sunflower and rapeseed substitution:European food manufacturers are reformulating away from palm in premium confectionery lines, compressing addressable demand in brand-sensitive categories.
Strategic Opportunities
- China:The country's cosmetics sector is absorbing RSPO-certified palm derivatives for surfactant and emulsifier applications, with Shanghai and Guangzhou formulators demanding segregated supply chains for export-facing brands.
- Blockchain-IoT convergence:Distributed ledger systems paired with plantation-level sensor networks are enabling real-time fruit bunch tracking from harvest to refinery, collapsing audit costs for compliance-heavy buyers.
- Indonesian B40 biofuel mandate:The national blending target creates a guaranteed offtake floor for domestic crude palm oil, insulating integrated plantation-refiners from European demand volatility.
Industry Challenges
- Auditor capacity constraints:RSPO and ISCC certification bodies face field inspector shortages across Kalimantan and Sumatra, stretching audit timelines and delaying supplier onboarding for European clients.
- Legacy mill infrastructure:Decades-old Malaysian palm oil mills require capital-intensive retrofitting to achieve methane capture and wastewater treatment standards under national environmental regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Palm Oil Market |
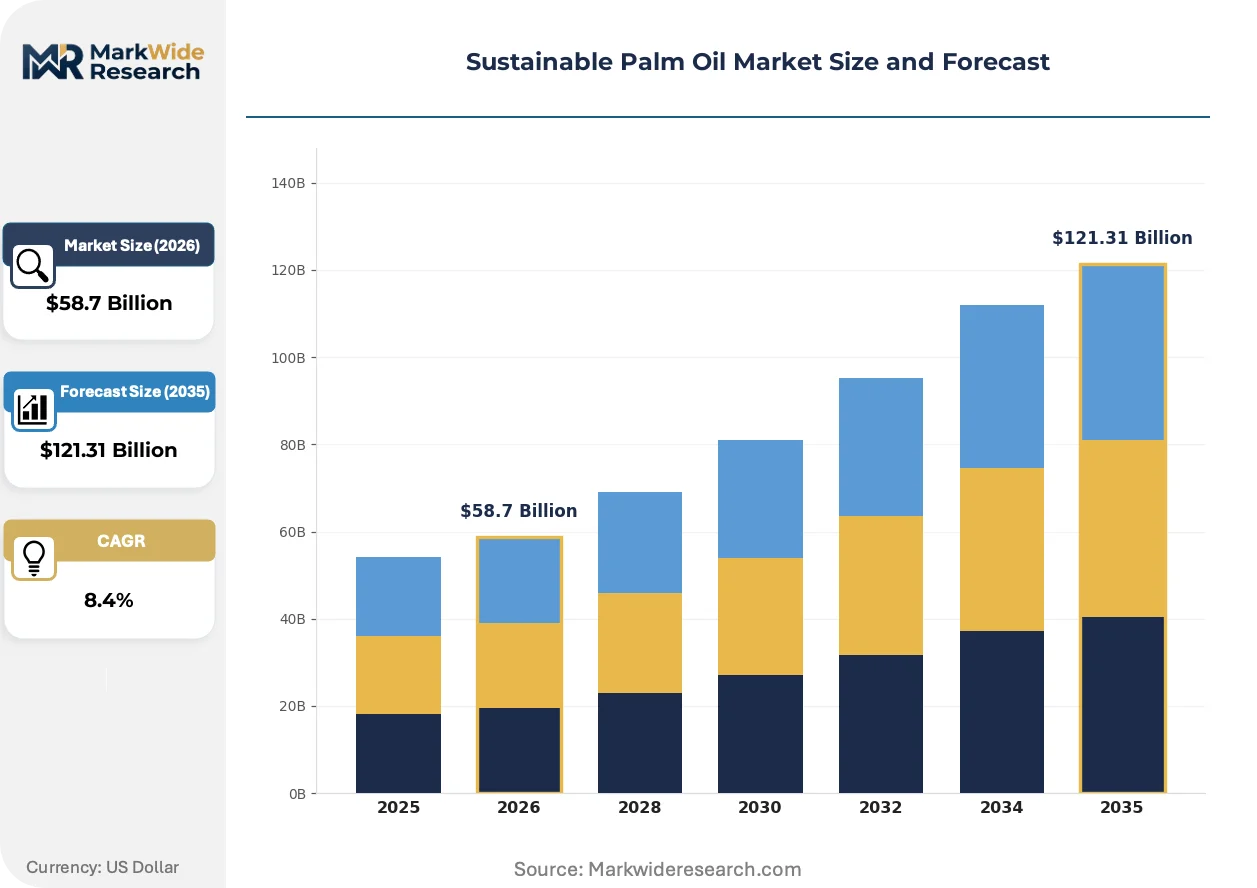
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Palm Oil, Refined Palm Oil, Palm Oil Derivatives, Palm Kernel Oil Application: Food Products, Personal Care, Biofuels, Industrial Applications End User: Food Manufacturers, Cosmetic Companies, Biofuel Producers, Industrial Users Certification Type: RSPO Certified, ISCC Certified, Rainforest Alliance, Others |
| Companies Covered | Unilever, Wilmar International, Cargill, Sime Darby Plantation, Golden Agri-Resources, FGV Holdings, IOI Group, Musim Mas Holdings, PT Astra Agro Lestari, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Palm Oil Market Strategic Shifts
Digital traceability infrastructure is displacing paper-based chain-of-custody systems, while novel fractionation chemistries and biofuel policy arbitrage are rewriting margin capture rules across the value chain.
Near-infrared spectroscopy paired with blockchain-enabled smart contracts is miniaturizing laboratory-grade fatty acid analysis to plantation checkpoints. Indonesian integrated groups are deploying handheld devices to verify fruit bunch ripeness and oil content at collection points, collapsing the information lag between harvest and refinery intake. This distributed verification architecture is compressing price discovery cycles and enabling real-time premium adjustments for certified smallholder deliveries.
REACH compliance requirements under ECHA jurisdiction are tightening purity thresholds for palm-derived glycerin and fatty alcohols entering European personal care formulations. The regulation's updated substance evaluation criteria are forcing Asian refiners to invest in molecular distillation capacity or exit cosmetic-grade supply tiers. German and Dutch formulators are responding by consolidating supplier panels around vertically integrated Malaysian groups with in-house analytical certification capabilities.
Brand-led procurement is consolidating around segregated certification tiers as Unilever and Nestlé publish supplier scorecards linking executive compensation to deforestation-free sourcing metrics. This accountability shift is displacing mass-balance certificates in premium product lines, with European retailers demanding SKU-level traceability disclosures. The behavior change is most visible in Netherlands and UK grocery channels, where private-label sustainability claims now require third-party verified geolocation data for every kilogram of palm input.
Sustainable Palm Oil Market Segmentation
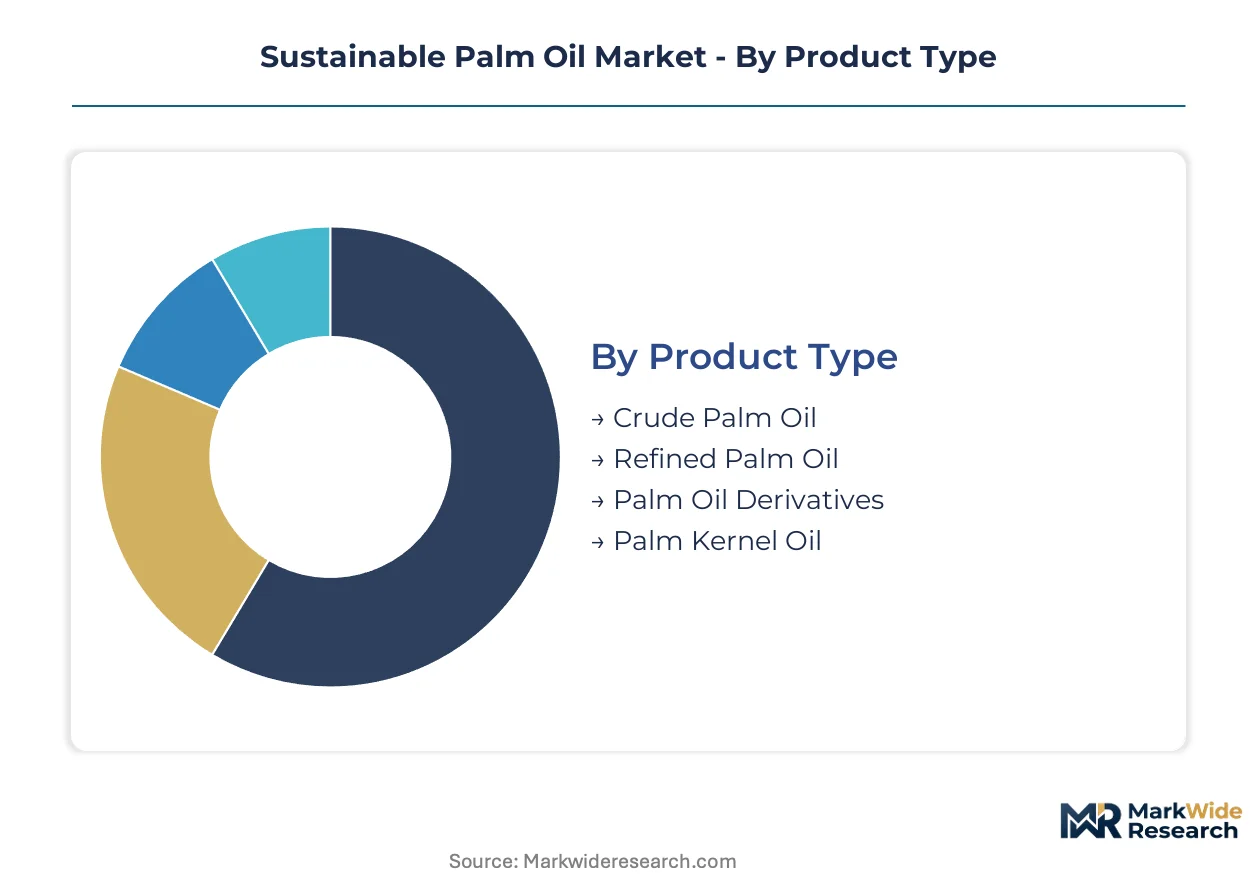
Segmentation in sustainable palm oil reveals how certification tiers, product forms, and end-use specifications fragment procurement requirements. Buyers align supplier selection with formulation needs, regulatory exposure, and brand positioning.
Product Type:
Refined grades dominate export flows to Europe and North America, while crude volumes serve domestic Indonesian and Malaysian biofuel mandates.
- Crude Palm Oil:Unrefined oil extracted from fresh fruit bunches retains carotenoids and high free fatty acid content. Indonesian biofuel producers under B40 blending mandates absorb domestic crude volumes, insulating integrated plantation-refiners from European demand volatility.
- Refined Palm Oil:Bleached and deodorized oil meets food-grade specifications for frying stability and neutral flavor. European food manufacturers under EUDR traceability requirements source refined grades through mass-balance certified supply chains.
- Palm Oil Derivatives:Fractionated olein and stearin plus fatty acid esters serve oleochemical applications.
- Palm Kernel Oil:Extracted from seed endosperm, this lauric-rich oil feeds surfactant production for personal care formulators.
Refined palm oil commands the established base. The steepest expansion runs through palm oil derivatives.
Application:
Cost tiers separate commodity food uses from premium cosmetic formulations where certification premiums justify price acceptance.
- Food Products:Cooking oils, margarines, and confectionery fats demand high oxidative stability. India's packaged food sector absorbs refined palm olein as urbanization shifts frying oil preferences toward cost-competitive, stable media.
- Personal Care:Surfactants, emulsifiers, and moisturizers require high-purity fatty acid derivatives. China's cosmetics sector in Shanghai and Guangzhou demands RSPO-certified segregated supply chains for export-facing brands.
- Biofuels:Fatty acid methyl ester blending redirects crude flows from food to energy applications.
- Industrial Applications:Lubricants and coatings utilize palm-based base stocks.
Food products anchor volume. Personal care generates the steepest margin expansion.
End User:
Customer type determines certification stringency, with consumer-facing brands demanding segregated tiers over mass-balance.
- Food Manufacturers:Nestlé and Unilever procurement teams link executive compensation to deforestation-free sourcing metrics. These buyers displace mass-balance certificates in premium product lines, demanding SKU-level traceability disclosures verified by third-party geolocation data.
- Cosmetic Companies:German and Dutch formulators consolidate supplier panels around Malaysian groups with in-house analytical certification for REACH compliance.
- Biofuel Producers:German blenders under greenhouse gas reduction quotas source ISCC-certified streams.
- Industrial Users:Oleochemical processors feed downstream specialty chemical production.
Food manufacturers drive certification coverage. Cosmetic companies are expanding segregated sourcing fastest.
Certification Type:
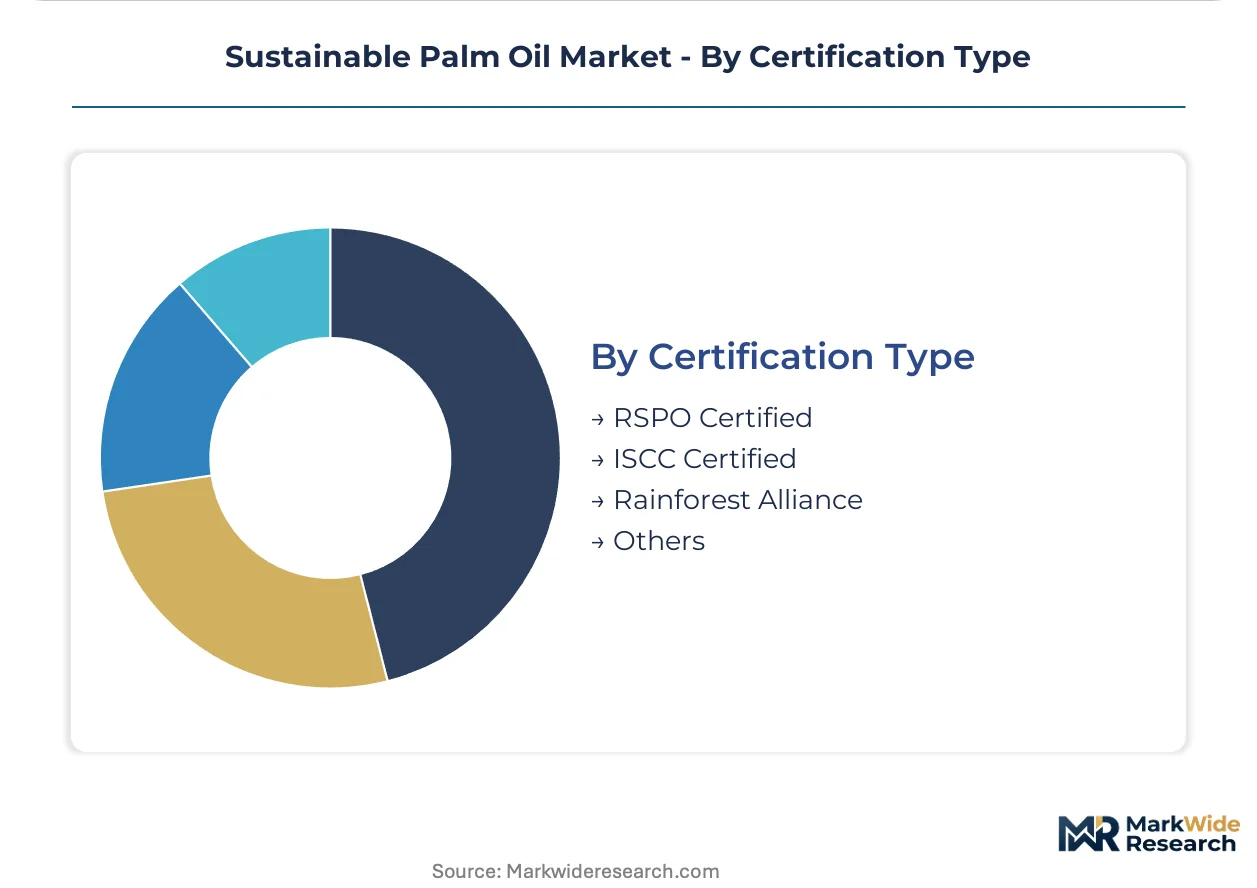
Supply concentration varies by scheme, with RSPO holding inspector capacity across Southeast Asia while ISCC gains European biofuel traction.
- RSPO Certified:The Roundtable on Sustainable Palm Oil operates the largest certification footprint, prohibiting deforestation and peatland conversion. RSPO-certified volumes still occupy the largest certification share, though auditor shortages across Kalimantan and Sumatra stretch onboarding timelines.
- ISCC Certified:The International Sustainability and Carbon Certification scheme captures biofuel offtake under EU renewable energy directives. ISCC streams are gaining traction in EU biofuel blending mandates, redirecting crude palm oil flows from food to energy applications.
- Rainforest Alliance:Integrated biodiversity and social standards serve niche premium segments.
- Others:Malaysian Sustainable Palm Oil and Indonesian national schemes enforce parallel sustainability benchmarks.
RSPO Certified holds the volume base. ISCC Certified is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Environment and Forestry enforces national sustainability benchmarks that parallel private certification standards, anchoring upstream production concentration while EU customs verification infrastructure reshapes export flows.
Indonesia
Domestic biofuel absorption under B40 blending mandates and smallholder training programs drive upstream investment. The Ministry of Environment and Forestry's traceability requirements interface with EU Deforestation Regulation verification systems. Kalimantan and Sumatra plantation clusters retrofit geolocation tracking infrastructure to maintain European market access.
Malaysia
Refined product exports to European oleochemical formulators and personal care manufacturers sustain downstream value capture. The Malaysian Sustainable Palm Oil certification scheme enforces parallel sustainability benchmarks to RSPO standards. Sarawak and Sabah origin shipments face heightened EU customs scrutiny over historical peatland conversion legacies.
India
Urbanization in packaged food sector shifts cooking oil preferences toward stable, cost-competitive frying media. The Food Safety and Standards Authority of India regulates edible oil quality specifications for domestic consumption. Mumbai and Ahmedabad refineries absorb refined palm olein volumes for national distribution networks.
China
Cosmetics sector demand for RSPO-certified surfactants and emulsifiers accelerates segregated supply chain adoption. The National Medical Products Administration oversees cosmetic ingredient safety assessments under GB standards. Shanghai and Guangzhou formulator clusters demand third-party verified geolocation data for export-facing brand formulations.
Germany
Biofuel blending mandates under greenhouse gas reduction quota systems redirect ISCC-certified crude flows from food to energy applications. The Federal Environment Agency administers renewable energy directive compliance for transport fuel markets. Hamburg and Rotterdam-adjacent crushing facilities consolidate European refining footprint for corporate NDPE commitments.
Sustainable Palm Oil Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the value chain. Plantation-to-refinery integrated groups dominate upstream cost structures through captive fresh fruit bunch supply, while downstream formulators compete on certification tier access and analytical compliance capabilities. The competitive terrain separates into three strategic archetypes: integrated plantation-refiners, merchant traders with crushing assets, and brand-led procurement consolidators. Capacity expansion in molecular distillation and blockchain-IoT traceability infrastructure represent the dominant competitive moves reshaping supplier panels.
Among integrated plantation-refiners, Wilmar International and Sime Darby Plantation occupy positions exemplifying upstream-downstream coordination, while Unilever represents the brand-led procurement archetype consolidating supplier relationships around deforestation-free sourcing metrics. These three entities anchor contrasting competitive vectors—production scale, traceability infrastructure, and procurement leverage—without any single archetype commanding full value chain control.
| Leading Market Players |
|---|
| Unilever |
| Wilmar International |
| Cargill |
| Sime Darby Plantation |
| Golden Agri-Resources |
| FGV Holdings |
| IOI Group |
| Musim Mas Holdings |
| PT Astra Agro Lestari |
| Others |
Value Chain & Pricing Dynamics
Integrated plantation-to-refinery scale economies in Indonesian and Malaysian upstream operations compress unit costs and establish price floors that smaller merchant traders cannot match. This concentration of crushing capacity around captive fresh fruit bunch supply locks in cost advantages while EU Deforestation Regulation compliance investments filter marginal suppliers from European offtake markets.
Pricing Analysis
Indonesian-origin crude palm oil trades at persistent discounts to Malaysian refined grades due to logistics inefficiencies and certification coverage gaps. Three-tier pricing structure across segregated RSPO, mass-balance certified, and uncertified tiers reflects buyer risk appetite and formulation requirements. Cost compression in standard mass-balance grades is intensifying as European food manufacturers consolidate supplier panels around early EUDR-compliant plantation groups. Smallholder-dependent traders exhibit highest price sensitivity due to audit cost pass-through limitations.
Supply Chain Analysis
Port congestion at Belawan and Tanjung Pelepas elevates inbound logistics costs for European-bound refined product shipments, compressing margins on long-haul trade lanes. Indonesia, Malaysia, and increasingly India concentrate upstream crushing and downstream refining capacity. Supply chains draw from fresh fruit bunches, methanol for FAME esterification, and molecular distillation reagents. Single-source vulnerability runs through Indonesian smallholder collection networks where four million independent farmers operate outside plantation traceability systems. Distribution runs through Rotterdam-adjacent storage terminals for European oleochemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and traceability infrastructure creates niche opportunities as brand-led procurement consolidates around segregated supply chains. Divergent national sustainability schemes and EU customs verification requirements reward specialized compliance capabilities.
For Market Incumbents: Consolidate backward integration into Kalimantan and Sumatra smallholder training networks to secure segregated certified volumes before auditor capacity constraints worsen. Lock in long-term offtake agreements with European food manufacturers now linking executive compensation to deforestation-free sourcing metrics. Capture methane capture and wastewater treatment retrofits at legacy Malaysian mills to preempt national environmental enforcement.
For New Entrants and Emerging Players: Anchor in Chinese cosmetics sector demand for RSPO-certified surfactants where Shanghai and Guangzhou formulators pay premiums for verified geolocation data. Target blockchain-IoT traceability infrastructure deployment as plantation groups retrofit paper-based chain-of-custody systems. Pursue partnerships with Indonesian integrated refiners lacking in-house digital verification capabilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-refiners with captive B40 biofuel offtake insulating domestic crude absorption from European demand volatility. Long-term viability centers on vertically integrated Malaysian groups with molecular distillation capacity for REACH-compliant cosmetic-grade derivatives. Monitor auditor onboarding timelines at RSPO and ISCC certification bodies as inflection indicator for supplier bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Smallholder Training Network Expansion | Secures segregated certified volumes for Unilever and Nestlé procurement scorecards. |
| Blockchain-IoT Traceability Deployment | Collapses audit costs for EUDR compliance at Indonesian plantation checkpoints. |
| Molecular Distillation Capacity Addition | Enables REACH-compliant glycerin supply to German and Dutch cosmetic formulators. |
| Biofuel Blending Infrastructure | Captures guaranteed offtake under Indonesia's B40 mandate insulating price volatility. |
| Segregated Certification Investment | Displaces mass-balance tiers in Netherlands and UK private-label grocery channels. |
Study Parameters
Initial hypotheses were tested against primary input from plantation operations managers, European food manufacturer procurement leads, RSPO certification body field inspectors, and Indonesian Ministry of Environment officials and refined through customs trade data, EUDR regulatory filings, ISCC audit records, and SEC disclosures from listed plantation groups. Bottom-up volume estimates from individual mill capacity and top-down demand validation from downstream formulation requirements were triangulated to constrain forecast variance.
Variance decomposition across product type, certification tier, end-use application, and geographic production cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers including urbanization patterns in India and biofuel policy arbitrage between EU and Indonesian mandates. Modeled inputs incorporated B40 blending mandate absorption curves and REACH compliance cost pass-through elasticity.
Decision-makers should treat outputs as directional under sustained EUDR enforcement and current auditor capacity constraints; material deviation would warrant model refresh. Palm oil substitution rates in European confectionery and peatland drainage legacy enforcement in Sarawak represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Environment & Sustainability
Global Weatherization Services Market
Environment & Sustainability
Oxygen Filters Market
Environment & Sustainability
Recyclate PET Market
Environment & Sustainability
Global Cloud Seeding Equipment Market
Environment & Sustainability
Waste Recycling Services Market
Environment & Sustainability
Middle East and Africa Air Quality Monitoring Market
Environment & Sustainability
Waste Management Market
Environment & Sustainability
UAE Biomedical Waste Management Market
Environment & Sustainability
India Cloud Seeding Market
Environment & Sustainability
United States Green Cement Market
Environment & Sustainability
Asia-Pacific Indoor Air Purification Market
Environment & Sustainability
UV Water Sterilizer Market
Environment & Sustainability
Waste Compactor Bins Market
Environment & Sustainability
Asia-Pacific Food and Environment Manual Testing Market
Environment & Sustainability
Europe Carbon Dioxide Market