
 Aluminum Cans Recycling Market | 2026-2036
Aluminum Cans Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
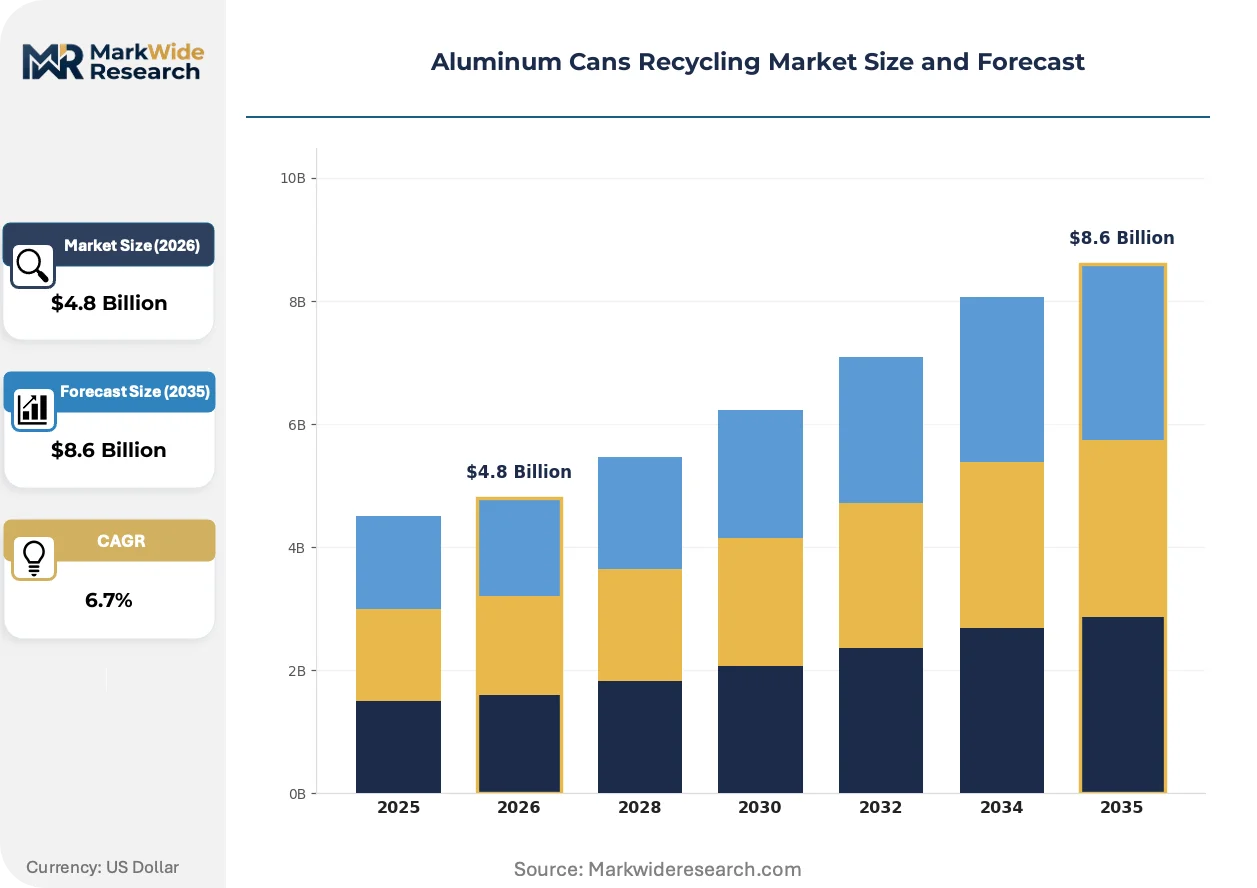
Aluminum Cans Recycling Market Outlook
Beverage manufacturers are gaining share against traditional scrap merchants as the dominant buyer archetype in aluminum can recycling, and demand is bifurcating between closed-loop contract buyers and spot-market processors. Novelis Inc. leverages its captive melting capacity to secure long-term supply agreements with major brewers. Norsk Hydro ASA anchors its position through hydropower-smelter integration in Nordic operations. Constellium SE differentiates via aerospace-grade alloy recovery streams that command premium sorting protocols.
Aluminum cans recycling encompasses the collection, sorting, shredding, and remelting of used aluminum beverage containers to produce secondary aluminum ingot with purity levels typically exceeding 99.5% after fluxing and degassing. The process reduces energy consumption by roughly 95% versus primary aluminum electrolysis, making it indispensable for carbon-reduction targets in packaging supply chains. Deposit systems dominate collection economics in markets with legislated container-return obligations, while mechanical recycling leads processing volume due to lower capital intensity than hydrometallurgical or pyrometallurgical alternatives. Post-consumer material quality segments attract the tightest supply competition as brand owners seek food-contact certified recycled content.
The EPA oversees hazardous waste classifications for spent potliner and salt cake byproducts in U.S. recycling operations, while the EU Green Deal's Packaging and Packaging Waste Regulation sets mandatory recycled content minimums for aluminum beverage containers sold in member states. China's MEE enforces import quality standards that restrict contaminated scrap inflows, redirecting regional trade flows toward Southeast Asian processing hubs. Stakeholders must monitor evolving extended producer responsibility frameworks and alloy-specific sorting investments to secure offtake contracts with carbon-accounting brand owners.
Market Dynamics
Closed-loop sourcing commitments from beverage manufacturers are compressing supply availability for spot-market processors and reshaping contract structures across secondary aluminum supply chains.
Growth Catalysts
- EU Green Deal Packaging Mandates:Mandatory recycled content thresholds for aluminum beverage containers sold in member states are pulling material through certified sorting facilities and tightening post-consumer scrap competition.
- Hydropower-Smelter Integration:Nordic operators leveraging renewable energy baseload are securing carbon-accounting contracts with brand owners seeking Scope 3 reductions in packaging supply chains.
- Deposit System Expansion:Legislated container-return obligations in Germany, Norway, and several US states are improving collection economics and feedstock quality for mechanical recycling operations.
Market Restraints
- Spent Potliner Disposal Costs:EPA hazardous waste classifications for salt cake byproducts elevate compliance burdens and limit smelter site expansion options in US operations.
- Import Quality Barriers:China's MEE enforcement of contaminated scrap restrictions has redirected regional trade flows toward Southeast Asian processing hubs, fragmenting supply chain coordination.
- Alloy Sorting Limitations:Current optical and eddy-current separation technologies struggle to achieve aerospace-grade purity thresholds without manual intervention, constraining premium stream recovery rates.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Emerging EPR legislation in US states and Canadian provinces creates structured offtake channels for certified recycled content producers.
- Food-Contact Certification Expansion:Brand owners seeking packaging circularity are contracting directly with recyclers possessing FDA and EFSA-compliant remelting protocols.
- Urban Mining Infrastructure:Dense metropolitan collection networks in Tokyo, Seoul, and Singapore offer untapped feedstock concentration for automated sorting investments.
Industry Challenges
- Flux Chemistry Expertise Gap:Specialized metallurgical knowledge for impurity control in secondary aluminum refining remains concentrated among aging technical workforces in European and North American operations.
- Legacy Equipment Integration:Retrofitting existing shredder and delacquering lines with sensor-based alloy identification requires capital outlays that strain mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Cans Recycling Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Curbside Collection, Drop-off Centers, Deposit Systems, Industrial Recycling End User: Beverage Manufacturers, Food Packaging Companies, Consumer Goods Industry, Recyclers Material Quality: Post-Consumer, Post-Industrial, Scrap, Clean Processing Technology: Hydrometallurgy, Pyrometallurgy, Mechanical Recycling, Electromagnetic Separation |
| Companies Covered | Novelis Inc., Norsk Hydro ASA, Constellium SE, REAL ALLOY, Matalco Inc., ArcelorMittal S.A., Ball Corporation, Crown Holdings, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Cans Recycling Market Strategic Shifts
Digital traceability platforms and advanced separation technologies are converging to enable alloy-specific recovery at commercial scale, transforming how recyclers contract with carbon-accounting brand owners.
Sensor-based sorting technology is bifurcating the competitive landscape between integrated beverage manufacturers with captive recycling assets and independent processors dependent on merchant scrap supply. Major brewers are deploying X-ray fluorescence and laser-induced breakdown spectroscopy systems to secure food-contact certified recycled content. This technology diffusion is compressing margins for conventional scrap merchants lacking equivalent capital deployment capacity.
The EU Green Deal's Packaging and Packaging Waste Regulation is mandating minimum recycled content thresholds for aluminum beverage containers sold in member states. This regulatory pressure is accelerating investments in closed-loop collection infrastructure and alloy-specific sorting protocols. German and French packaging compliance schemes are responding by consolidating producer responsibility organizations to streamline certified material flow documentation.
Direct contracting between beverage manufacturers and recyclers is displacing traditional merchant scrap channels in North American and European supply chains. Brand owners with science-based carbon targets are negotiating long-term offtake agreements that bypass conventional scrap yards. This procurement restructuring is most visible in Germany's industrial recycling corridor and the US Great Lakes aluminum cluster.
Aluminum Cans Recycling Market Segmentation
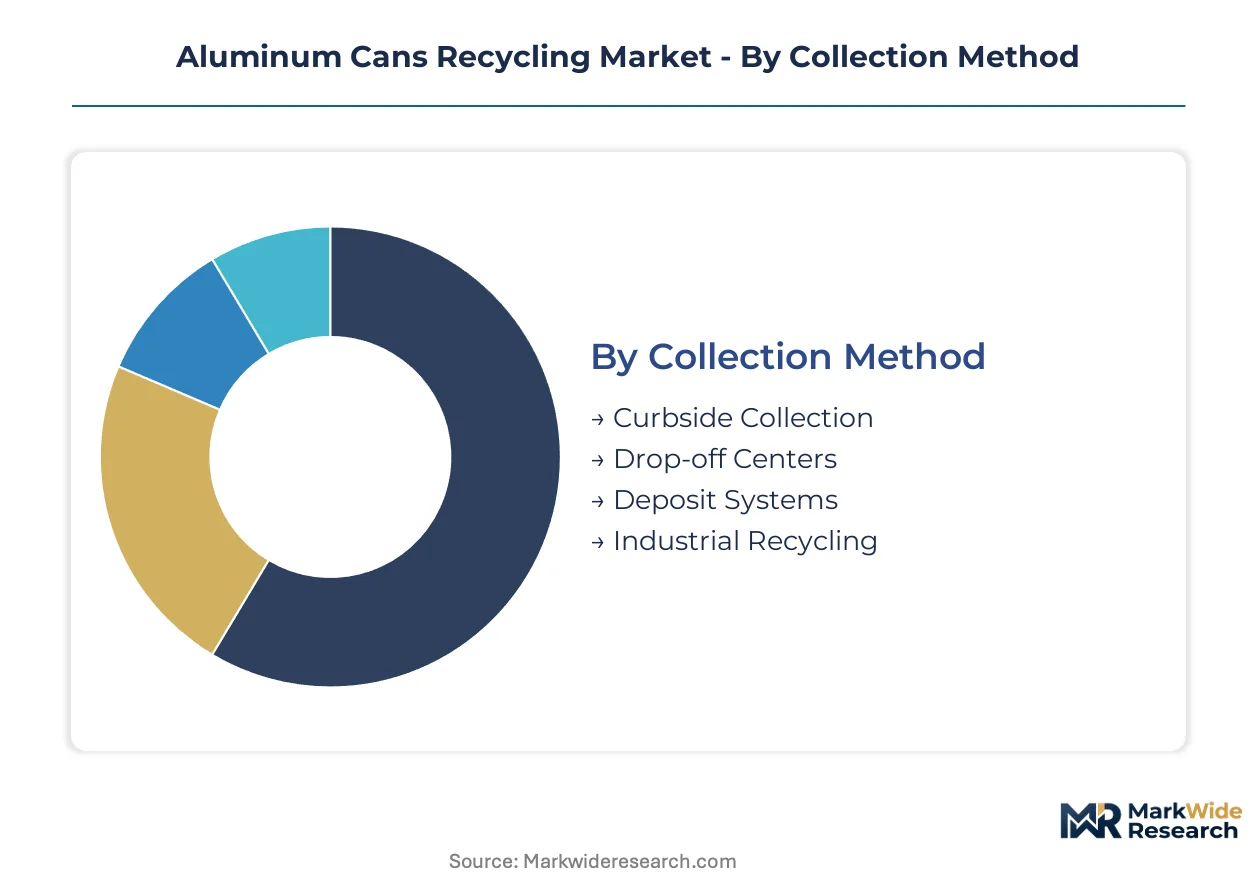
Aluminum can recycling segments diverge sharply on regulatory treatment and carbon accounting eligibility. Deposit systems and post-consumer streams command premium pricing due to food-contact certification requirements, while mechanical recycling dominates volume through lower capital barriers.
Collection Method:
Deposit systems operate under legislated container-return obligations that alter collection economics and material purity profiles.
- Deposit Systems:Mandated container-return schemes in Germany, Norway, and several US states deliver high-purity feedstock with documented chain-of-custody. Beverage manufacturers prioritize these streams for closed-loop contracts due to contamination rates below 2% and automatic sorting compatibility.
- Curbside Collection:Municipal programs generate volume at lower per-ton collection costs but suffer higher contamination from commingled waste streams. EPA hazardous waste classifications for mixed-material residue limit direct smelter acceptance without intermediate processing.
- Drop-off Centers:Self-directed consumer deposits create irregular supply patterns with quality variance.
- Industrial Recycling:Captive collection at beverage manufacturing facilities enables immediate closed-loop reintegration with minimal transport emissions.
Curbside collection handles the majority of throughput; deposit systems are expanding most quickly on share.
End User:
Procurement restructuring favors direct contracting over traditional merchant scrap channels.
- Beverage Manufacturers:Closed-loop sourcing commitments from major brewers and soft drink producers are compressing spot-market availability. These buyers negotiate long-term offtake agreements with recyclers possessing FDA-compliant remelting protocols and carbon accounting documentation.
- Recyclers:Independent processors face margin pressure from integrated beverage manufacturers with captive melting capacity. Merchant scrap yards in the US Great Lakes cluster and Germany's industrial recycling corridor are consolidating to secure alloy-specific sorting investments.
- Food Packaging Companies:Secondary aluminum demand for food-contact applications requires EFSA certification and traceable post-consumer content.
- Consumer Goods Industry:Non-food aluminum applications accept broader quality tolerances and lower-grade scrap streams.
Beverage manufacturers dominate procurement volume; food packaging companies show the steepest expansion trajectory.
Material Quality:
Quality tiers separate carbon-accounting eligible streams from commodity scrap.
- Post-Consumer:Used beverage containers recovered through deposit or curbside systems carry food-contact certification potential and Scope 3 reduction value for brand owners. EU Green Deal recycled content mandates specifically target this stream.
- Clean:Delacquered and pre-sorted aluminum with minimal coating residue commands sorting premiums and direct smelter acceptance.
- Post-Industrial:Manufacturing trim and process scrap from can production facilities offers consistent alloy composition but lacks circularity claims.
- Scrap:Mixed-grade material requiring fluxing and degassing intervention before remelting.
Post-consumer material handles the majority of certified throughput; clean grades are gaining share fastest.
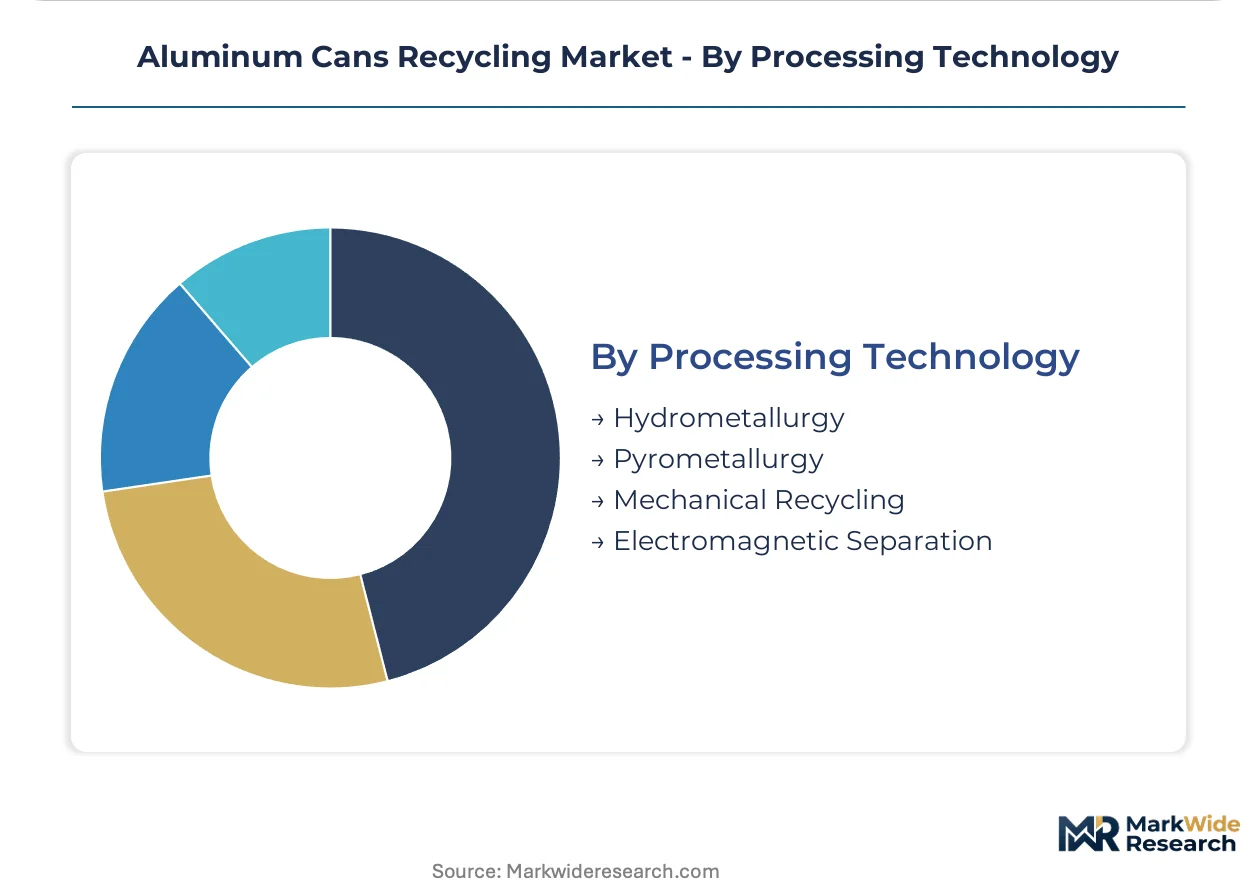
Processing Technology:
Capital intensity and alloy specificity drive technology selection across processor scale tiers.
- Mechanical Recycling:Shredding, delacquering, and remelting operations dominate installed capacity due to lower capital requirements and operational flexibility. China's MEE import restrictions have redirected mechanical processing toward Southeast Asian hubs.
- Electromagnetic Separation:Eddy-current and sensor-based sorting systems enable alloy-specific recovery for aerospace-grade applications.
- Hydrometallurgy:Chemical dissolution and precipitation methods achieve higher purity thresholds for specialized alloys.
- Pyrometallurgy:High-temperature refining processes handle contaminated feedstock but generate salt cake byproducts requiring EPA hazardous waste disposal.
Mechanical recycling handles the majority of volume; electromagnetic separation is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in aluminum can recycling logistics, connecting barge-accessible smelters to dense urban collection networks across multiple jurisdictions.
Germany
Beverage manufacturers operating along the Rhine corridor leverage the EU Green Deal's recycled content mandates to secure long-term supply contracts. The country's national packaging regulator enforces strict extended producer responsibility frameworks through the Zentrale Stelle Verpackungsregister. The industrial recycling corridor spanning Düsseldorf, Cologne, and the Ruhr Valley concentrates Europe's highest-capacity mechanical recycling operations.
United States
The Great Lakes aluminum cluster benefits from integrated barge-rail infrastructure linking Midwestern collection networks to secondary smelters. EPA hazardous waste classifications for salt cake byproducts shape compliance investments across Ohio, Indiana, and Michigan processing facilities. Detroit-Windsor cross-border logistics enable efficient feedstock movement between Michigan deposit-system collection and Ontario remelting capacity.
China
Domestic beverage production growth drives secondary aluminum demand despite MEE import restrictions redirecting mechanical processing toward Southeast Asian hubs. The country's environmental ministry enforces contaminated scrap standards that fragment regional trade coordination. The Yangtze River Delta manufacturing belt hosts the largest concentration of domestic can production and captive recycling integration.
Norway
Hydropower-smelter integration in Nordic operations secures carbon-accounting contracts with brand owners targeting Scope 3 reductions. The country's energy regulator certifies renewable baseload for secondary aluminum production. The Søral smelter corridor along the western fjords anchors Europe's lowest-carbon remelting infrastructure.
Japan
Metropolitan collection density in Tokyo and Osaka enables automated sorting investments with rapid payback periods. METI circular economy directives mandate aluminum packaging recovery rates above 90% in designated cities. The Keihin industrial zone between Tokyo and Yokohama concentrates beverage manufacturing and closed-loop reintegration facilities.
Aluminum Cans Recycling Market Competitive Environment
Listed leaders compete with private specialists across capital deployment capacity, with publicly traded recyclers leveraging equity markets for sensor-based sorting investments while family-owned processors defend regional feedstock relationships through operational flexibility. The vendor base organizes around three strategic archetypes: integrated beverage manufacturers with captive melting assets, independent secondary smelters with alloy-specific recovery capabilities, and merchant scrap processors dependent on spot-market supply. Consolidation pressure intensifies through long-term offtake agreements that bypass conventional scrap channels, while technology licensing partnerships enable mid-scale operators to access advanced separation protocols without full capital ownership.
Among integrated aluminum specialists, Novelis Inc. and Norsk Hydro ASA occupy positions exemplifying divergent competitive strategies. Novelis represents the beverage-captive archetype through its focus on closed-loop supply agreements with major brewers. Norsk Hydro ASA anchors the renewable-energy-integrated tier, leveraging Nordic hydropower infrastructure for carbon-accounting eligibility. Constellium SE sits within the aerospace-grade recovery segment, where alloy-specific purity thresholds command premium positioning.
| Leading Market Players |
|---|
| Novelis Inc. |
| Norsk Hydro ASA |
| Constellium SE |
| REAL ALLOY |
| Matalco Inc. |
| ArcelorMittal S.A. |
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between beverage manufacturers and secondary aluminum recyclers lock in supply access and price visibility across the EU Green Deal compliance window. These contracts bypass traditional merchant scrap channels and compress spot-market availability in Germany's industrial recycling corridor.
Pricing Analysis
Volume-discount tiering structures separate food-contact certified post-consumer streams from commodity-grade mixed scrap. Premium pricing attaches to deposit-system material with documented chain-of-custody and EFSA-compliant remelting protocols. Cost compression in spot-market tiers intensifies as integrated beverage manufacturers with captive melting capacity internalize supply. Independent processors show highest price sensitivity due to margin pressure from alloy-specific sorting investments.
Supply Chain Analysis
Inventory cycles compress around barge-rail logistics connecting Midwestern US collection networks to Great Lakes secondary smelters. Feedstock concentration centers on Germany, Norway, and the US Great Lakes cluster, with China's MEE import restrictions redirecting mechanical processing toward Southeast Asian hubs. Raw material flows draw from urban deposit systems, curbside municipal programs, and industrial manufacturing trim. Single-source vulnerability concentrates in hydropower-dependent Nordic remelting infrastructure. Distribution runs through closed-loop contracts directly linking beverage manufacturers to certified recyclers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU Green Deal mandates bifurcate demand between carbon-accounting brand owners and conventional spot-market buyers, creating tiered service niches across compliance and commodity segments.
For Market Incumbents: Secure long-term offtake agreements with beverage manufacturers seeking Scope 3 reductions before integrated competitors expand captive melting capacity. Invest in sensor-based alloy sorting to defend premium stream access against technology-diffusing merchant scrap consolidators. Hydropower-smelter integration in Nordic operations offers defensible positioning as renewable energy certification tightens. For New Entrants and Emerging Players: Alloy-specific recovery services for aerospace-grade applications represent an underserved niche where optical separation limitations constrain incumbent throughput. Target Southeast Asian processing hubs benefiting from redirected Chinese scrap flows under MEE enforcement. Deploy hydrometallurgical processing as a differentiated go-to-market angle for specialized purity requirements. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale processors with retrofit-ready infrastructure and established municipal feedstock relationships across the analysis window. Acquisition targets should possess FDA or EFSA-compliant remelting protocols and documented carbon accounting systems. Watch EU Green Deal recycled content threshold enforcement as the inflection indicator for contract restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Based Sorting Deployment | X-ray fluorescence systems enable aerospace-grade alloy recovery for premium contract eligibility. |
| Hydropower-Smelter Integration | Nordic renewable baseload certification secures carbon-accounting contracts with Scope 3-targeting brand owners. |
| Closed-Loop Collection Infrastructure | Deposit-system expansion in Germany and Norway delivers sub-2% contamination rates for food-contact certification. |
| Extended Producer Responsibility Participation | EPR framework alignment in US states and Canadian provinces creates structured certified material offtake channels. |
| Hydrometallurgical Processing Investment | Chemical dissolution methods achieve purity thresholds beyond mechanical recycling for specialized alloy streams. |
Study Parameters
A spread of perspectives from secondary smelter operations managers, beverage manufacturer procurement leads, municipal recycling coordinators, and alloy sorting technology specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from EPA hazardous waste classifications, EU Green Deal regulatory filings, China MEE import standard documents, and customs trade flow data. Bottom-up facility capacity assessments and top-down demand modeling triangulated volume estimates.
Segmentation dimensions modeled include collection method, end-user procurement structure, material quality tier, and processing technology capital intensity across the projection horizon. CAGRs derive from trend extrapolation of closed-loop contract growth, deposit system expansion rates, and regulatory compliance deadline pacing. Industry-specific inputs incorporate hydropower-smelter integration economics and sensor-based sorting technology diffusion curves.
Underlying assumptions cover EU Green Deal enforcement continuity, hydropower baseload availability in Nordic operations, and MEE import restriction persistence, with deviation risk concentrated in regulatory timeline delays and alloy sorting technology breakthroughs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
Solar Panel Recycling Management Market