
 Release Liner Recycling Market | 2026-2036
Release Liner Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Release Liner Recycling Market Analytics
Collector-processor networks for post-industrial release liner scrap is narrowing as regional consolidation favors integrated operators. Avery Dennison Corporation leverages its North American collection infrastructure to secure feedstock volumes. Mondi anchors European mechanical recycling capacity through proprietary de-siliconization systems. Techlan Ltd specializes in closed-loop services for UK label converters, competing on logistics density rather than scale.
Release liner recycling encompasses the recovery and reprocessing of carrier materials—typically glassine, kraft paper, or polymer films coated with silicone release agents—after their separation from pressure-sensitive adhesive constructions. Silicone-coated papers dominate feedstock volumes due to their prevalence in labeling and tape applications, though polyethylene-based liners present higher residual value after chemical washing. The mechanical process segment leads current installed capacity, while chemical recycling routes for silicone recovery command premium offtake from adhesive compounders seeking circular raw material credentials. Healthcare end users are driving specification tightening for recycled-content liners, creating margin pools around batch-traceable output.
EPA industrial waste rules and EU REACH restrictions on landfill of silicone-coated substrates shape collection economics on both sides of the Atlantic. The EU Green Deal packaging mandates and California's extended producer responsibility frameworks are tightening access for non-certified recyclers. Stakeholders must track regulatory divergence between US state-level programs and harmonized EU standards when siting preprocessing capacity.
Market Dynamics
Collector-processor consolidation across Germany, the United States, and China is concentrating feedstock access under vertically integrated operators, squeezing independent recyclers out of regional supply chains.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal mandates recycled content thresholds for packaging materials, compelling label converters to source certified recycled-content release liners from approved processors.
- Healthcare specification tightening:Medical device manufacturers and pharmaceutical labelers are imposing batch-traceability requirements that premium recyclers can satisfy, creating margin pools around audit-ready output.
- Mechanical recycling infrastructure scaling:Specialized de-siliconization systems in Germany and the Netherlands have achieved commercial throughput rates that lower unit processing costs for glassine and kraft paper feedstocks.
Market Restraints
- Silicone coating chemistry variability:Inconsistent curing agents and cross-link densities across supplier bases complicate mechanical recycling yield predictions and off-spec rates.
- Polyethylene liner feedstock concentration:High-value PE-based liner collection concentrates in East Asian converting clusters, limiting European and North American chemical recyclers to lower-margin paper substrates.
- REACH registration burdens:ECHA requirements for recycled silicone oil re-entry into adhesive compounder supply chains impose documentation costs that exclude small-volume processors.
Strategic Opportunities
- India packaging sector penetration:BIS standards for sustainable packaging are emerging, creating first-mover positioning for recyclers establishing collection networks in Maharashtra and Gujarat converting hubs.
- Chemical recycling technology convergence:Pyrolysis-based silicone recovery paired with solvent washing of polymer films enables circular raw material credentials for premium adhesive compounders.
- Extended producer responsibility frameworks:California's SB 54 implementation creates mandated recycling volume obligations that certified processors can contract against.
Industry Challenges
- De-siliconization technician scarcity:Operating specialized mechanical recycling equipment requires process chemistry expertise that vocational training programs have not yet scaled.
- Multi-site certification audit complexity:Achieving FSC or equivalent chain-of-custody accreditation across distributed collection networks stretches quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Release Liner Recycling Market |
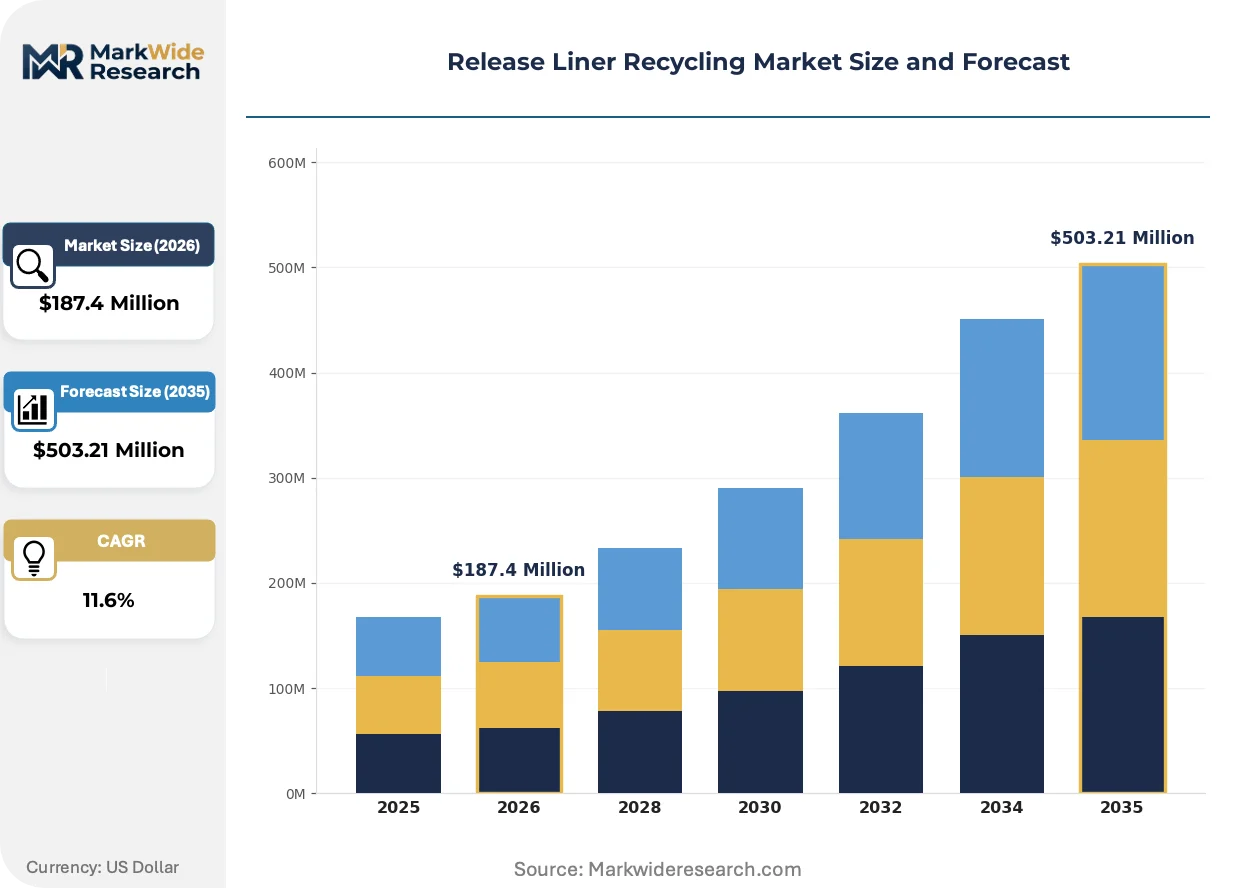
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicone, Polyethylene, Polyester, Paper End User: Healthcare, Packaging, Electronics, Automotive Process: Mechanical, Chemical, Thermal, Biodegradable Application: Adhesives, Tapes, Labeling, Protective Films |
| Companies Covered | 3M, Loparex, Avery Dennison Corporation, Mondi, Ahlstrom, Techlan Ltd, Channeled Resources Group, UPM, Fox River Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Release Liner Recycling Market Evolving Landscape
Digital tracking systems and policy mandates are restructuring how release liner recyclers prove provenance and access premium offtake channels.
Blockchain-based material passports are digitizing chain-of-custody documentation for post-industrial liner scrap. Healthcare label converters in Germany and Switzerland are mandating these systems for audit readiness. The technology is digitizing compliance workflows that previously required manual batch reconciliation, compressing certification timelines from weeks to days.
REACH restrictions on landfill of silicone-coated substrates are tightening across EU member states. The regulation is diverting feedstock volumes from waste-to-energy incineration toward mechanical and chemical recycling routes. German label converters are responding by consolidating supplier relationships around processors with ECHA-registered output streams.
Specification-driven procurement now dominates buyer behavior among multinational adhesive tape manufacturers. Long-term offtake agreements with certified recyclers are displacing spot-market purchasing in North American and European supply chains. This pattern is most visible in automotive and electronics end-uses where OEM circularity targets cascade down through tiered supplier contracts.
Release Liner Recycling Market Segmentation
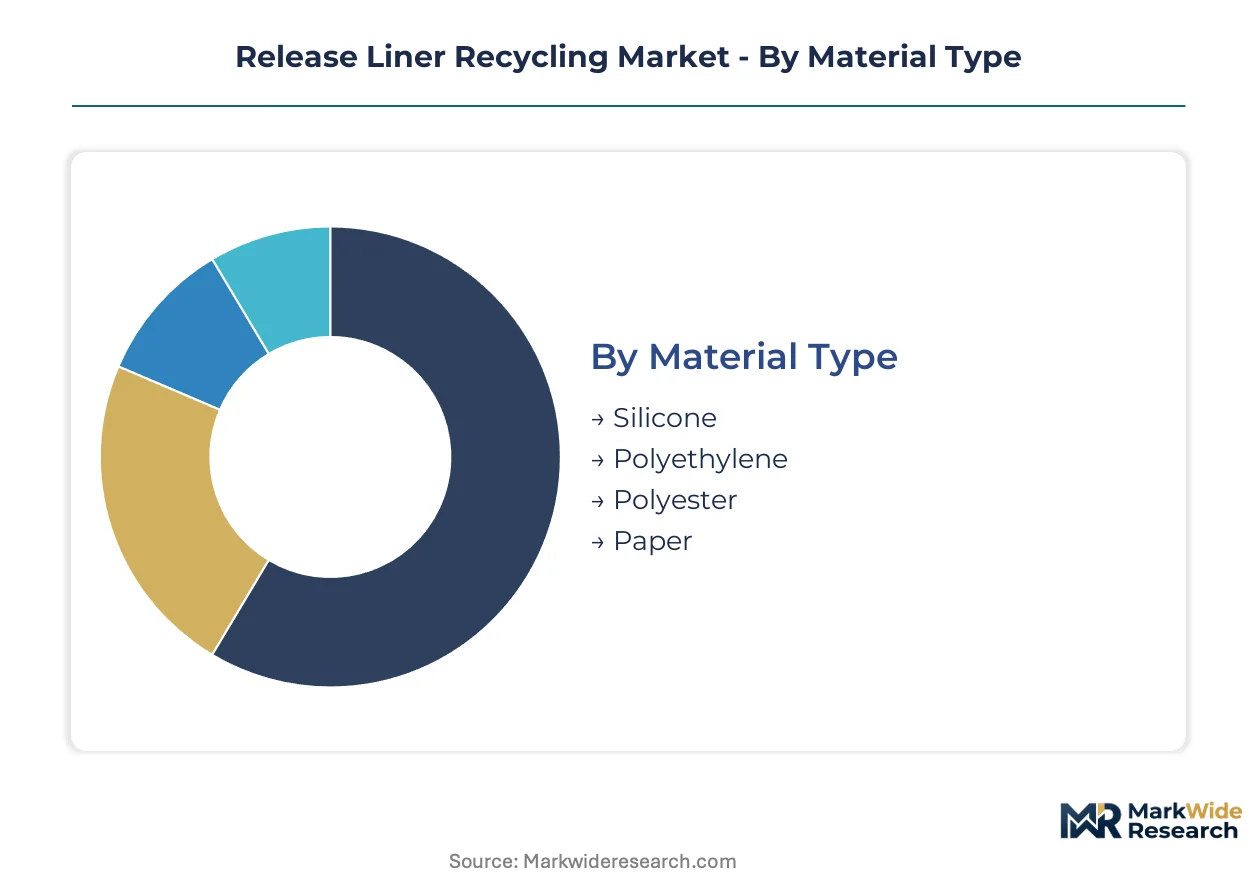
Release liner recycling economics hinge on material chemistry and contamination profiles. Each segment demands distinct preprocessing investments and commands divergent offtake premiums from adhesive compounders.
Material Type:
Cost tier structures separate high-residual-value polymer films from commodity paper substrates.
- Silicone:Cross-linked polydimethylsiloxane coatings dominate labeling applications. REACH registration requirements for recovered silicone oil re-entry limit processor participation to ECHA-registered operators in Germany and the Netherlands.
- Polyethylene:Low-density PE liners from tape backing carry premium recovery economics. East Asian converting clusters in Japan and South Korea concentrate collection volumes, constraining European chemical recyclers to lower-margin alternatives.
- Polyester:PET release films serve electronics and industrial tape markets. Solvent washing yields food-grade regrind for non-liner applications.
- Paper:Glassine and kraft substrates represent volume feedstock. Mechanical de-siliconization in German facilities achieves commercial scale.
Silicone holds installed capacity. Polyethylene is rotating up the share rankings.
End User:
Application-specific purity requirements stratify processor certification burdens and margin capture.
- Healthcare:Pharmaceutical labelers impose batch-traceability mandates. Swiss and German medical device manufacturers contract exclusively against blockchain-documented chain-of-custody systems.
- Packaging:Food and beverage label converters drive EU Green Deal compliance demand. California SB 54 extended producer responsibility frameworks create mandated recycling volume obligations.
- Electronics:Cleanroom specifications for display and semiconductor packaging limit qualified recyclers. Japanese OEM circularity targets cascade through tiered supplier contracts.
- Automotive:Interior trim and exterior badge adhesives tolerate broader contamination windows. Tier-1 suppliers source cost-optimized mechanical recycling output.
Packaging commands volume leadership. Healthcare is expanding most quickly.
Process:
Technology maturity curves separate scaled mechanical operations from emerging chemical routes.
- Mechanical:De-siliconization systems shred and wash coated papers. German and Dutch facilities achieve throughput rates that lower unit processing costs.
- Chemical:Solvent extraction and pyrolysis recover silicone oils and polymer resins. Premium offtake from adhesive compounders seeking circular raw material credentials commands price premiums.
- Thermal:Energy recovery from silicone-coated substrates faces tightening EU landfill restrictions. Waste-to-energy diversion toward material recovery is accelerating.
- Biodegradable:Emerging compostable liner alternatives require separate collection streams. Limited commercial scale constrains processor participation.
Mechanical recycling anchors current infrastructure. Chemical routes are climbing the fastest.
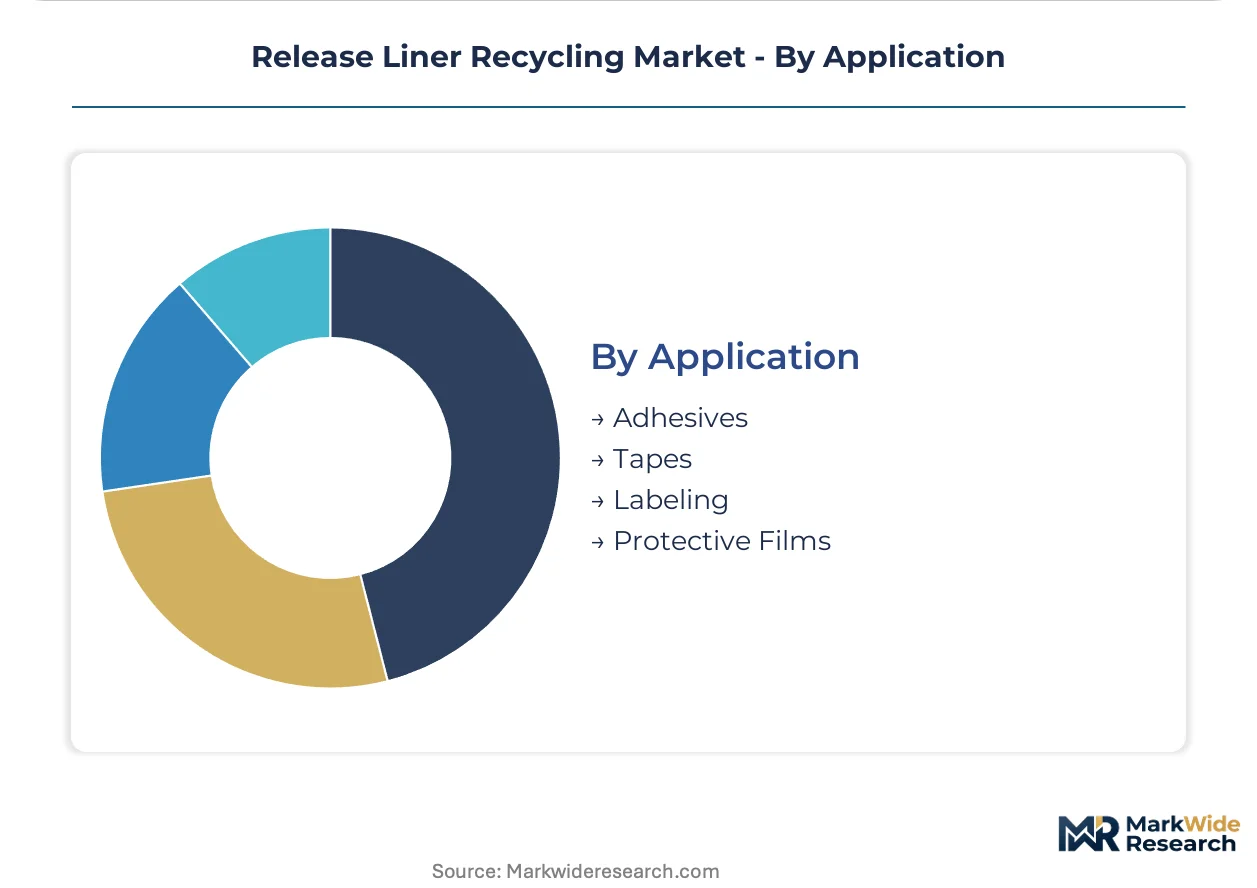
Application:
Customer type concentration determines collection logistics density and preprocessing standardization.
- Adhesives:Pressure-sensitive adhesive compounders purchase recovered silicone oils. ECHA registration documentation requirements exclude small-volume processors from this offtake channel.
- Tapes:Industrial and consumer tape manufacturers generate concentrated post-industrial scrap. East Asian converting clusters in China and Taiwan concentrate high-value PE liner feedstock.
- Labeling:Self-adhesive label converters produce homogeneous glassine waste streams. UK and German collection networks achieve logistics density that supports closed-loop services.
- Protective Films:Electronics and automotive surface protection films carry optical-grade cleanliness requirements. Limited qualified recyclers capture margin premiums.
Labeling dominates feedstock volumes. Adhesives is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA registration requirements and specialized mechanical recycling infrastructure anchor Germany's dominance in European release liner recovery. National regulatory frameworks and converting cluster density determine feedstock access across major processing geographies.
Germany
Pharmaceutical labelers in Baden-Württemberg and automotive adhesive suppliers in Bavaria drive certified recycled-content demand. The EU Green Deal packaging mandates and REACH compliance requirements compel converters to source ECHA-registered output streams. Specialized de-siliconization facilities in the Rhine-Ruhr region achieve commercial throughput rates that lower unit processing costs for glassine feedstocks.
United States
California's SB 54 extended producer responsibility framework creates mandated recycling volume obligations for packaging converters. EPA industrial waste rules shape collection economics across state-level programs with divergent compliance thresholds. Avery Dennison Corporation leverages North American collection infrastructure to secure post-industrial scrap volumes from Midwest labeling clusters.
China
East Asian converting clusters in Guangdong and Jiangsu provinces concentrate high-value polyethylene liner feedstock from tape manufacturers. MEE environmental enforcement and dual carbon goals divert silicone-coated substrates from landfill toward material recovery routes. Japanese OEM circularity targets cascade through tiered supplier contracts into Chinese electronics packaging supply chains.
India
BIS standards for sustainable packaging are emerging in Maharashtra and Gujarat converting hubs, creating first-mover positioning opportunities. The PLI scheme for advanced manufacturing indirectly supports packaging sector modernization. Techlan Ltd competes on logistics density through closed-loop services for UK label converters with comparable network models applicable to Indian market development.
Switzerland
Swissmedic batch-traceability requirements for medical device manufacturers impose blockchain-documented chain-of-custody systems on liner suppliers. Healthcare specification tightening creates margin pools around audit-ready output that premium recyclers can satisfy. Basel and Zurich pharmaceutical clusters contract exclusively against certified processors with full material passport documentation.
Release Liner Recycling Market Competitive Landscape
Vertically integrated material companies and specialized recycling service providers split the market along feedstock control versus processing technology vectors. Collector-processor consolidation favors operators with proprietary de-siliconization systems or captive collection networks. Three archetypes dominate: integrated paper and packaging conglomerates with backward recycling capacity, standalone mechanical recycling specialists, and regional logistics-focused service providers. Competitive moves center on collection infrastructure expansion and ECHA registration acquisition for silicone oil re-entry into adhesive compounder supply chains.
Among integrated packaging conglomerates, Mondi anchors European mechanical recycling capacity through proprietary systems. Avery Dennison Corporation represents the collection-network archetype with North American infrastructure securing feedstock volumes. Techlan Ltd exemplifies regional service specialization, competing on logistics density for UK label converters rather than processing scale. These three occupy positions across the strategic spectrum from scale-driven integrated operations to niche closed-loop services.
| Leading Market Players |
|---|
| 3M |
| Loparex |
| Avery Dennison Corporation |
| Mondi |
| Ahlstrom |
| Techlan Ltd |
| Channeled Resources Group |
| UPM |
| Fox River Associates |
| Others |
Value Network & Pricing Analysis
Undercapacity in German de-siliconization facilities is tightening supplier discipline and pushing contract pricing toward premium tiers for ECHA-registered output. Buyers face stepped cost structures as mechanical recycling throughput constraints concentrate negotiating leverage among integrated operators with proprietary systems.
Pricing Analysis
Geographic price spreads between German mechanical recyclers and East Asian chemical processors exceed fifty percent for comparable silicone recovery grades. Contract-based long-term offtake agreements dominate procurement patterns among pharmaceutical labelers and automotive adhesive compounders seeking supply security. Price differentiation rests on certification tier—ECHA-registered output commands substantial premiums over non-registered alternatives. Cost compression in standard-grade glassine recycling is intensifying because Mondi and Avery Dennison Corporation are scaling captive capacity. Healthcare end users demonstrate lowest price sensitivity due to Swissmedic batch-traceability mandates, while packaging converters face acute margin pressure from California SB 54 compliance costs.
Supply Chain Analysis
Upstream feedstock access concentrates in Germany, China, and the United States where post-industrial scrap generation clusters around converting hubs. Raw material dependencies center on silicone-coated glassine from label manufacturers, polyethylene liners from tape producers, and polyester films from electronics packaging. Supply chain risk stems from REACH registration documentation requirements that exclude small-volume processors from adhesive compounder supply chains. Distribution runs through vertically integrated collector-processor networks rather than spot-market intermediaries, with logistics density determining competitive positioning in UK and German closed-loop services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Release liner recycling is reconfiguring as a service-attach business where blockchain-documented chain-of-custody systems and certification management expand recurring revenue faster than commodity material sales. Logistics-intensive closed-loop contracts now generate margin premiums that hardware-centric competitors cannot replicate.
For Market Incumbents: Pre-empt independent recycler consolidation by acquiring regional collection networks in Maharashtra and Gujarat before BIS standards mature. Secure ECHA registration for silicone oil re-entry to defend against chemical recycling entrants targeting adhesive compounder offtake. Capacity addition in the Rhine-Ruhr region reinforces throughput advantages as de-siliconization technician scarcity worsens.
For New Entrants and Emerging Players: Build out chemical recycling infrastructure for polyethylene liner recovery in South Korea and Japan where East Asian converting clusters concentrate high-value feedstock. India's packaging sector penetration offers the most penetrable geography given emerging BIS standards and limited incumbent logistics density. Position around audit-ready output for healthcare labelers as a go-to-market angle that commands premium pricing.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized mechanical recyclers with proprietary de-siliconization systems and existing ECHA registration rather than commodity collection assets. Long-term viability across the analysis window favors operators integrating digital tracking systems for material passport documentation. Watch for California SB 54 enforcement intensity as the inflection signal determining mandated recycling volume contract availability.
| Strategic Initiative | Industry Significance |
|---|---|
| ECHA Registration Acquisition | Unlocks silicone oil re-entry into adhesive compounder supply chains under REACH compliance. |
| Backward Integration into Collection | Captures feedstock volumes from Midwest and Rhine-Ruhr labeling clusters before competitors. |
| Blockchain Material Passport Deployment | Compresses Swissmedic audit timelines from weeks to days for healthcare labelers. |
| Chemical Recycling Capacity Buildout | Enables pyrolysis-based silicone recovery for premium circular raw material credentials. |
| Regional Logistics Network Expansion | Establishes closed-loop service density in Maharashtra and Gujarat ahead of BIS standardization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration databases, SEC 10-K filings, and EU packaging directive implementation reports. Interviews with label converter procurement directors, mechanical recycling plant managers, adhesive compounder technical sourcing leads, and pharmaceutical packaging regulatory affairs officers informed demand-side validation. Bottom-up feedstock volume estimates from German and Chinese converting clusters were triangulated against top-down market sizing derived from liner consumption coefficients across end-use applications.
Forecast inputs considered material type segmentation by silicone, polyethylene, polyester, and paper substrates alongside process technology splits across mechanical, chemical, thermal, and biodegradable routes. End-user segmentation incorporated healthcare, packaging, electronics, and automotive purity requirements as demand drivers. CAGRs were derived from installed capacity expansion trajectories, regulatory mandate implementation schedules, and OEM circularity target cascades across the projection horizon. De-siliconization throughput rates and ECHA registration approval timelines served as industry-specific forecast inputs.
Stress conditions across REACH enforcement intensity, silicone coating chemistry variability, and de-siliconization technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization between US state-level programs and EU standards. Cross-checking against adhesive compounder procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
North America E-Waste Management Market