
 Electronic Waste Recycling Market | 2026-2036
Electronic Waste Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Waste Recycling Market Analysis
Consumer electronics take-back programs is restructuring how original equipment manufacturers fund end-of-life collection networks. Umicore SA leverages pyrometallurgical expertise to recover precious metals from complex circuit board assemblies at industrial scale. Aurubis AG anchors European copper and tin recovery through integrated smelter-refinery complexes in Germany and Bulgaria. SIMS Ltd. competes across Australasia and North America with mechanical shredding and sorting infrastructure tailored to local feedstock mixes.
Electronic waste recycling encompasses the disassembly, shredding, and material separation of discarded electrical and electronic equipment to recover metals, plastics, and rare earth elements with purity thresholds exceeding 95% for copper and 99% for gold in advanced hydrometallurgical circuits. The process serves primary industrial purpose by reducing virgin mining dependency while neutralizing lead, mercury, and cadmium hazards embedded in legacy devices. Metals recovery dominates value capture given concentrated precious metal content in printed circuit boards and cathode ray tube glass, while hydrometallurgy represents the fastest-growing technology segment as operators seek lower-emission alternatives to high-temperature smelting. Mechanical processing remains the volume backbone for plastic and ferrous fraction separation despite thinner margins per tonne processed.
The EPA oversees hazardous waste classification under RCRA in the United States, while the EU WEEE Directive mandates collection targets and recycling efficiencies across member states with ECHA restricting persistent organic pollutants through REACH annex amendments. These frameworks shape demand by forcing manufacturers to internalize collection costs and certify destruction of data-bearing components. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments and digital product passports alter competitive economics for cross-border material flows.
Market Dynamics
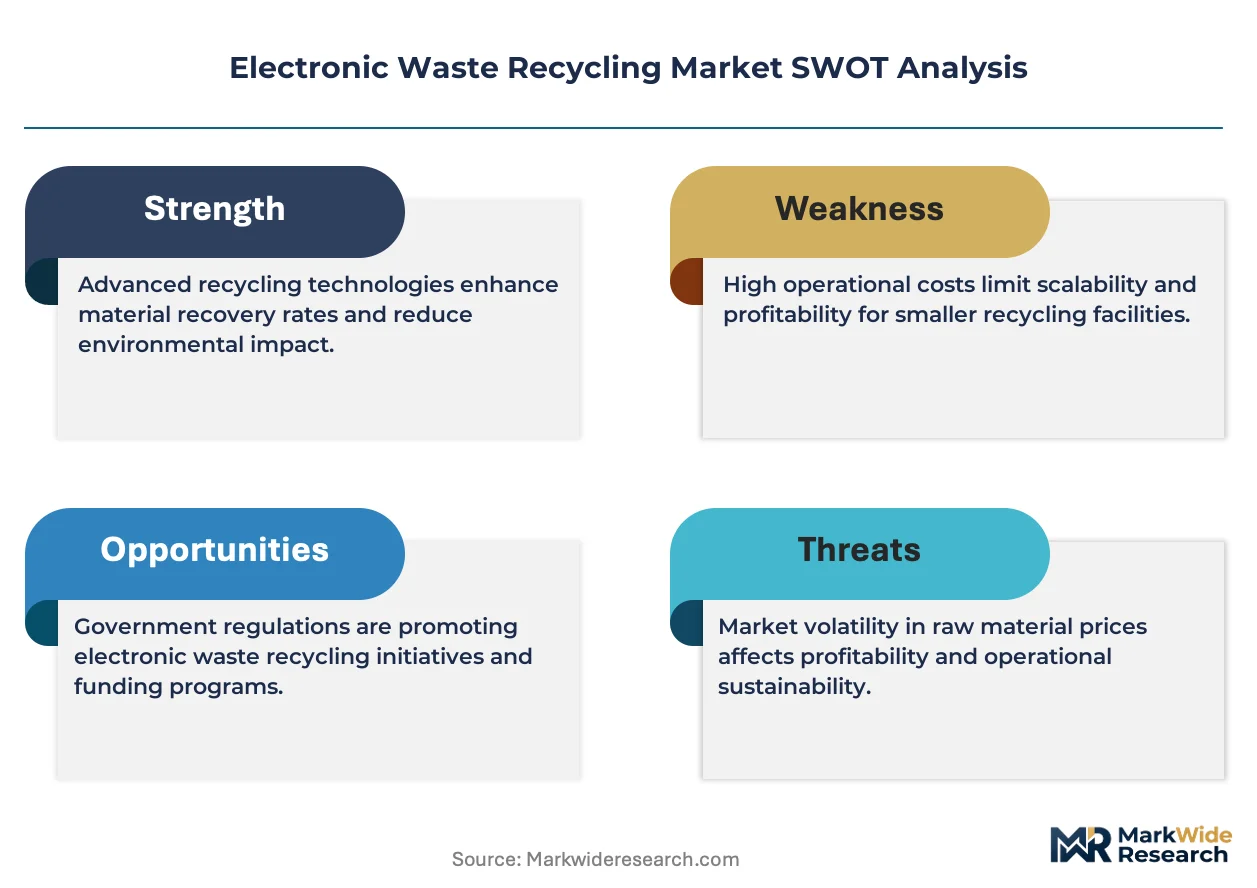
Extended producer responsibility mandates are forcing original equipment manufacturers to internalize end-of-life collection costs, fundamentally restructuring capital allocation across the electronics value chain. This regulatory pressure is accelerating investment in automated disassembly and urban mining infrastructure as compliance costs exceed landfill economics.
Growth Catalysts
- EU WEEE Directive collection targets:Member states must achieve specified recovery rates for electrical equipment, compelling manufacturers to fund dedicated take-back networks and certified recycling partnerships.
- Battery-grade lithium recovery:Hydrometallurgical circuits now extract cobalt and lithium from spent power cells at purities meeting cathode manufacturing specifications, creating closed-loop supply for electric vehicle producers.
- China's urban mining clusters:Concentrated refining capacity in Guangdong and Jiangsu provinces processes imported circuit board fractions at scale, anchoring regional material security strategies.
Market Restraints
- Copper concentrate price volatility:Smelter feedstock costs fluctuate with mining output disruptions, compressing margins for pyrometallurgical operators dependent on purchased secondary materials.
- Basel Convention cross-border restrictions:Hazardous e-waste shipment classifications require pre-notification protocols that delay material flows between OECD and non-OECD jurisdictions.
- Mechanical sorting yield ceilings:Optical and magnetic separation systems face hard limits recovering sub-millimeter precious metal fractions from shredded mixed plastics.
Strategic Opportunities
- India's informal sector formalization:Draft e-waste management rules mandate producer responsibility for imported electronics, creating first-mover advantage for integrated collection-smelting investments.
- Digital product passport mandates:EU battery and electronics regulations will require material composition disclosure, enabling premium pricing for certified recycled content.
- Artificial intelligence-optical sorting convergence:Machine vision trained on component databases identifies high-value fractions upstream, reducing downstream smelter energy intensity.
Industry Challenges
- Smelter emissions compliance timelines:EPA Maximum Achievable Control Technology standards for secondary copper require scrubber retrofits that strain mid-cap operator balance sheets.
- Data destruction certification bottlenecks:NIST 800-88 and DoD 5220.22-M wipe protocols for storage media extend processing times and require specialized shredding equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Waste Recycling Market |
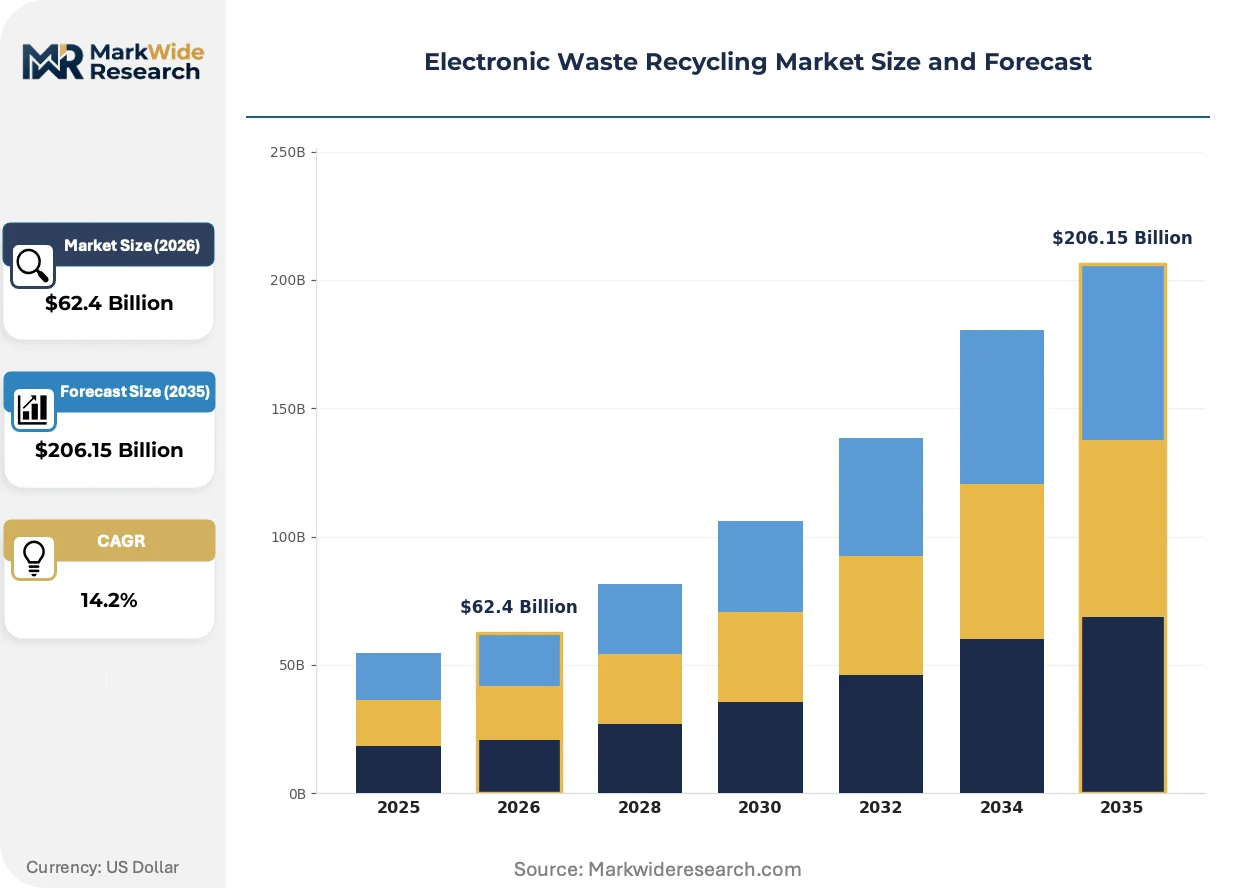
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $206.15 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Curbside Pickup, Drop-off Centers, Buy-back Programs, Collection Events Material Type: Metals, Plastics, Glass, Circuit Boards End User: Consumers, Businesses, Manufacturers, Government Agencies Recycling Technology: Mechanical Processing, Pyrometallurgy, Hydrometallurgy, Biorecycling |
| Companies Covered | Umicore SA, Aurubis AG, Veolia, SIMS Ltd., Enviro-Hub Holdings Ltd., Boliden Group, Electronic Recyclers International, Quantum Lifecycle Partners, Stena Metall AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Waste Recycling Market Emerging Trajectories
Deep learning and robotics are converging to automate identification and disassembly of heterogeneous electronic waste streams, compressing labor costs while improving material recovery precision. These advances are reshaping facility economics and geographic competitiveness.
Deep eutectic solvent systems are electrifying hydrometallurgical extraction by operating at ambient temperatures with water-based chemistry, eliminating sulfuric acid hazards. European refiners are piloting these circuits for gold and palladium recovery from mobile phone assemblies. The technology is compressing energy requirements and enabling distributed processing closer to collection points.
REACH annex amendments restricting persistent organic pollutants in recycled plastics are forcing compounders to certify flame-retardant content thresholds. ECHA enforcement has tightened testing protocols for polybrominated diphenyl ethers in ABS housings recovered from obsolete monitors. Electronics brands sourcing recycled resin for new enclosures now require third-party verification of contaminant levels.
Corporate procurement departments are embedding recycled content mandates into supplier scorecards, displacing price-only sourcing for plastic and metal feedstocks. Tier-one electronics manufacturers now specify minimum post-consumer recycled percentages in molded components and copper conductors. This preference shift is most visible in Germany and California where supply chain disclosure laws expose sourcing footprints.
Electronic Waste Recycling Market Segmentation
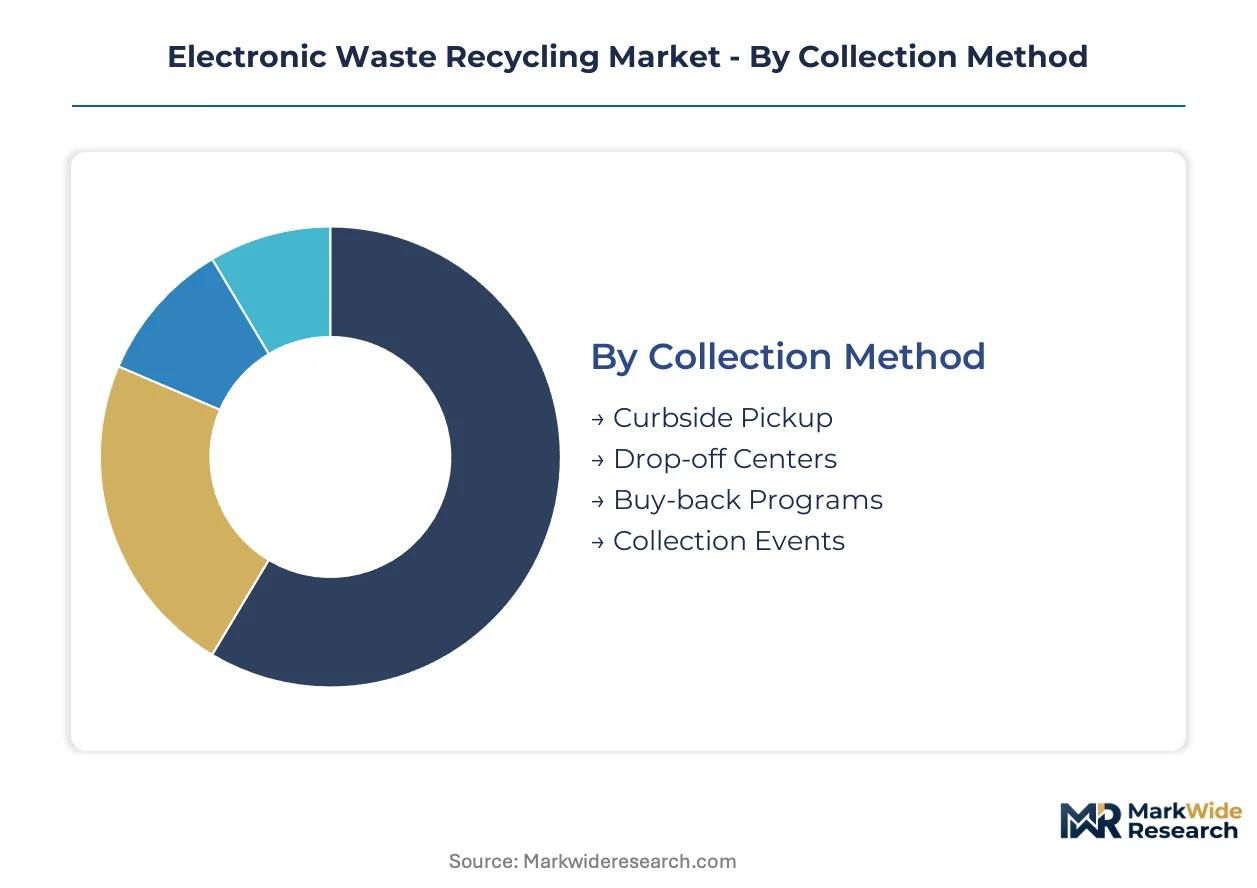
E-waste recycling operators configure service portfolios around certification requirements that vary sharply by material hazard class and collection source. Segment boundaries determine capital intensity, regulatory exposure, and margin structure across facility networks.
Collection Method:
EPA RCRA hazardous waste generator status and EU WEEE Directive compliance obligations diverge sharply across collection modalities, dictating transport documentation and liability chains.
- Curbside Pickup:Municipal contracts aggregate residential small electronics through scheduled collection routes with mixed-waste contamination risks. Demand clusters in German cities and California municipalities where EPR mandates fund dedicated fleet operations, though battery thermal incidents complicate truck loading protocols.
- Drop-off Centers:Permanent staffed facilities accept categorized streams with immediate hazard segregation and data destruction witnessing. Germany's dual system operators anchor European network density, while US county programs struggle with rural site economics.
- Buy-back Programs:Retailer-funded trade-in channels require reverse logistics integration and refurbishment resale capabilities.
- Collection Events:Periodic community drives generate volume spikes demanding temporary labor and rapid material exit to smelters.
Leading the category by volume: Drop-off Centers. Growing fastest: Buy-back Programs.
Material Type:
Feedstock composition determines whether facilities face Basel Convention hazardous shipment classifications or routine secondary materials handling.
- Metals:Ferrous, aluminum, and copper fractions command smelter offtake agreements with purity-dependent pricing. China's import restrictions on copper scrap have redirected Southeast Asian refining investment, while European pyrometallurgical operators secure circuit board concentrates under REACH-compliant sourcing.
- Plastics:ABS, polycarbonate, and mixed polymer streams require flame-retardant testing under ECHA POPs restrictions. German compounders now specify bromine-free certification for reprocessed housings, compressing supply from legacy monitor recovery.
- Glass:Cathode ray tube funnel glass contains lead oxide requiring hazardous landfill or lead smelter feedstock routing.
- Circuit Boards:Complex assemblies concentrate precious metals and rare earth elements in small mass fractions.
Metals dominate revenue capture. Circuit Boards are expanding most quickly as urban mining infrastructure scales.
End User:
Generator category shapes data security obligations, collection frequency, and material homogeneity.
- Consumers:Fragmented residential sources yield mixed-device streams with high collection cost per kilogram. US municipal programs and French eco-organisme networks subsidize access, though participation rates vary with device age and awareness campaigns.
- Businesses:Enterprise IT asset disposition demands chain-of-custody documentation and NIST 800-88 certified data destruction. Financial services and healthcare verticals in the US drive premium pricing for onsite shredding and serialized reporting.
- Manufacturers:Post-industrial scrap from assembly operations offers clean, homogeneous feedstock with predictable volumes.
- Government Agencies:Public sector procurement rules mandate recycled content targets and certified destruction for sensitive equipment.
Businesses anchor commercial margins. Manufacturers show steepest volume expansion with EPR compliance deadlines.
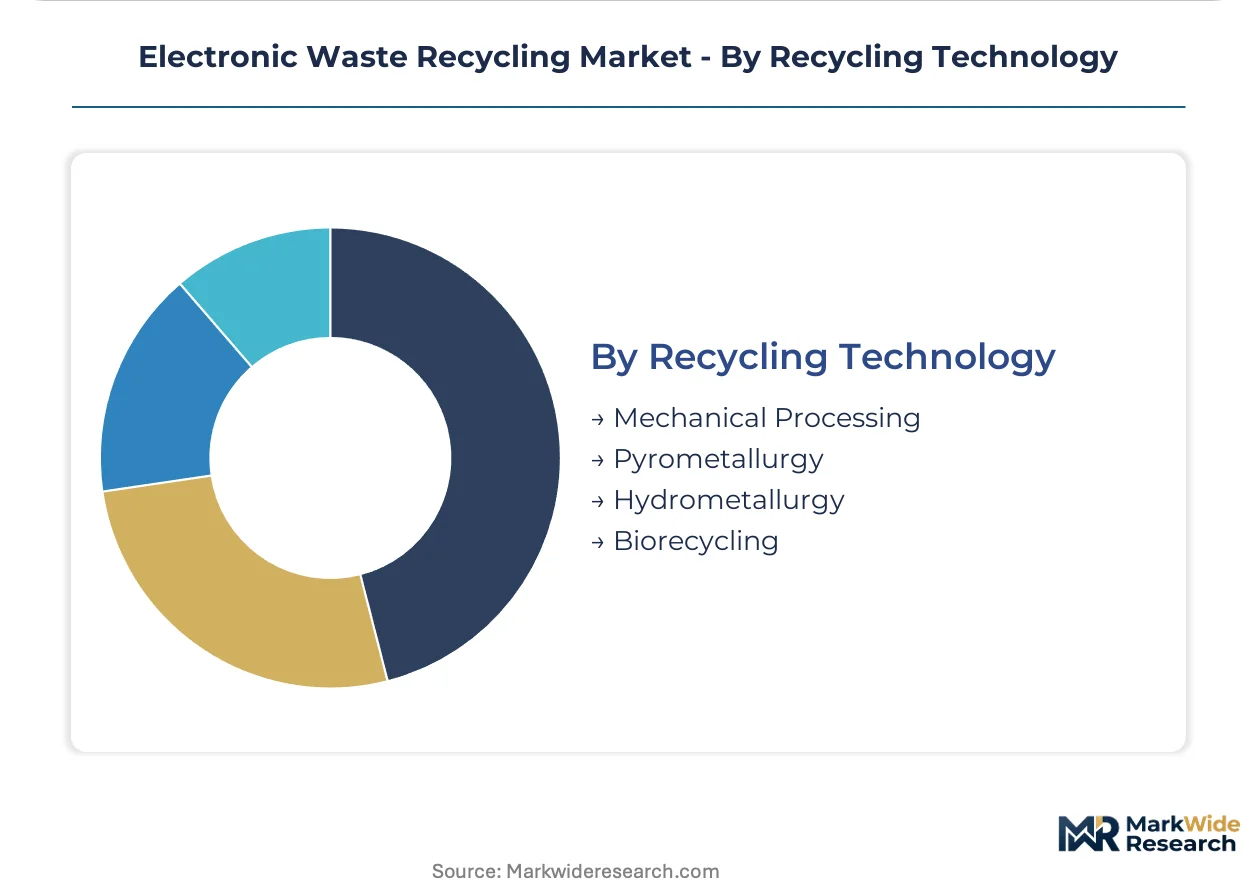
Recycling Technology:
Technology selection locks in energy intensity, emission profiles, and recovery yield curves against tightening EPA MACT and EU Industrial Emissions Directive limits.
- Mechanical Processing:Shredding, magnetic separation, and optical sorting handle volume throughput for plastics and ferrous recovery. Yield ceilings on sub-millimeter precious metal fractions limit value capture, though German and Japanese operators advance AI-guided robotic disassembly.
- Pyrometallurgy:High-temperature smelting recovers copper, gold, and palladium from complex concentrates. Umicore's Hoboken facility and Aurubis's Hamburg complex anchor European capacity, with emissions compliance driving scrubber retrofit investments.
- Hydrometallurgy:Acid and leaching circuits extract battery-grade lithium and cobalt at ambient temperatures. Deep eutectic solvent pilots in Belgium and Finland target gold recovery with reduced energy inputs.
- Biorecycling:Microbial leaching of rare earth elements from phosphors and magnets remains pre-commercial.
Mechanical Processing leads installed capacity. Hydrometallurgy is gaining share fastest with electric vehicle battery feedstock demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The gap between electronics consumption and domestic recycling capacity varies sharply across major economies. Germany and China operate surplus refining infrastructure that processes imported feedstocks, while India and Brazil rely on informal collection networks that formalization mandates are now disrupting.
United States
Enterprise IT asset disposition and federal government surplus equipment drive commercial volume. EPA RCRA hazardous waste classifications and state-level extended producer responsibility laws in California and New York shape compliance costs. The Southeast and Midwest concentrate mechanical shredding capacity near population centers and transport corridors.
Germany
Dual system operators fund dense collection networks through EPR fees on new electronics sales. The EU WEEE Directive mandates collection targets enforced by national regulators, while ECHA REACH restrictions on flame retardants in recycled plastics tighten material specifications. The Hamburg and Lünen industrial corridors anchor pyrometallurgical refining complexes serving circuit board concentrates from across Europe.
China
Domestic e-waste generation from consumer electronics replacement cycles now exceeds import-dependent processing volumes. The Ministry of Ecology and Environment enforces import bans on foreign scrap while promoting urban mining clusters in Guangdong and Jiangsu provinces. Qingyuan and Taizhou concentrate hydrometallurgical capacity for rare earth and precious metal recovery.
India
Rapid smartphone penetration and shortening device lifecycles expand feedstock availability faster than formal collection infrastructure can capture. Draft e-waste management rules mandate producer responsibility for imported electronics, with the Central Pollution Control Board licensing dismantlers and refiners. Maharashtra and Karnataka host emerging integrated facilities targeting battery-grade metal recovery.
Japan
Meti's home appliance recycling law mandates manufacturer-funded collection for specified categories, creating predictable feedstock flows. JIS standards for recycled plastics in electronics enclosures exceed typical international specifications, compressing supply from legacy device recovery. The Kanto and Kansai regions concentrate automated disassembly research and pilot facilities.
Electronic Waste Recycling Market Vendor Landscape
Top-tier vendors anchor integrated smelter-refinery complexes with multi-metal recovery capabilities, while mid-scale operators compete through specialized collection networks or regional mechanical processing infrastructure. The competitive landscape fragments across three archetypes: diversified metals conglomerates with captive electronics recycling divisions, pure-play e-waste specialists scaling automated sorting technology, and waste management groups layering electronics into broader environmental service portfolios. Capacity expansion and strategic partnerships dominate competitive moves as operators seek feedstock security and compliance certification breadth.
Among European-based refiners, Umicore SA and Aurubis AG exemplify the integrated metals recovery archetype, leveraging pyrometallurgical infrastructure to process complex circuit board assemblies at industrial scale. SIMS Ltd. occupies a position representing the geographic diversification strategy, with mechanical processing networks spanning multiple continents to serve local regulatory environments and feedstock mixes.
| Leading Market Players |
|---|
| Umicore SA |
| Aurubis AG |
| Veolia |
| SIMS Ltd. |
| Enviro-Hub Holdings Ltd. |
| Boliden Group |
| Electronic Recyclers International |
| Quantum Lifecycle Partners |
| Stena Metall AB |
| Others |
Supply Flow & Price Mechanics
Copper concentrate feedstock costs cascade through pyrometallurgical smelter economics to compress margins at secondary refiners, while battery-grade lithium recovery premiums attract hydrometallurgical investment toward electric vehicle supply contracts.
Pricing Analysis
Margin tightening in mechanical processing reflects yield ceilings on sub-millimeter precious metal fractions that limit value capture from shredded mixed plastics. Three-tier pricing structure across certified smelter offtake, standard secondary materials, and informal sector collection separates compliance-burdened operators from unlicensed competitors. Cost compression accelerates because China's import restrictions on copper scrap redirect feedstock flows toward Southeast Asian refining capacity. Municipal collection programs exhibit highest price sensitivity due to taxpayer-funded budget constraints, while enterprise IT asset disposition buyers prioritize data destruction certification over unit economics.
Supply Chain Analysis
Cross-border freight costs for hazardous e-waste classifications under Basel Convention pre-notification protocols strain material flows between OECD and non-OECD jurisdictions. Supply concentrates in Germany, China, and the United States where urban mining infrastructure and regulatory enforcement are most developed. Raw material dependencies rest on circuit board concentrates, spent lithium-ion batteries, and cathode ray tube glass containing lead oxide. Single-source vulnerability emerges from China's dominance in rare earth refining capacity. Distribution runs through dual system operators in Europe, county-level programs in the United States, and emerging formal collection networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility mandates are consolidating competitive positions as compliance costs exceed informal sector economics, forcing mid-scale operators toward acquisition or exit.
For Market Incumbents: Deploy automated disassembly robotics to compress labor costs and improve precious metal recovery precision against mechanical sorting yield ceilings. Deepen backward integration into collection networks through municipal contract aggregation, securing feedstock volume against China's import restriction spillover effects. EPA Maximum Achievable Control Technology scrubber retrofits represent a mandatory certification investment that strains competitor balance sheets. For New Entrants and Emerging Players: Digital trade-in platform integration offers a low-capital route to capture consumer electronics reverse logistics before refurbishment resale capabilities mature. India's draft e-waste management rules present the most penetrable geography as producer responsibility mandates formalize informal sector volumes. Target battery-grade lithium recovery from spent power cells as the fastest-expanding application segment. For Investors and Strategic Acquirers: Hydrometallurgical capacity announcements in Belgium and Finland are the leading indicator that deep eutectic solvent technology is approaching commercial scalability for distributed gold recovery. Long-term viability favors integrated collection-smelting operations with multi-metal recovery capabilities and REACH-compliant sourcing certifications. Watch for EU digital product passport implementation timelines as the inflection signal enabling premium pricing for certified recycled content.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Disassembly Robotics Deployment | Umicore and Aurubis pilot AI-guided component identification to reduce downstream smelter energy intensity. |
| Hydrometallurgical Capacity Expansion | Deep eutectic solvent circuits in Belgium target ambient-temperature gold recovery with reduced acid hazards. |
| Backward Integration into Collection Networks | German dual system operators aggregate municipal contracts to secure circuit board concentrate feedstock volumes. |
| Digital Product Passport Compliance Investment | EU battery regulations will require material composition disclosure for premium recycled content pricing. |
| Informal Sector Formalization Partnerships | India's Central Pollution Control Board licensing creates first-mover advantage for integrated dismantler-refiner facilities. |
Methodological Framework
Document review covered EPA RCRA enforcement actions, EU WEEE Directive implementation reports, Basel Convention amendment protocols, and national hazardous waste trade statistics, complemented by interviews with smelter operations directors, e-waste collection network managers, OEM sustainability officers, and hydrometallurgical process engineers. Secondary validation drew from ECHA REACH restriction amendments, Chinese Ministry of Ecology and Environment import ban notifications, and Indian Central Pollution Control Board licensing records. Bottom-up facility capacity estimates triangulated against top-down material flow analyses across the analysis window.
Segment-level value outputs trace to modeled recovery yields by technology type, feedstock composition premiums, and compliance cost burdens across collection modalities. The analytical framework incorporates material type segmentation, recycling technology pathways, end-user generator categories, and regional regulatory cluster differentiation. CAGRs derive from installed capacity expansion announcements, EPR mandate enforcement timelines, and electric vehicle battery retirement curves. Battery-grade lithium purity specifications and flame-retardant testing protocols under ECHA POPs restrictions inform technology adoption assumptions.
The model holds under sustained EPR enforcement and Basel Convention compliance; deviation in regulatory harmonization or copper concentrate price volatility would shift competitive economics toward informal sector leakage. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Solar Panel Recycling Management Market