
 Landfill Compactor Market | 2026-2036
Landfill Compactor Market Size, Share, and Industry Trends Forecast 2026-2036
Landfill Compactor Market Foresight
Chinese heavy equipment manufacturing is consolidating around state-supported production clusters that now supply landfill compactors across Asia, Africa, and Latin America. Caterpillar Inc. leverages its global dealer network to sustain aftermarket parts revenue and long-term service contracts in mature markets. Komatsu Ltd. anchors its position through integrated machine monitoring and telematics platforms that extend equipment uptime for remote landfill operations. BOMAG GmbH differentiates via specialized compaction drum designs that optimize density achievement per pass.
A landfill compactor is a purpose-built heavy machine equipped with spiked steel wheels or cleated drums that generate high ground pressure to shred, crush, and densify municipal solid waste and cover material within a landfill cell. These machines typically operate at weights exceeding 50 tonnes and achieve compaction densities of 1,200 to 1,400 pounds per cubic yard, enabling operators to maximize airspace utilization and extend landfill operational life. Single-engine compactors occupy the dominant share of unit sales due to lower capital outlay and simpler maintenance protocols, while electric systems represent the fastest-growing technology segment as operators pilot battery-powered units in enclosed transfer stations and urban-adjacent facilities. Multi-engine configurations retain relevance in high-volume sites where redundant power trains minimize downtime risk.
EPA Tier 4 Final and EU Stage V emission frameworks restrict particulate matter and nitrogen oxide outputs from diesel-powered landfill equipment, compelling manufacturers to integrate selective catalytic reduction and diesel exhaust fluid systems. OSHA workplace noise exposure limits and ISO 2631 whole-body vibration standards further shape operator cab design and isolation mounting specifications. Stakeholders must monitor evolving battery-electric range capabilities against the continuous-duty cycle demands of landfill face operations, as charging infrastructure deployment and duty-cycle matching will determine the pace of electrification adoption.
Market Dynamics
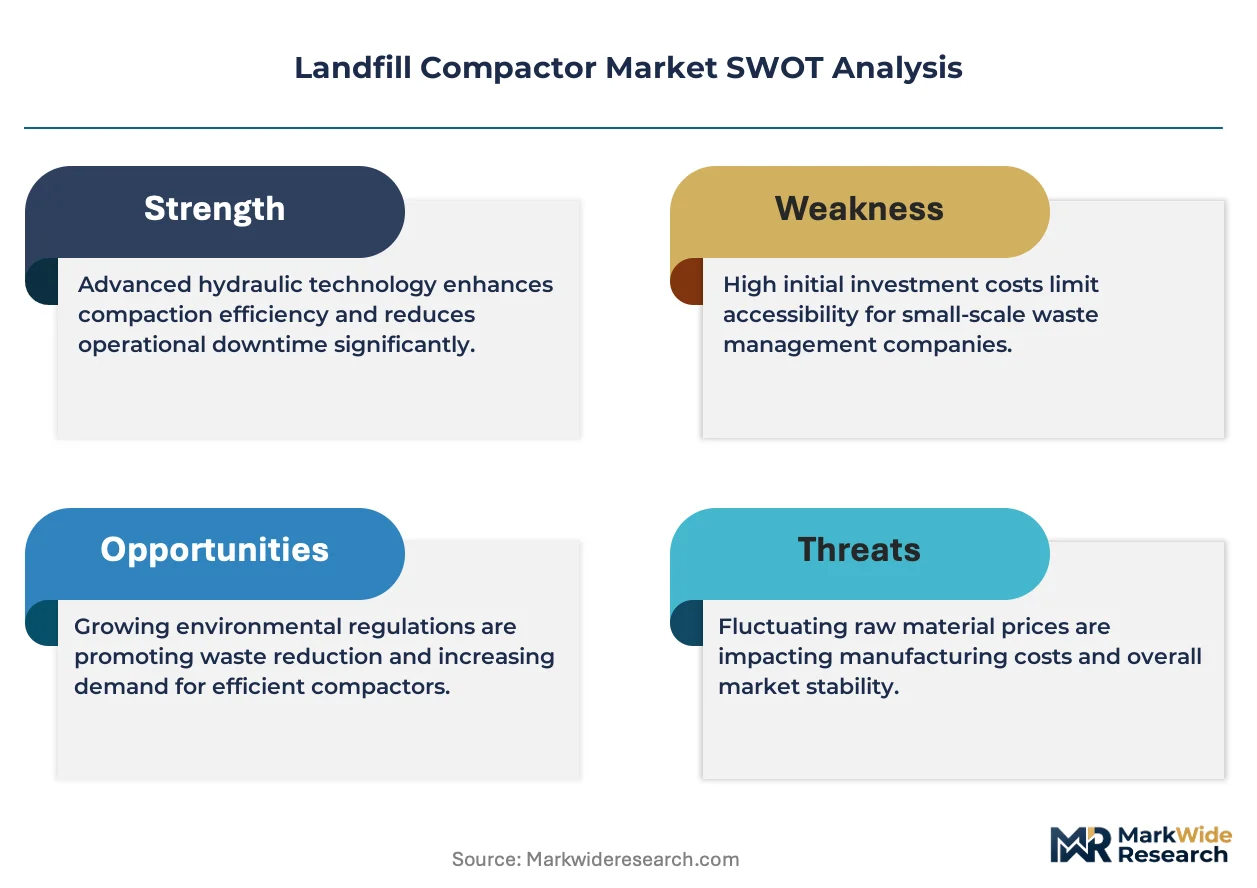
Tier 4 Final emission mandates and the dual carbon goals in China are compressing diesel equipment lifecycles while accelerating electric platform development. Manufacturers must now engineer for regulatory compliance across multiple jurisdictions simultaneously.
Growth Catalysts
- EPA Tier 4 Final:United States emission standards force fleet turnover toward lower-NOx configurations, sustaining replacement demand in mature markets.
- Urbanization in China:State-backed environmental remediation projects drive procurement of heavy compaction equipment for new landfill cell construction.
- Telematics integration:Remote machine monitoring extends equipment uptime and enables predictive maintenance for operators managing distributed sites.
Market Restraints
- Steel and component costs:Volatility in high-grade alloy pricing squeezes manufacturing margins for specialized compaction drum fabricators.
- Supply concentration:Chinese production clusters now dominate Asian, African, and Latin American supply, creating geographic dependency risk.
- Battery duty-cycle mismatch:Current lithium-ion energy density limits continuous operation at landfill faces, constraining electric adoption.
Strategic Opportunities
- Enclosed transfer stations:Zero-emission mandates in urban-adjacent facilities create pilot deployment opportunities for battery-powered compactors.
- Aftermarket service contracts:Long-term parts and maintenance agreements offer recurring revenue streams as equipment fleets age.
- ISO 2631 compliance:Whole-body vibration standards drive cab redesign demand, opening premium positioning for isolation system specialists.
Industry Challenges
- Electrification skill gaps:Maintenance technicians require retraining on high-voltage systems and battery thermal management protocols.
- Charging infrastructure deployment:Landfill sites lack grid capacity for fleet-scale electric conversion, requiring capital-intensive electrical upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landfill Compactor Market |
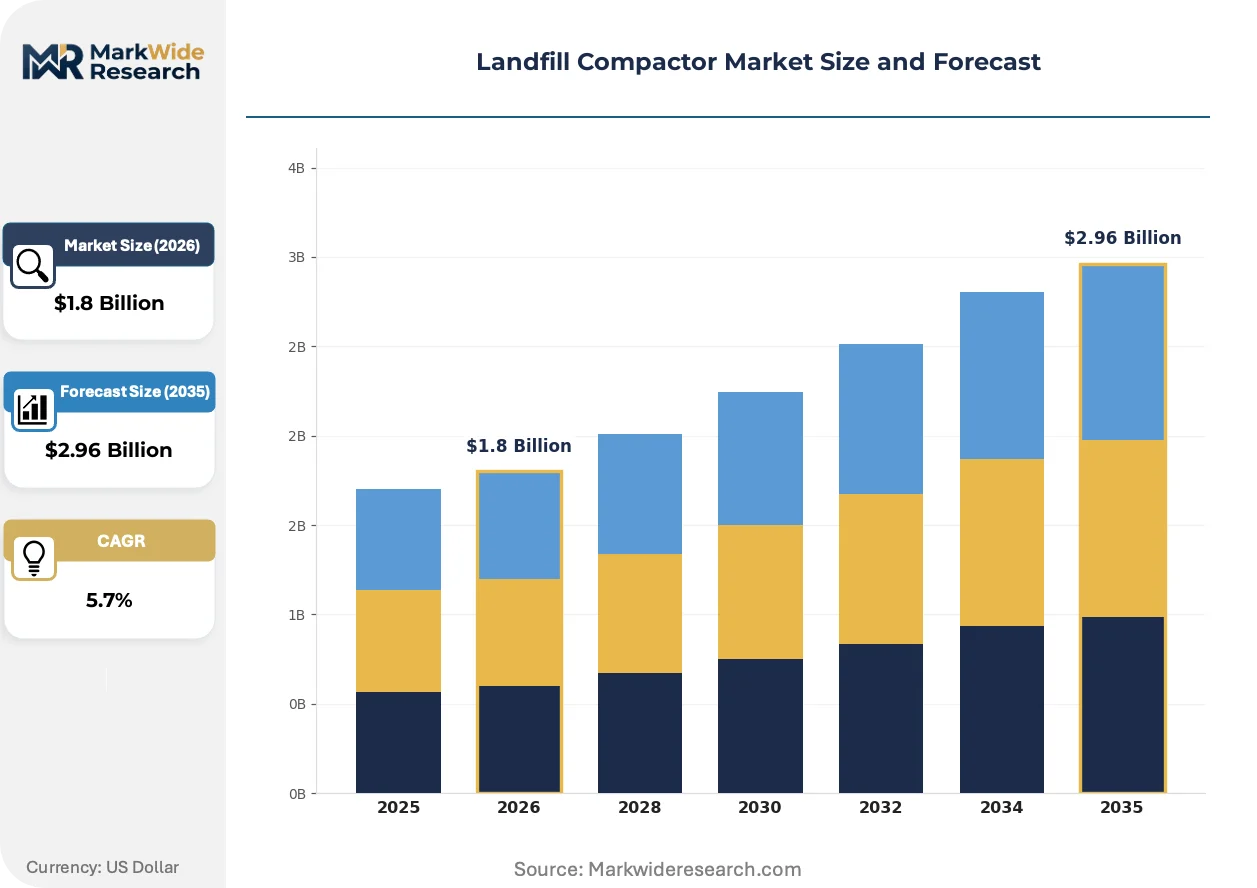
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Engine Compactors, Multi-Engine Compactors, Track Compactors, Rubber-Tired Compactors Technology: Hydraulic Systems, Electric Systems, Pneumatic Systems, Automated Controls End User: Waste Management Companies, Municipalities, Construction Companies, Industrial Facilities Fuel Type: Diesel, Biodiesel, Electric, Others |
| Companies Covered | SINOMACH-Hi International Equipment Co., Ltd., Tana Oy, Caterpillar Inc., Komatsu Ltd., Shantui Construction Machinery Co., BOMAG GmbH, XCMG, Liugong Machinery, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landfill Compactor Market Shifts & Advancements
Landfill compactor development now centers on three vectors: powertrain electrification, emission compliance engineering, and operator environment optimization. Each trajectory carries distinct technical and commercial implications for equipment manufacturers and waste management operators.
Spiked steel wheel designs with variable ground pressure modulation are rewriting compaction efficiency benchmarks. Waste management operators in high-volume municipal sites are adopting these configurations to maximize density per pass and extend cell operational life. The technology is compressing total cost of ownership calculations by reducing fuel consumption and machine hours per ton compacted.
EU Stage V frameworks restrict particulate matter outputs from diesel-powered equipment, compelling integration of selective catalytic reduction and diesel exhaust fluid systems. Manufacturers serving European markets must now engineer for simultaneous compliance with Stage V, EPA Tier 4 Final, and emerging Chinese GB standards. Multi-engine configurations retain relevance in premium segments where redundant power trains minimize downtime risk under stringent emission controls.
Service contract unbundling is fragmenting traditional dealer relationships in mature markets. Large waste management companies now negotiate direct parts procurement and third-party maintenance agreements, bypassing authorized service networks. This pattern is most visible in the United States, where consolidated national operators leverage fleet scale to extract pricing concessions and customize service level agreements.
Landfill Compactor Market Segmentation
Landfill compactor procurement patterns diverge sharply across operational scale, regulatory exposure, and site infrastructure maturity. Equipment specification choices directly determine compliance costs, maintenance intervals, and airspace yield per cell.
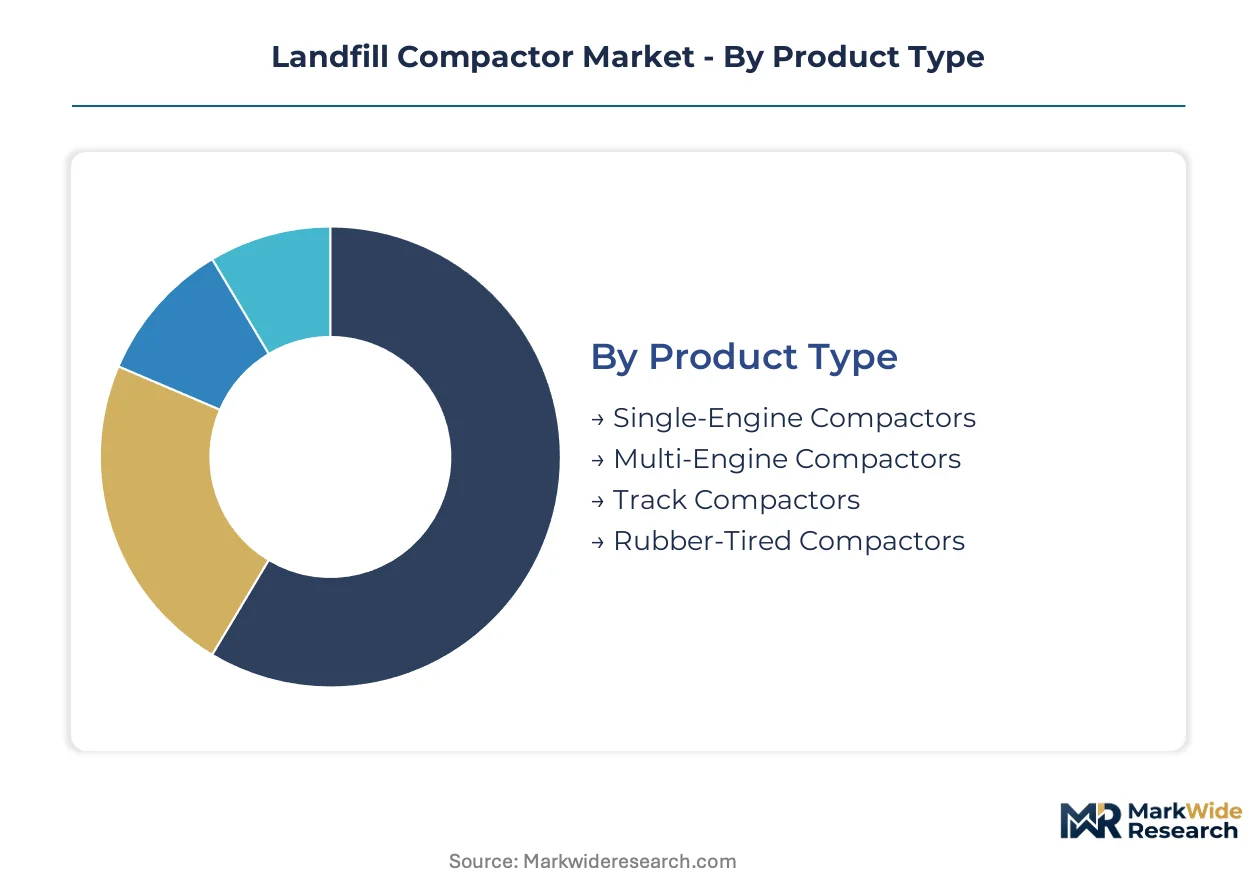
Product Type:
Powertrain architecture defines capital deployment and operational redundancy trade-offs for waste management operators.
- Single-Engine Compactors:These units deploy one diesel powerplant driving all compaction drums through mechanical or hydrostatic transmission. Municipalities in the United States favor this configuration for its lower acquisition cost and simpler EPA Tier 4 Final compliance pathway.
- Multi-Engine Compactors:Redundant engines isolate failure risk across drum sets, sustaining operation when one powerplant requires service. High-volume sites in China specify these for continuous-duty landfill face operations where downtime incurs cell closure penalties.
- Track Compactors:Steel or rubber track undercarriages distribute ground pressure across soft or irregular terrain. These units penetrate saturated cover soils and steep side slopes where wheeled configurations lose traction.
- Rubber-Tired Compactors:Conventional wheel configurations offer higher travel speeds between cells and easier road transport. Operators with distributed satellite sites specify these for fleet flexibility.
Single-engine configurations lead on scale; multi-engine designs lead on momentum in high-volume Asian markets.
Technology:
Control and actuation systems are differentiating total cost of ownership across operator skill levels and site automation maturity.
- Hydraulic Systems:Proportional valve controls modulate drum force in response to waste density feedback. This specification dominates current fleet composition due to technician familiarity and parts availability.
- Electric Systems:Battery-powered actuation and traction motors eliminate diesel exhaust in enclosed transfer stations. Urban-adjacent facilities in the European Union pilot these under Stage V zero-emission mandates, though landfill face deployment remains constrained by duty-cycle mismatch.
- Pneumatic Systems:Compressed air actuation serves specialized drum cleaning and debris clearing functions. These auxiliary systems appear in premium configurations for high-moisture waste streams.
- Automated Controls:Machine guidance and compaction density mapping reduce operator skill dependency. Telematics-integrated fleets in North America adopt these for distributed site management and predictive maintenance scheduling.
Hydraulic systems lead on scale; electric configurations are expanding most quickly in regulated urban corridors.
End User:
Procurement authority and financing structures shape specification priorities across institutional categories.
- Waste Management Companies:National and regional operators standardize fleet specifications to compress parts inventory and technician training costs. These entities drive telematics adoption and negotiate direct service contracts bypassing dealer networks.
- Municipalities:Public procurement cycles favor lowest-life-cycle-cost configurations with transparent emission compliance documentation. EPA and EU Stage V certification requirements dominate municipal specification sheets.
- Construction Companies:General contractors acquire compactors for landfill cell construction and capping projects, prioritizing rental flexibility and rapid deployment over specialized compaction optimization.
- Industrial Facilities:Captive waste generators at manufacturing sites specify smaller units for on-site pre-compaction before third-party haulage. These deployments emphasize noise and emission containment for community relations.
Waste management companies lead on scale; municipalities lead on specification standardization momentum.
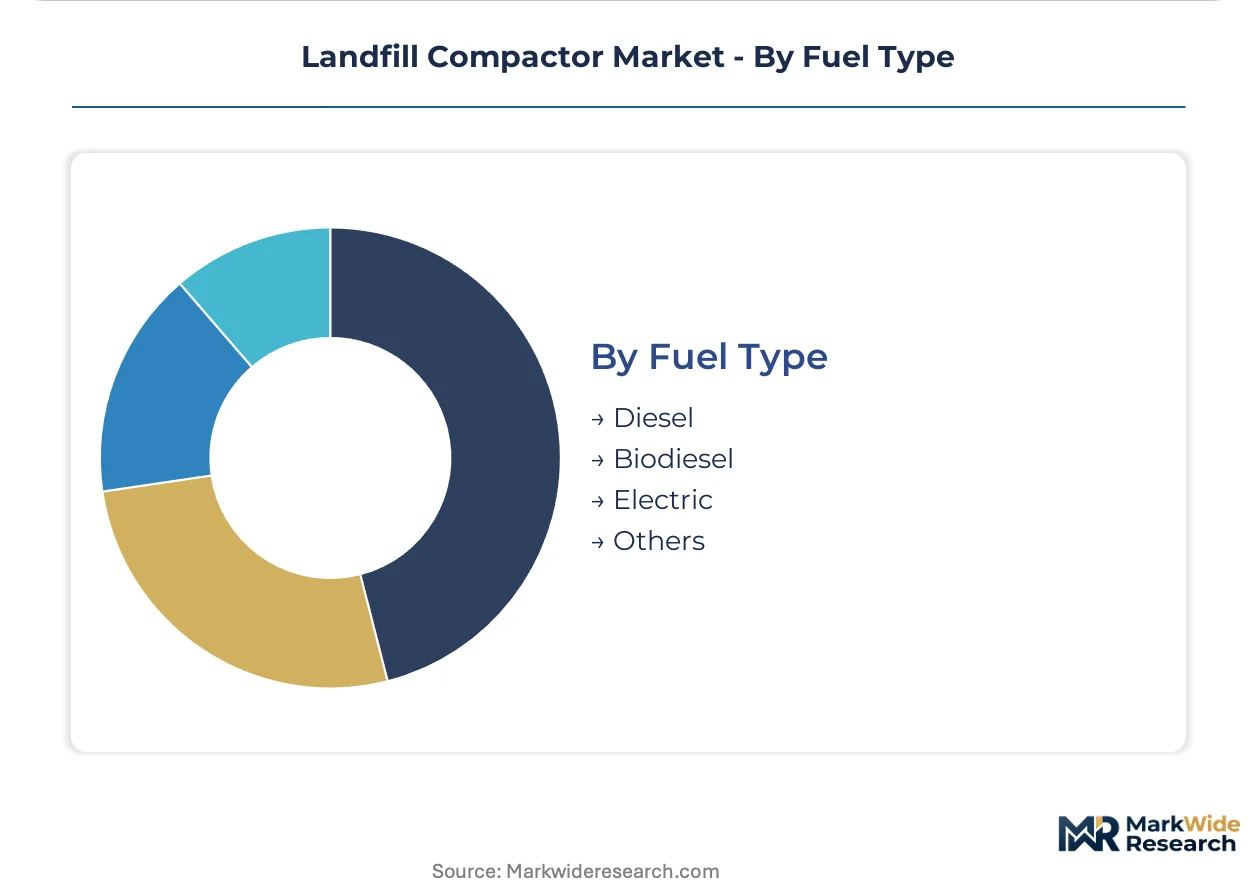
Fuel Type:
Energy source selection determines regulatory compliance pathways and infrastructure investment requirements.
- Diesel:Compression-ignition engines with selective catalytic reduction and diesel exhaust fluid systems satisfy EPA Tier 4 Final and EU Stage V limits. This fuel retains dominance in high-duty-cycle landfill face operations.
- Biodiesel:Renewable diesel and fatty acid methyl ester blends reduce lifecycle carbon intensity for operators with corporate sustainability commitments. Blending ratios remain constrained by cold-weather performance and warranty terms.
- Electric:Battery-electric powertrains eliminate tailpipe emissions and reduce noise signatures. Transfer stations and urban-adjacent facilities in China and the European Union deploy these where grid capacity permits.
- Others:Compressed natural gas and hydrogen fuel cell prototypes serve demonstration projects for zero-emission landfill operations. These configurations remain pre-commercial for continuous-duty applications.
Diesel leads on scale; electric configurations gain share fastest in enclosed and urban-adjacent installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys landfill compactors at triple the annual rate of Germany, yet both markets now prioritize emission-compliant configurations over legacy diesel fleets. Regulatory divergence is compressing equipment lifecycles in mature economies while accelerating first-time procurement in emerging waste infrastructure markets.
United States
EPA Tier 4 Final mandates force municipal fleet turnover toward selective catalytic reduction-equipped diesel units. Waste management companies in Texas and Florida negotiate direct parts procurement contracts that bypass traditional dealer networks. The Southeast region hosts the densest concentration of landfill cell construction activity, driving continuous-duty compactor specifications.
China
Dual carbon goals and state-backed environmental remediation programs compress diesel equipment lifecycles in coastal provinces. MIIT-enforced GB standards accelerate electric platform pilot deployments at urban-adjacent transfer stations. The Yangtze River Delta manufacturing cluster supplies heavy compaction equipment across Asia, Africa, and Latin America.
Germany
EU Stage V particulate matter limits compel diesel exhaust fluid system integration for landfill face operations. KBA certification requirements shape specification sheets for municipal procurement across Bavaria and North Rhine-Westphalia. Stuttgart-based engineering clusters specialize in compaction drum optimization for high-density waste streams.
India
Swachh Bharat Mission urban infrastructure investments drive landfill cell construction in Maharashtra and Gujarat. BIS emission standards for construction equipment tighten compliance pathways for diesel-powered fleets. The Delhi-NCR corridor experiences acute demand for enclosed transfer station compactors as satellite municipalities expand waste handling capacity.
Brazil
ANVISA workplace safety protocols intersect with municipal solid waste volume growth in São Paulo and Rio de Janeiro state contracts. State environmental agencies in Minas Gerais enforce landfill closure timelines that accelerate replacement equipment procurement. The Southeast region concentrates national waste management operator headquarters and fleet standardization decisions.
Landfill Compactor Market Competitive Landscape
Chinese producers anchor the volume tier; German and Japanese specialists hold premium positioning through emission compliance engineering and component integration. The vendor base splits between state-supported manufacturing clusters serving price-sensitive markets and integrated technology providers capturing aftermarket service revenue. Three archetypes dominate: full-line construction equipment multinationals, specialized compaction technology developers, and state-affiliated heavy machinery conglomerates. Competitive moves center on telematics platform integration and geographic expansion through distributor network acquisition.
Within the full-line equipment tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by global parts distribution infrastructure and machine monitoring system deployment. BOMAG GmbH exemplifies the specialized compaction archetype through engineering concentration on drum design and density optimization. Among state-affiliated fabricators, SINOMACH-Hi International Equipment Co., Ltd. and Shantui Construction Machinery Co. represent production scale advantages serving emerging market procurement cycles. Tana Oy sits within the niche technology segment, anchoring innovation positioning for specialized waste handling configurations.
| Leading Market Players |
|---|
| SINOMACH-Hi International Equipment Co., Ltd. |
| Tana Oy |
| Caterpillar Inc. |
| Komatsu Ltd. |
| Shantui Construction Machinery Co. |
| BOMAG GmbH |
| XCMG |
| Liugong Machinery |
| Volvo Construction Equipment |
| Others |
Supply & Pricing Matrix
Sovereign-backed Chinese producers anchor the volume tier, compressing price floors through state-financed capacity additions while German and Japanese specialists defend premium positioning via emission compliance engineering. This ownership dichotomy splits procurement patterns between price-sensitive emerging markets and specification-driven mature economies where total cost of ownership calculations dominate.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-configuration landfill compactors across Asia, Africa, and Latin America. Three-tier pricing structure across premium, standard, and economy levels separates EU Stage V-certified units with telematics integration from basic Tier 4 Final configurations and unregulated legacy fleets. Cost compression in the economy tier intensifies as Yangtze River Delta fabricators absorb steel alloy volatility through state subsidy mechanisms. Municipal procurement officers in India and Brazil exhibit highest price sensitivity, while consolidated waste management companies in the United States prioritize specification standardization over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for aftermarket parts fulfillment, while Chinese producers ship direct-to-port for emerging market contracts. High-grade alloy steel for compaction drums, selective catalytic reduction components, and telematics sensor arrays draw from concentrated supplier bases in China, South Korea, and Germany. Single-source vulnerability around lithium-ion battery modules for electric configurations constrains fleet-scale electrification timelines. Distribution runs through authorized dealer networks in mature markets and state-affiliated trading companies in Belt and Road corridor countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Landfill compactor procurement has shifted toward premium specifications as EPA Tier 4 Final and EU Stage V compliance costs compress equipment lifecycles in mature markets. This quality migration favors manufacturers with integrated emission engineering and long-term service contract capabilities.
For Market Incumbents: Cement aftermarket revenue streams through predictive maintenance platform deployment and direct parts procurement agreements that bypass traditional dealer markups. Capacity additions in Southeast Asia threaten margin structures for standard-configuration exports; backward integration into compaction drum fabrication preserves engineering differentiation against Chinese volume competitors.
For New Entrants and Emerging Players: Enter via enclosed transfer station electric configurations in EU urban corridors where Stage V zero-emission mandates create protected pilot deployment windows. Battery thermal management specialization offers the most penetrable technical wedge against established diesel-centric service networks. Partner with municipal energy utilities for charging infrastructure co-development to defray grid upgrade capital requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among state-affiliated Chinese fabricators facing margin compression from steel cost volatility and export financing constraints. Long-term viability hinges on electrification platform development and telematics integration capabilities rather than production scale alone. Monitor battery energy density announcements against continuous-duty landfill face operation requirements as the inflection signal for electric adoption pacing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Remote machine monitoring extends equipment uptime for distributed landfill operations. |
| Electric Powertrain Development | Battery-electric configurations satisfy EU Stage V mandates at urban-adjacent transfer stations. |
| Aftermarket Service Contract Expansion | Long-term parts agreements generate recurring revenue as municipal fleets age. |
| Compaction Drum Optimization | Specialized designs maximize density per pass and extend landfill cell operational life. |
| Geographic Distributor Acquisition | Network control in Southeast Asia and Latin America secures emerging market procurement flows. |
Research Methodology
Direct dialogue with landfill operations managers, fleet procurement directors, OEM aftermarket service heads, and EPA compliance officers grounded qualitative findings in operational reality. Secondary validation drew from EPA emission certification databases, EU Stage V type-approval records, MIIT equipment registry filings, and customs trade flow data for heavy compaction equipment. Bottom-up equipment unit economics and top-down waste infrastructure investment flows were triangulated against regional regulatory implementation timelines.
Bottom-up modeling of unit shipments by powertrain configuration, drum architecture, and emission compliance tier anchored volume projections across the analysis window. Segmentation dimensions included fuel type, technology sophistication, end-user procurement authority, and regional regulatory framework maturity. CAGRs were derived from equipment replacement cycle compression under Tier 4 Final and Stage V mandates, cross-referenced against municipal solid waste volume growth trajectories and state-backed environmental remediation program budgets.
Inputs from EPA certification registries and EU type-approval databases were available through the study window; gaps in electric configuration pilot deployment data introduce uncertainty bands around electrification adoption pacing. Forecasts reflect documented assumptions regarding battery energy density improvement curves and charging infrastructure deployment schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market