
 Middle East and Africa Solar Panel Recycling Market | 2026-2036
Middle East and Africa Solar Panel Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Solar Panel Recycling Market Foresight
Modular decommissioning packages bundled with new installation contracts is rebalancing procurement economics for solar asset operators. First Solar Inc. anchors its regional footprint through integrated recycling commitments tied to thin-film deployment. Canadian Solar Inc. leverages established collection partnerships across North African markets. Interco Trading Inc. competes on metal recovery yields from crystalline silicon frames and junction boxes.
Middle East and Africa solar panel recycling encompasses the recovery of semiconductor-grade silicon, silver metallization layers, tempered glass, and aluminum framing from photovoltaic modules that have reached end-of-service. Mechanical shredding followed by thermal delamination separates encapsulant polymers from recoverable substrates at temperatures exceeding 500 degrees Celsius. Processing services command margin premiums where hydrometallurgical routes extract high-purity silver and copper with minimal emissions. Glass recovery dominates volume throughput across the service mix while silicon purification through pyrometallurgical refining represents the fastest-expanding technology category.
Saudi Arabia's SASO technical regulations for electronic waste classification, South Africa's DEFF extended producer responsibility directives, and the UAE's MOCCAE circular economy policies collectively shape collection obligations and material recovery targets. These frameworks establish landfill diversion mandates that directly determine facility permitting and operational compliance costs. Stakeholders must track how evolving certification requirements for recovered silicon purity will reshape processing technology investments and offtake agreements with regional ingot manufacturers.
Market Dynamics
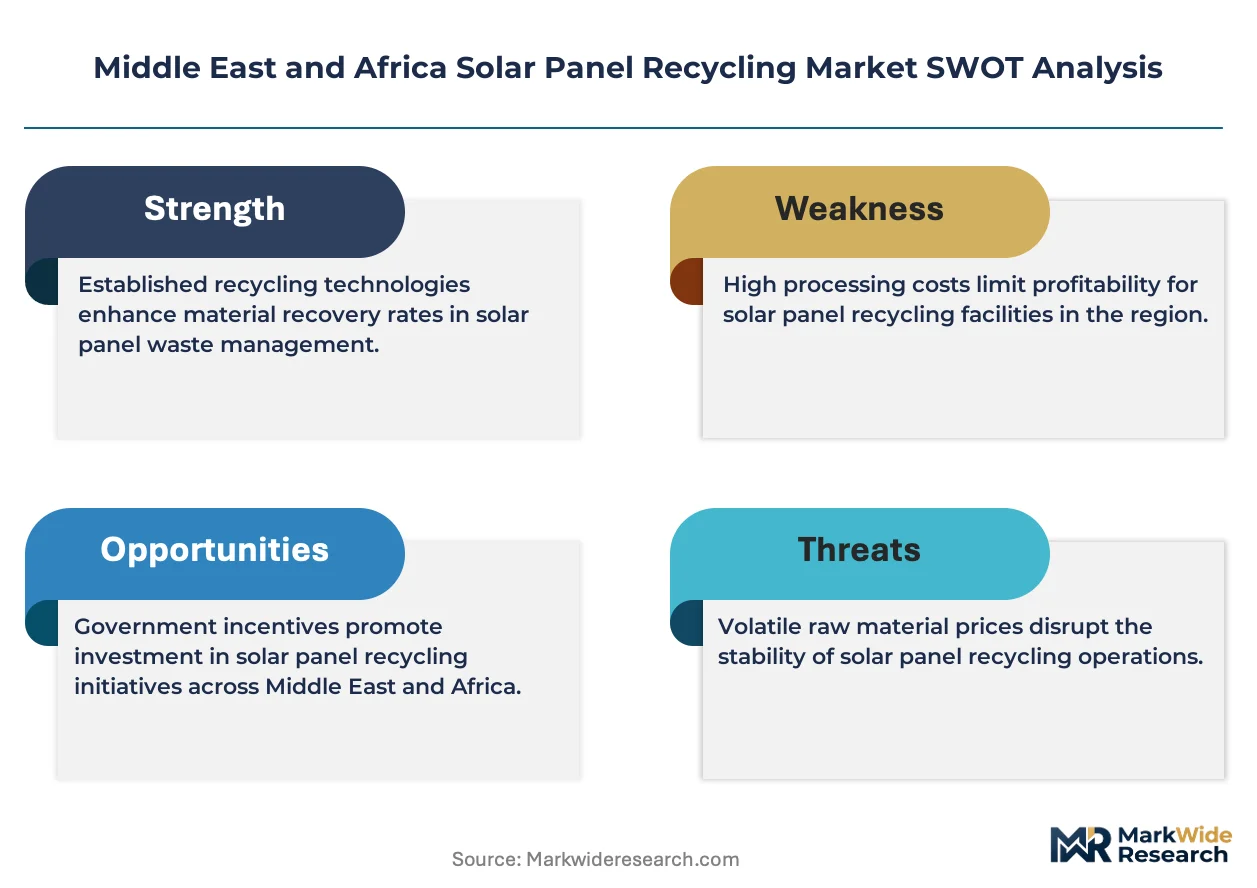
The Middle East and Africa Solar Panel Recycling Market is being fundamentally reshaped by the convergence of early photovoltaic installation decommissioning waves and tightening landfill diversion mandates across Gulf Cooperation Council member states. Utility-scale operators now face simultaneous pressure to recover semiconductor-grade materials while complying with emerging extended producer responsibility frameworks.
Growth Catalysts
- Saudi Arabia's SASO electronic waste classification:Technical regulations mandate material recovery targets for end-of-life photovoltaic modules, creating immediate collection obligations for gigawatt-scale solar corridor operators.
- Silver metallization recovery:Hydrometallurgical extraction routes for high-purity silver and copper command margin premiums where emissions constraints limit thermal processing alternatives.
- South Africa's DEFF directives:Extended producer responsibility mandates assign waste stream accountability to original equipment manufacturers, accelerating formal collection network development.
Market Restraints
- Pyrometallurgical refining capex intensity:Silicon purification facilities require substantial furnace investments that strain mid-scale processor balance sheets.
- Encapsulant polymer separation:Thermal delamination at temperatures exceeding 500 degrees Celsius consumes energy inputs vulnerable to regional electricity price volatility.
- Collection infrastructure fragmentation:Sparse reverse logistics networks across North African markets concentrate feedstock access in coastal urban corridors.
Strategic Opportunities
- UAE circular economy policies:MOCCAE frameworks incentivize integrated recycling commitments bundled with new thin-film deployment contracts.
- Aluminum framing recovery:Crystalline silicon module dismantling yields high-grade aluminum streams for regional secondary metal markets.
- Glass recovery volume scaling:Tempered glass dominates processing throughput and offers immediate offtake pathways to construction materials suppliers.
Industry Challenges
- Certification timeline compression:Evolving purity standards for recovered silicon ingots demand continuous laboratory validation that extends facility commissioning schedules.
- Mechanical shredding integration:Pre-processing equipment must handle variable module architectures from legacy installations without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Solar Panel Recycling Market |
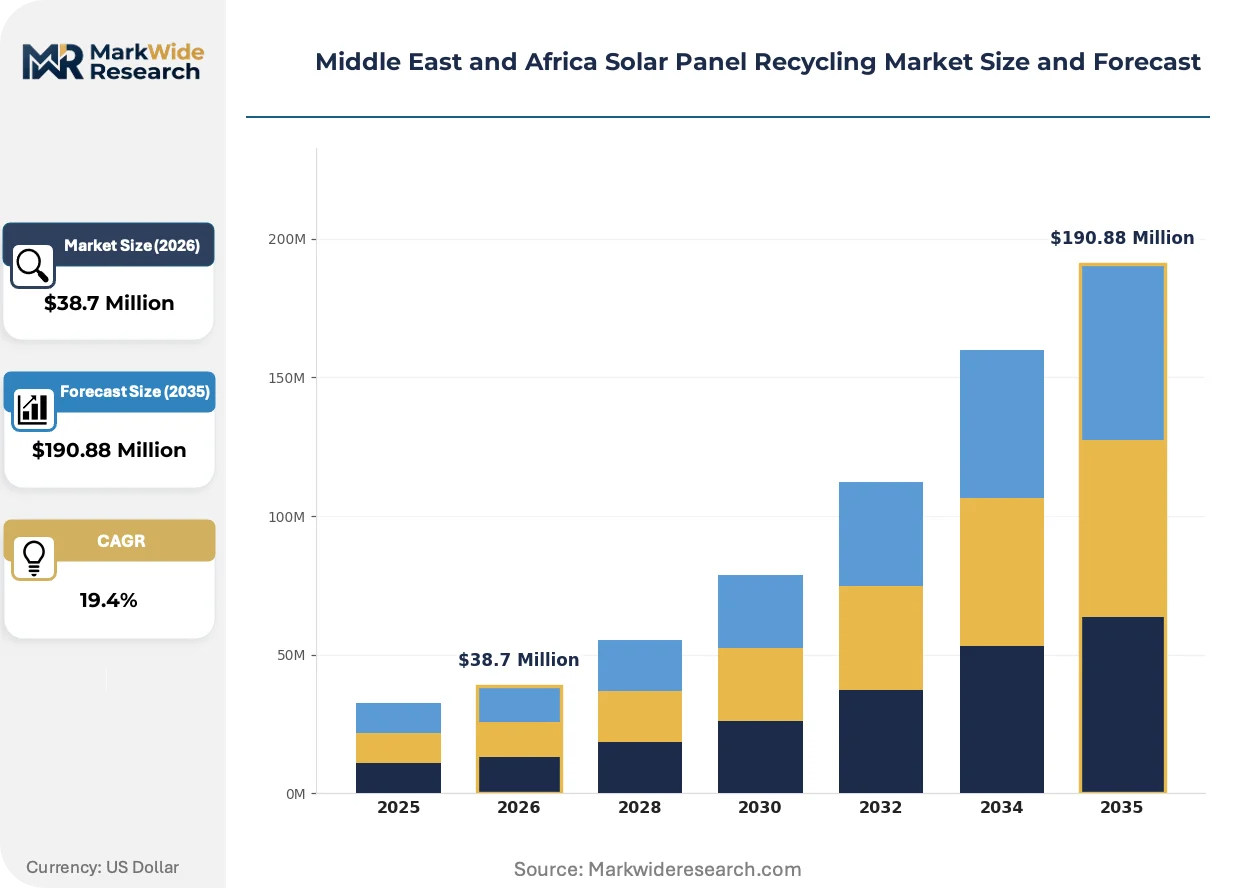
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Transportation, Processing, Reuse Material Type: Silicon, Glass, Metals, Plastics End User: Manufacturers, Distributors, Contractors, Retailers Technology: Mechanical, Hydrometallurgical, Pyrometallurgical, Biotech |
| Companies Covered | First Solar Inc., Canadian Solar Inc., SunPower Corporation, Trina Solar Ltd, Interco Trading Inc., Rinovasol GMBH, Sharp Corporation, Aurubis AG, Recycle PV Solar, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Solar Panel Recycling Market Shifts & Advancements
Processing technology evolution is compressing recovery economics while regulatory harmonization across Gulf states creates new compliance benchmarks for material traceability. These forces are reconfiguring how operators structure decommissioning service offerings.
Pyrometallurgical silicon purification is expanding into utility-scale operator procurement specifications as the technology enables direct ingot manufacturing feedstock supply. Saudi gigawatt-scale corridor developers now require recovery partners to demonstrate semiconductor-grade output capability. This technical threshold is expanding into contract terms that disqualify mechanical-only processors from large asset portfolios.
South Africa's DEFF extended producer responsibility directives are mandating landfill diversion minimums that reshape facility permitting economics. Photovoltaic waste stream accountability now falls on original equipment manufacturers rather than downstream asset owners. Large-scale solar farm operators in the Northern Cape and Western Cape provinces are responding by pre-negotiating recycling clauses in twenty-year power purchase agreements.
Modular decommissioning packages are displacing standalone end-of-life service procurement across North African markets. Engineering-procurement-construction firms now bundle recovery obligations with new installation contracts to lock in long-term material access. This contractual consolidation is most visible in Morocco's Noor Ouarzazate complex and Egypt's Benban solar park where integrated service providers capture multi-decade revenue streams.
Middle East and Africa Solar Panel Recycling Market Segmentation
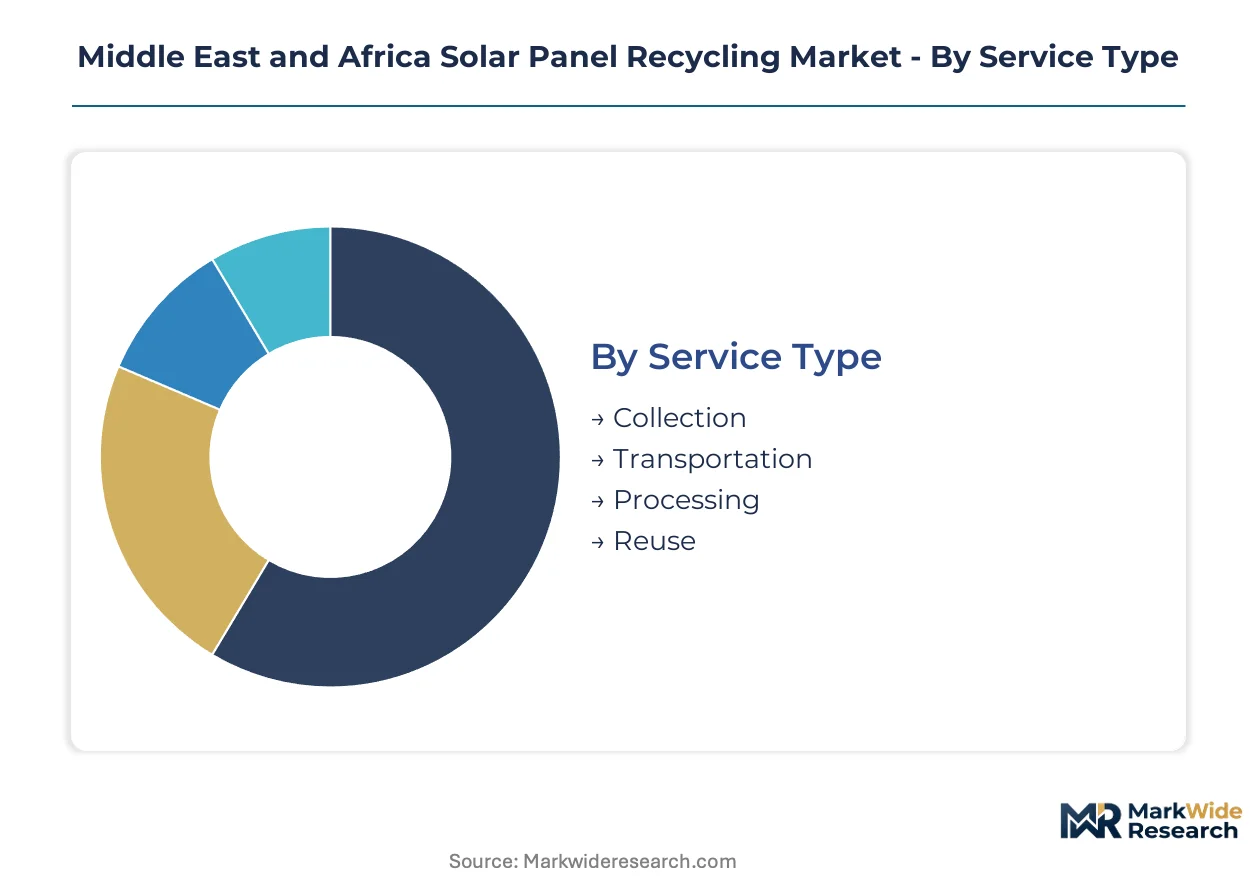
Segmentation in solar panel recycling reveals how value migrates across the service chain. Material purity thresholds and processing technology choices determine margin capture for operators serving Saudi gigawatt-scale corridors and South African utility portfolios.
Service Type:
Volume-heavy collection and transportation services contrast with premium-margin processing and reuse operations.
- Collection:Reverse logistics networks concentrate around Saudi Arabia's solar corridors and South Africa's Northern Cape installations. DEFF extended producer responsibility mandates are accelerating formal collection infrastructure buildout.
- Transportation:Specialized flatbed and containerized handling moves modules from decommissioning sites to centralized facilities. Sparse North African road networks limit feedstock access to coastal urban corridors.
- Processing:Mechanical shredding and thermal delamination command margin premiums where hydrometallurgical silver recovery is specified.
- Reuse:Secondary market refurbishment for functional panels serves off-grid applications across sub-Saharan markets.
Today's leader: Processing. Tomorrow's challenger: Reuse.
Material Type:
Glass dominates throughput tonnage while silicon and metals concentrate value recovery.
- Silicon:Semiconductor-grade purification through pyrometallurgical refining requires furnace investments exceeding mid-scale processor capacity. Saudi gigawatt-scale developers now specify ingot-manufacturing feedstock capability in procurement terms.
- Glass:Tempered glass recovery yields immediate offtake pathways to construction materials suppliers across Gulf Cooperation Council markets. Volume scaling advantages favor processors with adjacent glass beneficiation partnerships.
- Metals:Aluminum framing and silver metallization layers attract metal traders targeting regional secondary markets.
- Plastics:Encapsulant polymer separation at temperatures exceeding 500 degrees Celsius consumes energy inputs vulnerable to regional electricity price volatility.
Silicon purification is climbing the fastest as purity certification requirements reshape technology investments.
End User:
Asset ownership patterns determine who bears extended producer responsibility compliance costs.
- Manufacturers:Original equipment manufacturers face DEFF accountability for South African photovoltaic waste streams. First Solar anchors regional presence through integrated recycling commitments tied to thin-film deployment.
- Distributors:Collection network operators leverage established partnerships across North African markets to secure feedstock access.
- Contractors:Engineering-procurement-construction firms bundle decommissioning obligations with new installation contracts in Morocco's Noor Ouarzazate complex and Egypt's Benban solar park.
- Retailers:Distributed solar installers generate fragmented end-of-life volumes requiring aggregation before processor handoff.
Contractors currently capture multi-decade revenue streams through bundled service structures.
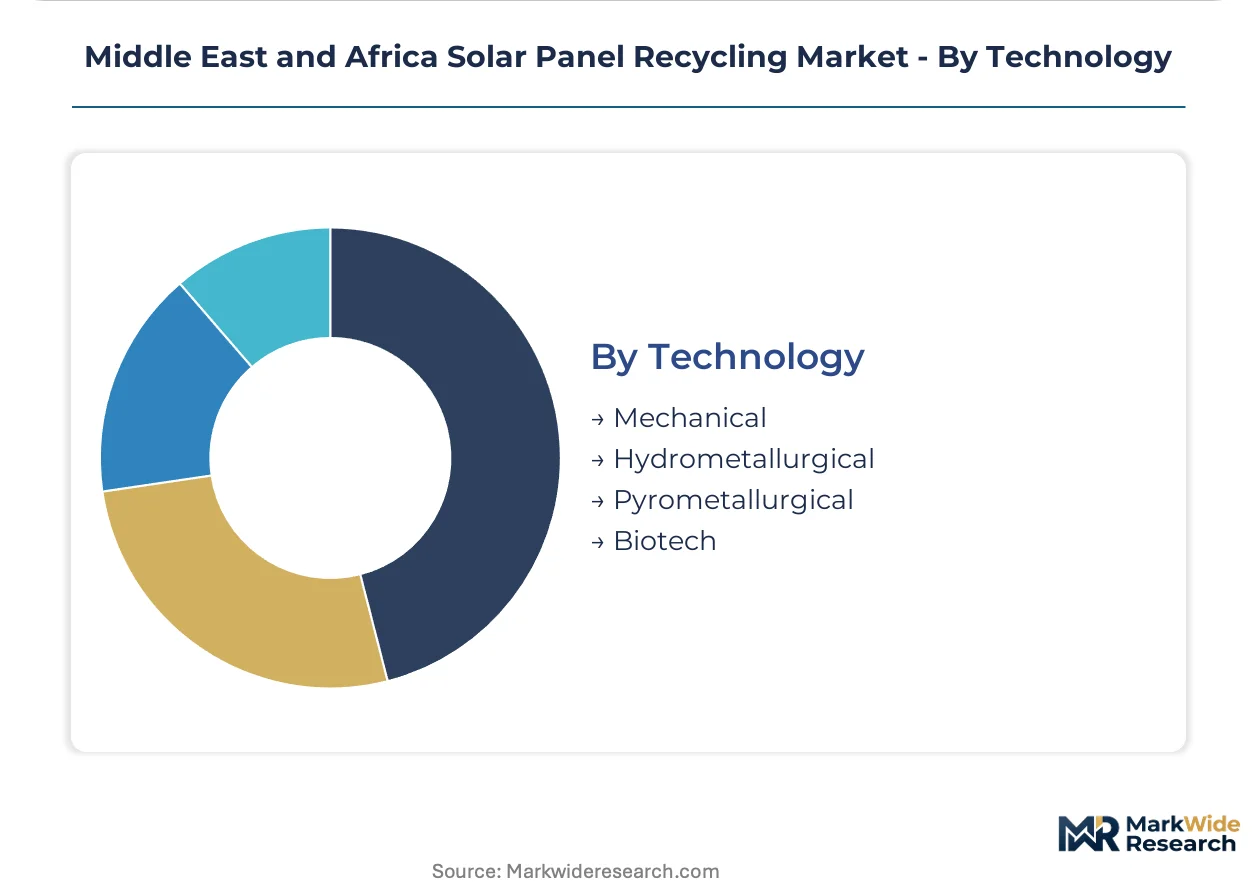
Technology:
Thermal and chemical routes are displacing mechanical-only approaches as purity requirements tighten.
- Mechanical:Shredding and sorting equipment handles variable module architectures from legacy installations. Pre-processing throughput degrades where encapsulant adhesion varies across manufacturer generations.
- Hydrometallurgical:Acid-based extraction routes recover high-purity silver and copper with minimal emissions. SASO technical regulations favor these methods where thermal alternatives face air quality constraints.
- Pyrometallurgical:Furnace-based silicon purification is expanding into utility-scale procurement specifications. Continuous laboratory validation demands extend facility commissioning schedules.
- Biotech:Microbial leaching approaches remain pre-commercial across Middle East and Africa processing facilities.
Pyrometallurgical routes are gaining share fastest as semiconductor-grade output becomes a contract disqualifier for mechanical-only operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solar panel recycling first scaled commercially in Europe's early photovoltaic markets, with Middle East and Africa operators now adapting those technical frameworks to desert climates and utility-scale deployment patterns. Regional facility planning concentrates where early installations approach end-of-service and landfill diversion mandates take effect.
Saudi Arabia
Gigawatt-scale solar corridor operators in the Eastern Province and Riyadh region generate concentrated end-of-life volumes from 2010s installations. SASO technical regulations for electronic waste classification mandate material recovery targets that reshape procurement economics. The Sudair and Al-Faisaliah solar clusters anchor feedstock access for processors seeking long-term supply agreements.
United Arab Emirates
Utility-scale portfolios in Dubai and Abu Dhabi approach decommissioning timelines that trigger recycling clause negotiations. MOCCAE circular economy policies incentivize integrated recovery commitments bundled with new project development. Jebel Ali industrial zone concentrates processing infrastructure adjacent to port logistics for secondary material export.
South Africa
Northern Cape and Western Cape solar farms face extended producer responsibility obligations under DEFF directives that assign waste accountability to original equipment manufacturers. The country's national waste management strategy mandates landfill diversion minimums that determine facility permitting economics. Port Elizabeth-Gqeberha corridor development targets coastal logistics advantages for material aggregation.
Egypt
Benban solar park operators negotiate recycling clauses in twenty-year power purchase agreements that lock in end-of-life service providers. Centralized utility-scale deployment creates feedstock density rare across North African markets. Aswan governorate infrastructure development targets integration with Red Sea port networks for secondary material offtake.
Morocco
Noor Ouarzazate complex engineering-procurement-construction firms bundle decommissioning obligations with new installation contracts to capture multi-decade revenue streams. National renewable energy agency frameworks shape collection network development timelines. Ouarzazate-Tafilalet region concentrates both operational capacity and planned recycling infrastructure.
Middle East and Africa Solar Panel Recycling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and purity certification capability. The vendor base stratifies between integrated thin-film manufacturers with captive recycling commitments and independent processors competing on metal recovery yields. Three archetypes dominate: technology-integrated OEMs with bundled service offerings, independent metal traders specializing in aluminum and silver streams, and engineering firms packaging decommissioning with construction contracts. Competitive moves concentrate on strategic partnerships for feedstock access and pyrometallurgical capacity expansion for silicon purification.
Within the technology-integrated tier, First Solar Inc. and Canadian Solar Inc. exemplify archetypes where manufacturing origin shapes recycling service bundling. First Solar anchors regional presence through thin-film deployment commitments that integrate end-of-life recovery. Canadian Solar leverages established collection partnerships across North African markets. Interco Trading Inc. occupies a distinct position as a metal recovery specialist competing on yields from crystalline silicon frames and junction boxes.
| Leading Market Players |
|---|
| First Solar Inc. |
| Canadian Solar Inc. |
| SunPower Corporation |
| Trina Solar Ltd |
| Interco Trading Inc. |
| Rinovasol GMBH |
| Sharp Corporation |
| Aurubis AG |
| Recycle PV Solar |
| Others |
Supply & Pricing Matrix
Sovereign-backed solar developers across Saudi Arabia and the UAE anchor procurement decisions, compressing supplier margins through bundled long-term service contracts while concentrating feedstock access within state-controlled solar corridors. This ownership pattern tightens pricing discipline for independent processors competing against integrated OEM recycling commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Middle East and Africa solar panel recycling market. Premium tiers capture semiconductor-grade silicon purification contracts for Saudi gigawatt-scale developers, while standard tiers handle mechanical shredding and glass recovery, and economy tiers aggregate fragmented residential volumes. Price differentiation hinges on purity certification thresholds and volume scale commitments. Cost compression in standard-tier processing is intensifying because energy-intensive thermal delamination faces regional electricity price volatility. Utility-scale operators show least price sensitivity given regulatory compliance mandates, whereas distributed solar installers demonstrate highest sensitivity due to thin margins on end-of-life aggregation.
Supply Chain Analysis
Reverse logistics for end-of-life photovoltaic modules flows through specialized flatbed networks from decommissioning sites to centralized facilities, with refurbishment streams diverting functional panels to sub-Saharan off-grid markets. Feedstock concentration centers on Saudi Arabia, South Africa, and the UAE where early utility-scale installations approach end-of-service. The supply chain draws from aluminum framing, silver metallization, and tempered glass inputs, with silicon purification capacity representing the critical bottleneck. Single-source vulnerability runs through pyrometallurgical furnace supply constrained by European and Asian equipment manufacturers. Distribution runs through engineering-procurement-construction firms bundling recovery obligations with new installation contracts across North African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa solar panel recycling market functions as a regulatory compounder where landfill diversion mandates and extended producer responsibility frameworks generate structurally recurring demand. South Africa's DEFF directives assigning waste accountability to original equipment manufacturers exemplify the enforcement milestones reshaping procurement economics.
For Market Incumbents: Anticipate margin compression from integrated thin-film manufacturers bundling recycling with deployment contracts by securing pyrometallurgical certification ahead of evolving silicon purity standards. Defensive consolidation through backward integration into collection networks across Saudi solar corridors locks in feedstock access against emerging metal-trading competitors. Capacity expansion in Jebel Ali and Port Elizabeth-Gqeberha corridors captures logistics advantages as coastal aggregation points. For New Entrants and Emerging Players: Launch via modular decommissioning packages bundled with engineering-procurement-construction contracts in Egypt's Benban solar park and Morocco's Noor Ouarzazate complex where incumbent coverage remains thin. White-space targets concentrate in secondary market refurbishment for functional panels serving off-grid applications across sub-Saharan Africa, and in hydrometallurgical silver recovery where SASO air quality constraints disadvantage thermal processors. The most penetrable segment is North African collection infrastructure where sparse reverse logistics networks fragment feedstock access. For Investors and Strategic Acquirers: Integrated solar developers with captive recycling commitments are the most active acquirer in this space, seeking technology-enabled purification capabilities to satisfy procurement specifications. Long-term viability favors processors with demonstrated semiconductor-grade silicon output and validated offtake agreements with regional ingot manufacturers. Acquisition target archetypes include independent metal recovery specialists with established aluminum and silver yields, and mid-scale processors holding coastal logistics positions. The signal to watch is SASO certification timeline compression for recovered silicon purity, which will disqualify mechanical-only operators from large asset portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrometallurgical Capacity Buildout | Semiconductor-grade silicon purification satisfies Saudi gigawatt-scale procurement specifications. |
| Reverse Logistics Network Expansion | Collection infrastructure in Northern Cape and Western Cape provinces secures South African feedstock under DEFF mandates. |
| Hydrometallurgical Technology Licensing | Acid-based silver extraction routes meet SASO air quality constraints in Saudi solar corridors. |
| Integrated Recycling Commitments | Bundled end-of-life services with new thin-film deployment capture multi-decade revenue streams. |
| Glass Beneficiation Partnerships | Adjacent construction materials offtake pathways monetize tempered glass volume dominance. |
Research Methodology
Bottom-up utility-scale and distributed solar modeling reconciled against top-down processing capacity and regulatory tracking forms the analytical core of this study. Primary interviews with solar asset operators, waste management facility managers, EPC contractors, and original equipment manufacturer sustainability officers combined with secondary validation from SASO technical regulations, South Africa DEFF directive filings, UAE MOCCAE circular economy policy documents, and customs data on secondary materials trade. Top-down supply-side assessment triangulates against bottom-up demand projections from decommissioning timelines across Saudi gigawatt-scale corridors and South African utility portfolios.
Historical trendline analysis of photovoltaic installation vintages and end-of-life service procurement patterns informs the projection framework. Segmentation modeling spans service type, material recovery category, end-user accountability structure, and processing technology route across the analysis window. CAGRs derive from fitted growth curves applied to regulatory enforcement timelines and capacity expansion announcements. Industry-specific forecast inputs include pyrometallurgical furnace commissioning schedules and evolving certification requirements for recovered silicon purity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory enforcement delays or feedstock aggregation failures in fragmented North African markets. Practitioners should monitor SASO certification standard revisions and DEFF penalty implementation intensity for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
Smart Waste Management Market