
 APAC E-Waste Management Market | 2026-2036
APAC E-Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
APAC E-Waste Management Market Insights
China's informal recycler consolidation is hardening into formal licensing requirements under MEE oversight. Veolia Group leverages its integrated hazardous waste platform to anchor collection networks across Southeast Asian industrial zones. Sims Recycling Solutions competes through proprietary shredding and sorting technology at scale in Australia and Singapore. TES-AMM specializes in secure data destruction alongside precious metal recovery, differentiating its service portfolio for enterprise clients.
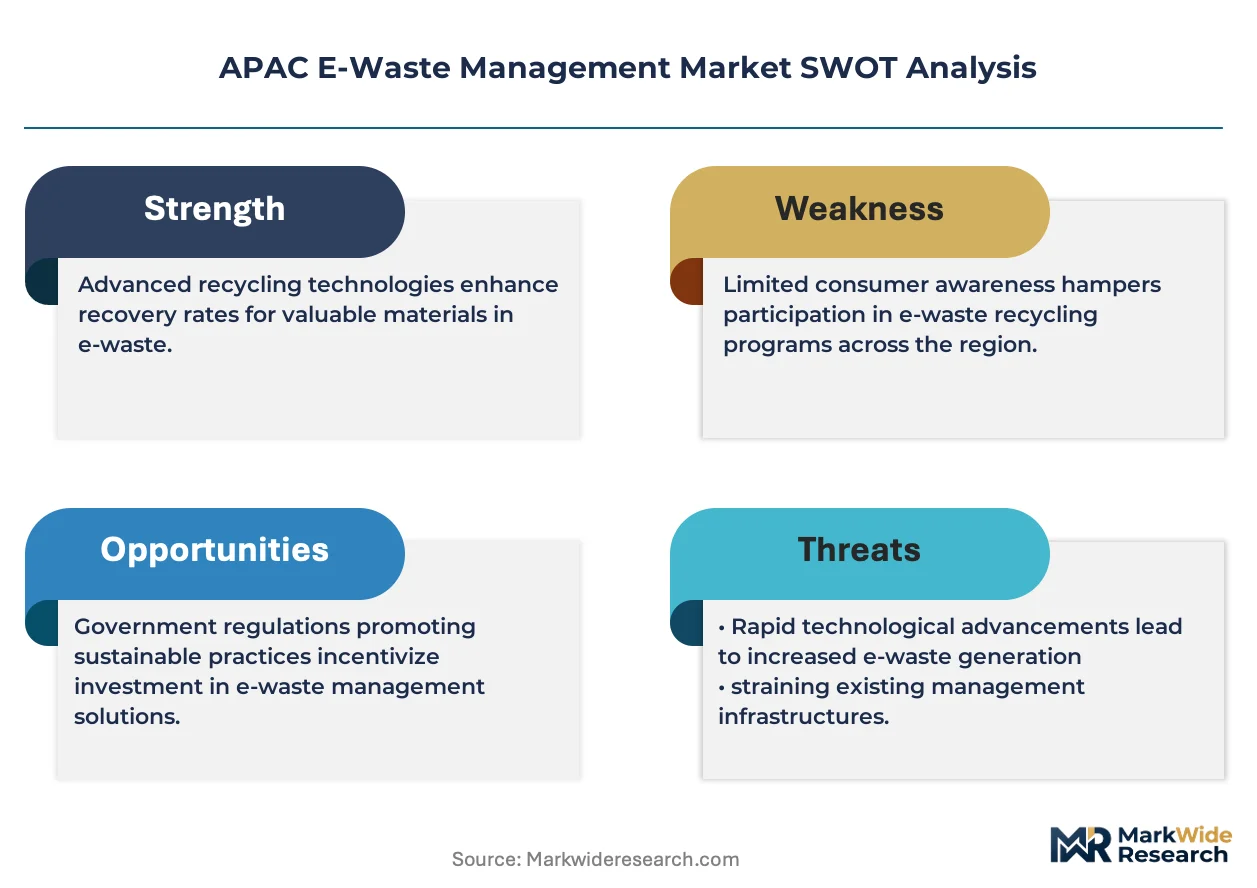
E-waste management encompasses the systematic collection, transportation, processing, and disposal of discarded electrical and electronic equipment containing recoverable metals, rare earth elements, and hazardous substances such as lead, mercury, and cadmium. The practice employs mechanical shredding, hydrometallurgical extraction, and pyrometallurgical refining to isolate valuable fractions while neutralizing toxic components for environmental protection. Metal recovery from circuit boards and cathode ray tubes commands premium processing margins due to concentrated gold, palladium, and copper content. Drop-off centers and retail take-back programs are expanding fastest as consumer-facing channels, though curbside collection still dominates volume throughput in mature municipal systems. Refurbishment activity is accelerating as secondary device markets lengthen product lifecycles and defer material extraction costs.
China's MEE enforces GB standards for e-waste treatment facility licensing and pollutant discharge limits, while India's CPCB administers E-Waste Management Rules mandating producer responsibility organization participation. Japan's METI operates the Home Appliance Recycling Ticket system, creating transparent cost allocation between manufacturers and consumers. Stakeholders must monitor evolving extended producer responsibility enforcement intensity and informal sector formalization timelines across the region's fragmented regulatory landscape.
Market Dynamics
Extended producer responsibility mandates across South Korea and Japan are forcing original equipment manufacturers to internalize end-of-life collection costs, compressing margins for informal recyclers and accelerating facility consolidation around licensed treatment centers.
Growth Catalysts
- Channelized collection mandates:India's E-Waste Management Rules require documented cradle-to-grave tracking, creating compliance pull for formal dismantlers and certified recyclers.
- Take-back obligation expansion:South Korean consumer electronics producers face tightening EPR frameworks that obligate retail-level product return infrastructure.
- Metal recovery economics:Hydrometallurgical extraction of gold and palladium from printed circuit boards generates processing premiums that subsidize hazardous waste neutralization costs.
Market Restraints
- Feedstock supply fragmentation:Informal collectors across Indonesia and Vietnam control 60-70% of recoverable volume, creating procurement bottlenecks for licensed operators.
- Capital intensity barriers:Pyrometallurgical smelting equipment for cathode ray tube glass processing requires eight-figure USD outlays that deter mid-scale entrants.
- Cross-border movement restrictions:Basel Convention amendments on transboundary hazardous waste shipments complicate regional feedstock arbitrage for Singapore-based processors.
Strategic Opportunities
- Enterprise data destruction bundling:Secure IT asset disposition services for financial services and healthcare verticals command 40-60% premiums over commodity metal recovery.
- Refurbishment channel development:Secondary device markets in Southeast Asia extend product lifecycles and defer material extraction costs for smartphone and laptop categories.
- Industrial zone clustering:China's Guangdong province offers co-located hazardous waste treatment permits that reduce logistics costs for multi-feedstock facilities.
Industry Challenges
- Skilled technician scarcity:Certified dismantling of lithium-ion battery packs requires specialized training programs that outpace vocational education capacity in India and Vietnam.
- Permitting timeline compression:China's MEE licensing reviews for new e-waste treatment facilities extend 18-24 months, delaying capacity expansion against tightening compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC E-Waste Management Market |
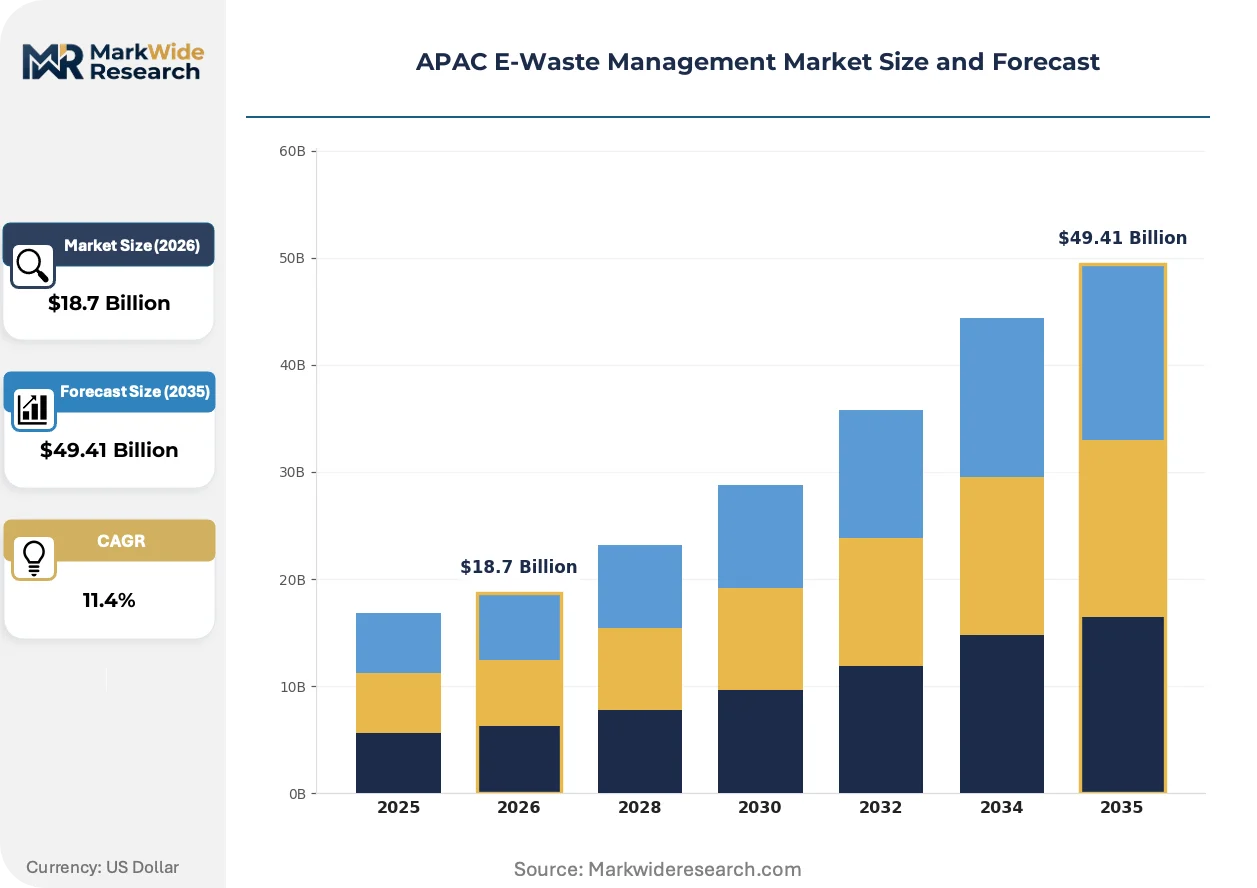
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Curbside Collection, Drop-off Centers, Retail Take-back, Events Processing Type: Recycle, Refurbish, Disassembly, Landfill Material Type: Metals, Plastics, Glass, Circuit Boards End User: Households, Businesses, Government, NGOs |
| Companies Covered | Veolia Group, Remondis, Averda, Sims Recycling Solutions, TES-AMM, Enviro-Hub Holdings Ltd, Capital Environment Holdings Limited, Sembcorp Industries, Attero, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC E-Waste Management Market Trends and Innovations
Mechanical preprocessing and automated sorting systems are displacing manual dismantling workflows, while regulatory enforcement intensifies around documented chain-of-custody requirements.
Sensor-based sorting technology using near-infrared and X-ray fluorescence detection is consolidating downstream processing economics. Large-scale recyclers in Australia and Singapore deploy these systems to achieve 95%+ purity in mixed plastic and metal fractions. The capital efficiency gains are compressing viable scale thresholds and marginalizing manual-sorting operations.
Japan's METI Home Appliance Recycling Ticket system creates transparent cost allocation between manufacturers and consumers. The framework mandates itemized recycling fees at point-of-sale, eliminating free-rider problems in collection infrastructure financing. White goods and consumer electronics categories face the strictest compliance timelines under this mechanism.
Retail take-back programs are displacing municipal drop-off centers as the dominant consumer-facing channel. Electronics retailers in South Korea and Taiwan now bundle collection obligations with new product sales, capturing end-of-life devices at the point of replacement. This shift is most visible in urban corridors where convenience-driven disposal patterns dominate household behavior.
APAC E-Waste Management Market Segmentation
E-waste management in APAC segments across collection logistics, processing economics, material recovery value, and stakeholder compliance obligations. Each dimension carries distinct certification burdens and margin profiles that shape competitive positioning across the region's fragmented regulatory landscape.
Collection Method:
Certification requirements diverge sharply across channels, with retail take-back programs facing the strictest EPR documentation mandates under South Korea's and Japan's frameworks, while curbside collection operates under municipal waste permits with lighter chain-of-custody obligations.
- Curbside Collection:Municipal trucks aggregate mixed household e-waste alongside general refuse, requiring MEE-licensed transfer stations in China to separate hazardous fractions before downstream processing. Volume concentrates in Shanghai and Beijing where residential density supports route economics, though contamination rates from co-mingling compress material recovery yields.
- Drop-off Centers:Dedicated facilities with on-site weighing and hazard identification capabilities command higher tipping fees from licensed dismantlers. India's CPCB mandates GPS-tracked transport from these nodes to registered recyclers, creating compliance pull for formal channel participants in Delhi and Mumbai corridors.
- Retail Take-back:South Korean electronics retailers face METI-style EPR obligations requiring point-of-sale collection infrastructure with itemized tracking.
- Events:Periodic community drives generate seasonal feedstock spikes without permanent overhead, common across Southeast Asian urban clusters.
Curbside Collection sits at the top of the volume ranking, with Retail Take-back climbing the fastest.
Processing Type:
Cost tier stratification separates capital-intensive pyrometallurgical operations from labor-heavy manual disassembly, with margin concentration in precious metal recovery versus thin economics in landfill diversion.
- Recycle:Mechanical shredding and hydrometallurgical extraction of gold, palladium, and copper from circuit boards generates premium margins that subsidize hazardous waste neutralization. Guangdong province hosts the region's densest cluster of licensed smelters with co-located hazardous waste permits.
- Refurbish:Secondary device markets extend smartphone and laptop lifecycles, deferring material extraction costs while capturing value from functional components. Southeast Asian demand for refurbished electronics drives processing concentration in Bangkok and Jakarta logistics hubs.
- Disassembly:Manual component separation requires skilled technician certification for lithium-ion battery handling, creating bottleneck constraints in India and Vietnam vocational pipelines.
- Landfill:Residual hazardous fractions including CRT glass and mercury-containing lamps face tightening disposal restrictions under China's GB standards and India's E-Waste Management Rules.
Recycle commands the dominant revenue share, with Refurbish expanding most quickly as secondary device channels mature.
Material Type:
Supply concentration around circuit board recovery in China's Pearl River Delta shapes regional arbitrage patterns, while glass and plastic fractions face thinner economics without premium metal content to subsidize processing.
- Metals:Ferrous and non-ferrous fractions from chassis and wiring harnesses feed established foundry networks across the region with standardized pricing benchmarks.
- Plastics:ABS and polycarbonate recovery from housings requires near-infrared sorting investment to achieve purity thresholds for recompounding, with Australian and Singaporean operators deploying sensor-based systems at scale.
- Glass:CRT funnel and panel glass separation demands specialized lead-extraction smelting capacity that has consolidated around a handful of licensed Chinese facilities.
- Circuit Boards:Concentrated gold, palladium, and copper content drives the steepest processing premiums, with hydrometallurgical extraction economics justifying eight-figure capital outlays for integrated recovery complexes.
Circuit Boards generate the highest unit margins, with Plastics gaining share fastest as automated sorting technology compresses viable scale thresholds.
End User:
Customer type determines service bundling complexity, with enterprise clients demanding secure data destruction alongside commodity recovery while household channels prioritize convenience and zero direct cost.
- Households:Convenience-driven disposal patterns dominate urban corridors, with retail take-back programs capturing replacement-cycle devices at South Korean and Taiwanese electronics retailers.
- Businesses:Financial services and healthcare verticals command 40-60% service premiums for certified IT asset disposition with documented chain-of-custody and data sanitization protocols.
- Government:Public sector procurement mandates increasingly require EPR compliance documentation and formal recycler certification for end-of-life equipment disposal.
- NGOs:Collection drives and awareness campaigns generate feedstock without commercial margin extraction, operating primarily in informal sector transition zones.
Households contribute the dominant volume base, with Businesses expanding fastest as enterprise data security requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China processes substantially higher e-waste volumes than Japan, yet both markets demonstrate tightening formalization trajectories under distinct regulatory architectures. The regional landscape spans mature EPR systems alongside emerging compliance frameworks.
China
Guangdong province hosts the densest concentration of licensed smelters processing circuit boards for gold and palladium recovery. The Ministry of Ecology and Environment enforces GB standards for treatment facility licensing with 18-24 month permitting timelines. Shenzhen and Dongguan industrial clusters anchor hydrometallurgical extraction capacity serving domestic and imported feedstock streams.
Japan
METI's Home Appliance Recycling Ticket system mandates itemized recycling fees at point-of-sale, eliminating free-rider problems in collection financing. White goods and consumer electronics face strict compliance timelines under this transparent cost allocation framework. Tokyo and Osaka metropolitan areas concentrate licensed dismantling infrastructure for refrigerator and air conditioner categories.
India
The Central Pollution Control Board administers E-Waste Management Rules requiring documented cradle-to-grave tracking and producer responsibility organization participation. Delhi and Mumbai corridors drive compliance pull for formal dismantlers as GPS-tracked transport mandates tighten. Informal sector transition zones in these metros face accelerating certification requirements.
South Korea
Consumer electronics manufacturers face expanding take-back obligations under tightening extended producer responsibility frameworks. Retail-level product return infrastructure captures end-of-life devices at replacement cycle points. Seoul Capital Area electronics retailers now bundle collection obligations with new product sales, channeling volume toward licensed processors.
Singapore
Basel Convention amendments on transboundary hazardous waste shipments complicate regional feedstock arbitrage for Singapore-based processors. The city-state's hazardous waste treatment permits attract co-located facilities serving multi-feedstock operations. Jurong Island industrial zone clustering reduces logistics costs for integrated recovery complexes handling circuit boards and lithium-ion batteries.
APAC E-Waste Management Market Competitive Landscape
European-origin environmental service groups anchor one tier; Asia-Pacific specialists hold differentiated positions in secure data destruction and regional collection networks. Market structure tilts toward consolidated licensing around hazardous waste treatment permits, with mid-scale manual dismantlers facing margin compression. Three archetypes dominate: integrated hazardous waste platforms, technology-driven mechanical processors, and secure IT asset disposition specialists. Capacity expansion through industrial zone clustering and strategic partnerships for feedstock procurement represent the dominant competitive vectors.
Within the integrated platform tier, Veolia Group exemplifies multi-service environmental infrastructure spanning collection through final treatment. Sims Recycling Solutions and TES-AMM occupy positions at the technology-intensive and secure disposition vectors respectively. These three entities represent distinct strategic postures: Veolia anchors hazardous waste integration, Sims exemplifies automated sorting scale, and TES-AMM sits within the premium enterprise service segment bundling data destruction with metal recovery.
| Leading Market Players |
|---|
| Veolia Group |
| Remondis |
| Averda |
| Sims Recycling Solutions |
| TES-AMM |
| Enviro-Hub Holdings Ltd |
| Capital Environment Holdings Limited |
| Sembcorp Industries |
| Attero |
| Others |
Pricing and Supply Chain Analysis
Enterprise financial services and healthcare verticals anchor premium pricing tiers, with certified IT asset disposition commanding substantial service premiums over commodity metal recovery. Their demand for documented chain-of-custody and secure data destruction protocols shapes a value-based pricing architecture distinct from volume-driven household channels.
Pricing Analysis
Capacity additions in China's Guangdong province are reshaping price floors for circuit board recovery as hydrometallurgical extraction scales. Three-tier pricing structure across certified secure destruction, standard licensed recycling, and informal commodity recovery reflects quality grade and certification level differentiation. Cost compression in standard recycling is intensifying because automated sorting technology marginalizes manual dismantling operations. Households exhibit highest price sensitivity, while enterprise clients prioritize compliance documentation over unit cost.
Supply Chain Analysis
MEE licensing requirements and GB standards certification gates create 18-24 month qualification timelines that constrain supplier base expansion. Feedstock concentration centers on China, Japan, and South Korea as dominant generation sources, with processing capacity drawing from printed circuit boards, lithium-ion battery packs, and cathode ray tube glass. Single-source vulnerability persists around Guangdong's smelter cluster for precious metal recovery. Distribution runs through licensed dismantlers to formal treatment facilities with GPS-tracked transport mandates under India's CPCB framework.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where tightening EPR enforcement across South Korea and Japan shifts procurement toward certified processors with documented environmental compliance.
For Market Incumbents: Cement collection network density through retail take-back partnerships in Seoul and Taipei corridors, insulating against informal sector price competition. Deepen backward integration into hazardous waste treatment permits on Jurong Island and in Guangdong industrial zones, capturing margin from co-located multi-feedstock operations. Accelerate sensor-based sorting deployment to compress viable scale thresholds below mid-tier manual dismantler break-even. For New Entrants and Emerging Players: Enter via enterprise data destruction bundling for financial services verticals in Singapore and Sydney, where security premiums subsidize facility economics. Target India's Delhi-Mumbai corridor where GPS-tracked transport mandates create compliance pull for formal channel participants. Pursue refurbishment channel development in Bangkok and Jakarta secondary device markets as the most penetrable white-space. For Investors and Strategic Acquirers: Integrated hazardous waste platforms are the most active acquirer in this space, consolidating licensed treatment capacity around multi-service environmental infrastructure. Long-term viability favors targets with co-located permits and established retailer collection partnerships. Watch for MEE licensing timeline compression as inflection indicator for capacity-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Industrial Zone Clustering | Co-located hazardous waste permits in Guangdong reduce logistics costs for multi-feedstock facilities. |
| Automated Sorting Scale-Up | Near-infrared and X-ray fluorescence deployment achieves 95%+ purity thresholds in Australian operations. |
| Retail Take-Back Partnership | South Korean electronics retailers bundle collection obligations with new product sales under EPR frameworks. |
| Secure Data Destruction Certification | Documented chain-of-custody protocols command 40-60% service premiums from financial services clients. |
| Refurbishment Channel Development | Bangkok and Jakarta logistics hubs extend smartphone lifecycles in Southeast Asian secondary markets. |
Research Methodology
Bottom-up enterprise and household modeling reconciled against top-down licensed facility capacity tracking forms the analytical core. Primary interviews with e-waste treatment plant managers, OEM sustainability officers, CPCB compliance leads, and retailer logistics heads combined with secondary validation from MEE GB standard filings, Basel Convention transboundary shipment records, and METI recycling ticket system disclosures. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrices map collection volume flows through processing type to material recovery value across the projection horizon. Segmentation dimensions span collection method, processing economics, material category, and end-user compliance obligations. CAGRs derive from facility throughput expansion rates against EPR enforcement intensity curves. Forecast inputs include informal sector formalization timelines and precious metal spot price correlation effects on processing margins.
Inputs from MEE licensing databases and METI recycling fee disclosures were available through the study window; gaps in informal sector volume estimates introduce uncertainty bands around feedstock supply projections. Forecasts reflect documented assumptions on EPR enforcement acceleration and technology substitution rates for automated sorting. A model refresh is warranted upon material change in China's MEE permitting timeline or Basel Convention amendment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Aluminum Cans Recycling Market