
 Solar Metal Roof Market | 2026-2036
Solar Metal Roof Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Metal Roof Market Analytics
Multi-source procurement for mounting hardware and racking systems is restructuring supply relationships across the solar metal roof value chain. Unirac Inc. leverages its domestic manufacturing footprint to serve North American utility-scale contractors with rapid fulfillment capabilities. S-5! anchors the attachment-system tier through its specialized clamp technology for standing-seam metal profiles. Schletter Group competes on engineering depth, offering project-specific structural calculations that differentiate its European-origin product lines.
A solar metal roof combines photovoltaic energy generation with structural metal roofing substrates, typically employing aluminum or steel standing-seam panels with integrated crystalline silicon cells rated for wind uplift pressures exceeding standard asphalt shingle assemblies. The primary industrial purpose is to eliminate separate mounting infrastructure while delivering weather protection and electricity generation from a single building envelope layer. PV Panels currently dominate product-type revenue, though Integrated Systems are capturing margin pools as architects specify factory-integrated cell-to-seam assemblies. Residential application growth outpaces commercial retrofit activity, driven by net-metering policy stability in key state markets and rising homeowner preference for curb-neutral solar aesthetics.
FERC interconnection standards and state-level building codes in the United States shape product certification requirements, while the EU Green Deal and CE marking directives govern material content and end-of-life recyclability for European market access. India's CEA technical standards for grid-connected rooftop systems further define inverter compatibility and earthing protocols that manufacturers must satisfy. Stakeholders should monitor evolving fire-resistance test protocols from Underwriters Laboratories and equivalent bodies, as these certification thresholds increasingly determine product eligibility for insurance-backed project financing.
Market Dynamics
Building-integrated photovoltaics are compressing installation timelines by eliminating separate racking infrastructure, forcing traditional solar installers to compete with roofing contractors for the same project envelope.
Growth Catalysts
- Net-metering policy stability:Residential buyers in California and New York are accelerating solar metal roof commitments following state-level tariff certainty. These policies protect homeowner investment returns across 20-year depreciation windows.
- Gujarat manufacturing park deployment:India's western industrial corridor is mandating solar-ready metal roofing across new facility construction. State industrial development corporations are bundling these specifications into land allotment agreements.
- CEA grid-interconnection standards:India's technical regulations for rooftop systems are standardizing inverter compatibility and earthing protocols. Manufacturers satisfying these requirements gain preferred vendor status with EPC contractors.
Market Restraints
- Aluminum alloy price volatility:Standing-seam substrate costs fluctuate with London Metal Exchange pricing. Project developers face margin compression when raw material spikes coincide with fixed-price contract periods.
- Specialized installer scarcity:Factory-integrated cell-to-seam assemblies require dual-certification in roofing and electrical trades. Training pipelines for this hybrid skill set remain underdeveloped across most construction markets.
- Asphalt shingle substitution:Conventional roofing with retrofitted solar panels retains cost advantage in price-sensitive residential segments. Builders in Texas and Florida continue specifying this combination for entry-level housing developments.
Strategic Opportunities
- CE marking recyclability mandates:The EU Green Deal's material recovery requirements are creating first-mover advantage for European manufacturers with closed-loop aluminum supply chains. These firms can certify end-of-life take-back programs that competitors lack.
- Commercial warehouse retrofit white space:United States distribution center operators face IRA tax credit deadlines that favor integrated roof replacements over panel additions. This segment shows minimal penetration relative to new construction.
- Architect specification channel:Factory-integrated systems are capturing specification authority from solar contractors. Design firms in Germany and the Netherlands are embedding solar metal roofs into envelope performance standards.
Industry Challenges
- UL fire-resistance certification timelines:Underwriters Laboratories test protocols for roof-integrated photovoltaics extend product launch cycles by 8-14 months. Manufacturers must parallel-track certification across multiple jurisdictions to maintain release schedules.
- Legacy electrical infrastructure compatibility:Grid interconnection for integrated systems requires utility-specific transformer upgrades in older commercial buildings. Project delays accumulate when local distribution operators lack capacity assessment bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Metal Roof Market |
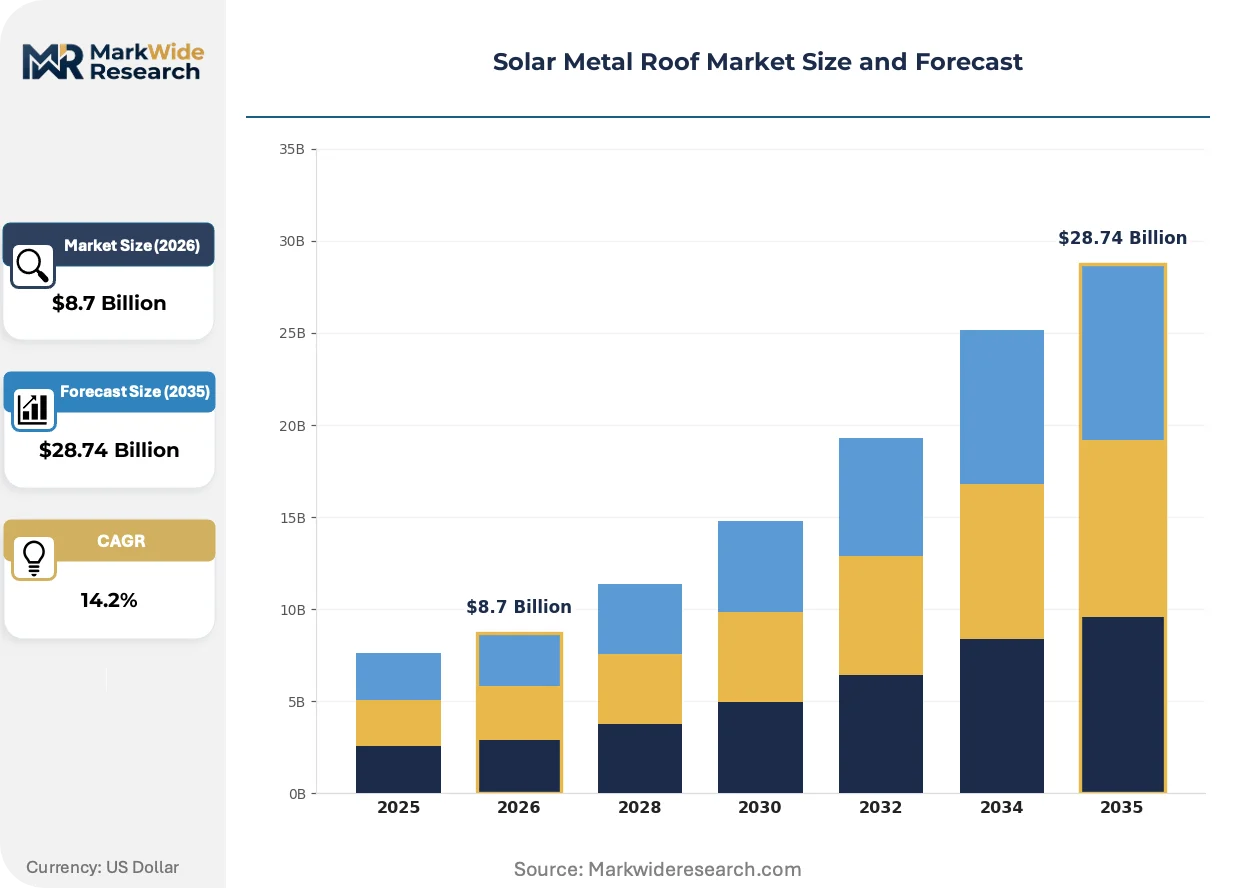
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PV Panels, Integrated Systems, Battery Storage, Mounting Solutions Application: Residential, Commercial, Industrial, Utility Scale Material: Aluminum, Steel, Zinc, Copper Installation Type: New Construction, Retrofit, DIY, Professional |
| Companies Covered | Unirac Inc., S-5!, IronRidge, Schletter Group, K2 Systems, Roofit.Solar, SunRoof International Holding AB, Solarstone, Tata Power Solar Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Metal Roof Market Evolving Landscape
Factory integration of photovoltaic cells with metal roofing substrates is collapsing the traditional separation between envelope construction and energy system installation. This convergence is redrawing competitive boundaries across the building trades.
Thin-film copper indium gallium selenide (CIGS) technology is integrating directly into standing-seam metal profiles, replacing conventional crystalline silicon modules in architecturally sensitive commercial projects. Luxury hospitality developers in California and Colorado are specifying these systems for slope-constrained roof geometries. The technology is integrating aesthetic performance with energy yield, compressing the historical trade-off between curb appeal and wattage density.
Germany's Ecodesign for Sustainable Products Regulation is mandating minimum recycled content thresholds for solar roofing components entering European markets. Manufacturers must document aluminum alloy provenance and end-of-life recovery pathways to maintain market access. Integrated system suppliers with captive smelter relationships are accelerating compliance investments ahead of enforcement deadlines.
Architects are displacing solar contractors as the primary specification gatekeeper for premium residential projects. Design firms in Massachusetts and New Jersey are bundling solar metal roofs into envelope performance contracts that bypass traditional installer bidding. This channel shift concentrates purchase authority with firms prioritizing factory warranty integration over component cost minimization.
Solar Metal Roof Market Segmentation
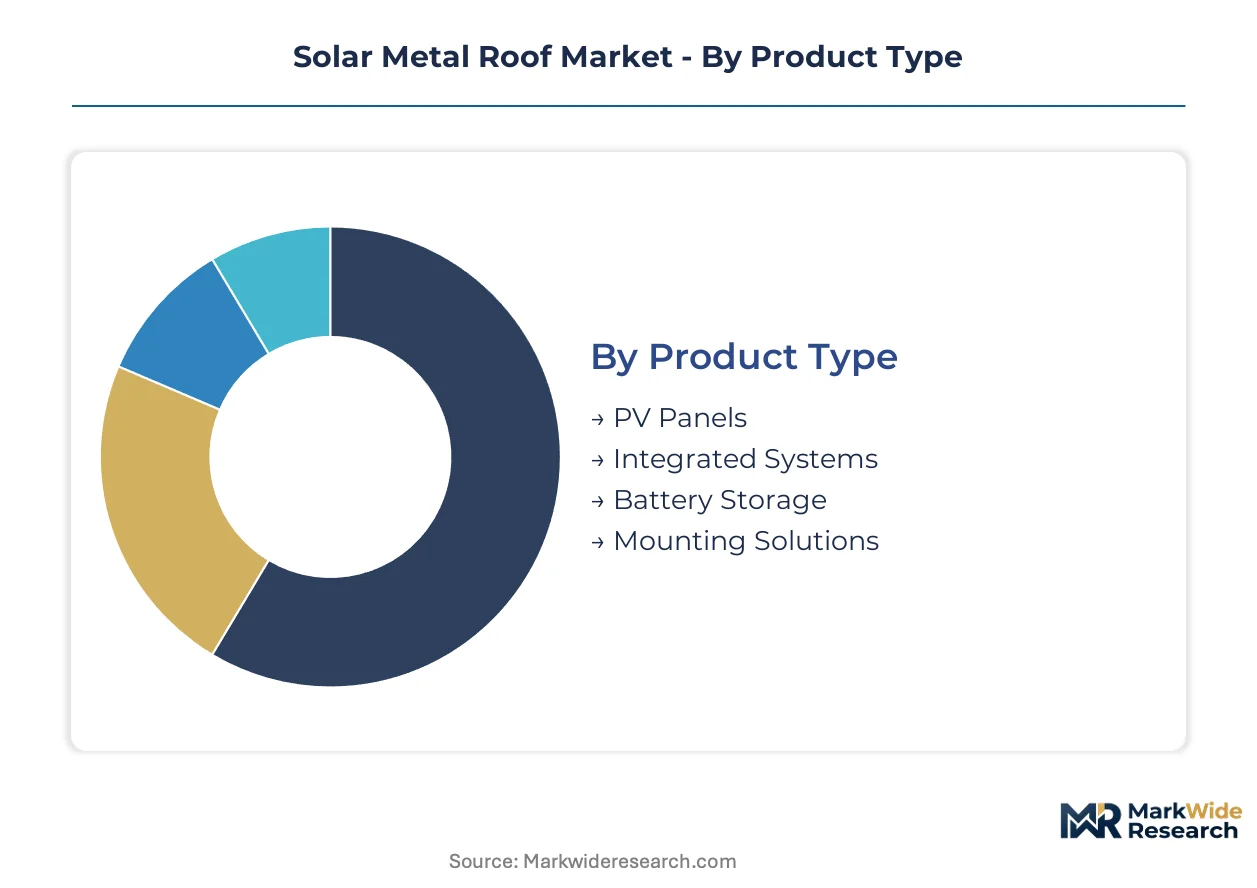
Segmentation in the solar metal roof market determines which certification pathways manufacturers must navigate. Product architecture and installation context dictate whether UL fire-resistance testing, FERC interconnection standards, or local building codes apply.
Product Type:
PV Panels carry lighter certification burdens than factory-integrated alternatives, requiring only module-level UL 1703 compliance rather than full roof assembly testing.
- PV Panels:Conventional crystalline silicon modules mounted atop standing-seam metal substrates using clamp-based attachment systems. Demand concentrates in Texas and Florida residential retrofits where homeowners prioritize cost minimization over aesthetic integration.
- Integrated Systems:Factory-bonded photovoltaic cells fused directly into metal roofing seams during manufacturing. Architects in Germany and the Netherlands are specifying these assemblies for envelope performance contracts that bypass traditional installer bidding channels.
- Battery Storage:Lithium-ion or solid-state units co-installed with solar metal roof systems for load shifting and backup power.
- Mounting Solutions:Specialized clamps, rails, and seam anchors engineered for specific metal profile geometries.
PV Panels sit at the top of the volume ranking, with Integrated Systems climbing the fastest.
Application:
Cost tiers separate application segments, with Industrial deployments commanding premium pricing for structural engineering and utility-scale projects competing on lowest levelized cost of energy.
- Residential:Single-family and multi-family rooftop installations where net-metering policy stability in California and New York protects 20-year investment returns. Homeowner preference for curb-neutral aesthetics is accelerating factory-integrated system uptake.
- Commercial:Office buildings, retail centers, and hospitality properties where fire-resistance certifications from Underwriters Laboratories determine insurance eligibility. Luxury hospitality developers in Colorado are specifying thin-film CIGS systems for slope-constrained geometries.
- Industrial:Manufacturing facilities and distribution centers across Gujarat and Maharashtra states in India's western industrial corridor. State industrial development corporations are mandating solar-ready metal roofing in land allotment agreements.
- Utility Scale:Large ground-mounted or building-integrated arrays feeding directly into transmission infrastructure.
Industrial applications command the highest project values, with Residential expanding most quickly.
Material:
Supply concentration varies sharply by substrate metal, with aluminum availability tied to London Metal Exchange volatility and steel pricing responsive to regional mill capacity.
- Aluminum:Lightweight standing-seam substrates rated for wind uplift pressures exceeding asphalt shingle assemblies. European manufacturers with closed-loop smelter relationships are accelerating compliance investments ahead of Ecodesign for Sustainable Products Regulation enforcement.
- Steel:Galvanized or galvalume-coated substrates offering structural strength at lower material cost. Project developers face margin compression when raw material spikes coincide with fixed-price contract periods.
- Zinc:Naturally weathering substrates prized for architectural longevity and self-healing surface properties.
- Copper:Premium substrates specified for heritage and institutional buildings where material patina contributes to design intent.
Aluminum dominates installed volume, with Steel gaining share fastest in price-sensitive segments.
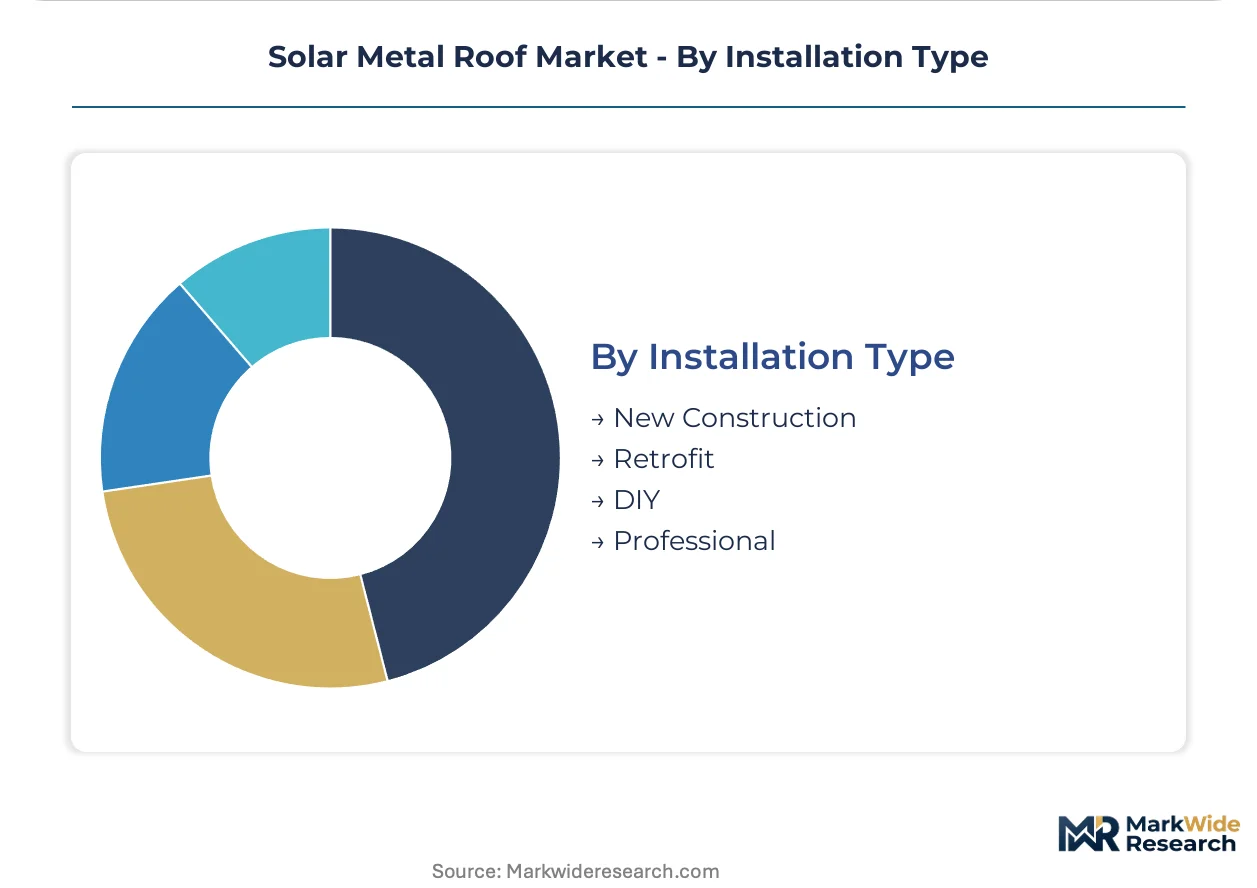
Installation Type:
Customer type and project maturity determine installation approach, with new construction enabling full integration and retrofits facing legacy electrical infrastructure constraints.
- New Construction:Solar metal roof systems specified during architectural design phase. United States distribution center operators face IRA tax credit deadlines that favor integrated roof replacements over panel additions in retrofit scenarios.
- Retrofit:Removal of existing roofing and installation of integrated photovoltaic-metal assemblies. Grid interconnection requires utility-specific transformer upgrades in older commercial buildings.
- DIY:Self-installed systems targeting qualified homeowners with electrical competency.
- Professional:Contractor-installed systems requiring dual-certification in roofing and electrical trades.
New Construction captures the largest project pipeline, with Retrofit showing the steepest expansion trajectory as IRA deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting solar metal roof manufacturing toward jurisdictions with lower compliance burdens. The EU Green Deal's material recovery mandates and India's CEA technical standards are creating divergent cost-of-compliance environments that favor localized production strategies.
United States
Commercial warehouse operators in California and Texas are driving demand for building-integrated photovoltaics ahead of IRA tax credit deadlines. FERC interconnection standards and state-level net-metering policies in New York protect residential investment returns across 20-year depreciation windows. Distribution center clusters in the Inland Empire and Dallas-Fort Worth are mandating solar-ready metal roofing in new construction specifications.
Germany
The Ecodesign for Sustainable Products Regulation is tightening material recovery mandates for solar roofing components entering European markets. CE marking directives now govern end-of-life recyclability requirements that manufacturers must satisfy for market access. Industrial parks in Bavaria and North Rhine-Westphalia are deploying factory-integrated cell-to-seam assemblies for envelope performance contracts.
India
State industrial development corporations in Gujarat and Maharashtra are bundling solar-ready metal roofing specifications into land allotment agreements for manufacturing parks. CEA grid-interconnection standards standardize inverter compatibility and earthing protocols that manufacturers must satisfy to gain preferred vendor status. The western industrial corridor is mandating these systems across new facility construction.
Netherlands
Architects in Amsterdam and Rotterdam are embedding solar metal roofs into envelope performance standards that bypass traditional installer bidding channels. EU Green Deal compliance investments are accelerating ahead of enforcement deadlines for material provenance documentation. Design firms are specifying factory-integrated systems for curb-neutral aesthetics in premium residential developments.
Japan
METI standards for grid-connected rooftop systems are defining inverter compatibility requirements for solar metal roof manufacturers seeking market entry. Kanto region construction firms are specifying thin-film CIGS technology for slope-constrained geometries in luxury hospitality projects. Tokyo metropolitan area building codes are tightening fire-resistance certification thresholds that determine insurance eligibility.
Solar Metal Roof Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue factory-integrated system architectures that collapse installation timelines. The market structures around three distinct capability clusters: domestic manufacturers with rapid fulfillment networks, specialized attachment-system engineers, and project-specific structural calculation providers. Competitive positioning hardens through certification velocity, smelter relationships for aluminum provenance, and dual-trade installer training pipelines. Leading moves include backward integration into captive aluminum supply and architect-channel specification capture.
Among mounting hardware specialists, Unirac Inc. and S-5! occupy positions that exemplify divergent strategic archetypes. Unirac represents the domestic manufacturing footprint model serving North American utility-scale contractors with rapid fulfillment capabilities. S-5! anchors the attachment-system tier through specialized clamp technology for standing-seam metal profiles. Schletter Group sits within the engineering-depth segment, offering project-specific structural calculations that differentiate European-origin product lines. These three firms illustrate how competitive differentiation fragments across fulfillment speed, technical specialization, and calculation authority rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Unirac Inc. |
| S-5! |
| IronRidge |
| Schletter Group |
| K2 Systems |
| Roofit.Solar |
| SunRoof International Holding AB |
| Solarstone |
| Tata Power Solar Systems Ltd. |
| Others |
Value Network & Pricing Analysis
Captive aluminum smelter relationships anchor supply position and pricing power for integrated system manufacturers serving European markets under Ecodesign compliance mandates. These upstream arrangements insulate producers from London Metal Exchange volatility while enabling certified provenance documentation that commands premium positioning.
Pricing Analysis
Architect-channel margins compress distributor markups as design firms bundle solar metal roofs into envelope performance contracts. Project-based pricing stratifies across UL-certified premium tiers, standard commercial grades, and economy retrofit assemblies. Cost compression in steel substrate tiers intensifies when raw material spikes coincide with fixed-price contract periods. Residential retrofits in Texas and Florida exhibit highest price sensitivity, while German industrial parks show lowest sensitivity due to regulatory compliance bundling.
Supply Chain Analysis
Specialized dual-trade installer scarcity in Gujarat and Maharashtra manufacturing corridors constrains deployment velocity for factory-integrated systems. Aluminum supply concentrates in China, Norway, and Canada, while crystalline silicon cell production draws from Taiwan, Malaysia, and Vietnam. Single-source vulnerability persists for thin-film CIGS semiconductor substrates. Distribution runs through EPC contractor networks in India, direct-to-architect channels in Germany and the Netherlands, and roofing contractor partnerships in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as building envelope electrification mandates proliferate across industrial development authorities. Regulatory compliance timelines create predictable procurement windows that stabilize demand visibility.
For Market Incumbents: Anticipate architect-channel displacement by accelerating factory warranty integration that design firms prioritize over component cost minimization. Defend position by deepening backward integration into captive aluminum supply chains ahead of EU Green Deal enforcement. Certification velocity at Underwriters Laboratories represents the critical lever for maintaining insurance-eligible product positioning.
For New Entrants and Emerging Players: United States distribution center operators facing IRA tax credit deadlines constitute an underserved buyer archetype with minimal penetration relative to new construction. Commercial warehouse retrofit white space offers faster specification cycles than residential channels. Pursue direct EPC contractor relationships in Gujarat and Maharashtra where state industrial development corporations mandate solar-ready roofing in land agreements.
For Investors and Strategic Acquirers: Roll-up economics work for specialized attachment-system engineers because fragmented installer networks create acquisition targets with captive regional relationships. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than technology differentiation. Monitor UL fire-resistance certification backlogs as the inflection signal for manufacturer capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Supply | Captive smelter relationships enable Ecodesign compliance documentation that competitors lack. |
| Dual-Trade Installer Training Pipeline | Hybrid roofing-electrical certification addresses scarcity constraining factory-integrated deployment. |
| Architect Channel Specification Capture | Design firm partnerships bypass traditional solar contractor bidding for premium residential projects. |
| UL Fire-Resistance Parallel Tracking | Multi-jurisdiction certification velocity determines product launch timing and insurance eligibility. |
| Commercial Warehouse Retrofit Focus | IRA deadline pressure creates concentrated demand from distribution center operators. |
Research Methodology
Bottom-up installation volume modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with EPC contractors, roofing system architects, utility interconnection planners, and industrial development corporation procurement officers combined with secondary validation from FERC interconnection databases, CEA technical standards filings, EU Ecodesign regulatory texts, and London Metal Exchange aluminum pricing records. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of residential retrofit penetration rates, commercial new construction specifications, and industrial park deployment timelines informed projection frameworks. Segmentation dimensions modeled include product architecture, application context, substrate material, and installation type across the analysis window. CAGRs derive from fitted growth curves adjusted for policy stability indicators and raw material cost trajectories. Net-metering policy durability and IRA tax credit phase-out schedules constitute key forecast inputs.
Underlying measurement precision varies by segment; factory-integrated systems carry tighter precision than retrofit PV panel installations due to concentrated supplier bases. Forecasts reflect assumptions regarding aluminum price volatility, installer training pipeline development, and regulatory enforcement timing. Material deviation in FERC interconnection standard revisions, EU Ecodesign enforcement intensity, or Indian state-level mandate expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Printable Solar Cells Market