
 Germany Distributed Solar Power Generation Market | 2026-2036
Germany Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Distributed Solar Power Generation Market Foresight
Photovoltaic module assembly capacity across Germany is expanding as domestic producers respond to supply chain realignment pressures. Trina Solar Limited leverages its vertically integrated cell-to-module manufacturing to secure cost positions in the distributed segment. RheinEnergie AG anchors regional deployment through its utility-scale project development expertise repurposed for commercial rooftops. Juwi Solar Inc. specializes in engineering services that reduce soft costs for agricultural and industrial ground-mounted installations.
Distributed solar power generation refers to decentralized photovoltaic electricity production sited at or near consumption points, typically employing silicon-based modules with conversion efficiencies ranging from 20% to 24% in monocrystalline configurations to offset retail grid tariffs or feed surplus into distribution networks. Rooftop systems dominate current installed capacity across residential and commercial segments, though building-integrated photovoltaics are gaining structural traction as construction codes tighten energy performance standards. Agricultural operations represent a fast-growing end user category where bifacial modules on elevated ground-mounted arrays enable dual land use, creating distinct margin pools for developers who navigate zoning complexity.
The Bundesnetzagentur administers grid connection queues and market premium auctions under EEG amendments, while KBA standards govern electrical safety in building-integrated configurations, and the EU Green Deal's solar rooftop mandate for commercial buildings is tightening product compliance requirements. These overlapping frameworks are elevating certification burdens for imported modules while privileging domestic assembly. Stakeholders must monitor how the forthcoming EU Net-Zero Industry Act local content provisions interact with Germany's accelerated permitting reforms to determine manufacturing investment timing.
Market Dynamics
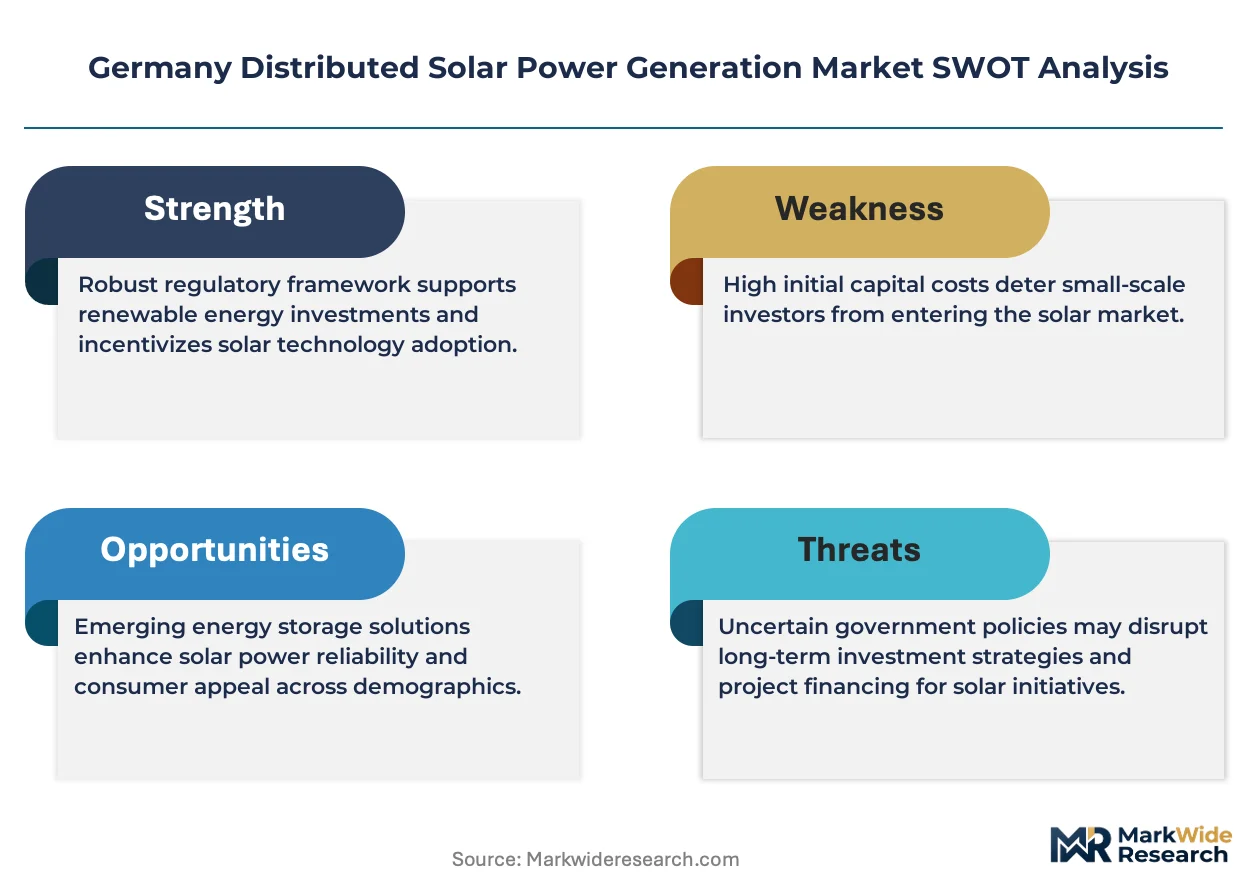
EEG feed-in tariff revisions and accelerated permitting reforms under the EnWG are compressing project development timelines and redistributing margin capture between developers, EPCs, and asset owners across German federal states.
Growth Catalysts
- EEG Market Premium Mechanism:The shift from fixed feed-in tariffs to direct marketing with market premiums incentivizes commercial offtakers to optimize self-consumption ratios and reduce grid dependency.
- Bavarian Manufacturing Clusters:Industrial facilities in Bavaria are deploying rooftop systems at scale to hedge against volatile wholesale electricity prices and secure operational cost predictability.
- Agrivoltaics Zoning Liberalization:Elevated bifacial arrays on agricultural land in North Rhine-Westphalia now qualify for simplified permitting under revised BauNVO provisions, unlocking dual-use revenue streams.
Market Restraints
- Polysilicon Supply Concentration:German module assemblers remain exposed to Xinjiang-origin polysilicon supply disruptions and forced labor due diligence requirements under the EU Forced Labor Regulation.
- Grid Connection Queue Congestion:Bundesnetzagentur processing backlogs for low-voltage connection approvals extend commercial project commissioning timelines by 8-14 months in high-demand districts.
- Skilled Installer Scarcity:Certified electrical technician shortages limit EPC scaling capacity, particularly for building-integrated photovoltaic configurations requiring specialized mounting expertise.
Strategic Opportunities
- EU Solar Rooftop Mandate:The EU Green Deal's phased requirement for solar installations on new commercial and public buildings creates guaranteed demand floors through 2029.
- Industrial Heat Electrification:Process heat applications in Baden-Württemberg's automotive supply chain are integrating rooftop generation with thermal storage to displace natural gas combustion.
- Prosumer Aggregation Platforms:Virtual power plant operators are recruiting distributed asset fleets to participate in secondary frequency regulation markets, monetizing flexibility previously trapped behind the meter.
Industry Challenges
- CE Marking Convergence:Module manufacturers face overlapping certification requirements from KBA electrical safety standards and impending EU Net-Zero Industry Act local content verification protocols.
- Legacy Grid Infrastructure:Rural distribution networks in eastern federal states lack voltage regulation capacity to absorb reverse power flows from high-penetration agricultural solar clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Distributed Solar Power Generation Market |
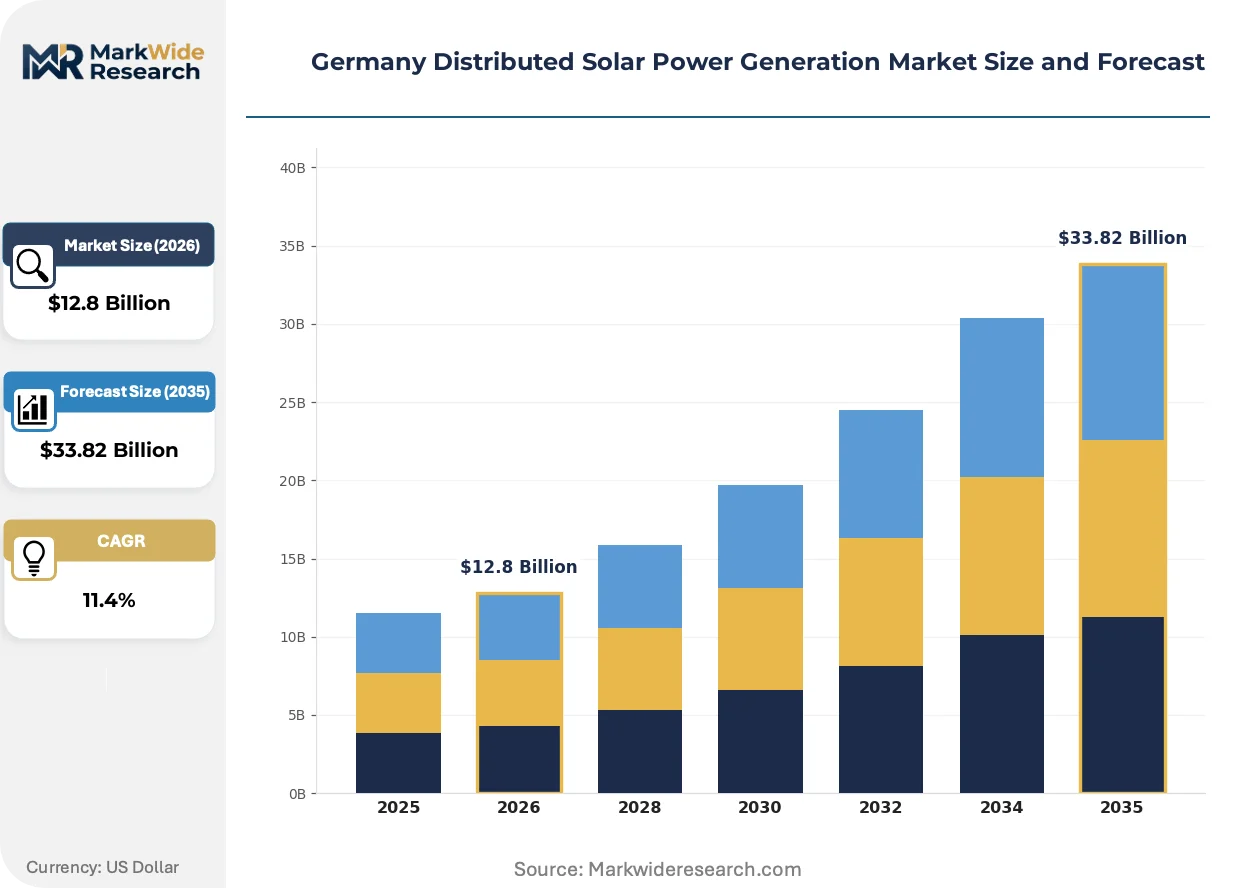
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
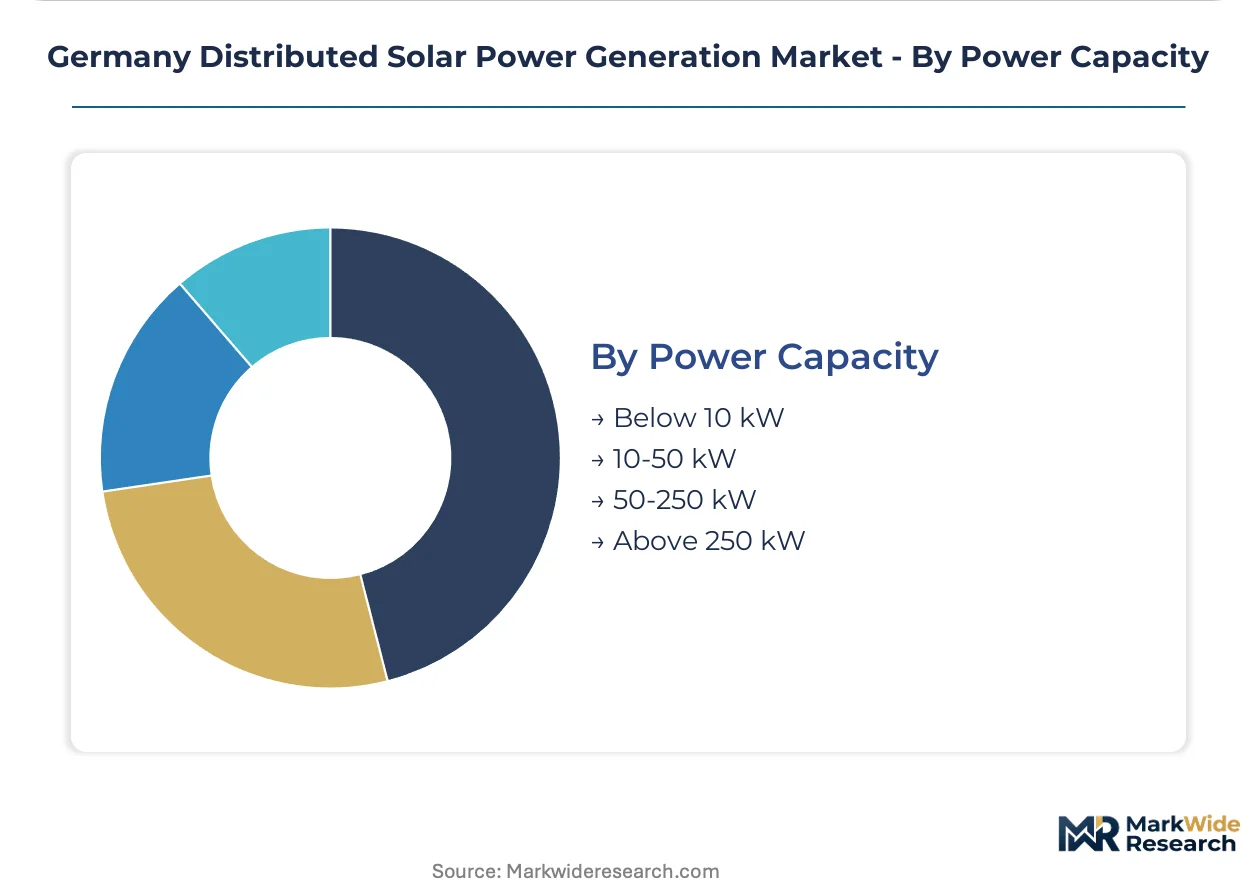
| Segmentation | Installation Type: Rooftop Systems, Ground-Mounted Arrays, Building-Integrated Photovoltaics, Floating Solar Panels Technology: Monocrystalline Silicon, Polycrystalline Silicon, Thin-Film, Bifacial, Concentrated Photovoltaics End User: Residential Consumers, Commercial Establishments, Industrial Facilities, Agricultural Operations Power Capacity: Below 10 kW, 10-50 kW, 50-250 kW, Above 250 kW |
| Companies Covered | Tesla Inc., RheinEnergie AG, Juwi Solar Inc., Redavia, Sono Motors, Trina Solar Limited, Wuxi Suntech Power Co. Ltd, Verbund, First Solar Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Distributed Solar Power Generation Market Shifts & Advancements
Bifacial module architectures and smart inverter controls are compressing levelized cost thresholds while policy mandates accelerate building-integrated deployment across German commercial real estate.
Module-level power electronics is modularizing distributed system architecture by replacing string inverter configurations with panel-integrated optimizers and microinverters. Agricultural and commercial installers in Lower Saxony are adopting these architectures to mitigate shading losses and simplify maintenance access. This technology is modularizing EPC service offerings, enabling standardized subsystem procurement that reduces engineering customization for repetitive ground-mounted layouts.
The EU Net-Zero Industry Act local content provisions are tightening supply chain documentation requirements for public procurement and auction participation. German project developers must now trace cell and wafer provenance through tiered supplier declarations to qualify for non-price criteria weighting. Commercial rooftop segments are responding by accelerating offtake agreements with domestic module assembly operations to secure bid competitiveness.
Corporate power purchase agreements are displacing traditional feed-in tariff reliance among large industrial offtakers in the Rhineland. Energy-intensive manufacturers now contract directly with project developers for behind-the-meter or virtual solar supply, transferring merchant price risk to specialized asset operators. This behavioral shift is most visible in North Rhine-Westphalia's chemicals corridor, where BASF and Covestro equivalents are consolidating procurement through multi-site portfolio structures.
Germany Distributed Solar Power Generation Market Segmentation

Deployment economics in Germany's distributed solar market diverge sharply across installation configurations, cell architectures, and offtaker profiles. Segment-specific regulatory treatment under EEG amendments and EnWG permitting reforms creates distinct margin pools that reshape competitive positioning.
Installation Type:
Structural mounting configurations determine grid connection voltage levels, permitting complexity, and land-use qualification under BauNVO amendments.
- Rooftop Systems:Silicon modules affixed to existing building envelopes dominate current installed capacity. Manufacturing clusters in Bavaria deploy these systems at scale to hedge volatile wholesale electricity prices and secure operational cost predictability.
- Ground-Mounted Arrays:Elevated steel or aluminum racking systems on open land enable larger capacity blocks. Agricultural operations in North Rhine-Westphalia are driving additions here as revised zoning provisions unlock dual-use revenue streams for bifacial configurations.
- Building-Integrated Photovoltaics:Structural elements where photovoltaic material substitutes conventional construction materials. KBA electrical safety standards and tightening energy performance codes elevate certification burdens for these specialized installations.
- Floating Solar Panels:Pontoon-mounted arrays on water bodies. Limited deployment to date reflects higher EPC costs and complex environmental permitting requirements.
Rooftop systems lead on scale; ground-mounted arrays lead on momentum.
Technology:
Cell architecture selection dictates conversion efficiency, temperature coefficients, and supply chain provenance requirements under EU Forced Labor Regulation.
- Monocrystalline Silicon:Single-crystal wafers with conversion efficiencies ranging from 20% to 24%. Commercial rooftop segments in Baden-Württemberg favor these modules for space-constrained installations where output density maximizes self-consumption economics.
- Bifacial:Dual-sided cell structures capturing reflected irradiance from ground surfaces. Agricultural ground-mounted installations in Lower Saxony are adopting these architectures to mitigate shading losses and enable elevated array configurations.
- Polycrystalline Silicon:Multi-crystal ingot production with lower manufacturing energy intensity. Cost-sensitive residential segments retain limited offtake despite efficiency disadvantages.
- Thin-Film:Cadmium telluride or copper indium gallium selenide deposition on glass substrates. Building-integrated configurations exploit uniform aesthetics and flexible form factors.
- Concentrated Photovoltaics:Optical concentration systems with dual-axis tracking. Niche utility-scale applications with minimal distributed market penetration.
Monocrystalline silicon dominates volume; bifacial architectures are climbing the fastest.
End User:
Offtaker category shapes financing structures, self-consumption optimization strategies, and participation eligibility in EEG market premium mechanisms.
- Industrial Facilities:Energy-intensive manufacturing operations with behind-the-meter generation and thermal storage integration. Rhineland chemicals corridors are consolidating procurement through multi-site portfolio structures.
- Agricultural Operations:Farms deploying elevated ground-mounted arrays with grazing or crop cultivation beneath. Simplified permitting under revised BauNVO provisions accelerates deployment in eastern federal states.
- Commercial Establishments:Retail, logistics, and office properties with predictable daytime load profiles. EU Green Deal rooftop mandates for new commercial buildings create guaranteed demand floors through 2029.
- Residential Consumers:Single-family and multi-family dwellings with sub-10 kW typical configurations. Prosumer aggregation platforms are recruiting these assets for virtual power plant participation.
Industrial facilities lead on scale; agricultural operations lead on momentum.
Power Capacity:
System size thresholds trigger distinct regulatory treatments under Bundesnetzagentur grid connection rules and EEG remuneration categories.
- 50-250 kW:Commercial rooftop and small ground-mounted configurations. This bracket captures the bulk of agricultural bifacial deployments and industrial self-consumption optimization in Bavaria.
- 10-50 kW:Large residential and small commercial installations. Virtual power plant operators actively recruit these assets for secondary frequency regulation market participation.
- Below 10 kW:Standard residential systems. Certified electrical technician shortages constrain EPC scaling capacity for these high-volume, low-margin installations.
- Above 250 kW:Large commercial and industrial arrays approaching utility-scale thresholds. Grid connection queue congestion extends commissioning timelines by 8-14 months in high-demand districts.
The 50-250 kW bracket leads on scale; the 10-50 kW bracket leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing module assembly capacity toward jurisdictions with streamlined permitting and local-content verification protocols. German federal states with accelerated EnWG reforms attract disproportionate developer capital relative to eastern regions where grid infrastructure lags.
Bavaria
Industrial manufacturing clusters and automotive supply chains drive rooftop deployment at scale. The EEG market premium mechanism incentivizes self-consumption optimization for energy-intensive facilities. Munich and Nuremberg manufacturing corridors anchor capacity additions as producers hedge volatile wholesale electricity prices.
North Rhine-Westphalia
Chemicals corridor offtakers including BASF and Covestro equivalents consolidate procurement through multi-site portfolio structures. Revised BauNVO provisions liberalize agrivoltaics zoning for elevated bifacial arrays. The Rhineland industrial belt leads corporate power purchase agreement adoption for behind-the-meter generation.
Baden-Württemberg
Automotive supply chain process heat electrification integrates rooftop generation with thermal storage systems. KBA electrical safety standards elevate certification burdens for building-integrated configurations. Stuttgart industrial zones prioritize monocrystalline modules for space-constrained installations.
Lower Saxony
Agricultural operations adopt elevated ground-mounted arrays with grazing beneath bifacial configurations. Module-level power electronics architectures mitigate shading losses for distributed layouts. Rural distribution networks face voltage regulation constraints from high-penetration solar clusters.
Hesse
Frankfurt-Rhine-Main logistics and data center properties deploy commercial rooftop systems with predictable daytime load profiles. Bundesnetzagentur grid connection queues extend commissioning timelines by 8-14 months in high-demand districts. Prosumer aggregation platforms recruit residential assets for virtual power plant participation.
Germany Distributed Solar Power Generation Market Competitive Landscape
Chinese producers anchor the module supply tier; German utility and engineering specialists hold downstream development and integration positions. The vendor base fragments across vertically integrated cell-to-module manufacturers, regional utility repurposers, and agricultural installation specialists. Three archetypes dominate: cost-optimized Asian fabricators, domestic grid-connection navigators, and agrivoltaics zoning experts. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms secure non-price criteria weighting under EU Net-Zero Industry Act provisions.
Among module manufacturers, Trina Solar Limited and Wuxi Suntech Power Co. Ltd represent cost-optimized fabrication archetypes with vertically integrated cell-to-module positions. RheinEnergie AG anchors the utility repurposer tier, leveraging grid-scale project development expertise for commercial rooftop deployment. Juwi Solar Inc. occupies the agricultural installation specialist position, engineering services that reduce soft costs for ground-mounted bifacial configurations in dual-use land applications.
| Leading Market Players |
|---|
| Tesla Inc. |
| RheinEnergie AG |
| Juwi Solar Inc. |
| Redavia |
| Sono Motors |
| Trina Solar Limited |
| Wuxi Suntech Power Co. Ltd |
| Verbund |
| First Solar Inc. |
| Others |
Supply & Pricing Matrix
The EU Green Deal's solar rooftop mandate gates both qualified supply and premium-tier pricing access for German distributed solar deployments, as module assemblers must document cell provenance through tiered supplier declarations to qualify for non-price criteria weighting in public procurement. This regulatory filtration compresses margin capture for uncertified imports while elevating domestic assembly premiums across Bavarian manufacturing clusters and Rhineland chemicals corridors.
Pricing Analysis
Distributor margins for module procurement absorb 12-18% of landed costs before EPC markups apply, with three-tier pricing structure across premium, standard, and economy levels differentiating by CE marking tier and KBA electrical safety certification. Price differentiation stems from supply chain documentation depth and Bundesnetzagentur queue priority access, while cost compression in the economy tier intensifies because of Xinjiang-origin polysilicon forced labor due diligence requirements. Residential consumers exhibit highest price sensitivity; industrial offtakers in North Rhine-Westphalia's chemicals corridor demonstrate lowest sensitivity due to corporate power purchase agreement structures.
Supply Chain Analysis
CE marking convergence with impending EU Net-Zero Industry Act local content verification protocols gates supplier qualification, as German project developers must trace wafer provenance through tiered declarations to secure bid competitiveness. Module assembly draws from polysilicon originating in China, Germany, and Norway, with cell processing concentrated in Southeast Asia and module finishing distributed across European contract manufacturers. Single-source vulnerability in metallurgical-grade silicon feedstock feeds from quartz mining concentration in specific jurisdictions. Distribution runs through utility-affiliated EPCs and agricultural installation specialists serving dual-use land applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany distributed solar market functions as a geographic-arbitrage play where accelerated EnWG permitting reforms in Bavaria and North Rhine-Westphalia compress development timelines relative to eastern federal states with legacy grid infrastructure constraints.
For Market Incumbents: Deepen backward integration into domestic module assembly to secure non-price criteria weighting under EU Net-Zero Industry Act provisions, while expanding captive installation capacity in Lower Saxony to capture agrivoltaics zoning liberalization momentum. The threat of Chinese cost-optimized fabricators with vertically integrated positions necessitates certification investment in KBA electrical safety standards for building-integrated configurations. Vertical integration into polysilicon refining represents the critical lever for margin defense. For New Entrants and Emerging Players: Smart inverter controls with panel-integrated optimizers offer a technology-first wedge into the 10-50 kW commercial rooftop segment where virtual power plant aggregation platforms actively recruit assets. The most penetrable white-space target sits in eastern federal states where skilled installer scarcity constrains EPC scaling capacity for residential sub-10 kW configurations. A go-to-market angle through prosumer aggregation partnerships enables secondary frequency regulation market participation without direct EPC competition. For Investors and Strategic Acquirers: Roll-up economics work for agricultural installation specialists because revised BauNVO provisions unlock dual-use revenue streams faster than organic EPC scaling permits. Long-term viability across the analysis window hinges on exposure to corporate power purchase agreement offtakers with multi-site portfolio structures. Acquisition targets should demonstrate grid-connection navigation expertise in Bundesnetzagentur queue management. The signal to monitor is EU Forced Labor Regulation enforcement intensity against Xinjiang-origin polysilicon supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Module Assembly Scale-Up | Secures non-price criteria weighting under EU Net-Zero Industry Act local content provisions for public procurement eligibility. |
| Agrivoltaics Zoning Expertise Acquisition | Captures dual-use land revenue streams in North Rhine-Westphalia where revised BauNVO provisions accelerate permitting. |
| Virtual Power Plant Platform Integration | Monetizes behind-the-meter flexibility from 10-50 kW assets in secondary frequency regulation markets through prosumer aggregation. |
| Grid Connection Queue Navigation Capability | Compresses commissioning timelines by 8-14 months in high-demand districts where Bundesnetzagentur processing backlogs concentrate. |
| Building-Integrated Photovoltaics Certification Investment | Addresses KBA electrical safety standards and EU Green Deal commercial building mandates tightening product compliance requirements. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with EPC contractors, utility planning officers, agricultural installation specialists, and corporate energy procurement leads with secondary validation through Bundesnetzagentur auction data, EnWG regulatory filings, and EEG amendment documentation. The approach triangulates module shipment records, grid connection queue databases, and federal state permitting statistics against installer capacity surveys and offtaker self-consumption ratio disclosures.
Input-output matrices map capacity deployment by installation type, cell architecture, and power capacity tier across the projection horizon, with segmentation dimensions spanning structural mounting configuration, monocrystalline versus bifacial technology selection, and offtaker category from industrial facilities to agricultural operations. CAGRs derive from capacity addition run-rates reconciled against policy mechanism phase-out schedules and grid absorption constraints. Forecast inputs incorporate EEG market premium mechanism participation rates and EnWG permitting velocity differentials across federal states.
The model holds under continued EEG premium support and EnWG acceleration; deviation in EU Forced Labor Regulation enforcement intensity or grid infrastructure investment shortfalls in eastern federal states would shift deployment gravity and margin distribution. Forecasts reflect assumptions on polysilicon supply chain realignment timing and skilled installer labor market expansion. A model refresh is warranted upon material change in EU Net-Zero Industry Act local content verification protocol implementation or Bundesnetzagentur queue management reform.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market