
 Smart Solar Solutions Market | 2026-2036
Smart Solar Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Solar Solutions Market Outlook
Utility-scale procurement is broadening as grid operators modernize infrastructure. Siemens AG leverages its automation portfolio to compete in utility-scale control systems. Schneider Electric SE anchors distributed energy management through its EcoStruxure platform. Enphase Energy specializes in microinverter architectures for residential retrofit applications.
Smart solar solutions integrate photovoltaic generation with real-time monitoring, predictive analytics, and grid-responsive control systems operating at 98-99% inverter efficiency. These systems optimize energy yield, reduce curtailment losses, and enable participation in demand-response programs. Photovoltaic technology dominates installed capacity, though bifacial modules capture expanding share in utility-scale ground-mounted installations where albedo enhancement lifts yields. Monitoring systems represent the fastest-expanding product category as operators prioritize predictive maintenance and fleet-level performance optimization.
Grid codes from FERC and IEEE 1547 in the United States shape inverter functionality requirements, while the EU Green Deal and F-Gas Regulation in Europe drive embodied-carbon standards for module manufacturing. California's NEM 3.0 and Germany's EEG framework illustrate how tariff restructuring redirects investment toward storage-integrated systems. Stakeholders must track evolving interconnection standards and carbon-border adjustments to maintain product-market fit across jurisdictions.
Market Dynamics
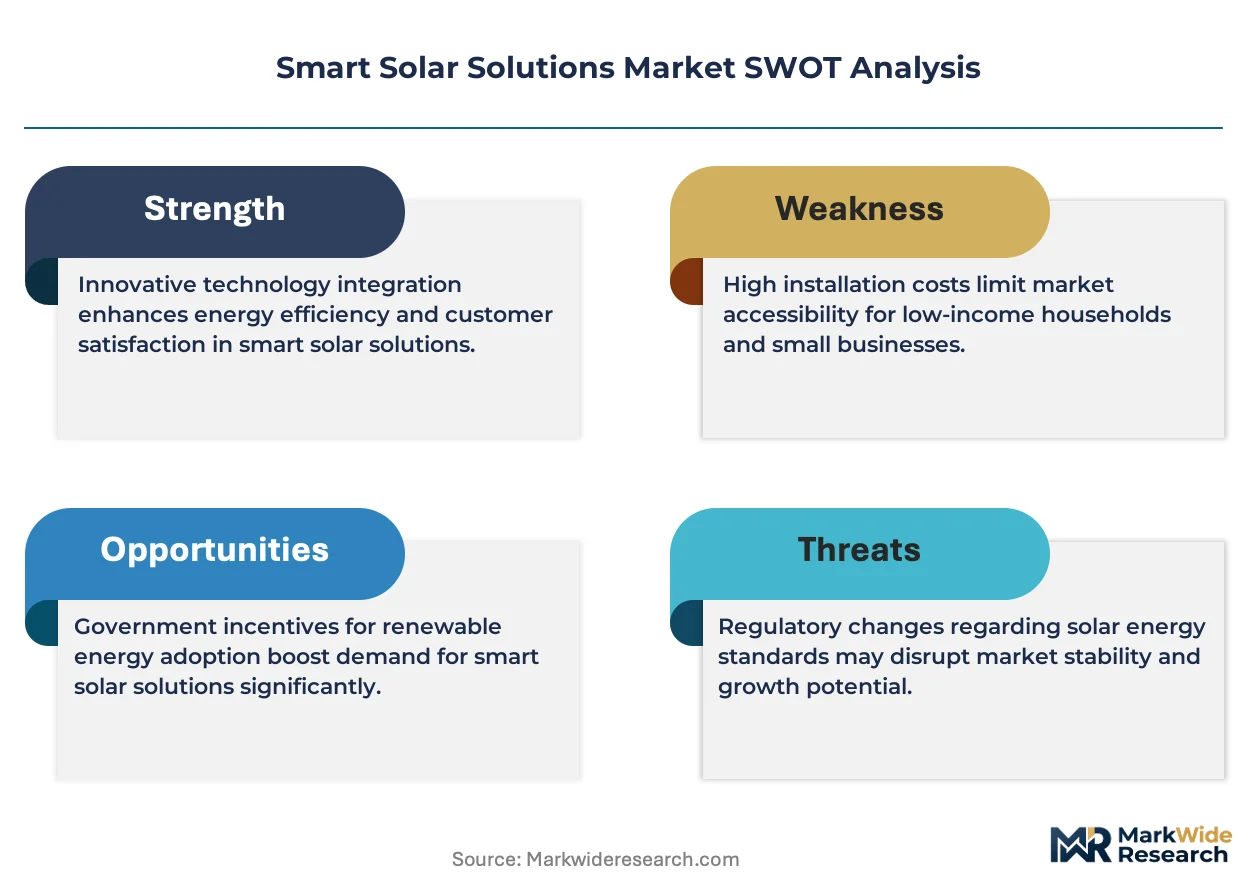
California's NEM 3.0 tariff restructuring is forcing residential solar economics toward mandatory storage pairing, compressing standalone system margins while expanding hybrid inverter deployment across the US Southwest.
Growth Catalysts
- Grid Modernization Mandates:FERC Order 2023 in the United States requires advanced inverter functionality for all new interconnections, accelerating smart solar control system procurement by utilities.
- Industrial Electrification:Germany's Ruhr industrial corridor is retrofitting manufacturing facilities with bifacial-plus-storage configurations to hedge against volatile wholesale electricity pricing.
- Module Efficiency Gains:Passivated emitter and rear contact cell architectures are lifting commercial rooftop yields above 22%, shortening payback periods for C&I adopters in high-tariff jurisdictions.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-sourced polysilicon faces EU carbon-border adjustment exposure, elevating module input costs for European project developers.
- Interconnection Queues:US transmission study backlogs now exceed three years in PJM and CAISO territories, freezing project completion timelines regardless of equipment availability.
- Skilled Installer Shortage:NABCEP-certified technicians remain scarce across the US Mountain West, capping deployment velocity in high-insolation markets.
Strategic Opportunities
- Agrivoltaics Expansion:Dual-use solar-plus-agriculture installations qualify for enhanced USDA Rural Energy for America Program incentives in the US Midwest.
- Virtual Power Plant Aggregation:Residential battery fleet orchestration creates new revenue streams for aggregators participating in Texas ERCOT ancillary services markets.
- AI-Driven Performance Optimization:Machine learning algorithms applied to satellite imagery and inverter telemetry are reducing O&M truck rolls by predicting soiling and degradation patterns.
Industry Challenges
- Legacy SCADA Integration:Utility-scale smart solar deployments must bridge proprietary protocols from 1990s-era grid management systems, extending commissioning timelines.
- Fire Safety Certification:Rapid shutdown compliance with UL 1741-SA requires redesigned string inverter architectures, forcing R&D recalibration across product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Solar Solutions Market |
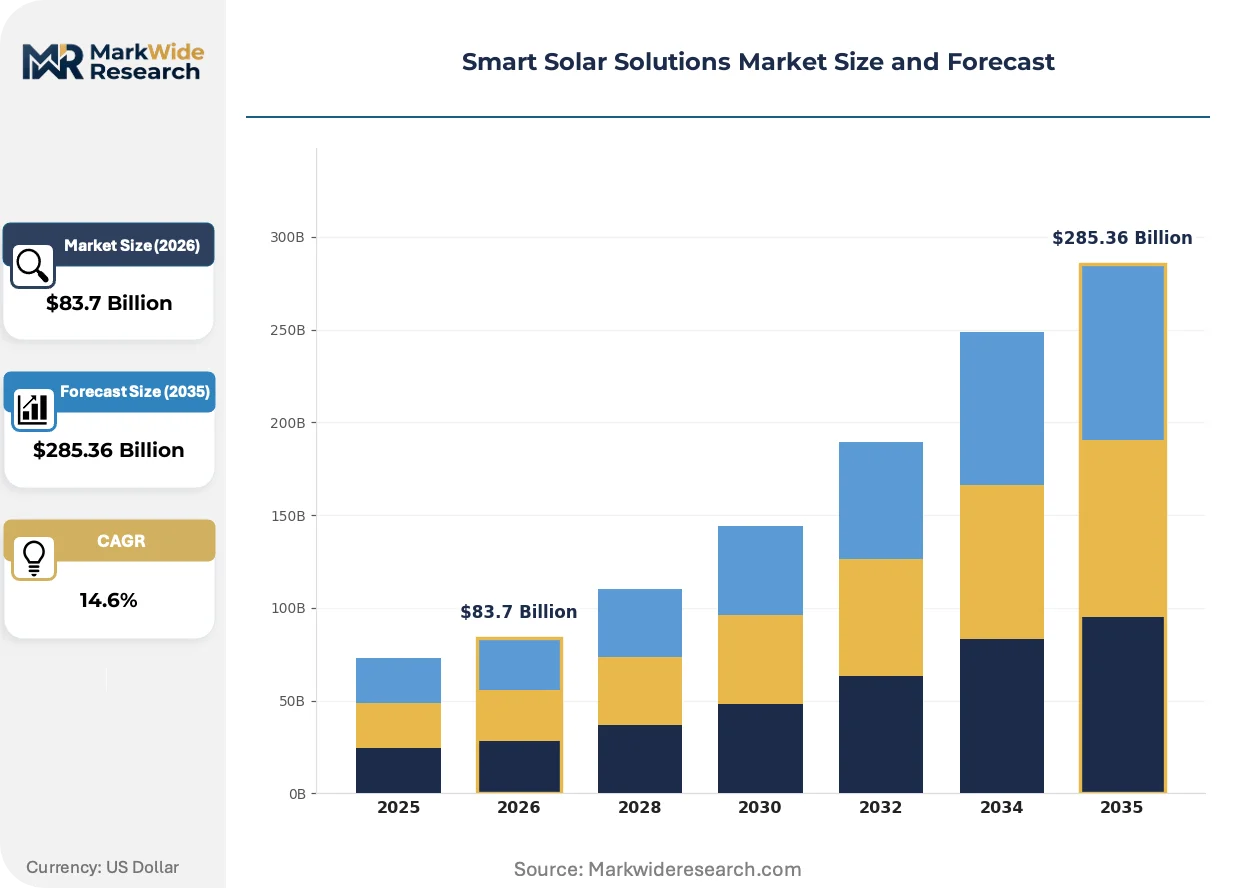
| Market Size in 2026 | $83.7 Billion |
| Market Size in 2035 | $285.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Batteries, Monitoring Systems Technology: Photovoltaic, Concentrated Solar Power, Bifacial, Thin-Film Application: Residential, Commercial, Industrial, Utility Installation: Rooftop, Ground-Mounted, Building-Integrated, Floating |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric SE, General Electric, Itron, Inc., SolarEdge Technologies, Enphase Energy, SMA Solar Technology AG, Tesla Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Solar Solutions Market Strategic Shifts
Smart solar hardware is converging with software-defined control layers, compressing the traditional separation between power electronics and grid management functions into unified platform architectures.
Power optimizer technology is modularizing at the module level, enabling granular maximum power point tracking across heterogeneous string conditions. Commercial installers in shaded urban environments are specifying optimizer-equipped systems for 40% of new rooftop capacity. This granularity is compressing system design constraints and reducing balance-of-system engineering hours per project.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in heat pump and inverter cooling systems, forcing manufacturers toward CO2 or propane-based thermal management. Industrial-scale inverter suppliers serving the German market are redesigning thermal architectures to maintain 99% efficiency targets under stricter refrigerant rules. Module-assemblers with European manufacturing footprints are securing early certification to capture utility-scale tenders with embodied-carbon scoring.
Energy-as-a-service contracting is displacing traditional equipment ownership models among US commercial real estate operators. Third-party financiers now structure 20-year power purchase agreements with embedded storage and predictive maintenance, transferring technology risk from building owners to specialized asset managers. This shift concentrates procurement authority with national-scale developers and squeezes regional installer margins in the US Southeast.
Smart Solar Solutions Market Segmentation
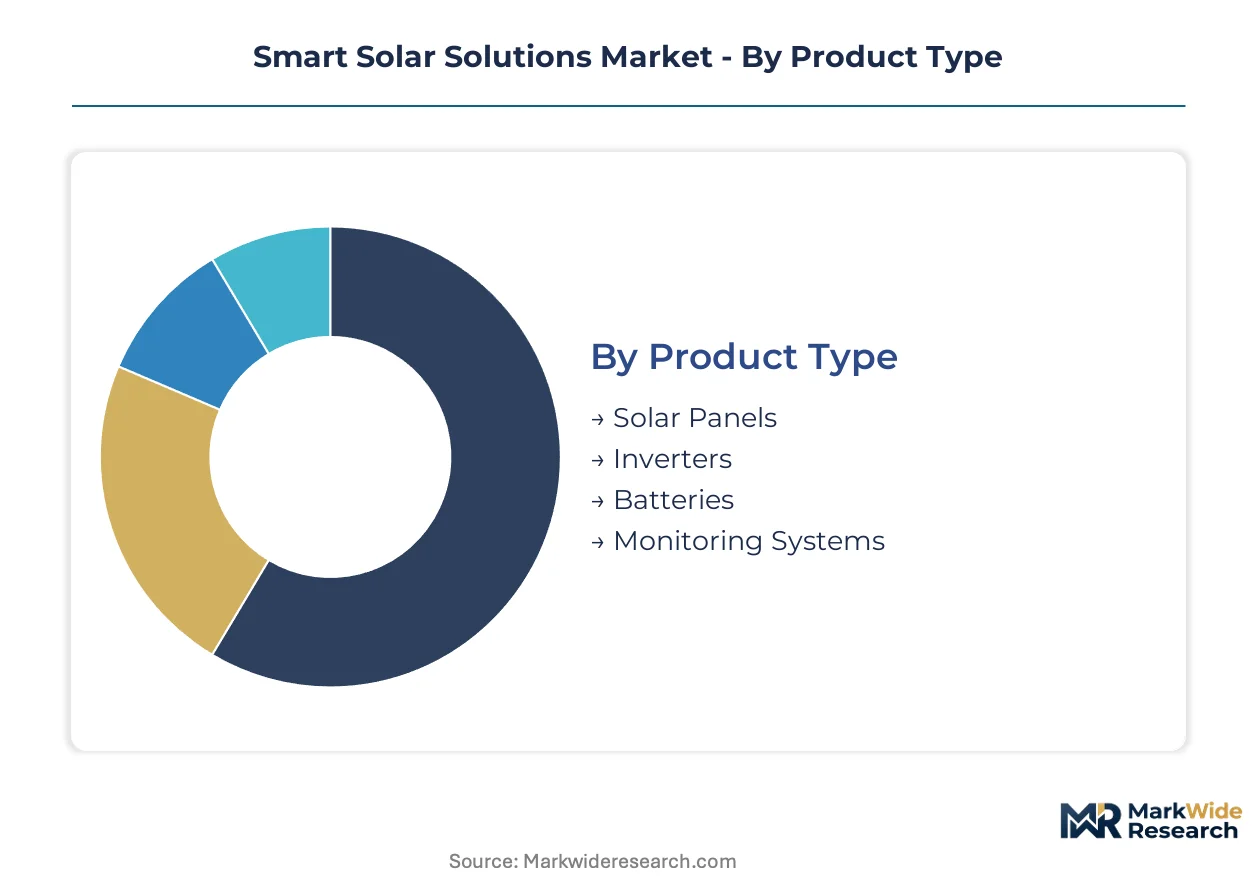
Smart solar solutions fragment across four distinct taxonomies that determine procurement patterns and margin structures. Product type dictates capital intensity and replacement cycles. Technology selection shapes yield profiles and geographic suitability. Application verticals drive regulatory exposure and financing mechanisms. Installation topology constrains labor availability and balance-of-system costs.
Product Type:
Supply concentrates in power electronics and monitoring subsystems where semiconductor content creates fabrication bottlenecks.
- Solar Panels:Crystalline silicon modules dominate procurement volumes, with passivated emitter rear contact architectures lifting commercial efficiency above 22%. Utility-scale developers in Texas and Arizona specify bifacial glass-glass constructions to capture albedo gains on high-reflectivity ground surfaces.
- Inverters:String and central inverter architectures are converging under IEEE 1547-2018 grid support requirements, forcing firmware differentiation over hardware topology. German industrial facilities specify hybrid inverters with integrated storage interfaces to comply with EEG framework incentives.
- Batteries:Lithium iron phosphate chemistries anchor residential and commercial stationary storage, with NEM 3.0 compliance mandating four-hour duration minimums across California installations.
- Monitoring Systems:Fleet-level analytics platforms with satellite-derived irradiance correlation are compressing O&M response times for distributed asset managers.
Today's leader: Solar Panels. Tomorrow's challenger: Monitoring Systems.
Technology:
Cost tier stratification separates premium-efficiency architectures from commodity silicon in procurement specifications.
- Photovoltaic:Crystalline silicon technology captures the dominant share of installed capacity, with PERC and TOPCon cell architectures extending efficiency leadership. Utility procurement in India and Brazil prioritizes photovoltaic for its bankable performance track record and established supply chains.
- Concentrated Solar Power:Molten salt thermal storage configurations anchor dispatchable renewable capacity in Spain and Morocco, where direct normal irradiance exceeds 2,000 kWh/m² annually. Parabolic trough and power tower designs face silicon cost competition but retain grid stability advantages.
- Bifacial:Dual-sided energy capture modules are gaining share fastest in utility-scale ground-mounted applications, with albedo-responsive yield modeling improving project finance terms.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies retain niche positioning in building-integrated applications where weight constraints and aesthetic flexibility outweigh efficiency premiums.
Photovoltaic maintains volume dominance. Bifacial climbs the fastest on expanding utility procurement.
Application:
Customer type determines financing structure complexity and regulatory compliance burden across deployment verticals.
- Residential:Behind-the-meter solar-plus-storage systems are restructuring under California NEM 3.0 export tariffs, with payback periods extending unless battery self-consumption rates exceed 80%. Virtual power plant aggregation creates new revenue streams for fleet orchestrators in Texas ERCOT markets.
- Commercial:Corporate power purchase agreements and on-site solar leases are displacing direct equipment ownership among US real estate investment trusts, transferring technology risk to specialized asset managers.
- Industrial:Germany's Ruhr corridor and US Gulf Coast petrochemical complexes are retrofitting bifacial-plus-storage configurations to hedge volatile wholesale electricity exposure.
- Utility:Merchant and contracted solar farms face interconnection queue backlogs exceeding three years in PJM and CAISO territories, freezing completion timelines regardless of equipment availability.
Utility commands capital deployment scale. Residential gains policy-driven momentum through storage mandates.
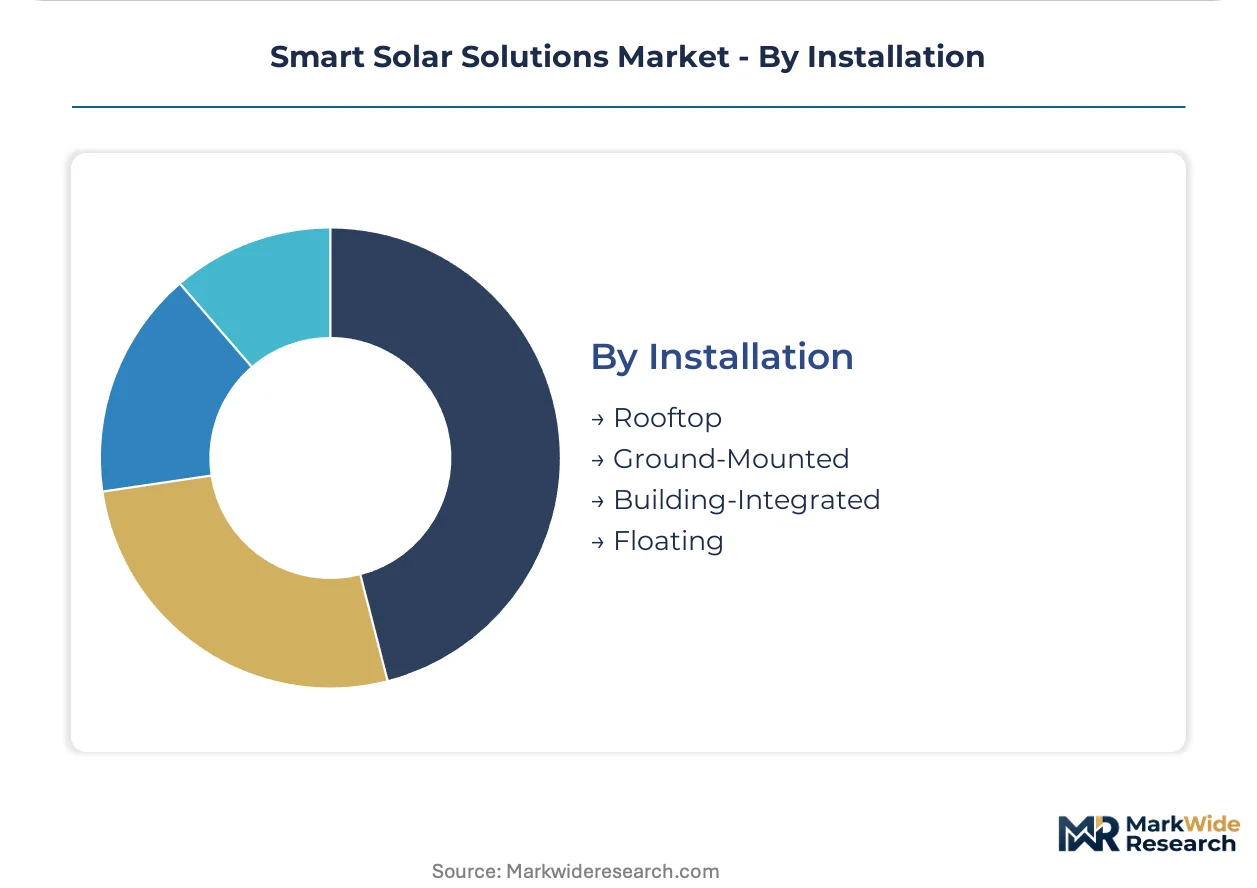
Installation:
Geography and site constraints dictate labor specialization requirements and balance-of-system engineering intensity.
- Rooftop:Commercial and residential rooftop deployments dominate distributed generation capacity, with power optimizers specified for 40% of new urban installations to mitigate shading losses. NABCEP-certified installer scarcity caps deployment velocity in the US Mountain West.
- Ground-Mounted:Utility-scale fixed-tilt and single-axis tracker configurations anchor procurement volumes, with agrivoltaic dual-use designs qualifying for enhanced USDA Rural Energy for America Program incentives in the Midwest.
- Building-Integrated:Photovoltaic glass and facade-integrated modules serve aesthetic and weight-constrained applications where conventional rack-mounted systems are precluded by structural or zoning restrictions.
- Floating:Reservoir and coastal floating solar reduces land-use conflicts and benefits from evaporative cooling efficiency gains, with deployment concentrating in Japan and Southeast Asia where land scarcity elevates water surface premiums.
Ground-Mounted retains infrastructure scale leadership. Floating emerges as the steepest expansion trajectory on land-use constraint intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as module producers migrate toward jurisdictions with favorable carbon-accounting rules and domestic content incentives.
United States
Utility-scale procurement is accelerating across Texas and Arizona as developers capitalize on the IRA's manufacturing tax credits and domestic content bonuses. FERC Order 2023 mandates advanced inverter functionality for all new interconnections, elevating smart control system specifications. The California-Arizona solar corridor is concentrating bifacial ground-mounted deployment where high-albedo desert surfaces maximize dual-sided yield capture.
Germany
Industrial electrification is driving bifacial-plus-storage retrofits across the Ruhr manufacturing belt as facilities hedge against volatile wholesale electricity pricing. The EU F-Gas Regulation is forcing inverter thermal management redesigns toward CO2-based cooling to maintain efficiency targets. North Rhine-Westphalia anchors manufacturing ecosystems where SMA Solar Technology AG and ABB Ltd maintain integrated production and R&D facilities.
China
Polysilicon supply concentration in Xinjiang is creating carbon-border adjustment exposure under EU Green Deal implementation timelines. MIIT dual carbon goals are accelerating domestic deployment of smart grid-responsive solar farms in western provinces with high irradiance. The Yangtze River Delta manufacturing cluster is vertically integrating from wafer production through inverter assembly to capture full value chain margins.
India
PLI scheme incentives are attracting module assembly investments as the country targets 280 GW solar capacity by 2030. CEA grid codes are mandating smart inverter functionality for all new utility-scale installations to address frequency regulation challenges. Gujarat and Rajasthan are concentrating ground-mounted deployment where land availability and irradiance levels support utility-scale economics.
Australia
Behind-the-meter storage pairing is accelerating in New South Wales and Victoria as time-of-use tariff structures extend solar payback periods without battery self-consumption. The country's national energy regulator is tightening inverter standards to maintain grid stability amid high distributed generation penetration. Floating solar is emerging in Queensland reservoir systems where land-use constraints elevate water surface premiums.
Smart Solar Solutions Market Competitive Environment
Capacity expansion dominates the current landscape as established power electronics manufacturers scale inverter and hybrid system output to capture utility procurement volumes. The vendor base stratifies across three tiers: diversified industrial conglomerates with automation portfolios, pure-play solar specialists with module-level power electronics expertise, and emerging storage-integrated system providers. Strategic archetypes include full-stack platform builders, component-specialist suppliers, and energy-as-a-service aggregators. M&A activity and strategic technology licensing are the primary competitive moves as firms bridge capability gaps in software-defined control layers.
Among German-based industrial conglomerates, Siemens AG and ABB Ltd occupy positions exemplifying the diversified automation-to-energy platform archetype, leveraging existing grid infrastructure relationships to compete in utility-scale control systems. Schneider Electric SE, headquartered in France, represents the distributed energy management specialization vector through its integrated software-hardware platforms. These three companies anchor the premium tier where full-stack capabilities determine procurement authority in European utility tenders.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| General Electric |
| Itron, Inc. |
| SolarEdge Technologies |
| Enphase Energy |
| SMA Solar Technology AG |
| Tesla Energy |
| Others |
Value Chain & Pricing Dynamics
Polysilicon spot indices cascading through wafer and cell contract tiers compress module pricing spreads between premium PERC architectures and commodity-grade alternatives, concentrating margin pressure on non-vertically integrated assemblers serving European carbon-border adjustment jurisdictions.
Pricing Analysis
Distributor margins absorb 8-12 percentage points between factory gate and utility-scale EPC procurement, compressing as direct-to-IPP offtake agreements displace channel intermediaries in Texas and Arizona markets. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61215-certified bifacial glass-glass modules from standard mono-facial units and thin-film building-integrated alternatives. Cost compression in string inverter tiers is intensifying because hybrid storage-integrated architectures capture NEM 3.0 compliance premiums. Residential retrofit installers exhibit highest price sensitivity, while German industrial offtakers prioritize efficiency guarantees over unit economics.
Supply Chain Analysis
Workforce availability constraints in Xinjiang polysilicon purification and Yangtze River Delta wafer slicing operations are elevating labor cost escalators across tier-1 module supply contracts. Manufacturing gravity centers on China, Vietnam, and Malaysia for cell and module assembly, with inverter fabrication concentrating in Germany, China, and the United States. Crystalline silicon ingots, silver metallization paste, and ethylene-vinyl acetate encapsulant films constitute critical input dependencies. Single-source vulnerability in metallization paste sourcing from Japanese chemical suppliers exposes European project timelines to logistics chokepoint risk. Distribution runs through national-scale EPC contractors and regional installer networks rather than traditional electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart solar solutions offer margin expansion through passivated emitter rear contact cell efficiency premiums and software-defined control layer recurring revenue, even as commodity module pricing faces polysilicon cost normalization.
For Market Incumbents: Hedge Xinjiang polysilicon exposure by securing Southeast Asian wafer supply alternatives ahead of EU carbon-border adjustment enforcement. Capture hybrid inverter firmware differentiation through IEEE 1547-2018 certification investment, defending against emerging storage-integrated system providers eroding string inverter market share. Prioritize backward integration into lithium iron phosphate cell supply for California NEM 3.0 compliance bundling.
For New Entrants and Emerging Players: Agrivoltaic EPC contractors in the US Midwest represent an underserved buyer archetype with enhanced USDA Rural Energy for America Program incentive access and limited national-scale developer competition. Floating solar integrators targeting Japanese reservoir systems and Southeast Asian coastal lagoons face lower land-use permitting barriers than ground-mounted alternatives. Lead with satellite-derived irradiance analytics and predictive O&M software to differentiate from hardware-commoditized incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with energy-as-a-service aggregators orchestrating residential battery fleets into Texas ERCOT ancillary services markets, capturing recurring revenue streams absent from equipment-only business models. Long-term viability favors platform builders with integrated software-hardware control layers over component-specialist suppliers facing margin compression. Watch FERC interconnection queue clearance velocity as the inflection signal for utility-scale procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Inverter Certification Investment | IEEE 1547-2018 compliance unlocks California NEM 3.0 and German EEG incentive capture. |
| Energy-as-a-Service Platform Buildout | Third-party PPA structuring transfers technology risk from building owners to specialized asset managers. |
| Agrivoltaic Dual-Use Development | USDA Rural Energy for America Program incentives enhance project finance terms in Midwest grain belt states. |
| Satellite-Derived Analytics Integration | Machine learning applied to irradiance correlation reduces O&M truck rolls for distributed fleet operators. |
| CO2-Based Thermal Management Redesign | EU F-Gas Regulation compliance maintains 99% inverter efficiency targets under stricter refrigerant rules. |
Study Parameters
Multiple input streams — utility interconnection filings, module shipment customs records, and inverter firmware certification databases — were reconciled against primary interviews with IPP project developers, EPC procurement directors, and grid operator planning officers. Secondary validation drew from FERC Order 2023 implementation guidance, EIA generation capacity reports, IEA renewable investment tracking, and CEA grid code notifications. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment were triangulated to constrain forecast variance.
Historical deployment trajectories were cross-referenced against panel input from utility procurement officers and commercial installer network managers to anchor growth assumptions. Segmentation modeling spanned product type, technology architecture, application vertical, and installation topology across the projection horizon. CAGRs were derived from capacity-weighted average buildout rates adjusted for interconnection queue clearance assumptions and tariff restructuring impacts. Forecast inputs incorporated bifacial albedo yield modeling, battery duration compliance mandates, and fleet-level monitoring software penetration curves.
Underlying measurement precision varies by segment; utility-scale and residential application data carry tighter precision than emerging floating solar and agrivoltaic categories with limited operational track records. Forecasts embed assumptions regarding IRA domestic content bonus continuity, EU carbon-border adjustment implementation sequencing, and polysilicon supply geographic diversification timelines. Material deviation in FERC interconnection reform, Xinjiang supply chain sanctions, or NEM 3.0 export tariff adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Solar Shed Light Market