
 Global Solar Module for Electric Vehicle Market | 2026-2036
Global Solar Module for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Module for Electric Vehicle Market Intelligence
Over-the-air software updates for optimizing energy management is shifting the value proposition from hardware alone to integrated performance services. Automakers like Volkswagen are exploring these systems to extend vehicle range and reduce grid dependency. Specialized firms such as Sono Motors focus exclusively on solar-electric vehicle development, pioneering new integration methods. Meanwhile, Maxeon Solar Technologies leverages its high-efficiency cell expertise to supply the demanding automotive sector.
A solar module for electric vehicles is a photovoltaic panel engineered for direct integration into vehicle body panels like roofs and hoods. These modules often utilize lightweight, durable materials and conformal designs to match vehicle contours, providing auxiliary power and supplementary range-extending charging. Monocrystalline product types currently dominate due to superior energy conversion efficiency. However, thin-film technologies are gaining traction for applications on commercial vehicles, where their flexibility and lower weight are critical advantages.
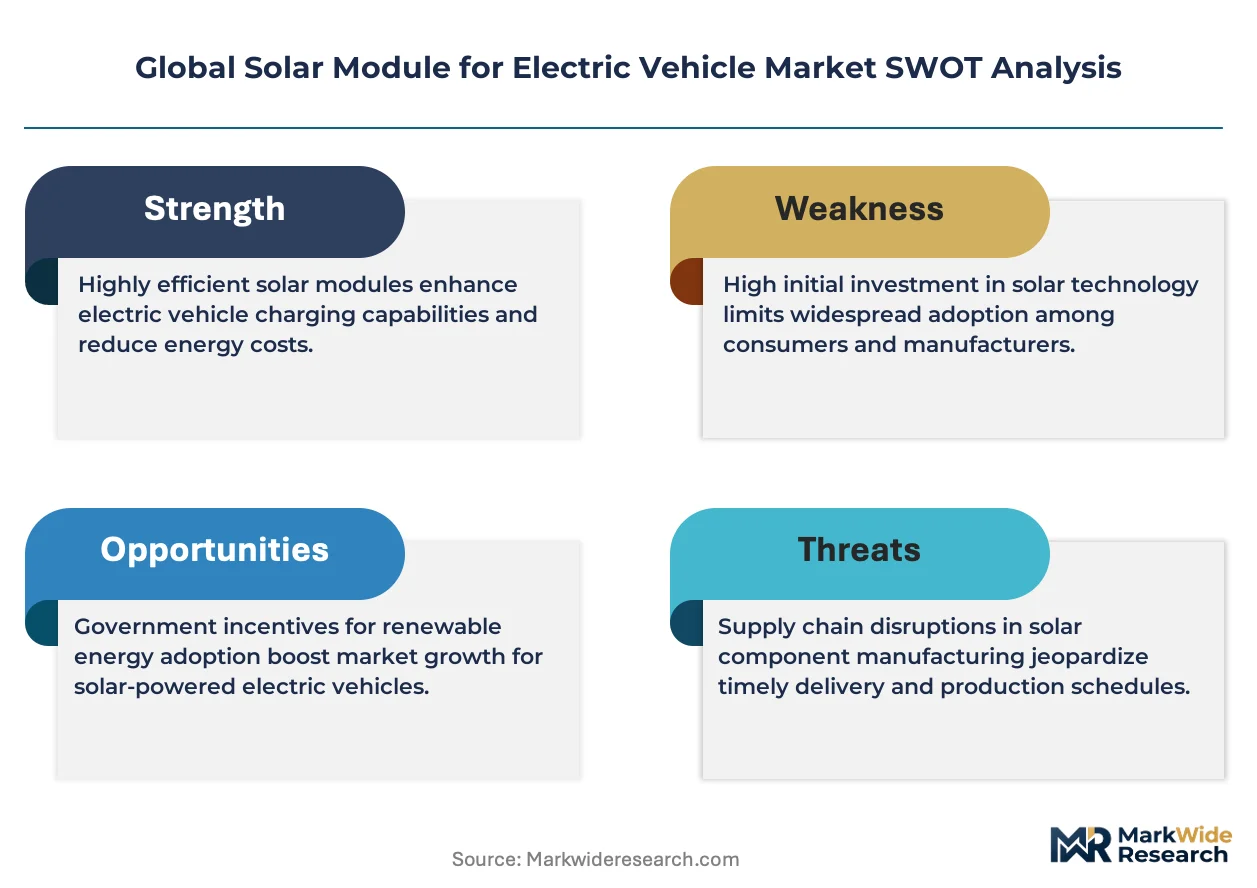
Regulatory frameworks, including the US EPA's emissions targets and the EU Green Deal, create a favorable environment by incentivizing zero-emission transportation. In China, the national 'dual carbon goals' further accelerate the push for renewable energy integration in the automotive sector. The key decision for vehicle manufacturers now centers on balancing the high initial cost of advanced photovoltaic integration against the long-term benefits of extended range and reduced grid reliance.
Market Dynamics
The central dynamic shaping this market is the convergence of automotive design with distributed energy generation. This is driven by regulatory pressure for zero-emission transport and the strategic need for automakers to differentiate electric vehicles by extending range and reducing dependency on fixed charging infrastructure.
Growth Catalysts
- Regulatory Incentives:Policies like the EU Green Deal and US EPA emissions targets create strong financial and compliance incentives for automakers to adopt technologies that reduce the carbon footprint of their fleets, including vehicle-integrated photovoltaics.
- Monocrystalline Cell Efficiency:Continuous improvements in the energy conversion efficiency of monocrystalline silicon cells make them increasingly viable for the limited surface area available on vehicles, maximizing power generation and range extension benefits.
- Commercial Fleet Adoption:The commercial vehicle sector, particularly for last-mile delivery and refrigerated transport, is adopting solar modules to power auxiliary systems, reduce fuel consumption from idling, and extend the operational range of electric vans.
Market Restraints
- High Integration Cost:The significant upfront cost associated with designing, manufacturing, and integrating custom, conformal solar modules into vehicle body panels remains a primary barrier to adoption in mass-market passenger cars.
- Performance Limitations:Photovoltaic cell efficiency is susceptible to degradation from high temperatures on vehicle surfaces and inconsistent power output due to partial shading from buildings or trees, impacting real-world energy generation.
- Specialized Supply Chain:The market depends on a limited number of suppliers capable of producing durable, lightweight, and high-efficiency solar cells that meet stringent automotive-grade quality and safety standards, creating potential supply bottlenecks.
Strategic Opportunities
- Aftermarket and Retrofit Kits:A significant opportunity exists in developing standardized solar module kits for the aftermarket, allowing owners of existing electric and conventional commercial vehicles to retrofit their fleets for auxiliary power and range benefits.
- Thin-Film on Polymer Panels:The convergence of flexible thin-film solar technologies with advanced lightweight polymer and composite body panels presents an opportunity to create highly integrated, seamless, and efficient vehicle surfaces.
- Expansion into Niche Mobility:There is untapped potential in integrating solar modules into other mobility applications such as electric buses, recreational vehicles, and agricultural machinery, where large surface areas and auxiliary power needs create a strong use case.
Industry Challenges
- Integration and Aerodynamics:Automotive engineers face the complex challenge of integrating solar panels onto curved vehicle bodies without compromising vehicle aerodynamics, crash safety standards, or overall design aesthetics.
- Lack of Standardization:The absence of universally accepted industry standards for vehicle-integrated photovoltaic (VIPV) performance, safety, and durability testing creates uncertainty for OEMs and complicates component sourcing.
- Long-Term Durability:Ensuring modules can withstand constant vibration, impact from road debris, and extreme weather conditions over a vehicle's lifespan poses a significant engineering and materials science challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Module for Electric Vehicle Market |
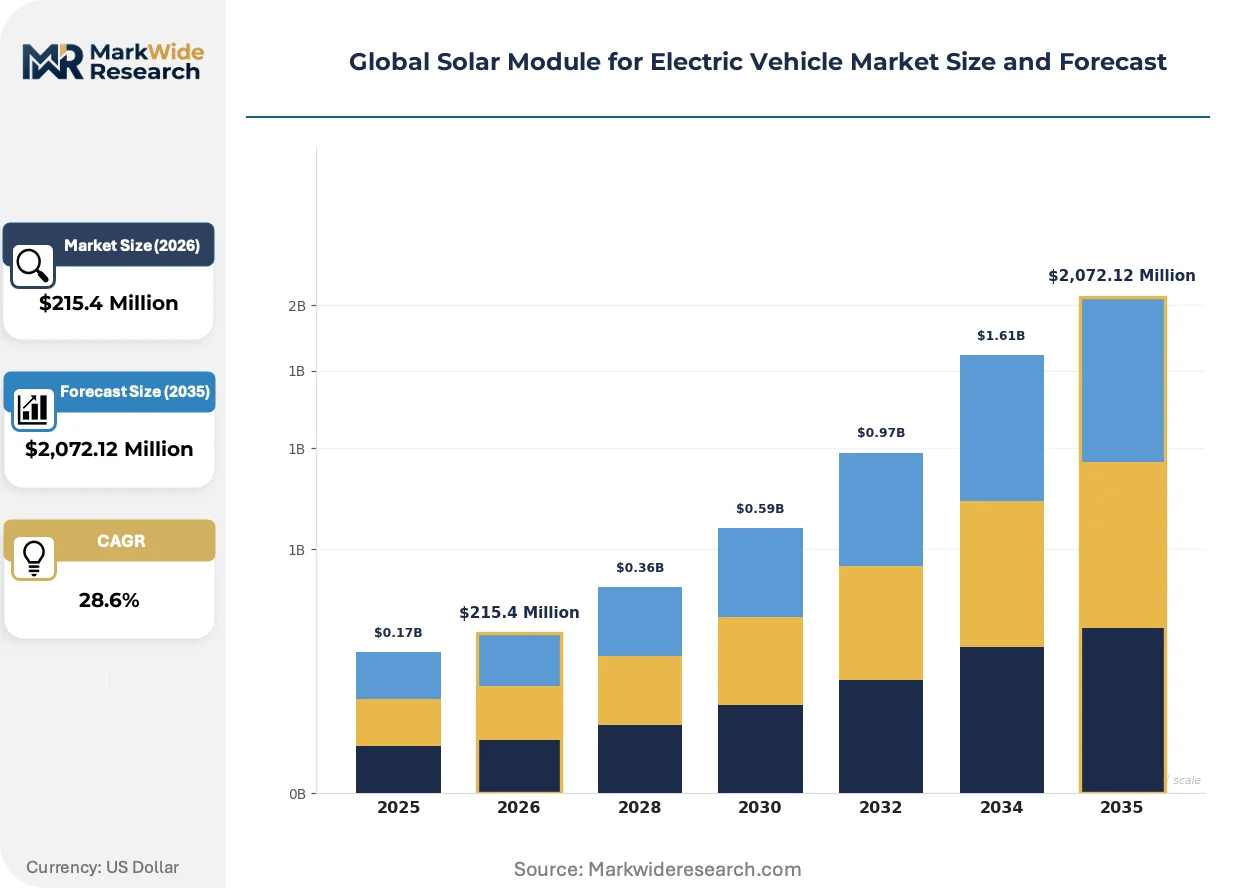
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $2,072.12 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Technology: Photovoltaic Cells, Perovskite, Organic, Concentrated Solar Power Application: Passenger Vehicles, Commercial Vehicles, Fleet Vehicles, Specialty Vehicles End User: Vehicle Manufacturers, Electric Mobility Providers, Charging Infrastructure Firms, Renewable Energy Integrators |
| Companies Covered | Volkswagen, JA Solar, Trina Solar, Jinko Solar, Canadian Solar, Sono Motors, Maxeon Solar Technologies, LONGI Solar, SunPower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Module for Electric Vehicle Market Strategic Shifts & Innovations
Performance optimization is shifting the market's focus from hardware components to integrated, software-managed energy ecosystems. Automakers are now evaluating solar integration not just as an add-on, but as a core element of the vehicle's energy management strategy to enhance range and grid independence.
Conformal thin-film solar technology provides a lightweight and flexible alternative to rigid crystalline panels. Commercial vehicle OEMs are the primary adopters, applying these films to the large, curved surfaces of truck cabs and delivery vans. This technology is electrifying auxiliary systems like liftgates and refrigeration units, reducing fuel use from engine idling and extending the daily operational window for EV fleets.
China's national 'dual carbon goals' are accelerating the development of vehicle-integrated solar solutions. This top-down policy framework directly incentivizes domestic automakers to incorporate renewable energy generation into new vehicle designs to meet stringent decarbonization targets. The passenger and commercial EV segments within China are responding by forming new technology partnerships to pioneer novel integration methods.
A notable behavioral shift is emerging among fleet managers and consumers, who increasingly prioritize total cost of ownership and energy autonomy over initial vehicle price. This trend disrupts the conventional reliance on grid-only charging, creating a pull for vehicles with self-generating capabilities. This is most visible in European automotive clusters, particularly in Germany, where high electricity costs amplify the value proposition of supplementary solar charging.
Global Solar Module for Electric Vehicle Market Segmentation
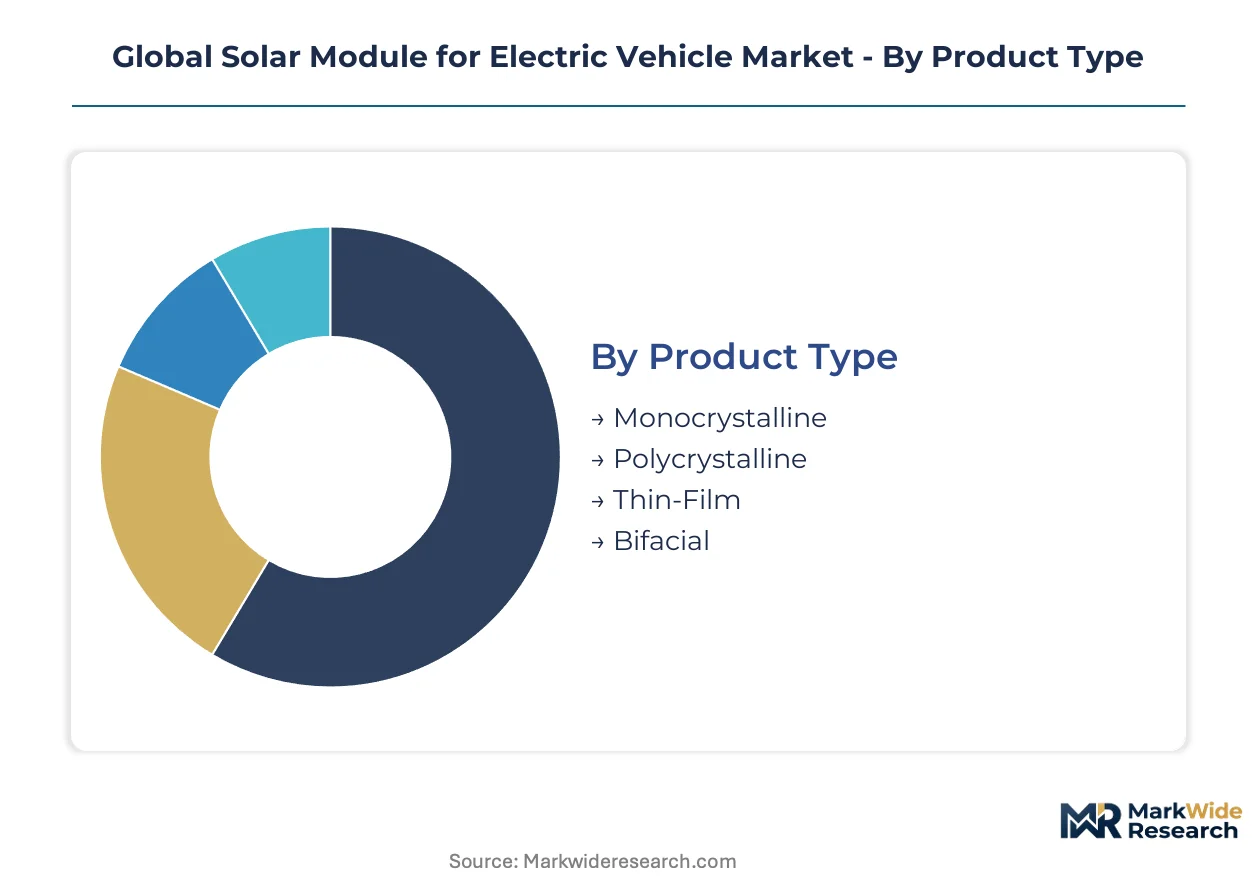
The Global Solar Module for Electric Vehicle Market is segmented to reflect the diverse technological approaches, vehicle applications, and end-user requirements driving its expansion. Understanding these distinct segments helps manufacturers and integrators tailor solutions that meet specific performance criteria and market demands. This segmentation provides clarity on where innovation is concentrating and where commercial opportunities are most pronounced.
Product Type:
The selection of solar module product type often differentiates based on efficiency requirements and vehicle integration flexibility.
- Monocrystalline:These modules utilize highly pure silicon crystals, offering superior energy conversion efficiency and a compact footprint. Demand concentrates in premium passenger vehicles and high-performance commercial applications where maximizing power generation from limited surface area is critical.
- Thin-Film:Characterized by their flexibility, low weight, and ability to conform to curved surfaces, thin-film modules are suitable for integration into complex vehicle body panels. Adoption is accelerating in commercial vehicles, particularly for large truck roofs and delivery van bodies in Europe and China.
- Polycrystalline:Composed of multiple silicon crystals, polycrystalline modules offer a more cost-effective alternative to monocrystalline, though with slightly lower efficiency. These modules find use in auxiliary power applications where surface area is less constrained and initial cost is a primary consideration.
- Bifacial:These panels capture sunlight from both their front and rear surfaces, potentially increasing energy yield in certain configurations. Their application in vehicles is currently niche, focusing on specialized designs that can leverage reflected light.
Monocrystalline leads volumes today; Thin-Film is gaining share fastest.
Technology:
Cost-effectiveness and power generation capabilities drive the choice of underlying solar technology.
- Photovoltaic Cells:This foundational technology converts light directly into electricity using semiconductor materials like silicon. These cells form the core of all vehicle-integrated solar modules, with continuous improvements in efficiency and durability.
- Perovskite:An emerging class of materials, perovskite cells offer high theoretical efficiencies and can be manufactured using low-cost, solution-based processes. Research and development efforts in China and Germany are exploring their potential for next-generation vehicle integration due to their tunable properties.
- Organic:Organic photovoltaic (OPV) cells are lightweight, flexible, and transparent, making them ideal for seamless integration into vehicle windows or panoramic roofs. Their lower efficiency compared to silicon limits their primary application to auxiliary power and aesthetic integration.
- Concentrated Solar Power:This technology uses mirrors or lenses to focus a large area of sunlight onto a small area of photovoltaic cells. Its application in mobile vehicles is severely limited by the need for direct sunlight tracking and bulky optical components.
Photovoltaic Cells form the foundational technology; Perovskite is expanding most quickly.
Application:
The specific vehicle application dictates the optimal balance between power output, weight, and aesthetic integration.
- Commercial Vehicles:This segment includes vans, trucks, and buses, where solar modules power auxiliary systems, reduce engine idling, and extend range for last-mile delivery fleets. European companies are actively integrating solar for refrigerated transport and telematics systems.
- Passenger Vehicles:Integrating solar panels into passenger cars provides supplementary charging for the main battery and powers cabin electronics, extending range and reducing grid dependency. Automakers like Volkswagen are exploring these systems in their EV lineups.
- Fleet Vehicles:Encompassing various vehicle types managed by organizations, fleet applications benefit from solar integration for operational efficiency and reduced fuel costs. Companies in the US are retrofitting existing fleets to enhance sustainability.
- Specialty Vehicles:This category includes recreational vehicles, agricultural machinery, and emergency vehicles, which often require off-grid power for extended periods. Large surface areas on these vehicles make solar integration highly effective for auxiliary power needs.
Commercial Vehicles currently represent the largest application; Specialty Vehicles show the steepest expansion trajectory.
End User:
The role and business model of the end-user determine the scale and nature of solar module procurement and integration.
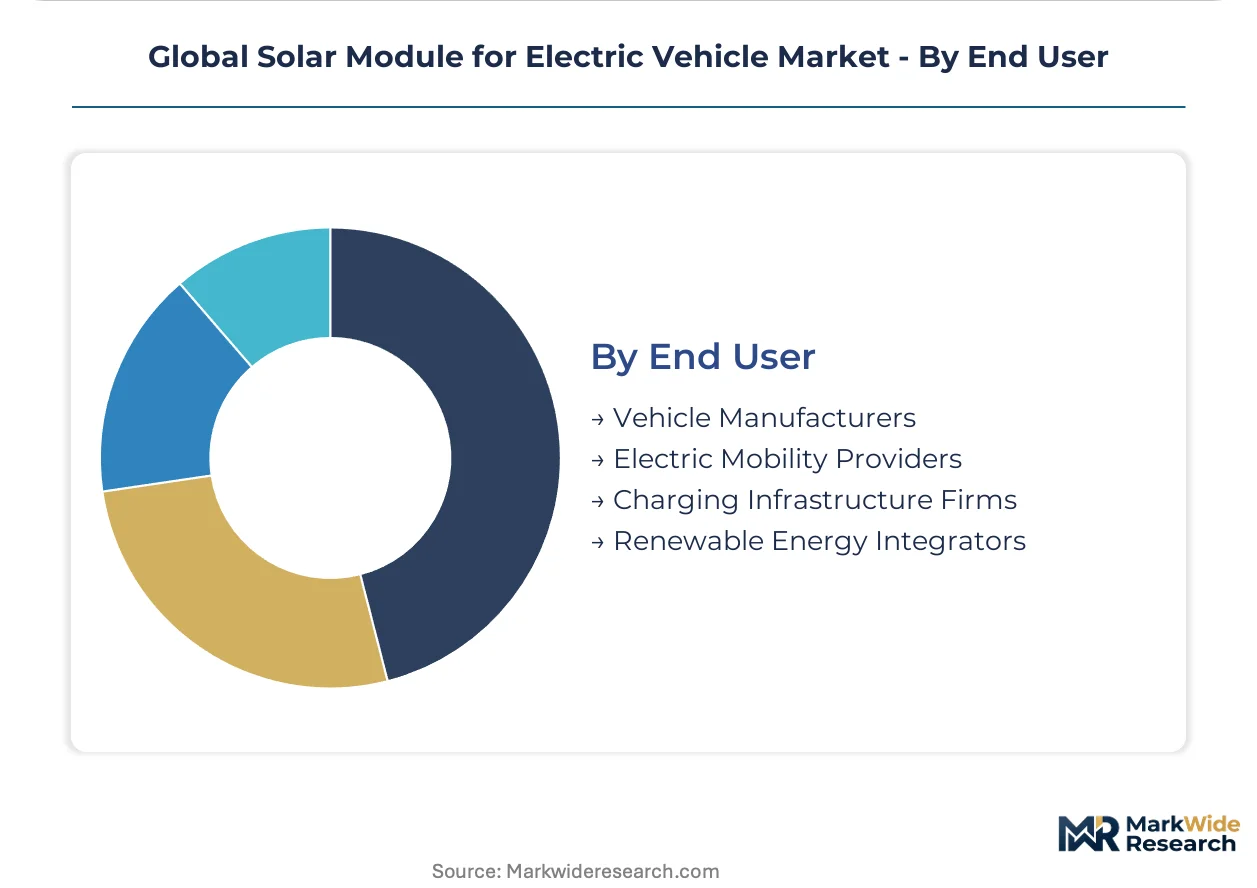
- Vehicle Manufacturers:These companies design, produce, and integrate solar modules directly into new electric vehicles during the manufacturing process. They collaborate with specialized suppliers like Maxeon Solar Technologies for high-efficiency cells.
- Electric Mobility Providers:Firms offering shared mobility services, electric vehicle subscriptions, or fleet management solutions integrate solar to enhance vehicle autonomy and reduce charging infrastructure reliance. They focus on total cost of ownership benefits.
- Charging Infrastructure Firms:While primarily focused on grid-connected charging, some firms explore solar integration to offer partially off-grid or enhanced charging solutions, particularly in remote locations. This extends their service reach.
- Renewable Energy Integrators:Companies specializing in renewable energy solutions, including solar, are adapting their expertise to vehicle-integrated photovoltaics. They focus on optimizing energy management and system efficiency for automotive applications.
Vehicle Manufacturers drive the bulk of demand; Renewable Energy Integrators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Germany's automotive industry drives innovation in premium solar EV integration, China's national policies accelerate mass-market adoption. European automotive clusters are a focal point for demand, particularly for commercial vehicle applications. This global market expansion is supported by diverse regulatory frameworks and technological advancements.
Germany
Demand for integrated solar modules stems from the need to extend EV range and reduce grid dependency in passenger vehicles. The EU Green Deal incentivizes zero-emission transport solutions for German automakers. Stuttgart's automotive cluster focuses on advanced integration methods for high-efficiency monocrystalline cells. Maxeon Solar Technologies collaborates with manufacturers in this region.
China
China's market for solar EV modules is propelled by stringent decarbonization targets and the expansion of electric commercial fleets. The national 'dual carbon goals' provide significant impetus for renewable energy integration in the automotive sector. Shanghai's EV manufacturing hubs are pioneering new integration methods for both passenger and commercial vehicles. This region sees rapid adoption of thin-film technologies.
United States
Commercial fleet operators in the United States prioritize solar modules for auxiliary power and reduced fuel consumption from idling. The US EPA's emissions targets create a favorable environment for vehicle-integrated photovoltaics. Detroit's automotive industry explores solar solutions to enhance total cost of ownership for fleet vehicles. Aftermarket retrofit kits also find significant interest here.
Japan
Japanese automakers are exploring solar integration to differentiate electric vehicles and enhance energy autonomy for consumers. METI initiatives support research into lightweight, high-efficiency solar cells for automotive applications. Toyota City's R&D centers focus on seamless integration into vehicle body panels without compromising aerodynamics. This includes advanced thin-film development.
South Korea
The South Korean market sees demand for solar modules driven by smart city initiatives and the need for extended range in urban EVs. Government policies encourage the development of sustainable mobility solutions and EV infrastructure. Seoul's technology firms are collaborating with automotive OEMs on advanced energy management systems for solar-equipped vehicles. This includes organic photovoltaic research.
Global Solar Module for Electric Vehicle Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the solar module for EV market. The market exhibits a tiered structure, with established solar cell manufacturers supplying automotive-grade components. Key strategic archetypes include high-efficiency cell producers, integrated vehicle solution providers, and flexible thin-film innovators. Strategic partnerships between module suppliers and automakers are a dominant competitive move, alongside continuous R&D investment in material science.
Within the integrated vehicle solution provider archetype, Sono Motors exemplifies a company focused exclusively on solar-electric vehicle development, pioneering new integration methods. Maxeon Solar Technologies represents a high-efficiency cell producer, leveraging its expertise to supply demanding automotive sector applications. JA Solar, a major solar panel manufacturer, also occupies a position as a foundational cell supplier to this evolving market. These entities anchor distinct segments of the supply chain, from specialized vehicle design to core component manufacturing, reflecting diverse approaches to market entry and value capture.
| Leading Market Players |
|---|
| Volkswagen |
| JA Solar |
| Trina Solar |
| Jinko Solar |
| Canadian Solar |
| Sono Motors |
| Maxeon Solar Technologies |
| LONGI Solar |
| SunPower |
| Others |
Cost & Logistics Intelligence
Skilled automotive engineers in Germany drive premium segment pricing, while high-volume cell production in China enables lower-cost options across the market. This dual dynamic creates distinct pricing tiers for vehicle-integrated solar modules.
Pricing Analysis
Capacity additions in China are reshaping price floors for thin-film and polycrystalline modules, intensifying competition. The market primarily operates on a per-unit transactional model, with long-term contracts for original equipment manufacturers. Price differentiation stems from energy conversion efficiency, automotive-grade certification, and customization levels for conformal integration. Pricing pressure stems from increasing module production capacity in Asia. Commercial fleet operators exhibit the highest price sensitivity, while premium passenger vehicle manufacturers prioritize performance over initial cost.
Supply Chain Analysis
Stringent automotive-grade certifications, such as IATF 16949, act as significant gating factors for component suppliers. The supply chain draws heavily from China for cell production and thin-film manufacturing, with Germany focusing on premium module integration and advanced R&D. Key raw material dependencies include high-purity silicon, specialized polymers, and silver pastes. Single-source vulnerability for critical automotive-grade components represents a structural risk. Distribution runs through direct sales to vehicle manufacturers, specialized automotive component distributors, and aftermarket kit providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, driven by a demand shift toward higher efficiency monocrystalline cells for maximum range extension in passenger electric vehicles.
For Market Incumbents:
Acquire specialized thin-film manufacturing capabilities or advanced energy management software firms. Incumbents should invest in proprietary conformal integration techniques to maintain differentiation against emerging low-cost thin-film solutions from Chinese manufacturers. Establishing long-term supply agreements for high-efficiency cells will mitigate supply chain risks. Further R&D in perovskite technology or vertical integration into module assembly can also strengthen market position.
For New Entrants and Emerging Players:
Begin with niche mobility applications, such as recreational vehicles or agricultural machinery, where large surface areas create strong use cases. The commercial vehicle aftermarket in the United States represents a highly penetrable segment. New entrants can gain traction by offering flexible, lightweight thin-film solutions with simplified installation processes, focusing on auxiliary power benefits and reduced fuel consumption from idling engines.
For Investors and Strategic Acquirers:
Valuations sit cheapest among specialized component suppliers with strong intellectual property in flexible photovoltaic materials. The market exhibits long-term growth potential driven by decarbonization targets and electric vehicle range anxiety. Acquisition targets should include companies with proven automotive-grade integration expertise or next-generation cell technology like perovskite. A significant signal to watch is major OEM announcements of solar as standard equipment in new electric vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop advanced conformal integration techniques. | This enhances aesthetic appeal and aerodynamic performance for passenger vehicle applications. |
| Secure long-term supply for high-efficiency monocrystalline cells. | Ensuring material availability supports consistent production for premium electric vehicle models. |
| Expand thin-film production capacity in China. | This reduces manufacturing costs and increases market penetration for commercial vehicle applications. |
| Form strategic partnerships for energy management software. | Optimizing power flow maximizes range extension and overall vehicle efficiency for OEMs. |
| Target aftermarket solutions for commercial vehicle fleets. | This creates new revenue streams by enabling retrofit options for existing electric and conventional vehicles. |
Research Approach
Multiple input streams — primary interviews, proprietary databases, and industry reports — were reconciled to construct a comprehensive market view. The analysis combined insights from automotive engineers, solar module manufacturers, fleet managers, and regulatory experts. Secondary data sources included OEM financial reports, national energy agency publications, and technology patent databases, all triangulated with bottom-up and top-down approaches.
Data stream reconciliation informed the analytical framework, enabling quantitative analysis across the modeling period. Segmentation dimensions modeled included product type, technology, application, end-user, and regional automotive production clusters. Compound annual growth rates were calculated based on historical trends and projected market dynamics. Industry-specific forecast inputs included electric vehicle production forecasts and solar cell efficiency advancements.
Several conditions sit outside the modeled scope, including short-term economic volatility and unforeseen geopolitical events. Forecasts reflect assumptions regarding technological development and market adoption rates. A model refresh is warranted upon material change in global electric vehicle adoption rates or regulatory incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Smart Solar Tracker Market