
 3D Printed Solar Energy Trees Market | 2026-2036
3D Printed Solar Energy Trees Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Solar Energy Trees Market Analysis
ISO 9001 quality management certification is rotating as a baseline qualification for suppliers bidding on municipal solar tree contracts. SolarBotanic leverages proprietary biomimetic designs to anchor its position in European urban deployments. Envision Solar International sustains channel control through direct relationships with North American city planners. VTT Technical Research Centre of Finland differentiates via deep R&D partnerships with Nordic energy agencies.
3D printed solar energy trees integrate photovoltaic cells within additively manufactured trunk-and-branch structures that mimic natural tree geometry for optimized sun tracking and surface exposure. These systems typically employ conductive polymer composites or metal-polymer hybrid filaments deposited through fused deposition modeling or selective laser sintering processes, producing integrated wiring channels and modular joint assemblies that support field-assembly without heavy equipment. Fixed solar trees dominate current municipal procurement due to lower installed cost, while modular solar trees represent the fastest-expanding category as cities demand scalable, redeployable assets for temporary installations and event infrastructure. Hybrid solar trees command premium positioning by combining energy generation with environmental sensors and Wi-Fi relay functions, concentrating margin pools in smart-city integrated deployments.
Federal Energy Regulatory Commission grid interconnection standards and EPA renewable energy incentives shape product design requirements and project finance structures for US-based deployments, while EU Green Deal carbon-neutrality targets and CE marking directives drive material traceability and lifecycle assessment protocols for European suppliers. Municipal procurement officers and technology integrators must monitor evolving building-integrated photovoltaic codes and distributed generation tariff structures to anticipate which product configurations will secure long-term contract flows.
Market Dynamics
Conductive polymer formulation breakthroughs are compressing production cycles for integrated photovoltaic structures, forcing municipal procurement officers to rewrite technical specifications mid-contract and eroding first-mover advantages held by incumbent additive manufacturing suppliers.
Growth Catalysts
- EU Green Deal carbon-neutrality targets:Municipal governments in Germany, France, and the Netherlands face binding decarbonization deadlines that mandate renewable infrastructure deployment in public spaces, creating guaranteed offtake for urban solar assets.
- Conductive polymer composites:New filament formulations with embedded silver nanowire networks enable single-pass printing of structural and electrical elements, eliminating post-assembly wiring and reducing field labor requirements by half.
- Fused deposition modeling scalability:Print farm configurations using standardized gantry systems allow regional production hubs to serve multiple municipalities without intercontinental shipping of finished structures.
Market Restraints
- Silver and copper price volatility:Conductive ink formulations depend on precious metal feedstocks whose commodity price swings directly compress gross margins for finished solar tree systems.
- Photovoltaic cell supply concentration:Crystalline silicon wafer production clusters in China create single-point vulnerability for European and North American 3D printing integrators facing tariff and logistics risk.
- CE marking directive complexity:Multi-component certification requirements for combined structural-electrical systems extend approval timelines and require specialized testing facilities unavailable in smaller markets.
Strategic Opportunities
- India smart city mission:Urban renewal programs in Bangalore, Hyderabad, and Pune specify integrated street furniture with embedded digital infrastructure, opening procurement channels for hybrid solar tree configurations.
- Building-integrated photovoltaic code convergence:Harmonization of electrical and structural standards across German federal states is reducing project-specific engineering overhead and enabling catalog-based municipal purchasing.
- Selective laser sintering with recycled polymers:Post-industrial nylon powder recovery systems paired with solar-grade conductive coatings are creating closed-loop production models eligible for circular economy procurement preferences.
Industry Challenges
- Multi-physics simulation expertise:Concurrent modeling of thermal, electrical, and mechanical performance in organic geometries requires computational design talent scarce in traditional civil engineering programs.
- ISO 9001 certification timelines:Municipal contract eligibility now demands documented quality management systems that take 14-18 months to implement for additive manufacturing specialists transitioning from prototyping services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Solar Energy Trees Market |
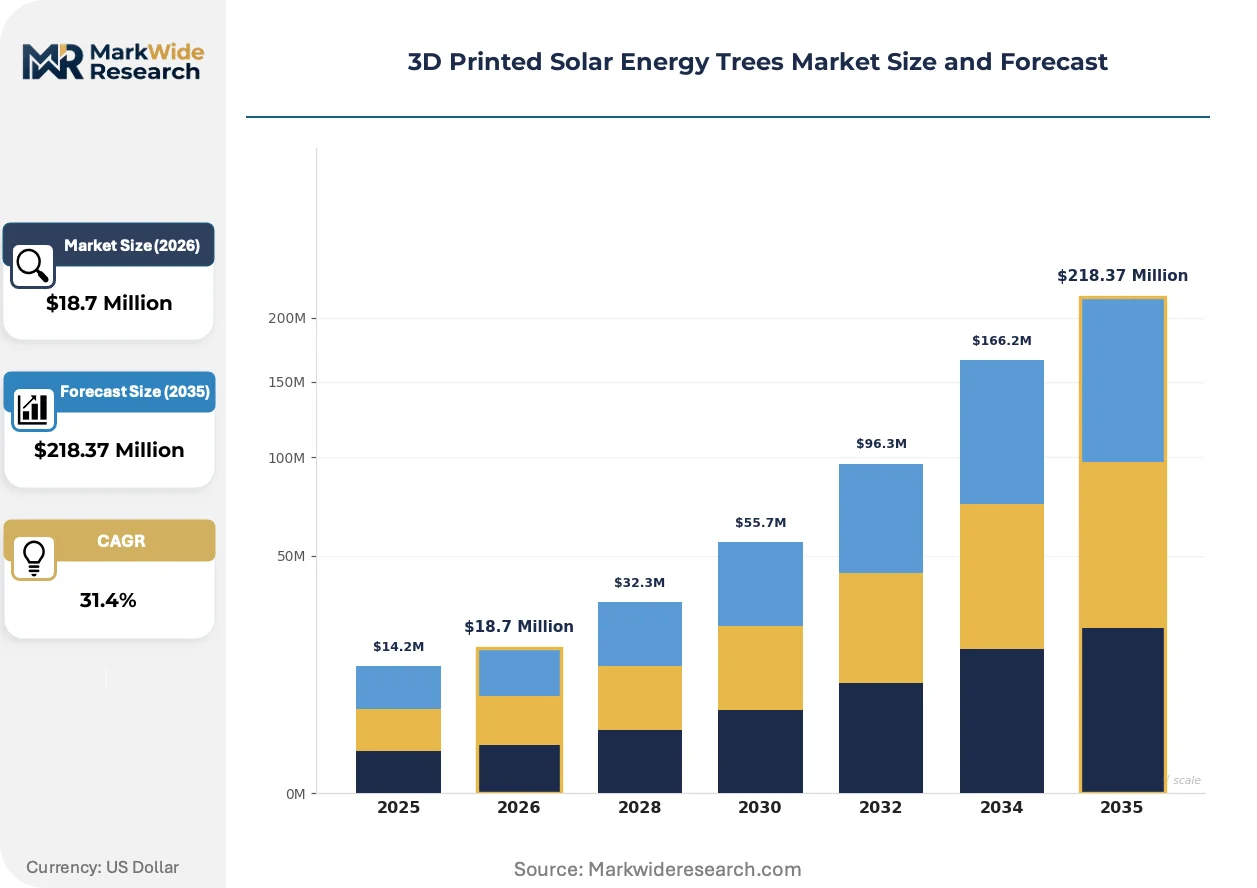
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic Cells, Organic Photovoltaics, Dye-Sensitized Cells, Thin-Film Solar Cells Product Type: Fixed Solar Trees, Adjustable Solar Trees, Modular Solar Trees, Hybrid Solar Trees End User: Residential, Commercial, Industrial, Government Application: Energy Generation, Environmental Conservation, Urban Infrastructure, Aesthetic Installations |
| Companies Covered | SolarBotanic, Envision Solar International, Solar Impulse Industry Co. Ltd, VTT Technical Research Centre of Finland, SolarBotanic Trees, RAW Solar, 3D Solar Tree, Arka360, Green Venture Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Solar Energy Trees Market Emerging Trajectories
Photovoltaic integration methods and procurement specifications are diverging along regional regulatory lines, with European municipalities prioritizing lifecycle assessment transparency while Asian urban planners emphasize rapid deployment modularity.
Embedded micro-inverter architectures within printed branch nodes are miniaturizing power electronics to the point where individual leaf clusters operate as independent generation units. German municipal utilities now specify this topology for shade-tolerant performance in dense urban canyons. The technology is miniaturizing balance-of-system components and compressing installation footprints to sidewalk-scale footprints previously impractical.
EU Green Deal lifecycle assessment protocols now mandate material traceability from polymer pellet to field installation. Suppliers must document carbon intensity per kilogram of printed structure and submit to third-party verification. Nordic energy agencies have tightened these requirements fastest, disqualifying filament sources without renewable electricity certificates.
Swedish and Danish procurement officers now bundle solar tree deployment with 15-year energy service contracts rather than capital purchase agreements. Equipment vendors assume performance risk and retain ownership, shifting municipal budgeting from infrastructure accounts to operational expenditure lines. This restructuring concentrates contract awards among firms with balance sheet capacity to carry long-dated receivables.
3D Printed Solar Energy Trees Market Segmentation
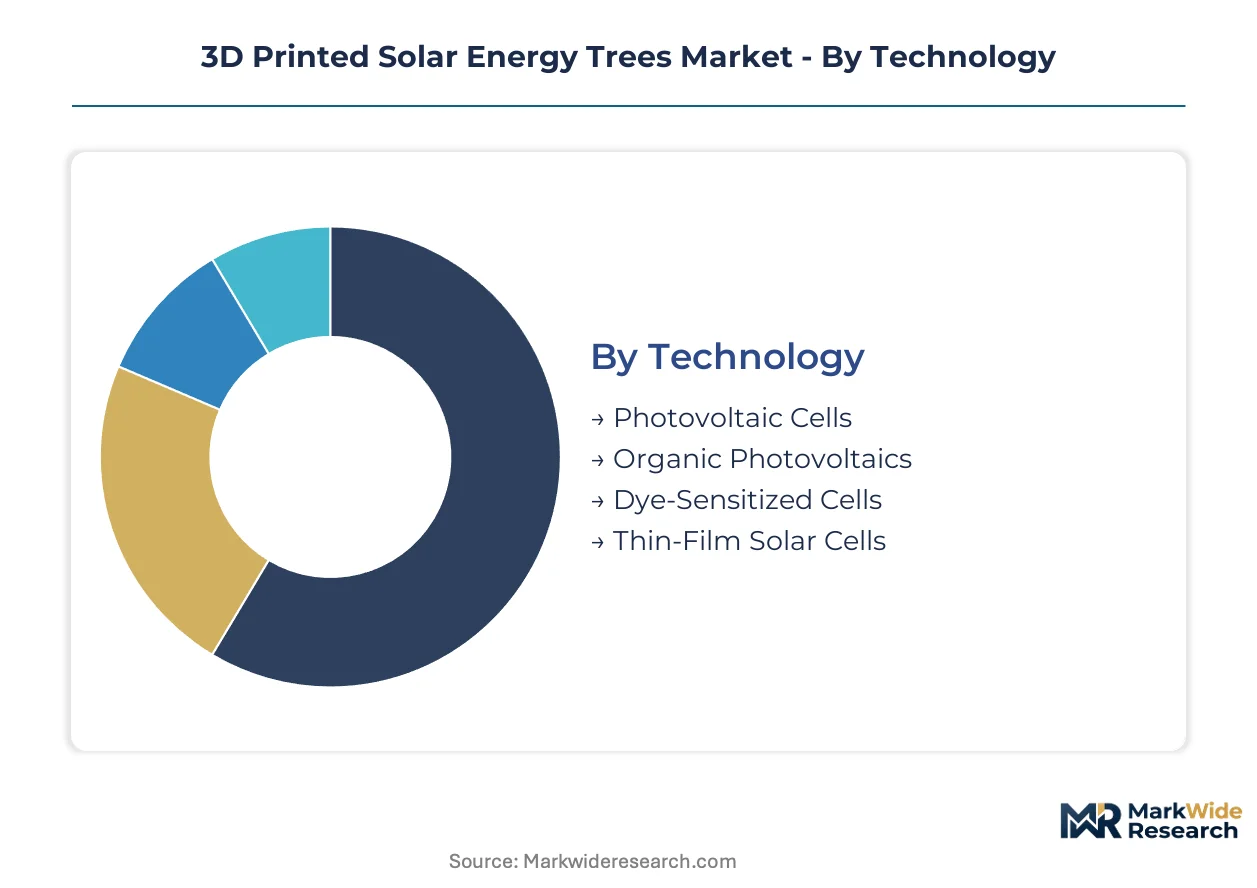
Technology choices in 3D printed solar energy trees determine conductive filament compatibility, print resolution requirements, and municipal procurement eligibility. Product configurations diverge sharply between permanent urban infrastructure and temporary deployable assets. End-user economics and application specifications further stratify vendor positioning across contract channels.
Technology:
Organic photovoltaics and dye-sensitized architectures face intensifying substitution pressure from crystalline silicon alternatives as municipal buyers prioritize proven degradation curves and bankable performance warranties.
- Photovoltaic Cells:Crystalline silicon wafers embedded in printed branch channels deliver standardized efficiency metrics that satisfy German municipal utility procurement specifications. Demand concentrates in Bavarian and Baden-Württemberg urban renewal contracts where CE marking compliance and documented degradation rates outweigh upfront cost considerations.
- Organic Photovoltaics:Polymer-fullerene blends deposited through roll-to-roll integration with fused deposition modeling enable curved surface conformality impossible with rigid cells. French municipal parks departments specify these systems for heritage-sensitive installations where visual intrusion restrictions exclude conventional panel geometries.
- Dye-Sensitized Cells:Titanium dioxide nanoparticle electrodes printed with organic dye sensitizers tolerate partial shading without catastrophic performance loss.
- Thin-Film Solar Cells:Cadmium telluride and copper indium gallium selenide layers sputtered onto printed substrates suit Nordic low-light conditions.
Photovoltaic cells retain volume leadership; organic photovoltaics hold the steepest expansion curve.
Product Type:
Cost tier stratification separates capital-intensive permanent installations from operational-expenditure-friendly deployable systems, reshaping vendor balance sheet requirements and contract structuring.
- Fixed Solar Trees:Monolithic trunk-and-canopy structures printed as single assemblies dominate current municipal procurement due to lowest installed cost per kilowatt. German cities including Munich and Hamburg specify fixed configurations for sidewalk-scale energy generation where foundation permanence matches 25-year infrastructure planning horizons.
- Modular Solar Trees:Interlocking branch segments and tool-free joint systems enable rapid assembly without heavy equipment. Danish municipal utilities favor these for festival and event infrastructure where redeployment cycles compress payback period calculations and shift procurement toward short-term lease structures.
- Adjustable Solar Trees:Motorized azimuth and tilt mechanisms optimize seasonal sun angles through printed gear housings.
- Hybrid Solar Trees:Integrated environmental sensors, Wi-Fi relays, and air quality monitors command premium positioning in smart-city procurement.
Fixed solar trees capture the largest contract volume; modular solar trees are expanding most quickly as temporary deployment models gain municipal acceptance.
End User:
Customer-type concentration in government channels reflects municipal sustainability mandates, while commercial buyers prioritize brand visibility and energy cost hedging over pure generation economics.
- Government:Municipal procurement officers in Germany, the Netherlands, and Denmark drive guaranteed offtake through binding decarbonization deadlines and EU Green Deal compliance requirements. Specifications emphasize lifecycle assessment transparency, material traceability, and ISO 9001 quality certification as baseline eligibility filters.
- Commercial:Corporate campus operators and retail developers deploy solar trees as visible sustainability commitments that support ESG reporting and customer-facing brand positioning.
- Residential:Single-property installations remain limited by per-unit cost and zoning restrictions.
- Industrial:Manufacturing facilities with flat-roof constraints and high consumption profiles represent emerging demand.
Government end users dominate contract flow; commercial installations are gaining share fastest as corporate ESG commitments harden into capital allocation priorities.
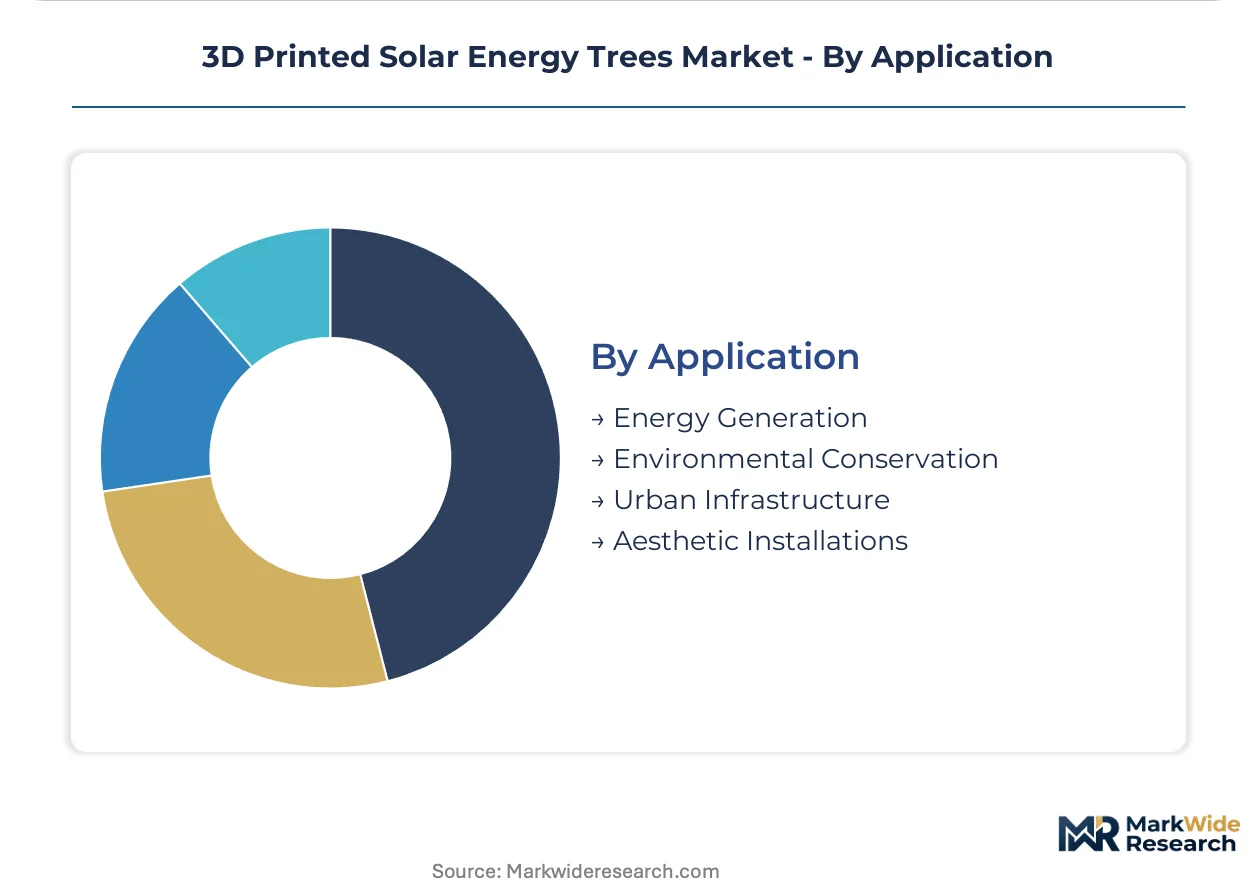
Application:
Application maturity diverges between proven energy generation deployments and nascent aesthetic installations where design premiums remain unproven at scale.
- Energy Generation:Grid-interconnected systems feeding municipal utilities or behind-the-meter commercial loads constitute the functional core of current deployments. German federal states harmonizing building-integrated photovoltaic codes enable catalog-based purchasing that reduces project-specific engineering overhead.
- Urban Infrastructure:Street furniture integration with lighting, charging stations, and digital wayfinding concentrates in Indian smart city missions and Nordic pedestrian zone renewals.
- Environmental Conservation:Biodiversity monitoring sensors and pollinator habitat structures printed into branch geometries serve ecological restoration projects.
- Aesthetic Installations:Sculptural forms prioritizing visual impact over generation efficiency occupy museum and plaza commissions.
Energy generation applications anchor procurement volume; urban infrastructure applications are climbing the fastest as multi-functional specifications proliferate in municipal tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal grid interconnection corridors underwriting cross-border renewable energy trading anchor Europe's central role in 3D printed solar energy tree deployment. Municipal procurement networks in Germany, the Netherlands, and Denmark channel standardized specifications through these transmission backbones.
Germany
Municipal sustainability mandates in Bavaria and Baden-Württemberg drive fixed solar tree procurement for sidewalk-scale generation. The EU Green Deal carbon-neutrality targets bind federal states to binding decarbonization deadlines. Munich and Hamburg cluster early deployments where harmonized building-integrated photovoltaic codes enable catalog-based purchasing.
Netherlands
Randstad urban planners specify modular solar trees for redeployable event infrastructure and temporary installations. CE marking directives govern multi-component certification for structural-electrical systems. Amsterdam and Rotterdam concentrate pilot programs testing energy service contract structures that shift municipal budgeting to operational expenditure.
Denmark
Copenhagen municipal utilities bundle solar tree deployment with 15-year performance contracts rather than capital purchases. Nordic energy agencies enforce tightened lifecycle assessment protocols requiring renewable electricity certificates for filament sources. Danish procurement officers favor tool-free joint systems for festival infrastructure with compressed payback calculations.
India
The Smart Cities Mission in Bangalore, Hyderabad, and Pune specifies integrated street furniture with embedded digital infrastructure for hybrid solar tree configurations. Central Electricity Authority grid interconnection standards shape distributed generation tariff structures. Indian urban renewal programs concentrate procurement channels where multi-functional specifications proliferate in municipal tenders.
United States
Federal Energy Regulatory Commission grid interconnection standards and EPA renewable energy incentives shape product design requirements for municipal deployments. North American city planners channel procurement through direct vendor relationships. California and Northeast corridor cities test embedded micro-inverter architectures for shade-tolerant performance in dense urban canyons.
3D Printed Solar Energy Trees Market Vendor Landscape
Listed leaders compete with private specialists across municipal contract eligibility, quality certification, and balance sheet capacity for long-dated energy service agreements. The vendor base stratifies between incumbent additive manufacturing specialists and cross-over entrants from photovoltaic integration. Three archetypes dominate: biomimetic design specialists, municipal channel controllers, and R&D partnership anchors. Competitive moves concentrate on ISO 9001 certification acquisition and regional print farm configuration for localized production.
Within the R&D partnership tier, VTT Technical Research Centre of Finland occupies a position exemplifying deep collaboration with Nordic energy agencies on lifecycle assessment protocols. SolarBotanic and Envision Solar International represent contrasting channel strategies—one anchoring European urban deployments through proprietary biomimetic designs, the other sustaining North American municipal relationships through direct city planner engagement.
| Leading Market Players |
|---|
| SolarBotanic |
| Envision Solar International |
| Solar Impulse Industry Co. Ltd |
| VTT Technical Research Centre of Finland |
| SolarBotanic Trees |
| RAW Solar |
| 3D Solar Tree |
| Arka360 |
| Green Venture Solar |
| Others |
Supply Flow & Price Mechanics
Energy service contracts with 15-year performance guarantees lock in municipal offtake while insulating vendors from silver and copper price swings through pass-through clauses. Danish and Swedish procurement officers now structure these agreements to shift capital expenditure to operational budgets, binding filament suppliers to fixed pricing tiers indexed to renewable electricity certificate costs.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified bidders, with ISO 9001 and CE marking compliance adding substantial premiums to baseline quotes. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and degradation warranty terms. Cost compression in economy tiers is intensifying because conductive polymer formulation breakthroughs enable single-pass printing. Municipal procurement officers exhibit lowest price sensitivity due to binding decarbonization mandates, while commercial campus operators negotiate aggressively on per-kilowatt installed cost.
Supply Chain Analysis
China anchors crystalline silicon wafer fabrication, while Germany and the Netherlands concentrate additive manufacturing equipment and conductive filament formulation. Conductive ink formulations draw from silver nanowire networks and copper feedstocks, with post-industrial nylon powder recovery systems emerging in Nordic markets. Single-source vulnerability in photovoltaic cell supply creates tariff exposure for European and North American integrators facing logistics disruption. Distribution runs through regional print farm configurations that serve multiple municipalities without intercontinental shipping of finished structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation intensifies as municipal specifications diverge along regional regulatory lines, creating specialist niches for biomimetic designers, micro-inverter integrators, and lifecycle assessment auditors.
For Market Incumbents: Shield installed base relationships by accelerating ISO 9001 certification timelines for additive manufacturing specialists transitioning from prototyping services. Deepen captive supply of silver nanowire conductive polymers through backward integration into filament formulation partnerships, neutralizing commodity price volatility that erodes gross margins on fixed-price municipal contracts. For New Entrants and Emerging Players: Anchor in Indian smart city missions where hybrid solar tree specifications for integrated street furniture remain undersupplied by incumbent European vendors. Target Bangalore, Hyderabad, and Pune municipal tenders with rapid-deployment modular configurations paired with embedded digital infrastructure capabilities that local integrators struggle to source. For Investors and Strategic Acquirers: Biomimetic design specialists with documented R&D partnerships and municipal reference contracts represent the most defensible acquisition profile across the projection horizon. Balance sheet capacity to carry long-dated energy service receivables serves as the critical inflection indicator distinguishing viable platform investments from stranded asset risks.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Print Farm Configuration | Localized production hubs in Germany and Denmark eliminate intercontinental shipping costs for municipal deployments. |
| Conductive Polymer Formulation Partnership | Silver nanowire network access secures single-pass printing capabilities that halve field labor requirements. |
| ISO 9001 Certification Acceleration | Documented quality management systems unlock eligibility for Bavarian and Baden-Württemberg sidewalk-scale generation contracts. |
| Energy Service Contract Structuring | 15-year performance agreements with Copenhagen municipal utilities shift procurement to operational expenditure lines. |
| Lifecycle Assessment Protocol Compliance | Third-party verified carbon intensity documentation satisfies Nordic energy agency requirements for renewable electricity certificates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, additive manufacturing specialists, photovoltaic integration engineers, and Nordic energy agency technical leads. Secondary validation drew from EU Green Deal implementation reports, CE marking directive databases, FERC grid interconnection filings, and Indian Smart Cities Mission tender documents. Bottom-up unit economics modeling triangulated against top-down municipal infrastructure spending forecasts.
Across the analysis window, forecasts segment by photovoltaic cell technology, product configuration, end-user category, and application type, with additional stratification by regional regulatory cluster. CAGRs derive from installed base growth curves, replacement cycle assumptions, and municipal budget allocation patterns. Forecast inputs incorporate conductive polymer cost trajectories, silver commodity price scenarios, and harmonization timelines for building-integrated photovoltaic codes.
Underlying assumptions cover municipal decarbonization mandate continuity and photovoltaic cell supply chain stability, with deviation risk concentrated in tariff policy shifts and CE marking directive amendments. Recalibration cycles align with material shifts in EU Green Deal enforcement intensity and conductive filament formulation breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market