
 Chile Solar Photovoltaic (PV) Market | 2026-2036
Chile Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Solar Photovoltaic (PV) Market Outlook
Aftermarket service revenue from operations and maintenance contracts is tilting toward balance-sheet owners as project portfolios mature. Enel Green Power leverages its integrated development-to-operations model across Chilean assets. AES Andes anchors its competitive stance through thermal-solar hybrid dispatch strategies that optimize grid capacity. Colbún competes by securing long-term power purchase agreements with mining offtakers in northern zones.
Chile Solar Photovoltaic (PV) systems convert solar irradiance into direct-current electricity through semiconductor junctions, with monocrystalline silicon modules achieving conversion efficiencies above 21% in desert conditions. These installations primarily supply bulk power to regulated and unregulated offtakers, plus isolated mining operations beyond grid reach. Bifacial modules capture reflected irradiance from high-albedo Atacama terrain, boosting energy yield per hectare and compressing land requirements for utility-scale parks. Energy storage integration represents the fastest-expanding technology segment as hourly price volatility in Chile's spot market rewards dispatchable solar capacity. Ground-mounted installations dominate the project pipeline given land availability and economies of scale in the northern regions.
Chile's Ministry of Energy and the National Energy Commission administer auction rounds and grid connection standards that determine project viability timelines. The Superintendency of the Environment enforces environmental impact assessments for solar parks exceeding 50 MW, adding procedural layers to northern desert developments. Stakeholders must track transmission expansion schedules and curtailment protocols as renewable penetration rises in the Sistema Interconectado Central.
Market Dynamics
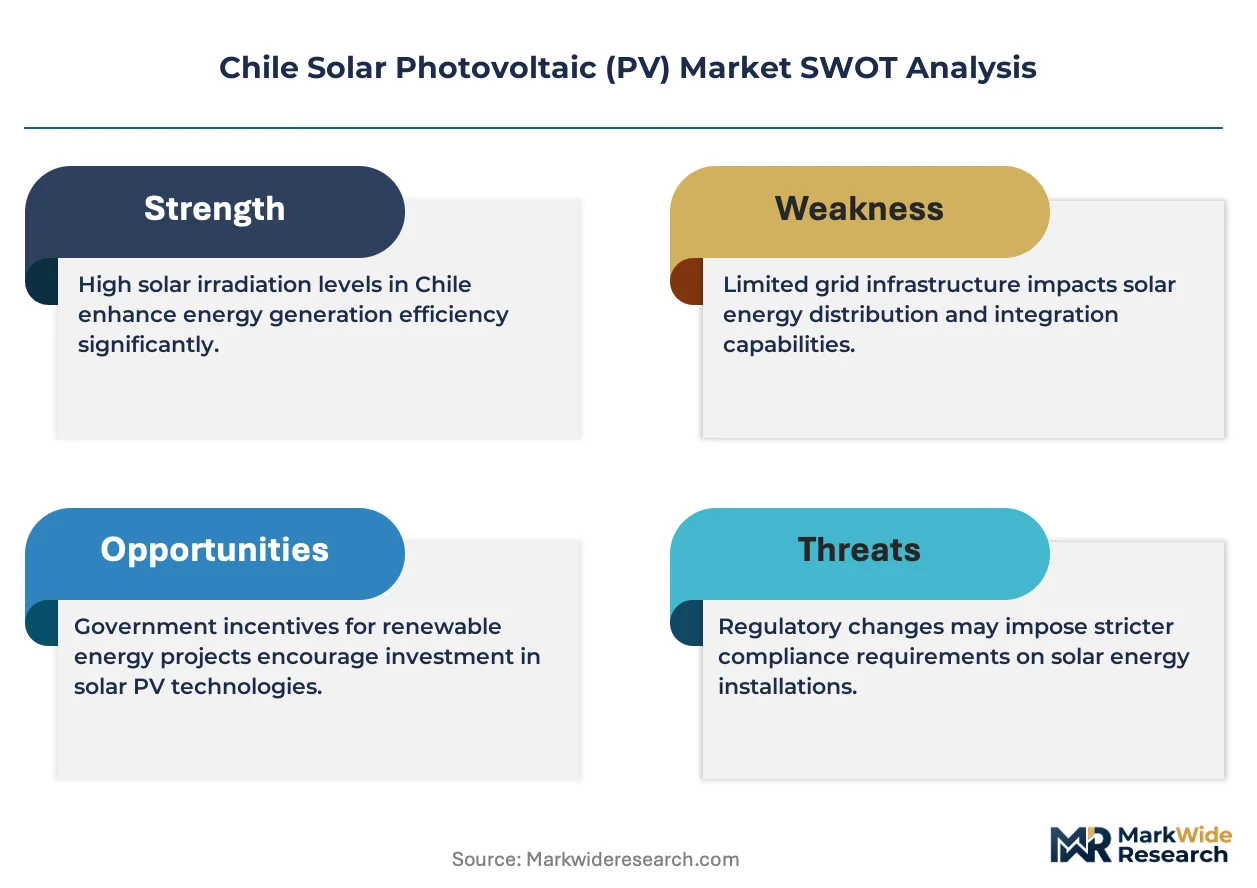
Bifacial module deployment is compressing land requirements in Chile's Atacama Desert while hourly spot market volatility accelerates energy storage co-location mandates from grid operators.
Growth Catalysts
- Law 20.698 Auction Mechanism:Chile's renewable energy auction framework guarantees long-term offtake contracts that de-risk utility-scale project financing and attract international capital flows.
- Mining Sector Electrification:Copper and lithium extraction operations in northern zones demand isolated grid solutions that solar-plus-storage configurations supply competitively.
- Albedo-Enhanced Yields:High-reflectance Atacama terrain enables bifacial modules to capture rear-side irradiance, boosting energy density per hectare deployed.
Market Restraints
- Polysilicon Supply Concentration:Module manufacturers depend on Chinese polysilicon refiners, exposing project timelines to geopolitical trade friction and input cost spikes.
- Transmission Bottlenecks:Sistema Interconectado Central expansion lags behind generation capacity additions in Antofagasta and Tarapacá regions, forcing curtailment protocols.
- Grid Integration Complexity:Chile's spot market settlement rules penalize non-dispatchable resources during oversupply hours, disadvantaging pure solar without storage.
Strategic Opportunities
- Green Hydrogen offtake:Chile's National Green Hydrogen Strategy creates anchor demand for electrolyzer-powered solar parks in Magallanes and Antofagasta zones.
- Behind-the-Meter C&I:Unregulated large consumers in Santiago and Valparaíso seek direct bilateral contracts to hedge volatile spot exposure.
- Agrivoltaic Convergence:Northern agricultural valleys near Copiapó present dual-use land configurations combining shade-tolerant crop cultivation with elevated panel arrays.
Industry Challenges
- Environmental Permitting Delays:Superintendency of the Environment impact assessments for 50 MW-plus parks extend development timelines by twelve to eighteen months in sensitive desert ecosystems.
- Specialized O&M Workforce Scarcity:Thermal inverter maintenance and predictive analytics capabilities concentrate with Enel and AES crews, constraining third-party service market depth.
- Land Tenure Fragmentation:Indigenous community consultation requirements under ILO Convention 169 complicate site acquisition in Arica-Parinacota and Tarapacá territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Solar Photovoltaic (PV) Market |
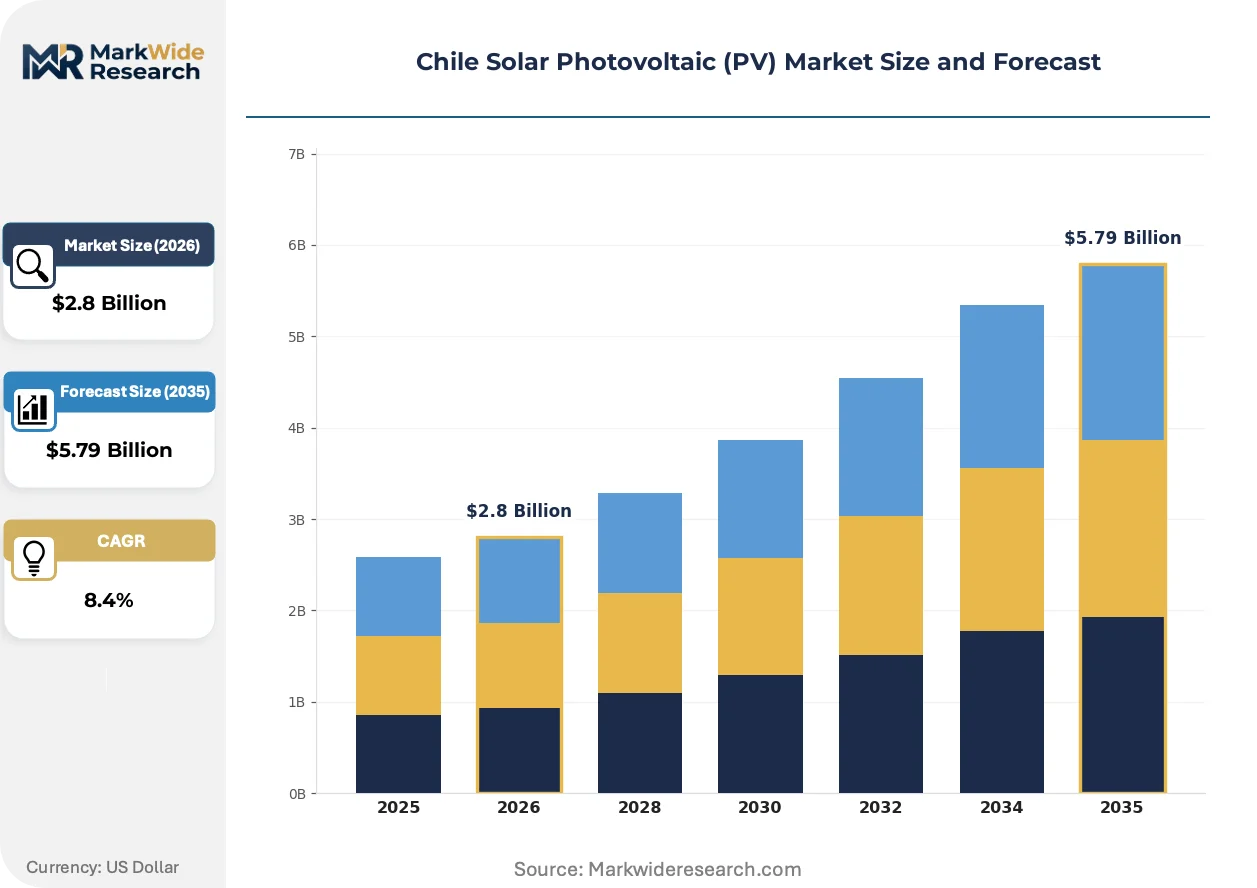
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Utility Scale, Residential, Commercial, Off-Grid Technology: Solar Inverters, Mounting Systems, Tracking Systems, Energy Storage Installation Type: Ground-Mounted, Rooftop, Building Integrated, Others |
| Companies Covered | Enel Green Power, AES Andes, Colbún, Solarpack, JA Solar, Mainstream Renewable Power, Sonnedix, Acciona Energía, ContourGlobal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Solar Photovoltaic (PV) Market Strategic Shifts
Technology convergence between solar generation and electrochemical storage is redefining project economics while regulatory pressure on grid stability accelerates dispatchable capacity requirements.
DC-coupled solar-plus-storage architectures are hybridizing plant design standards by integrating battery inverters directly at the module string level. Mining offtakers in Calama and Antofagasta now specify four-hour duration storage as standard procurement terms. This configuration is hybridizing traditional EPC contracting scopes into unified engineering packages that compress interconnection queues.
Chile's Ministry of Energy has tightened frequency response obligations for renewable generators above 10 MW through updated grid code annexes. Industrial consumers in the Sistema Interconectado Norte now face mandatory fast-frequency response capabilities or financial penalties. Northern utility-scale developers are responding by oversizing inverter loading ratios and pre-installing synthetic inertia controls.
Long-term power purchase agreement tenors are shortening as mining houses prefer five to seven year contracts over traditional fifteen to twenty year structures. Developer balance sheets now absorb greater merchant tail exposure to secure offtake. This compression is most visible in Antofagasta Region where copper producers hedge commodity price cycles against electricity cost volatility.
Chile Solar Photovoltaic (PV) Market Segmentation
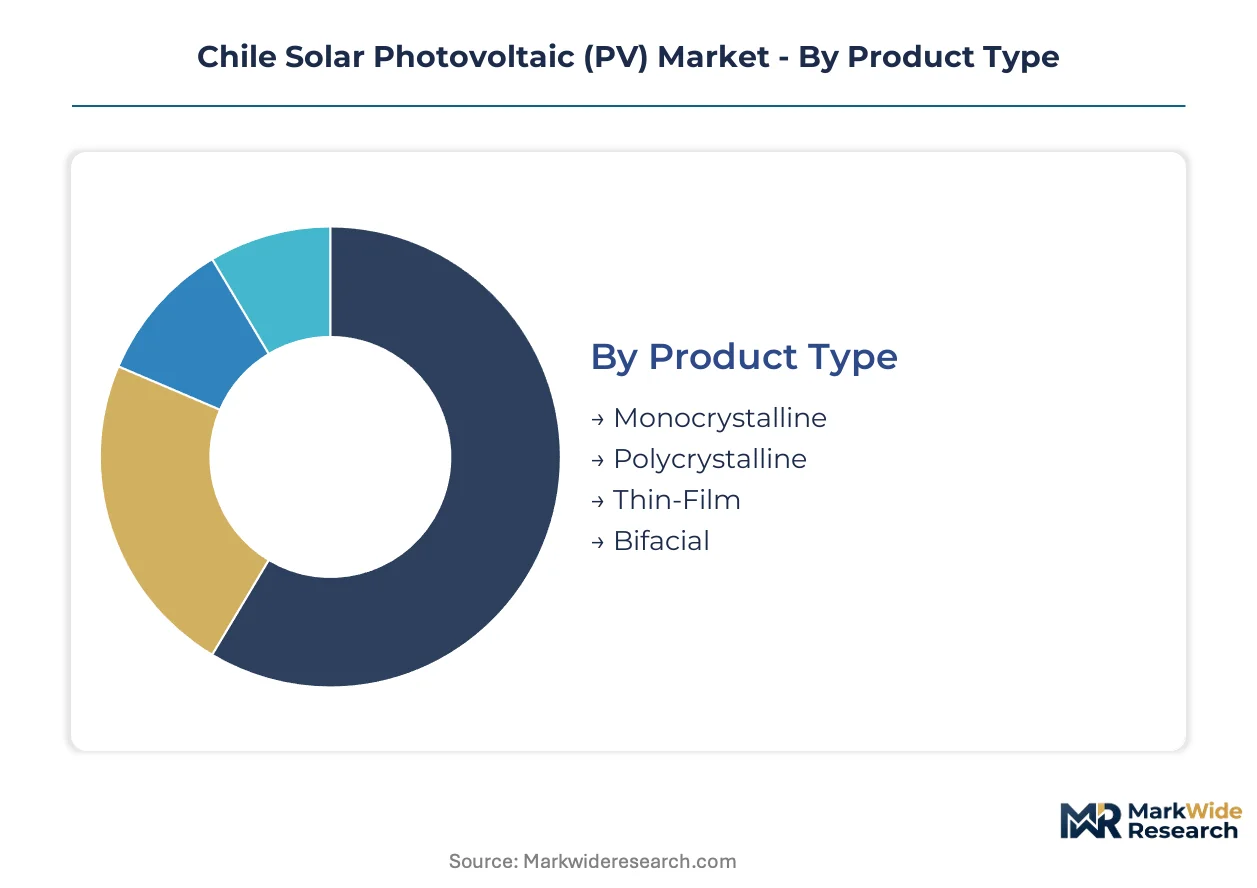
Module technology selection dictates O&M contract structures and spare parts inventory requirements across Chile's desert installations. Procurement patterns bifurcate between balance-sheet owners optimizing long-term yield and merchant developers minimizing upfront capital exposure.
Product Type:
After-sales service intensity varies sharply by cell architecture, with bifacial and monocrystalline deployments requiring specialized soiling management protocols in Atacama conditions.
- Monocrystalline:Single-crystal silicon wafers deliver conversion efficiencies exceeding 21% under high-irradiance desert conditions. Mining offtakers in Antofagasta specify these modules for isolated grid installations where land constraints limit array footprint.
- Bifacial:Dual-sided light capture harnesses albedo reflection from high-reflectance Atacama terrain, boosting energy yield per hectare. Utility-scale developers in Tarapacá deploy these to compress land acquisition requirements and reduce civil works intensity.
- Polycrystalline:Multi-crystal silicon construction offers lower unit capital cost for price-sensitive distributed installations in Santiago metropolitan zone.
- Thin-Film:Cadmium telluride and CIGS architectures tolerate partial shading better than crystalline alternatives, suiting agrivoltaic configurations in Copiapó valley agricultural corridors.
By volume, monocrystalline leads procurement queues. By growth pace, bifacial is gaining share fastest as land scarcity intensifies in prime northern zones.
Application:
Customer type determines financing structure complexity, with mining houses demanding isolated solutions and regulated utilities seeking grid-connected bulk supply.
- Utility Scale:Centralized parks above 50 MW supply the Sistema Interconectado Central through high-voltage transmission infrastructure. Colbún and AES Andes anchor development pipelines in Antofagasta Region where irradiance levels minimize levelized cost.
- Off-Grid:Standalone solar-plus-storage configurations electrify copper and lithium extraction sites beyond transmission reach. Calama mining clusters specify four-hour battery duration as standard procurement terms.
- Commercial:Behind-the-meter installations for unregulated large consumers in Valparaíso and Santiago hedge spot market volatility through bilateral contracts.
- Residential:Distributed rooftop systems concentrate in middle-income Santiago municipalities with net metering enabled by distribution utility regulations.
Utility-scale dominates capital deployment. Off-grid climbs fastest as mining electrification accelerates.
Technology:
Margin concentration follows component criticality, with energy storage and inverter systems commanding premium service attach rates.
- Energy Storage:Lithium-ion battery systems co-located with solar parks enable dispatchable capacity that satisfies Chile's tightened frequency response obligations. Hourly spot market volatility rewards four-hour duration configurations in northern zones.
- Solar Inverters:Power electronics convert DC module output to grid-synchronous AC, with 1500V central inverters dominating utility-scale architectures. Thermal management requirements concentrate predictive maintenance capabilities with integrated developer crews.
- Tracking Systems:Single-axis trackers boost energy capture 15-25% over fixed-tilt configurations, justifying mechanical complexity in high-DNI Atacama locations.
- Mounting Systems:Structural hardware secures modules against seismic loads and wind uplift, with galvanized steel dominating ground-mounted installations.
Inverters represent the largest equipment spend category. Storage is expanding most quickly as grid code compliance tightens.
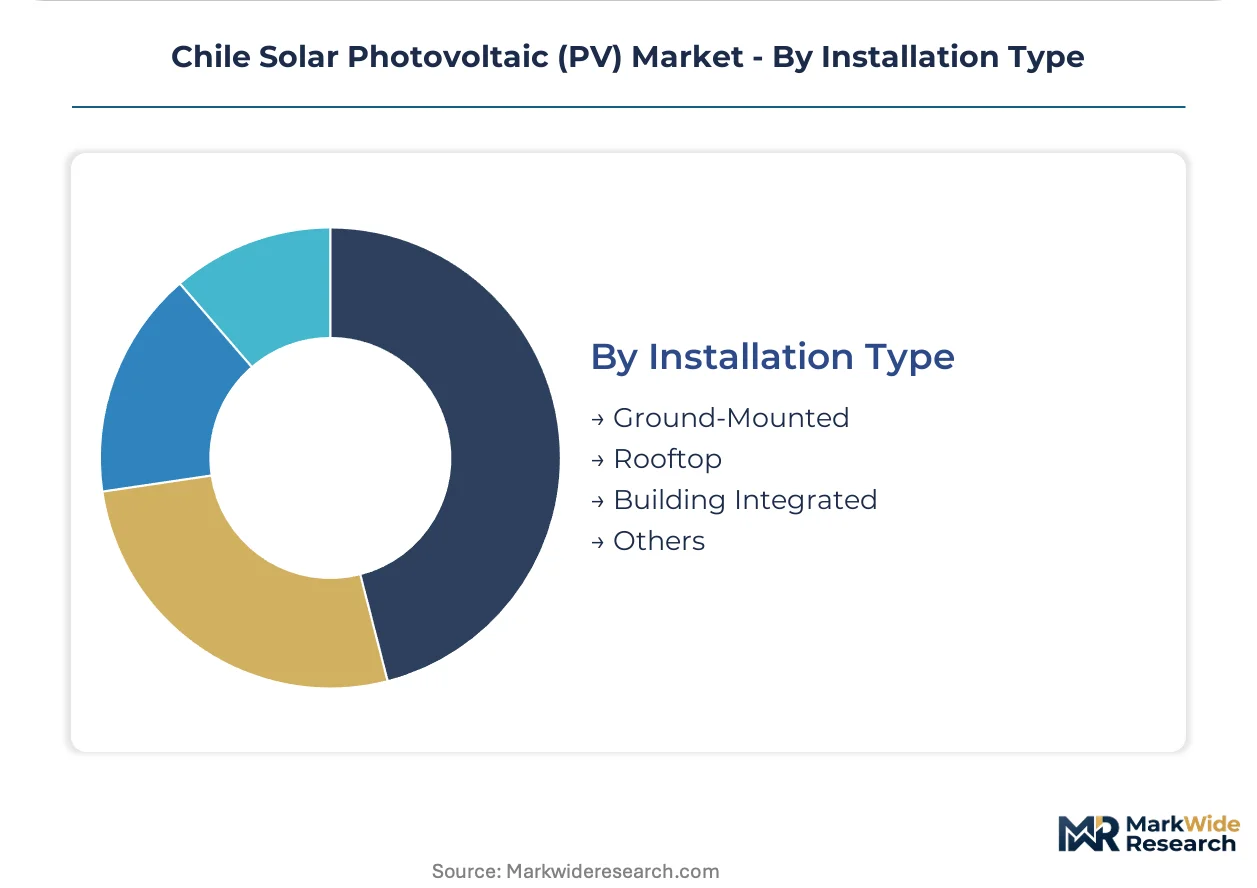
Installation Type:
Geography within Chile determines viable mounting configurations, with northern desert availability favoring ground-mounted economies of scale.
- Ground-Mounted:Elevated steel structures on graded terrain dominate utility-scale deployment in Atacama and Tarapacá regions where flat desert topography minimizes civil engineering cost.
- Rooftop:Commercial and residential distributed generation concentrates on Santiago and Valparaíso building stock with structural load capacity for PV arrays.
- Building Integrated:Façade and canopy-integrated modules serve architectural dual-use requirements in urban commercial developments.
- Others:Floating solar and agrivoltaic elevated configurations address land-use constraints in water-intensive mining operations and northern agricultural valleys.
Ground-mounted commands project pipeline volume. Building-integrated shows steepest expansion trajectory as urban distributed generation policies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's solar consumption pattern diverges sharply from neighboring markets by concentrating almost entirely on utility-scale desert installations rather than distributed urban generation. The Atacama Desert's irradiance premium drives a project economics model distinct from Brazil's agricultural belt deployment or Mexico's industrial park focus.
Antofagasta Region
Copper mining electrification dominates procurement queues as BHP and Antofagasta Minerals seek isolated grid solutions. Chile's Ministry of Energy transmission expansion schedule under the 2022-2026 National Electric System Plan determines interconnection priority for solar parks here. Calama and María Elena host the densest cluster of bifacial installations supplying mining offtakers with four-hour storage configurations.
Tarapacá Region
High-albedo terrain supports the most aggressive bifacial deployment ratios in the national pipeline. The Superintendency of the Environment enforces extended consultation timelines for projects exceeding 50 MW near Pampa del Tamarugal. Iquique and Alto Hospicio anchor logistics corridors for module importation through the Port of Iquique Free Trade Zone.
Atacama Region
Agrivoltaic pilots in the Copiapó valley test dual-use configurations combining grape cultivation with elevated tracking arrays. Regional environmental commissions apply stricter groundwater protection standards for solar park civil works near agricultural zones. Vallenar and Diego de Almagro concentrate early-stage development for green hydrogen offtake tied to Chile's National Green Hydrogen Strategy.
Magallanes Region
Wind-solar hybrid configurations dominate feasibility studies as the National Green Hydrogen Strategy designates this zone for electrolyzer anchor demand. Subsidized transmission tariffs under the 2023 Energy Transition Law improve project economics for remote developments. Puerto Natales and Punta Arenas host pilot installations testing extreme weather module resilience for future export-scale hydrogen production.
Santiago Metropolitan Region
Behind-the-meter commercial installations serve unregulated large consumers hedging spot market volatility through bilateral contracts. Net metering regulations from the Superintendence of Electricity and Fuels cap distributed generation capacity per connection point. Santiago and Valparaíso concentrate financial structuring expertise and corporate PPA origination for nationwide project portfolios.
Chile Solar Photovoltaic (PV) Market Competitive Environment
Capability concentration sits with integrated developers possessing in-house O&M crews; scale advantage sits with international IPPs deploying standardized EPC templates. The market structures around three tiers: balance-sheet owners with operational portfolios, merchant developers seeking auction offtake, and equipment suppliers anchoring module supply chains. Two competitive moves dominate: securing long-term mining PPAs in northern zones and co-locating storage to satisfy tightening grid code frequency obligations.
Within the integrated developer tier, Enel Green Power and AES Andes represent archetypes of operational capability concentration, while Colbún anchors the regulated utility vector. These three occupy positions spanning development, construction, and long-term asset ownership across Chile's northern desert zones. Their procurement patterns shape module technology selection and storage integration standards for subsequent market entrants.
| Leading Market Players |
|---|
| Enel Green Power |
| AES Andes |
| Colbún |
| Solarpack |
| JA Solar |
| Mainstream Renewable Power |
| Sonnedix |
| Acciona Energía |
| ContourGlobal |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese polysilicon refining is compressing module pricing globally while simultaneously eroding supplier margins and forcing Chilean developers toward longer-dated procurement strategies that lock in cost certainty.
Pricing Analysis
Long-term offtake contracts under Law 20.698 anchor pricing stability for utility-scale developers, while merchant developers face spot market volatility that compresses returns during oversupply hours. Price differentiation stems from module efficiency tiers and storage co-location requirements, with bifacial-plus-storage configurations commanding premiums over standalone fixed-tilt arrays. Pricing pressure intensifies as mining offtakers shorten PPA tenors to five-to-seven-year structures, forcing developers to absorb greater merchant tail exposure. Balance-sheet owners like Enel Green Power exhibit lowest price sensitivity due to integrated O&M capabilities, while merchant entrants face acute margin compression from input cost volatility and curtailment penalties.
Supply Chain Analysis
Export-control regimes limiting semiconductor and battery technology flows have concentrated module supply dependence on Chinese, Vietnamese, and Malaysian manufacturing hubs. Chilean project pipelines draw from polysilicon, wafer, and cell production concentrated in Xinjiang and Jiangsu provinces, with lithium iron phosphate battery cells sourcing predominantly from CATL and BYD facilities. Single-source vulnerability in inverter power electronics creates procurement bottlenecks when grid code updates mandate rapid technology refreshes. Distribution runs through the Port of Iquique Free Trade Zone, with EPC contractors managing last-mile logistics to Atacama and Antofagasta construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining sector consolidation around BHP, Antofagasta Minerals, and Codelco has concentrated buyer power in northern zones, tilting PPA negotiation leverage toward offtakers and compressing developer margins.
For Market Incumbents: Build operational capability moats through captive O&M crews trained on thermal inverter maintenance and predictive analytics. AES Andes and Enel Green Power should deepen backward integration into energy storage system assembly to secure battery supply priority during lithium carbonate shortages. Defensive positioning requires pre-empting Colbún's mining PPA origination through earlier-stage site control in Antofagasta Region. For New Entrants and Emerging Players: Behind-the-meter commercial installations in Santiago and Valparaíso represent the most penetrable entry point for developers lacking balance-sheet scale for utility-scale auctions. Agrivoltaic pilots in Copiapó valley agricultural corridors offer differentiated land-access strategies that bypass indigenous consultation complexities. Direct bilateral contracting with unregulated large consumers hedging spot exposure provides faster revenue recognition than auction-tied development timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solar-plus-storage configurations as four-hour duration batteries become standard procurement terms. Long-term viability over the coming decade hinges on developers proving dispatchable capacity revenue streams beyond energy-only market participation. Acquisition targets should demonstrate secured grid interconnection queue positions and operational track records in Chile's Sistema Interconectado Central. Watch for transmission expansion schedule delays as the primary inflection signal for portfolio valuation stress.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Mandate | Four-hour battery integration satisfies Chile's tightened frequency response obligations for renewable generators above 10 MW. |
| Mining PPA Origination | Direct bilateral contracts with copper and lithium extractors secure offtake in high-irradiance Antofagasta and Tarapacá zones. |
| Agrivoltaic Pilot Expansion | Dual-use configurations in Copiapó valley circumvent land tenure fragmentation under ILO Convention 169 consultation requirements. |
| Backward Integration into Inverter Assembly | In-house power electronics production reduces exposure to Chinese supply concentration and grid code compliance delays. |
| Green Hydrogen Offtake Positioning | Electrolyzer anchor demand in Magallanes and Antofagasta creates long-term revenue streams beyond electricity market participation. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and mining procurement managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through Chile's Ministry of Energy auction documentation, National Energy Commission grid connection standards, Superintendency of the Environment permitting records, and SEC filings from listed developers. Bottom-up project pipeline aggregation triangulated against top-down market sizing from transmission expansion schedules and curtailment protocol disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for polysilicon supply disruption, transmission bottleneck severity, and mining demand cyclicality. Segmentation dimensions modeled include module technology architecture, application type, installation configuration, and regional grid zone. CAGRs derived from capacity addition schedules, auction award volumes, and mining electrification timelines. Key forecast inputs encompassed Law 20.698 auction participation rates and lithium carbonate price trajectories affecting storage economics.
Practitioners should monitor transmission expansion delays, environmental permitting timeline extensions, and mining sector capital expenditure cycles for early signals requiring forecast reassessment. Material shifts in Chile's spot market settlement rules or Chinese export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Ghana Solar Energy Market