
 High-Efficiency Solar Modules Market | 2026-2036
High-Efficiency Solar Modules Market Size, Share, and Industry Trends Forecast 2026-2036
High-Efficiency Solar Modules Market Insights
Silicon is consolidating its position as the dominant wafer material, displacing legacy thin-film substrates in utility-scale deployments due to superior conversion efficiency and falling polysilicon costs. LONGi Green Energy Technology anchors its competitive position through aggressive backward integration into polysilicon and wafer production. JinkoSolar leverages vertically integrated manufacturing across Southeast Asia to navigate tariff complexities in key export markets.
High-efficiency solar modules are photovoltaic assemblies engineered to exceed standard conversion efficiencies, typically surpassing 20% through advanced cell architectures such as passivated emitter rear contact and heterojunction designs, serving industrial, commercial, and utility-scale electricity generation. Bifacial modules occupy the fastest-expanding product segment as dual-sided light capture improves energy yield per installed watt. Heterojunction technology leads the technology segment in margin capture due to lower temperature coefficients and simplified manufacturing flows, while utility-scale installation dominates volume as independent power producers prioritize levelized cost optimization.
The EPA enforces domestic content requirements under the Inflation Reduction Act, reshaping supply chain geography for modules sold into US projects. EMA and REACH frameworks in Europe govern chemical inputs in cell manufacturing, restricting certain dopants and metallization pastes. Stakeholders must monitor evolving certification standards and trade remedy proceedings across multiple jurisdictions to secure market access and avoid stranded manufacturing investments.
Market Dynamics
Utility-scale solar farms are consolidating procurement around bifacial and heterojunction architectures as land scarcity forces developers to maximize energy yield per hectare. This efficiency imperative is compressing margins for legacy mono-facial suppliers while rewarding cell manufacturers with advanced passivation capabilities.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic module assembly are drawing capital toward integrated manufacturing clusters in Gujarat and Tamil Nadu, reducing import dependency for gigawatt-scale projects.
- F-Gas Regulation:The European Union's tightening controls on fluorinated process gases are accelerating adoption of cleaner cell chemistries, creating first-mover advantage for manufacturers with fluorine-free metallization.
- Heterojunction cell architecture:Simplified manufacturing flows and superior temperature coefficients are capturing margin from incumbent PERC lines as independent power producers prioritize levelized cost optimization.
Market Restraints
- Polysilicon supply concentration:Captive production in Xinjiang creates geopolitical exposure for non-integrated module assemblers dependent on spot-market wafer sourcing.
- Silver paste input costs:Metallization pastes constitute a rising share of cell bill-of-materials, with price volatility tied to precious metals markets compressing margins at scale.
- Technical limitation in thin-film:Cadmium telluride and CIGS substrates face efficiency ceilings below silicon benchmarks, restricting deployment to niche building-integrated applications.
Strategic Opportunities
- Agrivoltaics deployment:Dual-use installations combining crop cultivation with elevated bifacial arrays are opening acreage in agricultural zones previously excluded from solar development.
- US domestic content credits:The Inflation Reduction Act's adder incentives for American-made cells are reshaping supply chain geography for modules sold into federally subsidized projects.
- Perovskite-silicon tandems:Laboratory-validated architectures approaching 30% conversion efficiency are nearing pilot production, promising step-change performance for rooftop commercial segments.
Industry Challenges
- Cell metallization expertise:Screen-printing precision for fine-line fingers requires specialized process engineers, with talent scarcity constraining yield ramp at new heterojunction facilities.
- Module certification timelines:IEC 61215 and IEC 61730 testing protocols extend 6-9 months for novel bifacial designs, delaying revenue recognition for product iterations.
- Wafer-thinning yield loss:Migration to 130-micrometer substrates increases fragmentation rates during cell fabrication, demanding capital-intensive laser processing upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Efficiency Solar Modules Market |
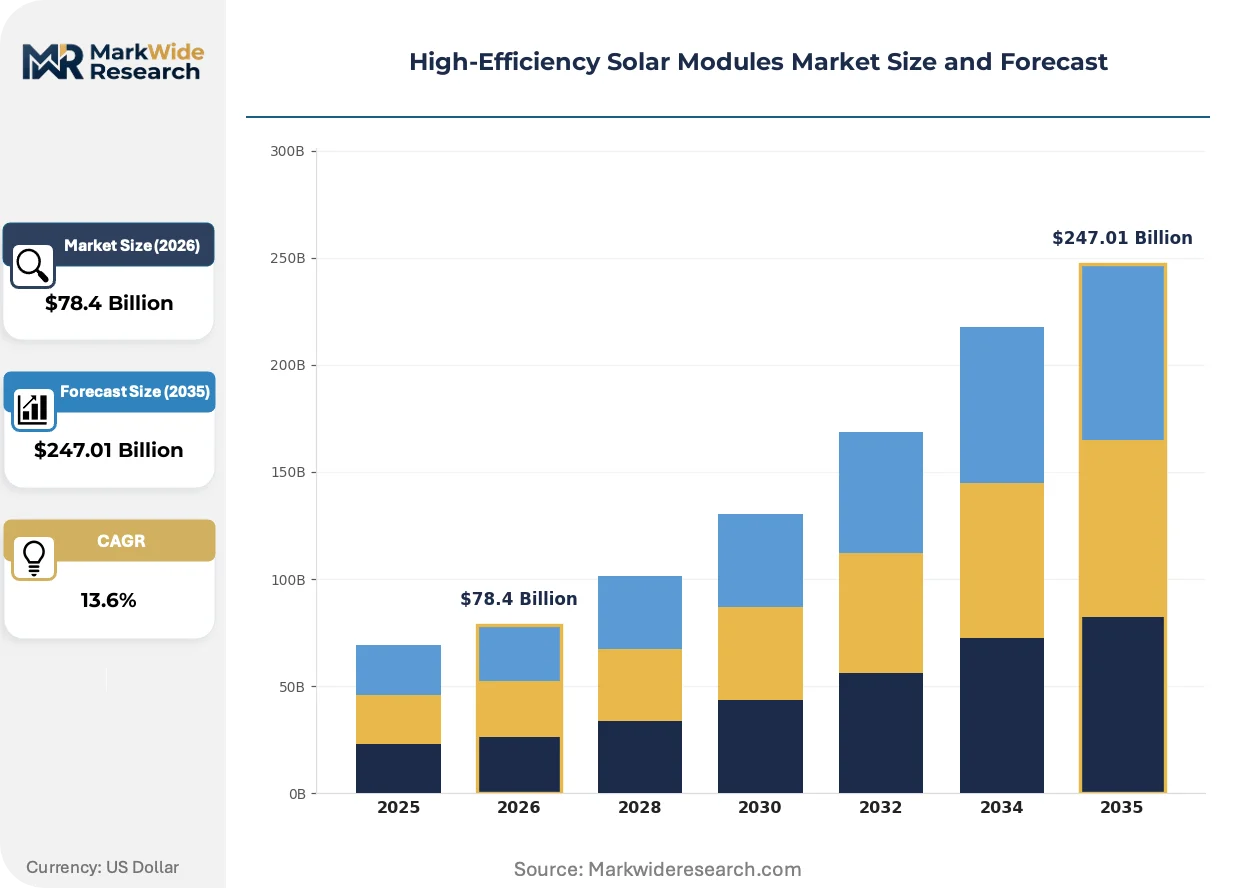
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin Film Technology: Passivated Emitter Rear Cell, Interdigitated Back Contact, Heterojunction, Multi-junction Installation: Residential, Commercial, Utility Scale, Off-Grid End User: Governments, Utilities, Homeowners, Businesses |
| Companies Covered | Maxeon, JA Solar, REC Group, Canadian Solar, LONGi Green Energy Technology, JinkoSolar, Trinasolar, VSUN, Tongwei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Efficiency Solar Modules Market Trends and Innovations
Cell architecture evolution and procurement model compression are redrawing competitive boundaries. Manufacturers must now combine process innovation with supply chain restructuring to defend position.
Heterojunction technology is overtaking passivated emitter rear contact as the efficiency benchmark for utility-scale procurement. Independent power producers in the Middle East and Australia are specifying heterojunction modules for new tenders, attracted by lower temperature coefficients in high-irradiance environments. This transition is compressing capital recovery timelines for incumbent PERC equipment and accelerating write-downs of legacy diffusion furnaces.
The EPA's domestic content requirements under the Inflation Reduction Act are forcing supply chain reconfiguration for modules sold into US projects. Module assemblers must now source cells from qualified American facilities to capture full tax credit value, redirecting capital toward polysilicon and wafer capacity in Arizona and Washington. European developers are observing this geographic shift and pressing the European Commission for analogous local content mechanisms under the EU Green Deal.
Independent power producers are consolidating procurement around long-term frame contracts with tier-one manufacturers, displacing spot-market purchasing for gigawatt-scale pipelines. This buyer concentration is squeezing mid-tier module suppliers without bankable balance sheets, particularly in Southeast Asian markets where project finance requirements are tightening. The shift is most visible in India, where national solar mission auctions now favor bidders with demonstrated manufacturing scale and multi-gigawatt delivery track records.
High-Efficiency Solar Modules Market Segmentation
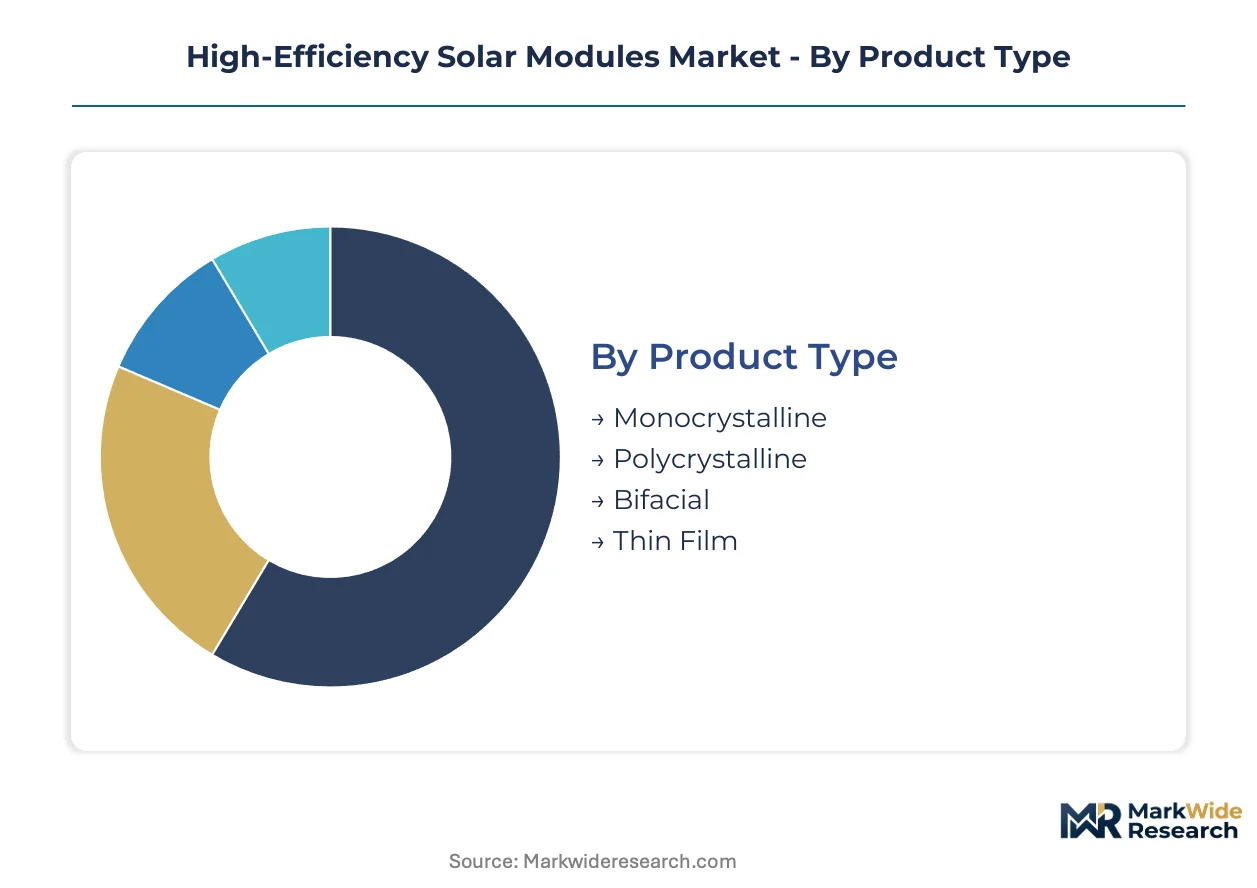
Technology roadmaps and procurement specifications fragment the high-efficiency solar modules market into distinct competitive arenas. Each segmentation dimension reveals divergent margin structures, certification requirements, and customer decision hierarchies that manufacturers must navigate simultaneously.
Product Type:
Module replacement cycles accelerate as developers retire sub-20% efficiency assets for next-generation architectures, compressing product lifespans and reshaping manufacturing priorities.
- Bifacial:Dual-sided light capture through transparent backsheet or glass-glass construction harvests albedo reflection from ground surfaces. Utility-scale developers in Saudi Arabia and Australia specify bifacial modules for desert installations where sand reflectivity boosts effective yield per watt-peak.
- Monocrystalline:Single-crystal silicon wafers deliver the highest commercial conversion efficiencies through uniform lattice structures. Residential rooftop installers in Germany and California prioritize monocrystalline panels where limited surface area demands maximum output density per square meter.
- Polycrystalline:Multi-crystal silicon ingots offer lower manufacturing energy intensity and capital equipment requirements. Emerging market distributors in Vietnam and South Africa stock polycrystalline inventory for price-sensitive commercial segments.
- Thin Film:Cadmium telluride and CIGS deposition on flexible substrates enables lightweight building-integrated applications. European architects specify thin-film laminates for facade retrofits where structural load limits exclude glass-encased crystalline modules.
Bifacial sits at the top of the volume ranking, with bifacial climbing the fastest as independent power producers rewrite procurement specifications.
Technology:
Cost tiers stratify sharply between legacy diffusion lines and advanced deposition equipment, with capital intensity per gigawatt of cell capacity spanning a threefold range.
- Heterojunction:Amorphous silicon layers deposited on crystalline substrates create superior surface passivation with lower temperature coefficients. Japanese and South Korean equipment suppliers ship heterojunction turnkey lines to cell manufacturers seeking margin expansion through simplified process flows.
- Passivated Emitter Rear Cell:Localized rear contact openings reduce recombination losses while retaining compatibility with existing screen-printing infrastructure. Indian module assemblers under the PLI scheme deploy PERC as a bridge technology toward heterojunction migration.
- Interdigitated Back Contact:Rear-side metallization eliminates front grid shading for aesthetic-sensitive applications. Premium residential installers in California and the Netherlands specify IBC modules where visible cell lines degrade property valuations.
- Multi-junction:III-V semiconductor stacking achieves conversion efficiencies exceeding 40% under concentrated illumination. Space agencies and concentrated solar power developers in Morocco and Chile procure multi-junction receivers for satellite and dish-Stirling applications.
Passivated Emitter Rear Cell commands current installed base, with heterojunction gaining share fastest as equipment depreciation cycles accelerate.
Installation:
Application-specific certification protocols and mounting hardware requirements create distinct customer acquisition economics across deployment contexts.
- Utility Scale:Ground-mounted arrays exceeding 10 megawatts dominate procurement volume through independent power producer tenders. Developers in Rajasthan and Arizona negotiate frame contracts with module suppliers for multi-gigawatt project pipelines.
- Commercial:Rooftop and carport installations on warehouses, retail centers, and manufacturing facilities balance space constraints with behind-the-meter economics. German Mittelstand manufacturers self-procure commercial systems to hedge against volatile wholesale electricity prices.
- Residential:Distributed generation on single-family homes and multi-unit buildings requires simplified permitting and installer training. Australian households lead per-capita residential deployment through net metering policies and financing through property-assessed clean energy bonds.
- Off-Grid:Stand-alone systems with battery storage serve remote telecommunications, mining camps, and rural electrification. Kenyan and Nigerian rural electrification agencies tender off-grid solar-diesel hybrid systems for health clinics and agricultural processing centers.
Utility Scale anchors procurement volume, with Commercial expanding most quickly as corporates execute renewable energy certificate strategies.
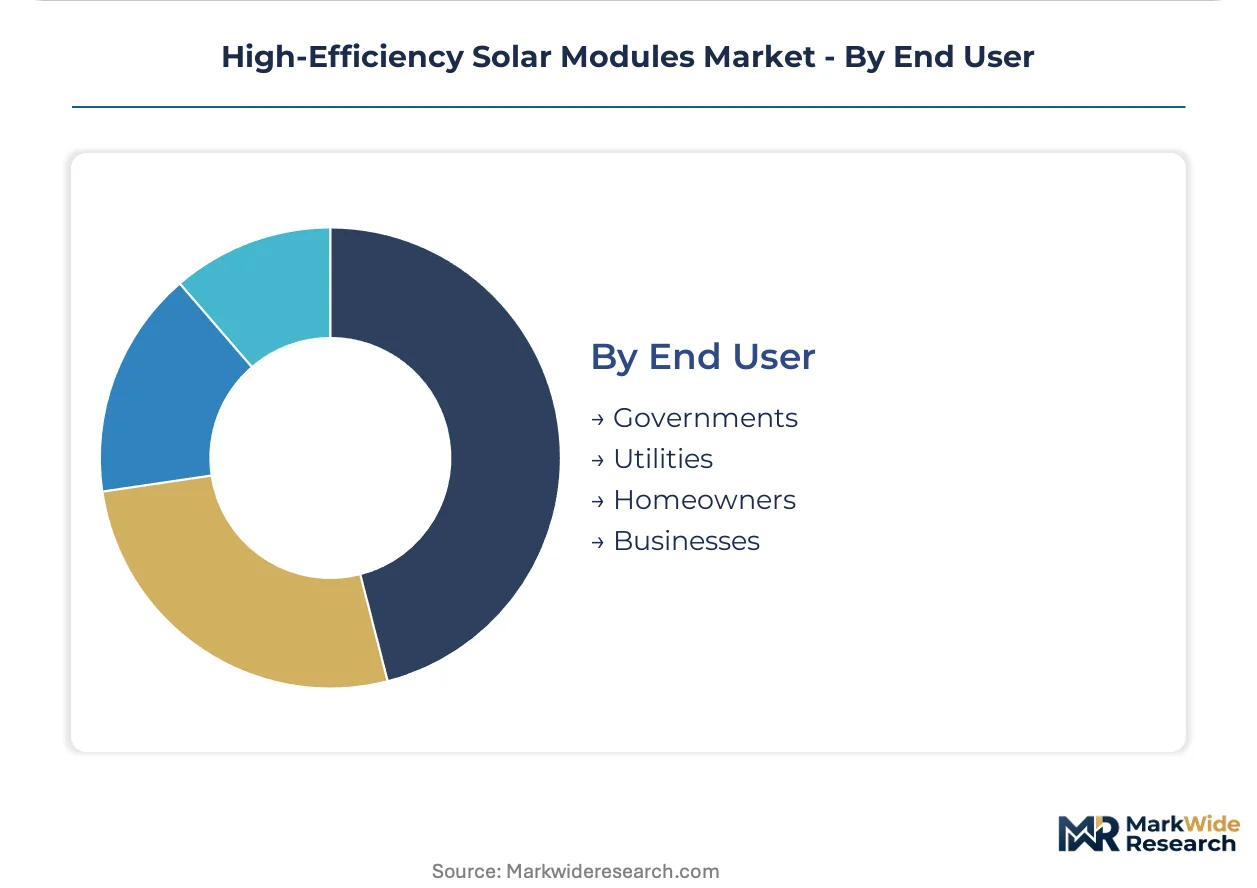
End User:
Customer type determines contract structure, with utilities favoring 20-year power purchase agreements against homeowners prioritizing payback period visibility.
- Utilities:Vertically integrated and independent power producers procure modules through competitive auctions with delivery schedules tied to grid interconnection timelines. State-owned utilities in India and Brazil dominate tender volumes through national solar mission allocations.
- Businesses:Commercial and industrial enterprises deploy onsite generation to reduce scope two emissions and secure electricity price certainty. RE100 multinationals in the Netherlands and Sweden specify high-efficiency modules for supply chain decarbonization commitments.
- Homeowners:Individual households make purchase decisions through installer recommendations and financing availability. Italian and Australian homeowners leverage feed-in tariff remnants and net metering to justify premium module selections.
- Governments:Public sector procurement covers military installations, federal facilities, and international development finance. The US Department of Defense mandates domestic content compliance under IRA provisions for military base solar deployments.
Utilities sit at the top of the volume ranking, with Businesses climbing the fastest as corporate renewable targets harden into capital allocation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's polysilicon corridor anchors upstream material flows, while module assembly concentrates in coastal manufacturing belts across three continents. Demand geography diverges sharply from production geography, forcing complex tariff-navigation strategies.
United States
Utility-scale developers in Arizona and Texas specify heterojunction and bifacial modules for desert installations with high albedo reflection. The EPA enforces domestic content requirements under the Inflation Reduction Act, redirecting capital toward polysilicon and wafer capacity in Washington and Arizona. The Department of Defense mandates IRA compliance for military base solar deployments, consolidating procurement around bankable tier-one suppliers.
China
LONGi Green Energy Technology and JinkoSolar anchor wafer and cell production in the Yangtze River Delta and Xinjiang polysilicon belt. The country's dual carbon goals accelerate capacity expansion for export markets. Ningbo and Suzhou host module assembly clusters serving Middle Eastern and Australian utility tenders.
India
National solar mission auctions concentrate demand in Rajasthan and Gujarat, where gigawatt-scale projects maximize land yield with high-efficiency bifacial arrays. The PLI scheme for solar manufacturing draws capital toward integrated clusters in Gujarat and Tamil Nadu. DGFT import restrictions on Chinese cells force domestic assembly scale-up.
Germany
Residential rooftop installers in Bavaria and Baden-Württemberg prioritize monocrystalline panels where limited surface area demands maximum output density. The F-Gas Regulation accelerates adoption of fluorine-free metallization chemistries. EMA and REACH frameworks govern chemical inputs in cell manufacturing, restricting certain dopants.
Saudi Arabia
Independent power producers specify bifacial modules for desert installations where sand reflectivity boosts effective yield per watt-peak. The kingdom's renewable energy tender program drives procurement consolidation. Industrial clusters in Riyadh and the Eastern Province host module assembly for regional export.
High-Efficiency Solar Modules Market Competitive Landscape
Global majors compete with regional champions across technology roadmaps and tariff-access geographies. The vendor base stratifies into tier-one bankable suppliers, integrated polysilicon-to-module players, and specialist heterojunction pioneers. Three archetypes dominate: backward-integrated silicon giants, Southeast Asian tariff-hubs, and premium-efficiency technology licensors. Competitive moves center on polysilicon captive supply and heterojunction capacity expansion.
Within the integrated-silicon tier, LONGi Green Energy Technology and Tongwei exemplify upstream control over polysilicon and wafer production. JA Solar occupies a position among Southeast Asian fabricators navigating US tariff complexities through Vietnam and Thailand assembly. Maxeon represents the premium-efficiency archetype with interdigitated back-contact specialization for distributed rooftop segments.
| Leading Market Players |
|---|
| Maxeon |
| JA Solar |
| REC Group |
| Canadian Solar |
| LONGi Green Energy Technology |
| JinkoSolar |
| Trinasolar |
| VSUN |
| Tongwei |
| Others |
Pricing and Supply Chain Analysis
Heterojunction cell architecture migration simultaneously compresses manufacturing step counts and concentrates equipment sourcing among Japanese and South Korean tool vendors, reshaping both unit economics and supplier bargaining power across the value chain. This technology transition feeds back into polysilicon procurement strategies as integrated manufacturers capture margin through in-house wafer production.
Pricing Analysis
Silver paste and polysilicon pass-through dominates module pricing dynamics. Three-tier pricing structure across premium heterojunction, standard PERC, and economy polycrystalline levels separates bankable tier-one suppliers from mid-tier assemblers. Cost compression in standard-tier modules is intensifying because of Xinjiang polysilicon spot-price volatility. Utility-scale independent power producers exhibit lowest price sensitivity due to long-term power purchase agreement structures, while emerging market distributors face acute margin pressure.
Supply Chain Analysis
IEC 61215 and IEC 61730 certification gating restricts qualified supplier pools to manufacturers with sustained testing investment. Geographic concentration centers on China for polysilicon and wafers, Vietnam and Thailand for tariff-advantaged module assembly, and India for PLI-subsidized domestic production. Raw material dependencies draw from metallurgical-grade silicon, silver paste, and aluminum frames. Single-source vulnerability in heterojunction equipment creates bottleneck risk. Distribution runs through independent power producer frame contracts and EPC contractor specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement specifications from Middle Eastern and Australian independent power producers now mandate heterojunction performance thresholds, displacing legacy PERC suppliers without advanced passivation capabilities.
For Market Incumbents: Extend heterojunction capacity deployment ahead of equipment depreciation cycles to capture premium pricing windows. Secure captive polysilicon supply through backward integration or long-term offtake agreements to mitigate Xinjiang sourcing exposure. Defend against emerging Southeast Asian tariff-hub assemblers by accelerating American cell qualification under IRA domestic content rules. For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for qualified domestic cell manufacturing. Target Arizona and Washington for greenfield heterojunction facilities to capture adder incentives. Pursue agrivoltaic deployment partnerships as the most penetrable application segment. Build go-to-market credibility through IEC certification investment and demonstrated bankability for project finance. For Investors and Strategic Acquirers: Valuations sit cheapest among Southeast Asian tariff-hub assemblers facing IRA compliance gaps. Long-term viability centers on technology licensors with perovskite-silicon tandem pipelines and established heterojunction process expertise. Watch heterojunction equipment order backlogs as the inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heterojunction Capacity Buildout | Captures premium pricing from IPPs in Saudi Arabia and Australia seeking lower temperature coefficients. |
| Domestic Content Qualification | Unlocks IRA tax credit value for modules sold into federally subsidized US utility projects. |
| Silver Paste Reduction R&D | Lowers bill-of-materials exposure to precious metals volatility through copper metallization development. |
| Agrivoltaic Partnership Formation | Opens agricultural acreage previously excluded from solar development through dual-use installation models. |
| Perovskite Tandem Licensing | Positions for step-change efficiency gains approaching laboratory-validated thresholds in commercial rooftop segments. |
Research Methodology
Multiple input streams — confidential interviews with cell manufacturing executives, utility procurement officers, and EPC project developers; secondary validation through FERC interconnection filings, IEA deployment databases, and customs trade records; plus IEC certification registry analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured capacity expansion timelines, equipment order patterns, and tender specification evolution across Middle Eastern, Australian, and Indian markets.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include cell architecture technology, module product type, installation scale tier, and regional regulatory framework. CAGRs were derived from installed base replacement cycles, efficiency upgrade premiums, and policy incentive trajectories. Industry-specific forecast inputs incorporated silver paste price indices, polysilicon capacity utilization rates, and heterojunction equipment lead times.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt tariff regime changes or breakthrough perovskite commercialization. Forecasts reflect assumptions regarding IRA domestic content rule stability, F-Gas Regulation enforcement timelines, and PLI scheme extension decisions. A model refresh is warranted upon material change in heterojunction equipment order patterns or silver substitution technology viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Dual Axis Solar Tracker Market