
 Laser-Induced Breakdown Spectroscopy Market | 2026-2036
Laser-Induced Breakdown Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Laser-Induced Breakdown Spectroscopy Market Intelligence
Benchtop-to-portable specification-tier migration is rotating demand toward field-deployable units with IP-rated enclosures and battery-operated laser sources. Hitachi High-Tech Analytical Science leverages its semiconductor detector supply chain to sustain cost advantages in miniaturized architectures. Thermo Fisher Scientific anchors North American service infrastructure through factory-certified calibration networks. Bruker Corporation differentiates via dual-pulse laser configurations that extend detection limits for light-element quantification in geological matrices.
Laser-induced breakdown spectroscopy employs a pulsed laser to ablate a microscopic sample volume, generating a plasma whose atomic emission spectrum reveals elemental composition with detection limits reaching parts-per-million for heavy metals; its primary industrial purpose spans rapid alloy verification, soil contaminant screening, and pharmaceutical raw-material identification without sample dissolution. Portable product types now capture the fastest expansion as battery and fiber-laser advances shrink footprint below ten kilograms. Time-of-flight technology leads in resolution-sensitive mining applications where isobaric interferences complicate frequency-domain alternatives. Academia end users represent a mature, price-sensitive pool where grant-funded procurement favors open-architecture systems with user-programmable acquisition parameters.
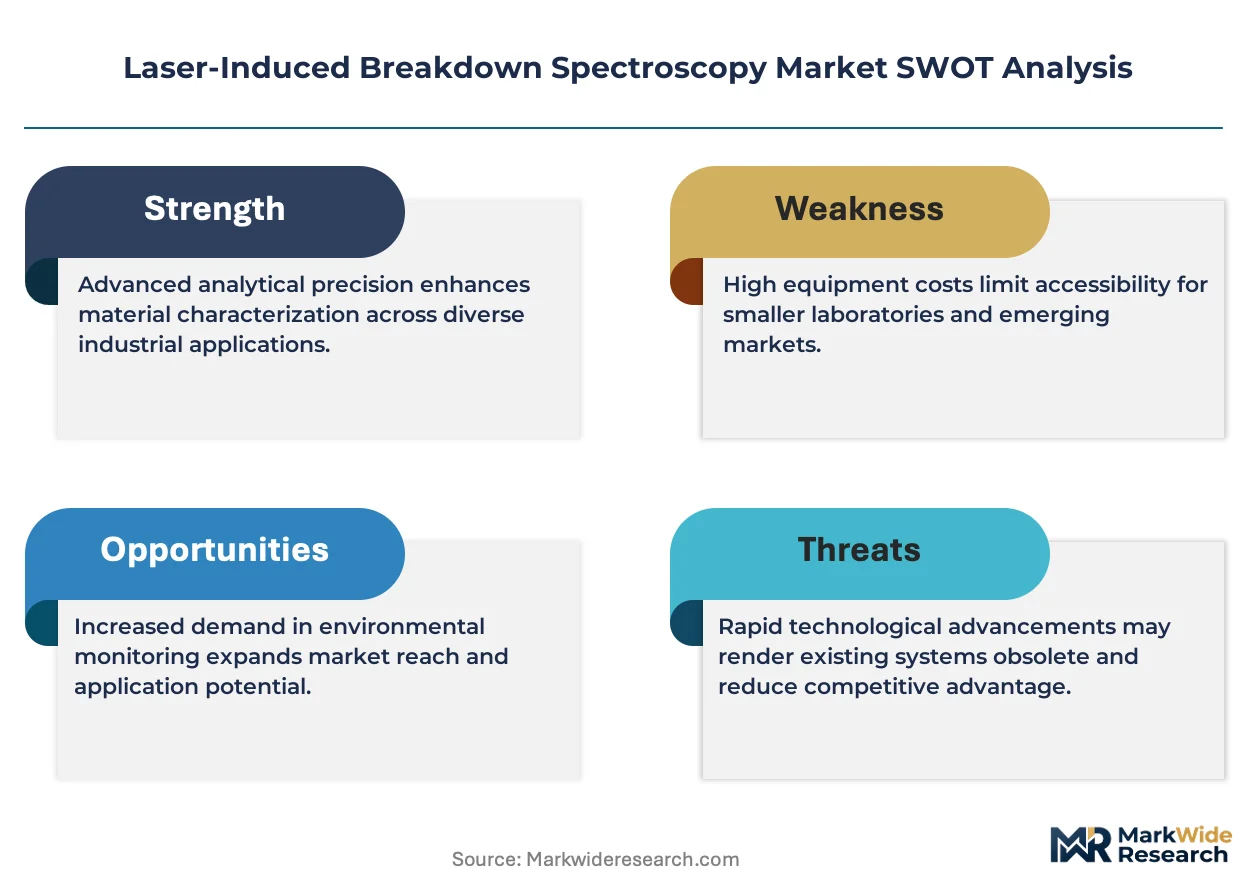
FDA elemental-impurity guidelines under ICH Q3D and EPA Method 200.7 compliance obligations shape pharmaceutical and environmental demand for validated LIBS protocols with documented uncertainty budgets. ISO 17025 accreditation requirements for testing laboratories restrict market access to vendors offering traceable reference materials and software audit trails. REACH substance restrictions in Europe further steer material-analysis procurement toward non-destructive techniques that eliminate hazardous reagent consumption. Stakeholders must monitor evolving laser-safety classification thresholds and RoHS exemptions for high-power diode modules, as these standards will determine which hardware configurations remain certifiable across key jurisdictions.
Market Dynamics
The portable LIBS specification tier is rotating demand toward field-deployable units, compressing procurement timelines for mining operations and displacing slower laboratory-based wet-chemistry workflows across industrial quality control applications.
Growth Catalysts
- EPA Method 200.7 compliance:Environmental monitoring mandates in the United States are validating LIBS protocols for heavy-metal screening in soil and water matrices, expanding instrument deployment at remediation sites.
- Battery-chemistry verification:Lithium-ion supply chains require rapid elemental analysis of cathode materials, pulling portable units into gigafactory receiving docks for incoming raw-material qualification.
- Chile-Australia mining corridors:Real-time ore grading at pit faces eliminates laboratory turnaround delays, embedding LIBS into extraction economics for copper and iron-oxide operations.
Market Restraints
- Detector supply concentration:Semiconductor detector fabrication clusters in East Asian foundries expose vendors to single-source risk for silicon drift and CCD architectures.
- Laser-safety classification thresholds:IEC 60825-1 compliance costs escalate for Class 4 laser configurations, restricting certifiable product architectures in European jurisdictions.
- X-ray fluorescence substitution:Benchtop XRF retains cost advantages for high-precision alloy verification in centralized laboratory settings, capping LIBS penetration in mature metallurgical workflows.
Strategic Opportunities
- India pharmaceutical corridors:CDSCO enforcement of ICH Q3D elemental-impurity limits creates first-mover openings for validated LIBS protocols in API manufacturing clusters around Hyderabad and Ahmedabad.
- Dual-pulse architecture convergence:Coupling femtosecond pre-ablation with nanosecond analytical pulses extends light-element detection limits, unlocking geological matrices previously reserved for mass-spectrometry methods.
- Factory-direct calibration networks:Bypassing distributor markups through certified service infrastructure captures margin compression in price-sensitive academic procurement channels.
Industry Challenges
- Plasma-physics expertise gap:Interpretation of spectral interferences in complex matrices requires spectroscopists with atomic-emission training, a skill set scarce in industrial maintenance departments.
- ISO 17025 accreditation timelines:Testing laboratories face eighteen-to-twenty-four-month validation cycles for LIBS protocols, delaying revenue recognition for instrument vendors in regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser-Induced Breakdown Spectroscopy Market |
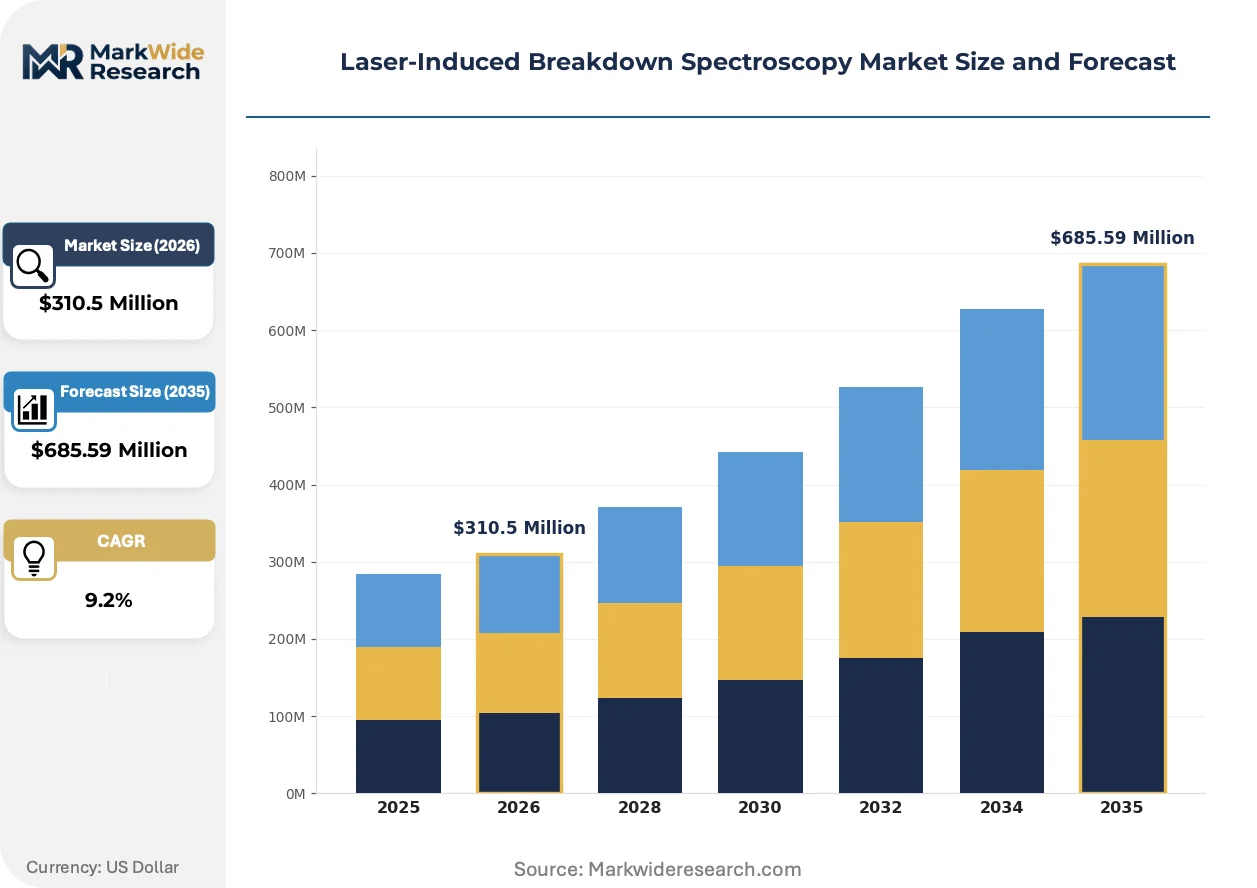
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $685.59 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Laboratory, Handheld, Online Technology: Time-of-Flight, Frequency Domain, Multi-Channel, Miniaturized Application: Material Analysis, Environmental Monitoring, Forensic Science, Mining End User: Aerospace, Pharmaceuticals, Academia, Manufacturing |
| Companies Covered | Hitachi High-Tech Analytical Science, Applied Spectra, Thermo Fisher Scientific, B&W Tek, Princeton Instruments, Rigaku, SciAps, Avantes, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser-Induced Breakdown Spectroscopy Market Strategic Shifts & Innovations
Hardware architectures are compressing toward sub-ten-kilogram footprints while software workflows integrate machine-learning classification for automated spectral interpretation, collapsing the skill barrier for field operators.
Fiber-laser technology is miniaturizing excitation sources into battery-operated packages, enabling single-handed operation in underground mining environments. Australian iron-ore majors are deploying these units for blast-hole chip analysis, compressing assay turnaround from days to minutes. The form-factor reduction is displacing centralized laboratory contracts for routine grade-control sampling.
REACH substance restrictions across European manufacturing jurisdictions are eliminating hazardous reagent consumption in material analysis, redirecting procurement toward non-destructive techniques. Industrial laboratories in Germany's Ruhr corridor are retiring dissolution-based workflows for incoming metals inspection, accelerating LIBS validation under ISO 17025 frameworks.
Service unbundling is fragmenting traditional instrument-sales contracts into subscription-based calibration and software-update tiers. North American pharmaceutical quality-control departments are separating hardware capital expenditure from recurring compliance-support fees, compressing initial procurement thresholds while elongating vendor revenue cycles.
Laser-Induced Breakdown Spectroscopy Market Segmentation
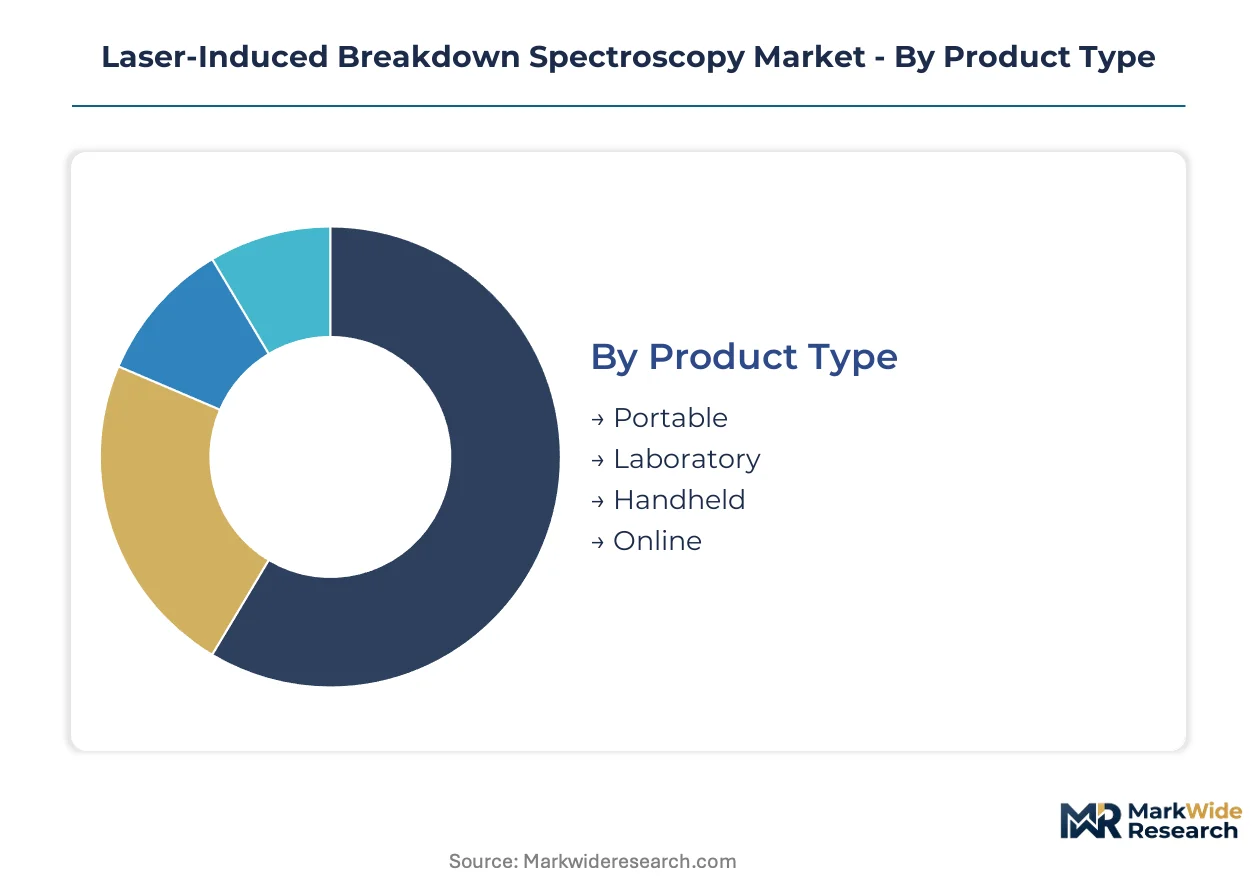
Segmentation in laser-induced breakdown spectroscopy reveals divergent specification requirements across deployment contexts. Portable architectures demand ruggedized enclosures and battery autonomy, while laboratory systems prioritize spectral resolution and automation throughput. Understanding these tiered demands illuminates where vendors must concentrate R&D investment versus service infrastructure.
Product Type:
Portable units dominate export-led procurement from mining jurisdictions, while laboratory systems anchor domestic replacement cycles in established industrial economies.
- Portable:Field-deployable architectures integrate fiber-laser excitation and silicon drift detectors into IP-rated enclosures below ten kilograms. Demand concentrates in Chilean and Australian open-pit operations where real-time ore grading eliminates laboratory turnaround bottlenecks. Battery-chemistry verification at Asian gigafactory receiving docks is accelerating procurement timelines.
- Laboratory:Stationary configurations emphasize dual-pulse laser geometries and cryogenically cooled detectors for parts-per-billion detection limits. German industrial laboratories along the Ruhr corridor are displacing wet-chemistry workflows under REACH substance restrictions, validating these systems for ISO 17025 accreditation.
- Handheld:Single-handed operation variants target underground mining environments with simplified spectral interpretation interfaces.
- Online:Continuous-process integration units monitor molten metal streams and pharmaceutical powder lines without sampling interruption.
Laboratory systems hold the largest share; momentum sits with portable configurations.
Technology:
Cost tiering separates premium time-of-flight architectures from mid-market frequency-domain alternatives, with miniaturized systems capturing price-sensitive academic procurement.
- Time-of-Flight:Picosecond timing resolution separates isobaric interferences in complex geological matrices. Mining applications in Western Australia and northern Chile specify these systems for rare-earth element quantification where mass-spectrometry alternatives prove logistically impractical.
- Frequency Domain:Grating-dispersed architectures offer cost-optimized elemental screening for routine alloy verification. Centralized metallurgical laboratories in the United States retain these systems where X-ray fluorescence competition constrains specification escalation.
- Multi-Channel:Simultaneous multi-element detection arrays accelerate throughput for high-volume environmental screening contracts.
- Miniaturized:Chip-scale spectrometer integration targets grant-funded academic procurement with open-architecture programmability.
Time-of-Flight commands premium positioning; miniaturized systems are climbing the fastest on volume.
Application:
Application maturity varies sharply: material analysis represents saturated replacement demand, while environmental monitoring faces regulatory acceleration.
- Material Analysis:Alloy verification and incoming metals inspection constitute established workflows with documented uncertainty budgets. German automotive supply chains and Japanese precision manufacturers drive replacement demand as REACH and JIS standards tighten elemental-impurity thresholds.
- Environmental Monitoring:EPA Method 200.7 compliance obligations in the United States validate LIBS protocols for soil and groundwater remediation. Superfund site contractors are embedding portable units into field mobilization kits, displacing laboratory sample shipment.
- Forensic Science:Trace evidence analysis for gunshot residue and glass fragment identification requires portable systems with chain-of-custody documentation.
- Mining:Blast-hole chip analysis and conveyor-belt ore sorting compress assay turnaround from days to minutes, embedding LIBS into extraction economics.
Material analysis retains the largest installed base; environmental monitoring shows steepest expansion trajectory.
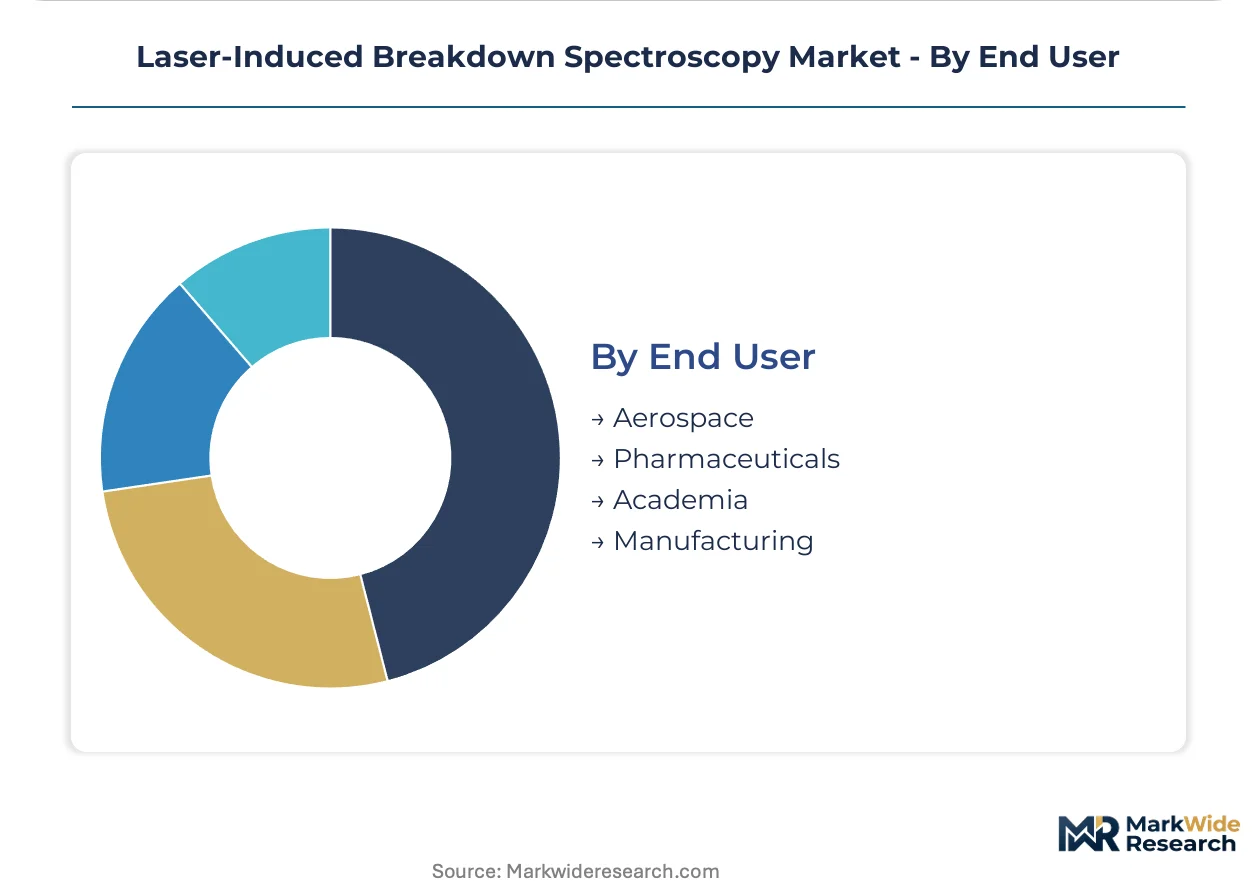
End User:
Customer type determines procurement authority structure: manufacturing and aerospace centralize capital expenditure, while academia fragments across grant-funded principal investigators.
- Aerospace:Tier-one suppliers and airframe manufacturers specify LIBS for titanium alloy verification and thermal barrier coating analysis. FAA airworthiness directives and AS9100 quality mandates drive validation investment for documented traceability.
- Pharmaceuticals:API manufacturers in India and Ireland face ICH Q3D elemental-impurity enforcement, pulling validated protocols into quality-control laboratories. CDSCO and EMA inspection readiness requires software audit trails and reference material traceability.
- Academia:University research groups prioritize open-architecture systems with user-programmable acquisition parameters for plasma-physics investigation.
- Manufacturing:Industrial metals processors deploy in-line systems for continuous quality verification, displacing slower batch sampling.
Manufacturing holds the largest share; pharmaceuticals are gaining share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for semiconductor detectors and fiber-laser modules tilts trade flows toward East Asian fabrication clusters, while mining-driven demand in resource economies generates counterbalancing export revenues for instrument vendors.
United States
EPA Method 200.7 compliance obligations validate LIBS protocols for soil and groundwater remediation at Superfund sites. FDA enforcement of ICH Q3D elemental-impurity guidelines pulls validated systems into pharmaceutical quality-control laboratories. Houston-area environmental contractors embed portable units into field mobilization kits for petrochemical corridor monitoring.
Germany
Industrial laboratories along the Ruhr corridor displace wet-chemistry workflows under REACH substance restrictions. ECHA enforcement of hazardous reagent elimination redirects procurement toward non-destructive techniques. Automotive supply chains in Baden-Württemberg drive replacement demand as JIS and DIN standards tighten elemental-impurity thresholds for incoming metals inspection.
Australia
Iron-ore majors in Western Australia deploy fiber-laser units for blast-hole chip analysis, compressing assay turnaround from days to minutes. TGA alignment with ISO 17025 accreditation requirements shapes laboratory procurement specifications. Pilbara operations embed LIBS into extraction economics, eliminating centralized laboratory contracts for routine grade-control sampling.
Chile
Open-pit copper operations specify time-of-flight architectures for real-time ore grading at pit faces. The national mining regulator validates field-deployable protocols for production geology workflows. Antofagasta and Calama extraction clusters represent the densest concentration of portable unit deployment in Latin American mining.
India
CDSCO enforcement of ICH Q3D elemental-impurity limits creates first-mover openings in API manufacturing clusters around Hyderabad and Ahmedabad. BIS certification requirements for analytical instruments shape vendor qualification timelines. Pharmaceutical quality-control departments separate hardware capital expenditure from recurring compliance-support fees, compressing initial procurement thresholds.
Laser-Induced Breakdown Spectroscopy Market Key Industry Players
Concentration sits with diversified analytical-instrument conglomerates and specialized spectroscopy houses. The vendor base stratifies across three tiers: integrated life-science conglomerates with service infrastructure depth; mid-cap spectroscopy specialists with detector supply-chain control; and regional fabricators competing on price-sensitive academic procurement. Dominant competitive moves include backward integration into semiconductor detector supply and factory-direct calibration network expansion bypassing distributor markups.
Among diversified analytical-science conglomerates, Thermo Fisher Scientific and Bruker Corporation exemplify the infrastructure-heavy archetype with established calibration networks. Hitachi High-Tech Analytical Science anchors the detector-supply-chain integration position. SciAps and Applied Spectra occupy positions within the portable-specialist tier, while Avantes and B&W Tek represent component-level and miniaturization-focused positions respectively. Princeton Instruments and Rigaku exemplify the precision-optics heritage segment with cryogenic detection capabilities.
| Leading Market Players |
|---|
| Hitachi High-Tech Analytical Science |
| Applied Spectra |
| Thermo Fisher Scientific |
| B&W Tek |
| Princeton Instruments |
| Rigaku |
| SciAps |
| Avantes |
| Bruker Corporation |
| Others |
Cost & Logistics Intelligence
Fourteen-to-eighteen-week lead times for silicon drift detectors concentrate pricing power with East Asian foundry operators while compressing margins for instrument assemblers facing battery-chemistry verification deadlines at Asian gigafactories.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 17025 certification grade and after-sales service bundling, with validated protocols commanding substantial premiums over open-architecture academic systems. Cost compression in the economy tier intensifies because detector supply concentration limits vendor negotiation leverage. Academic procurement teams exhibit highest price sensitivity, while pharmaceutical quality-control departments prioritize compliance documentation over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane expose European assemblers to inbound logistics volatility. Semiconductor detector fabrication draws from Taiwan, South Korea, and Japan, while fiber-laser module production rests on Chinese and German manufacturing clusters. Single-source vulnerability for silicon drift architectures threatens production continuity. Distribution runs through factory-direct calibration networks and authorized distributor channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mining majors consolidate procurement authority across Chilean and Australian extraction corridors, compressing vendor margins and elevating service-infrastructure requirements.
For Market Incumbents: Consolidate detector supply relationships through backward integration or exclusive offtake agreements with Taiwanese foundries. Deepen service infrastructure in the Pilbara and Antofagasta mining clusters to defend against portable-specialist entrants. X-ray fluorescence substitution in centralized metallurgical laboratories threatens replacement-cycle revenue.
For New Entrants and Emerging Players: ISO 17025 fast-track programs unlock first-mover positioning in Indian pharmaceutical corridors around Hyderabad and Ahmedabad. Target price-sensitive academic procurement with open-architecture miniaturized systems. Battery-chemistry verification at gigafactory receiving docks offers the most penetrable application white space.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA Method 200.7 and ICH Q3D enforcement deepen instrument replacement cycles. Acquisition targets should display captive detector supply or established calibration network density. Watch CDSCO inspection readiness timelines as the inflection signal for Indian pharmaceutical demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Supply | Captive silicon drift detector production insulates Hitachi High-Tech from East Asian foundry concentration risk. |
| Factory-Direct Calibration Network Expansion | Bypassing distributor markups captures margin in price-sensitive academic procurement channels. |
| Dual-Pulse Architecture Development | Femtosecond-nanosecond pulse coupling extends light-element detection limits for geological matrices. |
| ISO 17025 Validation Investment | Accreditation capability opens regulated pharmaceutical and environmental testing laboratory verticals. |
| Portable Product Miniaturization | Sub-ten-kilogram fiber-laser systems displace centralized laboratory contracts in Australian iron-ore operations. |
Research Approach
A spread of perspectives from spectroscopy R&D directors, mining operations geologists, pharmaceutical quality-control managers, and environmental remediation contractors converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC instrument-manufacturer filings, EPA method documentation, ISO accreditation registries, and mining industry technical publications. Bottom-up unit shipment estimates and top-down addressable market sizing were triangulated against each other.
Segmentation dimensions modeled include product architecture tier, detection technology type, end-use application vertical, and customer procurement authority structure across the analysis window. CAGRs were derived from slope analysis of replacement-cycle timing, regulatory enforcement calendars, and technology substitution elasticities. Forecast inputs incorporated battery-chemistry supply chain expansion rates and mining capital expenditure intentions.
Underlying assumptions cover EPA and CDSCO enforcement continuity, with deviation risk concentrated in laser-safety classification threshold revisions and RoHS exemption timelines for high-power diode modules. Practitioners should keep alternative scenarios live as semiconductor fabrication capacity allocation and REACH substance restriction scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Analytical Instrumentation Market