
 Solar Roof Tiles Market | 2026-2036
Solar Roof Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Roof Tiles Market Insights
The premium architectural segment is rebalancing away from pure efficiency metrics toward aesthetic integration and building-permit compatibility. Tesla leverages its brand ecosystem to anchor high-end residential demand across North American metro corridors. Meyer Burger sustains European manufacturing scale through specialized crystalline-silicon tile architectures. GAF Energy competes via deep channel control through established roofing contractor networks.
Solar roof tiles are photovoltaic-integrated roofing elements, typically employing monocrystalline or thin-film cells laminated beneath tempered glass or polymer substrates, designed to replace conventional roofing materials while generating grid-tied electricity. Monocrystalline product types command the dominant share where efficiency-per-square-foot drives value in space-constrained retrofits. Thin-film segments are gaining traction in commercial new construction where weight reduction and flexible form factors offset lower conversion rates. BIPV applications concentrate margin pools among architects and builders specifying whole-building energy envelopes rather than add-on panel systems.
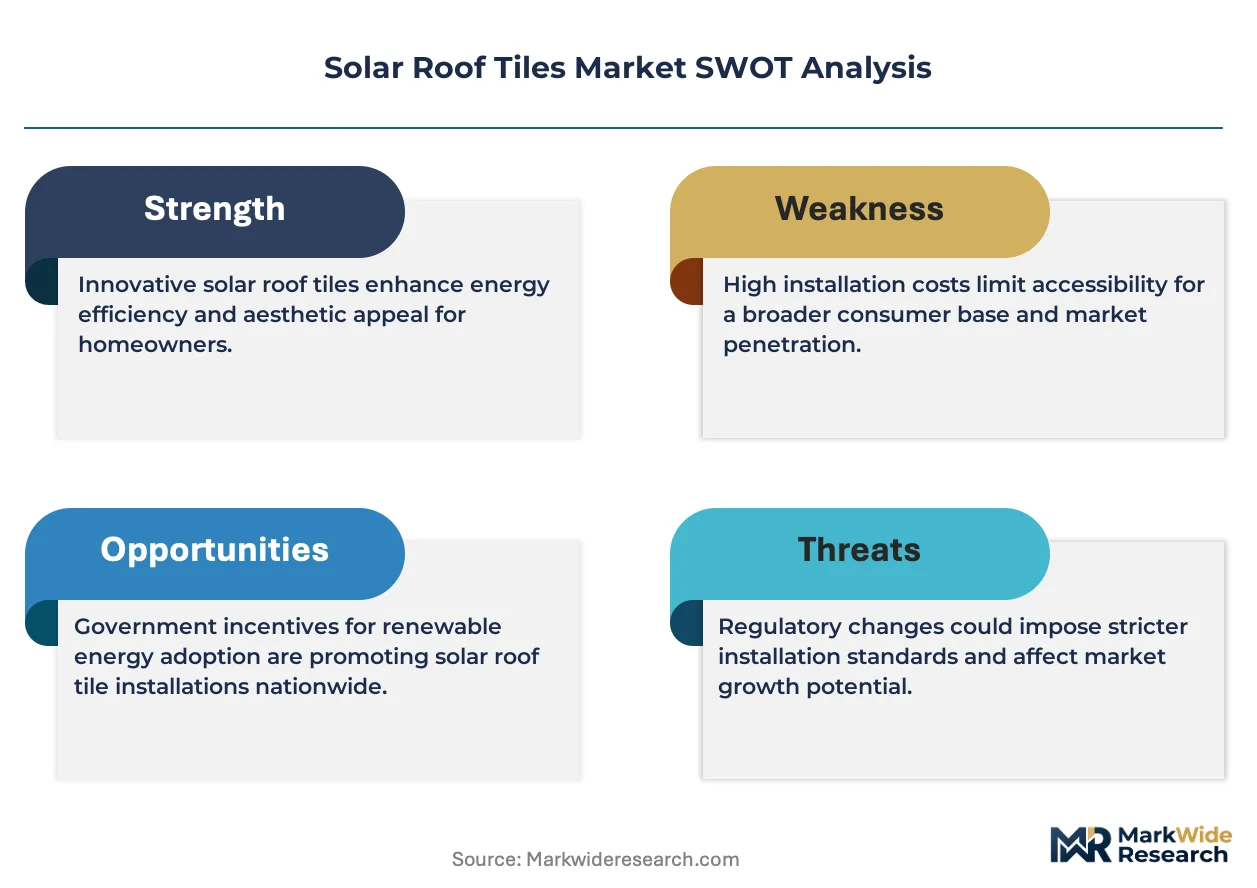
US IRA tax credits, EU Green Deal building renovation mandates, and California Title 24 energy codes collectively reshape product certification requirements and installer licensing across key demand centers. EMA and CE marking standards govern grid-interconnection safety for European-sourced tiles, while NHTSA-adjacent fire-resistance protocols influence polymer substrate approvals in North American jurisdictions. Stakeholders must monitor evolving net-metering rule changes and local permitting streamlining as these determine effective payback periods and contractor adoption velocity.
Market Dynamics
The US Inflation Reduction Act's residential clean energy credits are compressing payback periods and rewiring contractor economics across North American solar roof tile installations. This single policy mechanism is accelerating the shift from retrofit panel attachments to new-construction integrated roofing systems.
Growth Catalysts
- California Title 24 mandates:The state's building energy codes now require solar-ready construction on new homes, directly embedding photovoltaic roofing into standard building permits.
- Monocrystalline efficiency gains:Cell conversion improvements above 20% are eliminating the historical performance gap between tiles and conventional panels in space-constrained residential retrofits.
- Germany's BAFA renovation subsidies:Federal funding for building-integrated photovoltaics is channeling retrofit demand toward aesthetic roof replacements rather than surface-mounted alternatives.
Market Restraints
- Silver and polysilicon input volatility:Raw material price swings in photovoltaic metallization and wafer feedstocks compress manufacturing margins unpredictably.
- Specialized installer scarcity:Dual roofing-electrical certification requirements limit qualified contractor pools in suburban and rural ZIP codes.
- Conventional panel substitution:Mature supply chains and lower per-watt installed costs for rack-mounted systems defend retrofit market share aggressively.
Strategic Opportunities
- Australia's NCC energy efficiency provisions:The National Construction Code's trajectory toward net-zero-ready buildings positions solar roofing as default specification in premium housing developments.
- Thin-film commercial adoption:Weight reduction and substrate flexibility are unlocking flat-roof and membrane-compatible applications in warehouse and logistics construction.
- Utility-scale virtual power plant aggregation:Distributed residential generation is enrolling into grid-balancing revenue streams through software-enabled fleet orchestration.
Industry Challenges
- Permitting timeline fragmentation:AHJ-specific electrical and structural approval processes stretch installation schedules across hundreds of municipal jurisdictions.
- Fire-resistance certification complexity:Polymer substrate variants face divergent testing protocols between NHTSA-influenced North American standards and EU CPR classifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Roof Tiles Market |
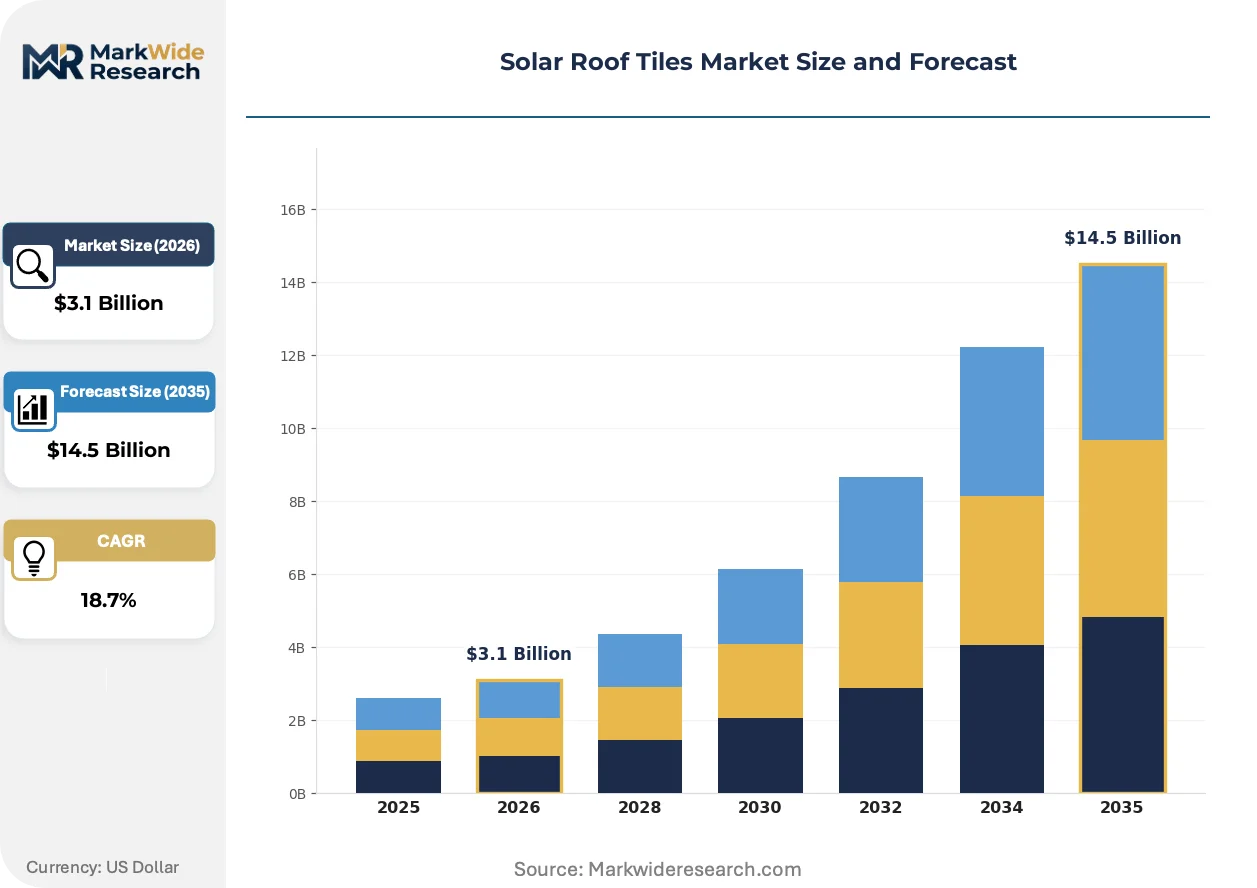
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $14.5 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, BIPV Installation Type: New Construction, Retrofit, Residential, Commercial End User: Homeowners, Builders, Contractors, Architects Material: Silicon, Glass, Metal, Polymer |
| Companies Covered | Roofit.Solar, Onyx Solar, Tesla, SANGOBUILD, Meyer Burger, GAF Energy, Solarstone, TOENERGY, SunRoof International Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Roof Tiles Market Trends and Innovations
Product architecture is pivoting from efficiency-first engineering toward building-code compatibility and aesthetic standardization. This reorientation is compressing development cycles and expanding addressable market segments.
Monocrystalline silicon cell lamination beneath tempered glass substrates is consolidating as the dominant residential architecture. High-end new construction developers in California and Germany are specifying these systems as default roofing materials. The technology is consolidating supplier R&D budgets away from thin-film alternatives and toward crystalline efficiency optimization.
The EU Green Deal's building renovation mandates are tightening embodied-carbon thresholds for construction materials. Solar roof tile manufacturers must now document lifecycle emissions across supply chains to maintain CE marking eligibility. German and Dutch building inspectors are prioritizing products with Environmental Product Declarations in public procurement.
Architect specification behavior is rotating from add-on renewable systems toward whole-building energy envelopes. Design firms in Australia and California are bundling solar roofing into passive house and net-zero certifications from project inception. This shift is displacing post-design panel retrofits in premium residential segments and compressing traditional solar installer channel margins.
Solar Roof Tiles Market Segmentation
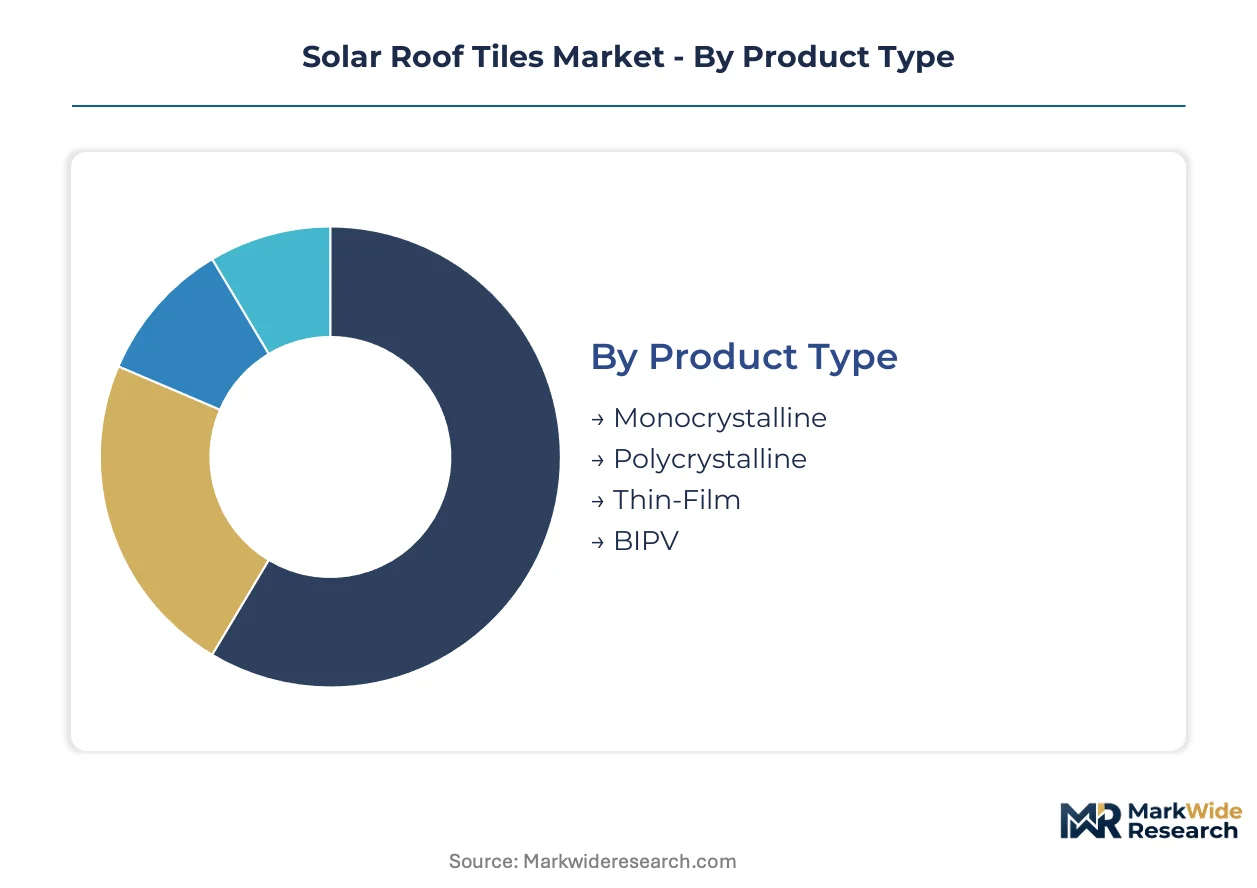
Solar roof tile configurations diverge sharply between performance-optimized residential retrofits and aesthetic-driven new construction specifications. Material choices and installation modalities determine contractor qualification requirements, permitting timelines, and end-user financing structures across distinct addressable markets.
Product Type:
Standardization dominates crystalline silicon architectures while thin-film and BIPV variants demand project-specific engineering customization.
- Monocrystalline:Single-crystal silicon cells laminated beneath tempered glass deliver conversion efficiencies exceeding 20% in space-constrained California and German residential retrofits. Premium housing developers specify these systems where roof area limits total generation capacity.
- Thin-Film:Cadmium telluride and CIGS chemistries deposited on flexible substrates reduce weight loads for commercial membrane roofs. Warehouse construction in Australia's logistics corridors favors these systems where structural load-bearing constraints exclude glass-heavy alternatives.
- Polycrystalline:Multi-crystal silicon formulations balance cost and performance for mid-market residential builders in cost-sensitive suburban developments.
- BIPV:Building-integrated photovoltaic tiles replace conventional roofing materials entirely, serving architects specifying whole-envelope energy systems from project inception.
Most installed capacity flows through Monocrystalline. Expansion is steepest in BIPV.
Installation Type:
Volume concentrates in residential new construction where building codes embed solar-ready requirements into standard permits.
- New Construction:California Title 24 mandates and Australia's NCC efficiency provisions position solar roofing as default specification rather than upgrade option. Developers capture IRA tax credits through integrated system bundling at rough-in stage.
- Residential:Single-family homeowners in Germany's BAFA-subsidized renovation market prioritize aesthetic roof replacements over surface-mounted panels. Permitting streamlining in municipal jurisdictions accelerates adoption velocity.
- Retrofit:Existing structure modifications face structural assessment requirements and electrical service upgrades that extend project timelines.
- Commercial:Flat-roof warehouse and logistics facilities in premium land markets deploy thin-film systems where weight reduction offsets lower conversion efficiency.
New Construction captures the dominant share of annual installations. Retrofit is climbing the fastest as European renovation mandates mature.
End User:
Procurement authority splits between specification-stage architects and execution-stage contractors with divergent technical priorities.
- Builders:Production home developers in California and Australia standardize solar roofing across subdivision portfolios to streamline permitting and capture scale pricing from manufacturers.
- Architects:Design firms bundle BIPV specifications into passive house and net-zero certifications, displacing post-design panel retrofits in premium segments.
- Homeowners:Individual purchasers in Germany's renovation subsidy programs select aesthetic-integrated systems for property value enhancement.
- Contractors:Dual-certified roofing-electrical installers capture margin pools in fragmented suburban and rural service territories where qualified labor scarcity limits competition.
Builders command the largest volume channel. Architects are gaining share fastest as whole-envelope design practices displace add-on procurement.
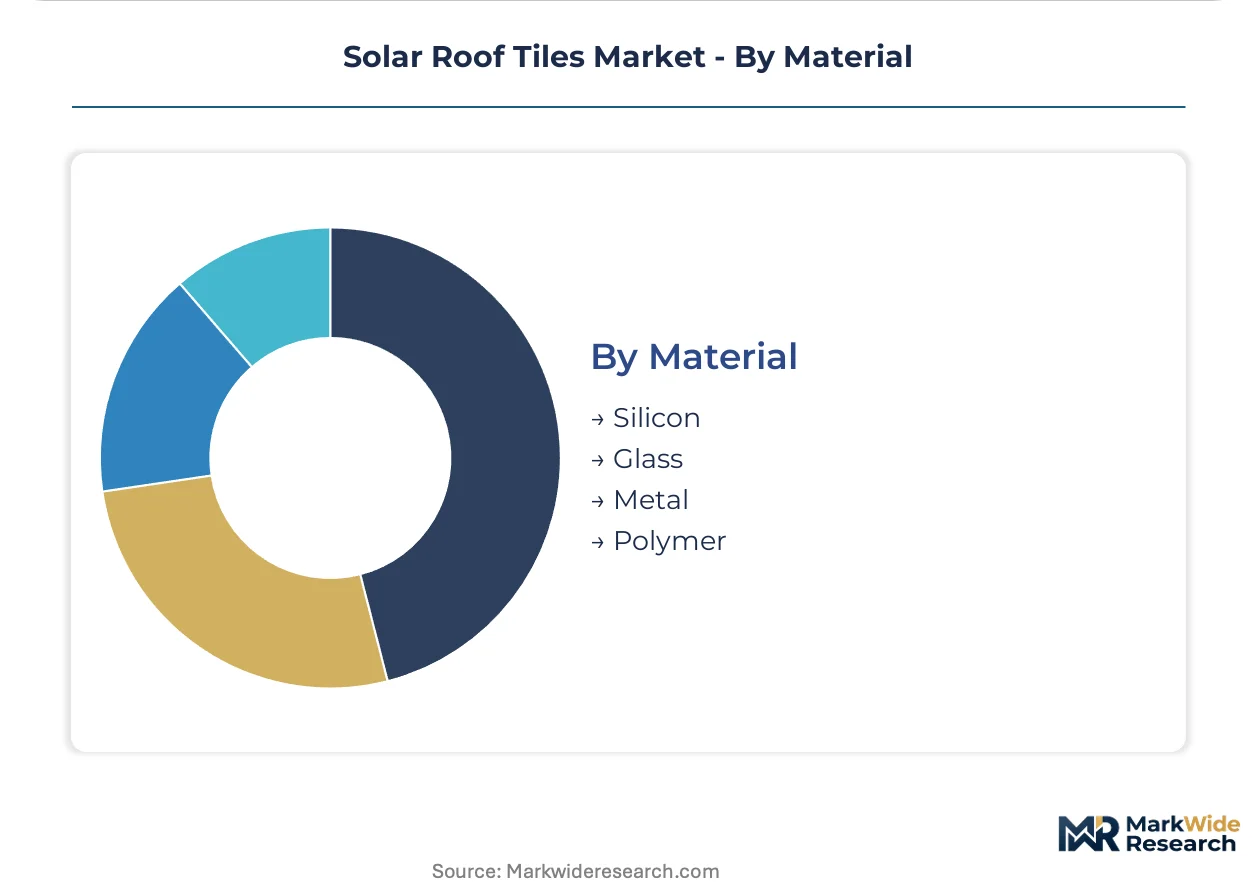
Material:
Substrate selection trades off fire-resistance certification complexity against manufacturing cost structure and installation labor requirements.
- Glass:Tempered glass laminates dominate crystalline silicon architectures, satisfying California and German structural load requirements while enabling 25-year performance warranties.
- Silicon:Wafer-based cell substrates anchor efficiency metrics in space-constrained applications where per-square-foot generation determines project economics.
- Metal:Aluminum and steel backing structures provide mounting integration for standing seam and tile-replacement profiles in commercial applications.
- Polymer:Lightweight thermoplastic substrates face divergent fire-resistance testing between NHTSA-influenced North American protocols and EU CPR classifications, fragmenting supplier certification requirements.
Glass substrates carry the majority of installed capacity. Polymer formulations are expanding most quickly in weight-sensitive commercial membrane applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified roofing-electrical dual trades concentrate in California, Germany, and Australia, creating installation bottlenecks that constrain market velocity in suburban ZIP codes. These workforce clusters align with jurisdictions where building codes embed solar-ready mandates into standard construction permits.
United States
California Title 24 energy codes require solar-ready construction on new single-family homes, embedding photovoltaic roofing into standard building permits. The IRA's residential clean energy credits compress payback periods and rewire contractor economics across North American installations. Los Angeles and San Diego metro corridors anchor demand as production home developers standardize integrated systems across subdivision portfolios.
Germany
Federal BAFA renovation subsidies channel retrofit demand toward aesthetic roof replacements rather than surface-mounted panel alternatives. The EU Green Deal's building renovation mandates tighten embodied-carbon thresholds for construction materials, requiring Environmental Product Declarations for CE marking eligibility. Munich and Stuttgart industrial clusters concentrate crystalline-silicon manufacturing scale through specialized tile architectures.
Australia
The National Construction Code's trajectory toward net-zero-ready buildings positions solar roofing as default specification in premium housing developments. New South Wales and Victoria lead adoption velocity where solar mandates overlap with premium residential construction markets. Sydney and Melbourne architect firms bundle BIPV specifications into passive house certifications from project inception.
China
Dual carbon goals and MIIT industrial policy accelerate domestic photovoltaic manufacturing capacity expansion for building-integrated applications. GB standards govern grid-interconnection safety and fire-resistance protocols for polymer substrate variants. Yangtze River Delta industrial zones concentrate thin-film deposition capacity for commercial membrane roof applications.
Solar Roof Tiles Market Competitive Landscape
Top-tier vendors anchor premium residential segments, while mid-scale specialists compete on channel depth and regional certification expertise. The market structure reflects tiered positioning across brand ecosystem players, European manufacturing scale operators, and roofing contractor network integrators. Three archetypes dominate: ecosystem-anchored premium brands, crystalline-silicon manufacturing specialists, and channel-control-focused roofing incumbents. Competitive moves concentrate on strategic partnerships with production home developers and capacity expansion into building-code-compliant product lines.
Among ecosystem-anchored premium brands, Tesla occupies a position exemplifying high-end residential demand capture across North American metro corridors. Meyer Burger represents European manufacturing scale through specialized crystalline-silicon tile architectures. GAF Energy sits within the channel-control archetype, leveraging established roofing contractor networks for installation velocity.
| Leading Market Players |
|---|
| Roofit.Solar |
| Onyx Solar |
| Tesla |
| SANGOBUILD |
| Meyer Burger |
| GAF Energy |
| Solarstone |
| TOENERGY |
| SunRoof International Holding AB |
| Others |
Pricing and Supply Chain Analysis
Production home developers in California and Australia concentrate procurement volume through standardized subdivision portfolios, anchoring project-based bundled pricing where solar roofing integrates at rough-in stage rather than post-construction upgrade. This buyer concentration compresses contractor margins while rewarding manufacturers with volume scale.
Pricing Analysis
Bundled new-construction specifications diverge sharply from unbundled retrofit quotations. Three-tier pricing structure across premium, standard, and economy levels separates BIPV architect-specified systems from mid-market polycrystalline builder tiers and thin-film commercial membrane applications. Price differentiation hinges on fire-resistance certification grade and dual roofing-electrical installer availability. Cost compression in mid-market residential tiers is intensifying because qualified labor scarcity extends project timelines. Individual homeowners in Germany's BAFA renovation market show highest price sensitivity, while premium California developers prioritize permit compatibility over per-watt economics.
Supply Chain Analysis
Dual-certified roofing-electrical workforce availability constrains manufacturing location decisions in Germany's Stuttgart industrial cluster and Australia's eastern seaboard. Crystalline silicon wafer supply draws from Yangtze River Delta deposition capacity and specialized European lamination facilities. Silver metallization paste and tempered glass substrates feed from established photovoltaic component networks. Single-source vulnerability in monocrystalline wafer supply concentrates risk during polysilicon price volatility cycles. Distribution runs through roofing contractor networks in suburban North American ZIP codes and architect-direct specifications in European premium residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as building-code solar-ready mandates embed photovoltaic roofing into standard construction economics across California, Germany, and Australia.
For Market Incumbents: To counter thin-film commercial substitution in weight-sensitive warehouse applications, crystalline silicon specialists should deepen backward integration into silver metallization supply and expand tempered glass lamination capacity in jurisdictions with streamlined NHTSA-influenced fire-resistance protocols. Certification investment in EU CPR Environmental Product Declarations preserves CE marking eligibility as the EU Green Deal tightens embodied-carbon thresholds. For New Entrants and Emerging Players: Begin with Australia's National Construction Code net-zero trajectory, where premium housing developments in New South Wales and Victoria show penetrable white space for BIPV architect specifications displacing post-design panel retrofits. Target municipal jurisdictions with streamlined permitting for dual-certified installer recruitment. Partner with passive house certification bodies to embed solar roofing into whole-envelope energy design from project inception. For Investors and Strategic Acquirers: Roofing contractor consolidators are the most active acquirer in this space, capturing margin pools in fragmented suburban service territories where qualified labor scarcity limits competition. Long-term viability rests on building-code embedding durability rather than technology disruption cycles. Monitor net-metering rule changes and local permitting streamlining velocity as the primary inflection indicator for contractor adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Workforce Expansion | IRA tax credit capture depends on qualified roofing-electrical installer density in California metro corridors. |
| Environmental Product Declaration Investment | CE marking eligibility under EU Green Deal requires documented lifecycle emissions across German supply chains. |
| Architect Partnership Programs | Sydney and Melbourne design firms bundle BIPV specifications into passive house certifications from project inception. |
| Thin-Film Commercial Capacity Buildout | Weight reduction unlocks warehouse and logistics flat-roof applications in Australia's premium land markets. |
| Utility Virtual Power Plant Enrollment | Software-enabled fleet orchestration enrolls distributed residential generation into grid-balancing revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured production home developer procurement directors, dual-certified roofing-electrical contractors, architect specification leads, and municipal building permit officials across California, Germany, and Australia. Secondary validation drew from IRA implementation guidance, EU Green Deal building renovation mandate texts, California Title 24 energy code filings, and Australia's National Construction Code trajectory documents. Bottom-up installation volume estimates triangulated against top-down manufacturer capacity disclosures.
Segment-weighting distributed value and volume across monocrystalline, thin-film, polycrystalline, and BIPV product architectures, further disaggregated by new construction, residential retrofit, and commercial installation modalities. CAGRs derived from regression analysis of policy incentive trajectories and building permit velocity trends across the analysis window. Forecast inputs incorporated silver and polysilicon commodity price cycles alongside qualified installer pool expansion rates.
Several conditions sit outside the modeled scope, including abrupt net-metering compensation rule reversals, NHTSA fire-resistance protocol amendments, and EU CPR classification divergence. Forecasts reflect assumptions about policy continuity and workforce training program scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Australia Solar Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar Cell Films Market