
 Vietnam Solar Energy Market | 2026-2036
Vietnam Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Solar Energy Market Analytics
A capital-intensity divergence between integrated cell-and-module manufacturers and project-only developers is bifurcating competitive returns in Vietnam. Trina Solar leverages captive wafer capacity to compress module costs and secure utility-scale tenders. Vietnam Sunergy Joint Stock Company anchors its position through domestic assembly lines and proximity to southern province installations. Sao Mai Group competes via agrivoltaic hybrid projects that combine aquaculture with floating solar arrays.
Vietnam solar energy encompasses photovoltaic systems that convert solar radiation into direct-current electricity through semiconductor junctions, typically operating at 15-22% conversion efficiency depending on cell architecture. These installations serve grid-connected generation, industrial self-consumption, and rural electrification across tropical climates with high annual irradiance. Monocrystalline technology leads installed capacity due to superior efficiency density and declining wafer costs, while bifacial modules represent the fastest-growing segment as developers exploit albedo gains from reflective ground surfaces. Utility-scale application dominates pipeline capacity, though rooftop commercial installations command stronger margin pools through avoided-wheeling-charge economics and shorter development cycles.
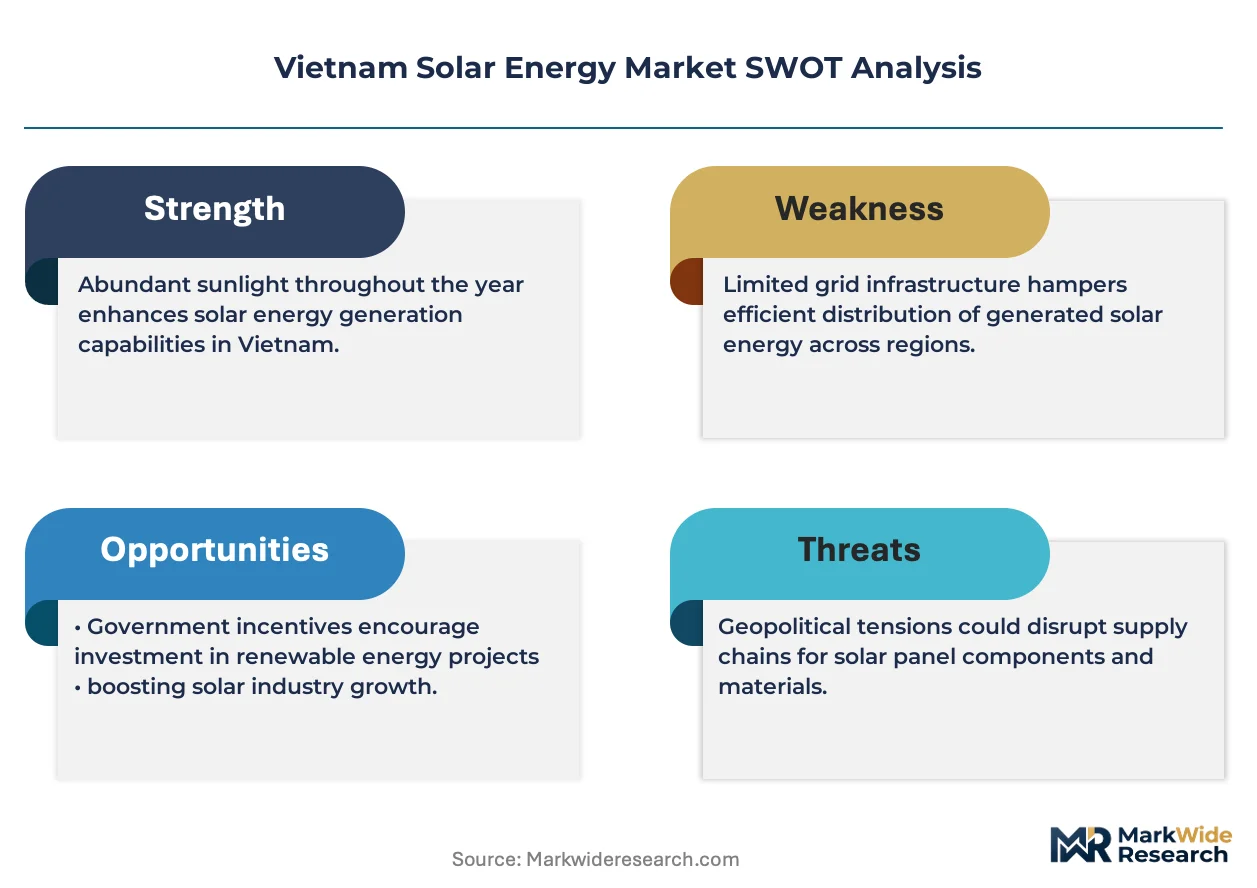
Vietnam's Ministry of Industry and Trade implements power purchase agreement frameworks under the Electricity Law, while the national technical standards QCVN regulate grid connection safety and inverter synchronization requirements. The Prime Minister's Decision 13/2020/QD-TTg establishes feed-in tariff ceilings that directly determine project IRR thresholds and foreign capital commitment timelines. Stakeholders must monitor forthcoming direct power purchase agreement pilot expansions and provincial land-use planning revisions that will determine site bankability and construction timelines.
Market Dynamics
Vietnam's solar market pivots on the expiration window of feed-in tariff guarantees under Decision 13/2020/QD-TTg, compressing developer timelines and forcing rapid procurement of crystalline silicon modules before tariff step-downs take effect.
Growth Catalysts
- Industrial self-consumption mandates:Manufacturing facilities in Dong Nai and Binh Duong provinces deploy rooftop systems to circumvent grid instability and volatile commercial electricity tariffs. Factory clusters now specify solar readiness in new construction permits.
- Decision 13/2020/QD-TTg tariff floors:The Prime Minister's mechanism guarantees purchase prices for grid-connected projects, attracting foreign equity from Singaporean and Thai infrastructure funds into utility-scale developments.
- Ninh Thuan irradiance concentration:Annual solar exposure exceeding 2,300 kWh/m² in coastal provinces enables capacity factors above 22% for fixed-tilt installations, reducing LCOE calculations against northern alternatives.
Market Restraints
- Polysilicon supply concentration:Vietnamese module assemblers depend on Xinjiang and Inner Mongolia ingot sources, exposing project pipelines to US Customs detention orders and forced labor documentation requirements.
- Grid absorption ceilings:EVN's transmission infrastructure in the Central Highlands lacks synchronous condenser capacity to stabilize intermittent solar injection, forcing curtailment during peak generation hours.
- Land-use classification friction:Provincial People's Committees reclassify agricultural zones under Resolution 55/NQ-TW, delaying environmental impact assessments for ground-mounted arrays in rice-cultivation districts.
Strategic Opportunities
- Floating solar on hydropower reservoirs:Da Mi and Tri An dam complexes offer 5,000+ hectares of water surface for bifacial installations, evading land-acquisition disputes while benefiting from evaporative cooling gains.
- Direct power purchase agreement expansion:MOIT's pilot program for industrial consumers to contract generators bypassing EVN wheeling charges opens bilateral contracting for textile and electronics manufacturers.
- Agrivoltaic convergence with dragon fruit cultivation:Binh Thuan farmers deploy elevated arrays providing partial shade for orchard crops, generating dual revenue streams from electricity sales and export horticulture.
Industry Challenges
- SCADA integration with legacy distribution automation:Provincial power companies operate incompatible communication protocols between solar farm inverters and existing feeder management systems, requiring middleware development for each interconnection.
- Construction finance tenor mismatch:Vietnamese commercial banks offer 5-7 year project loans against 20-year PPA durations, forcing developers to source offshore green bonds or multilateral agency guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Solar Energy Market |
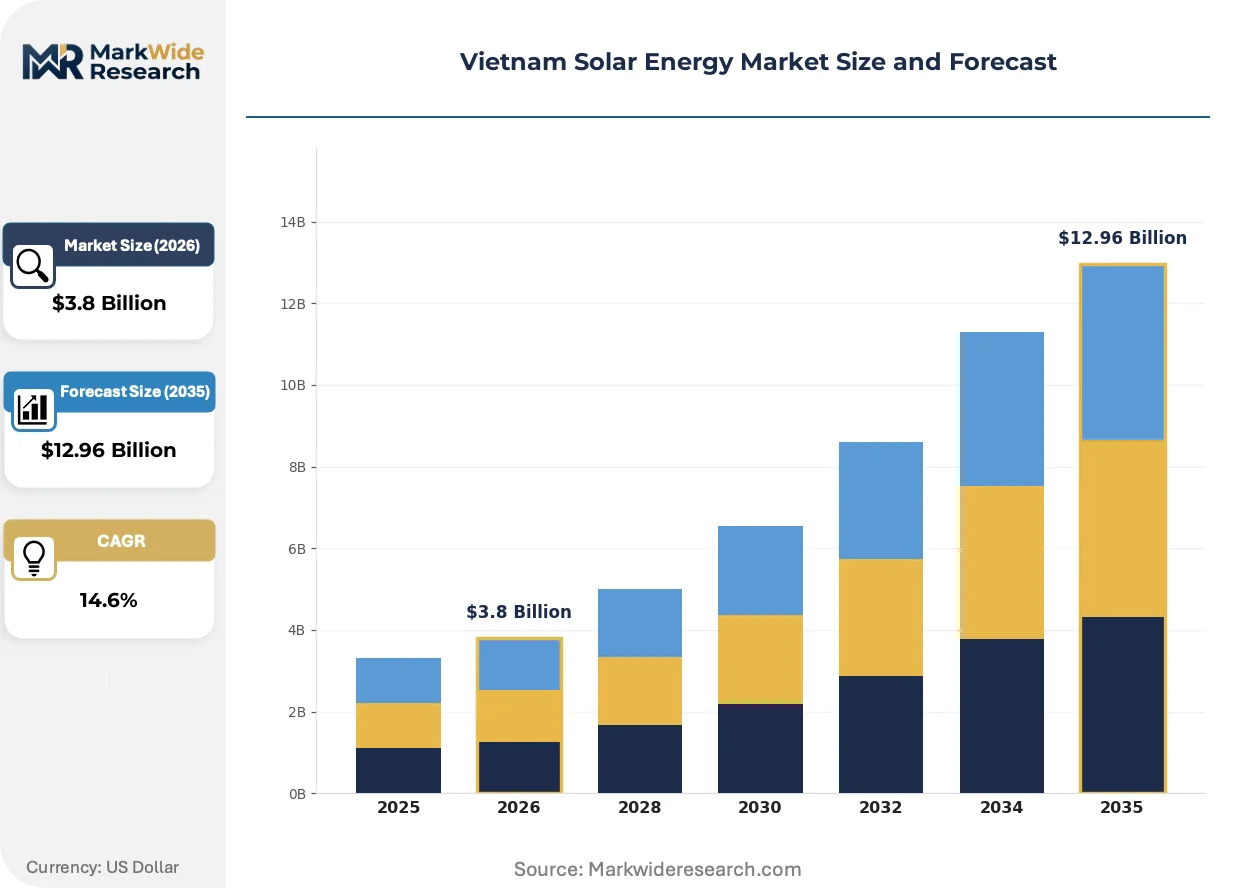
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Utility-Scale, Rooftop, Commercial, Residential End User: Government, Private Sector, Industrial, Agricultural Installation Type: Ground-Mounted, Roof-Mounted, Floating, Hybrid |
| Companies Covered | Trina Solar, Vietnam Sunergy Joint Stock Company, Sao Mai Group, Adani Green Energy, JA Solar Technology, Trung Nam Group, Canadian Solar, First Solar, LONGi Green Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Solar Energy Market Evolving Landscape
Bifacial module architecture and floating platform systems are compressing development constraints in Vietnam's land-scarce southern corridor, while regulatory pilots reshape offtake contracting.
TOPCon cell technology is miniaturizing passivated contact layers to sub-20 nanometer thicknesses, boosting conversion efficiency beyond 24% in mass production. Industrial offtakers in Ho Chi Minh City industrial parks now specify n-type bifacial modules for new rooftop tenders, accepting 8-12% capital cost premiums for enhanced yield density. This efficiency compression is enabling viable project economics on constrained warehouse roof areas previously deemed sub-scale.
MOIT's draft circular on direct power purchase agreements expands eligibility beyond pilot participants to all voltage classes above 22 kV, permitting electronics manufacturers in Bac Ninh to contract solar farms without EVN intermediation. The policy shift fragments traditional single-buyer market structure and forces provincial grid operators to develop wheeling charge methodologies. Foreign-invested factories with renewable energy targets constitute the primary demand segment accelerating bilateral PPA negotiations.
Energy storage co-location is altering procurement specifications for utility-scale tenders, with developers bundling lithium iron phosphate systems to satisfy EVN's ramp-rate requirements for grid stability. Industrial buyers now evaluate solar-plus-storage proposals against diesel backup alternatives for mission-critical semiconductor fabrication facilities. This hybrid configuration is most visible in Bac Giang and Thai Nguyen provinces, where Samsung and Foxconn suppliers require sub-50 millisecond power quality guarantees.
Vietnam Solar Energy Market Segmentation
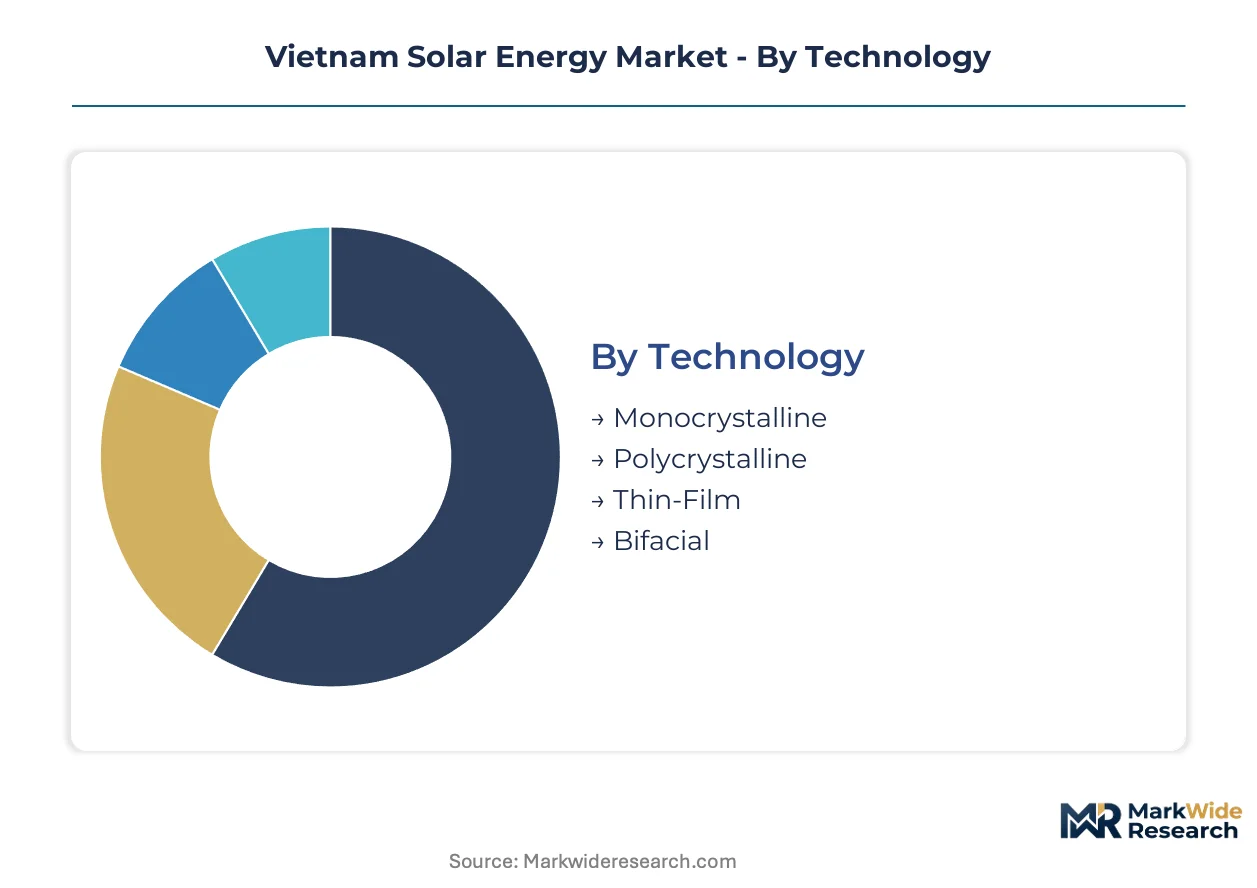
Technology selection determines project IRR thresholds and land-use efficiency across Vietnam's irradiance-dense southern corridor. Application and installation-type choices reflect competing pressures from feed-in tariff deadlines, grid absorption limits, and land-acquisition friction.
Technology:
Monocrystalline and bifacial architectures face intensifying substitution pressure from TOPCon and heterojunction alternatives as efficiency premiums compress module cost differentials.
- Monocrystalline:Single-crystal silicon ingots cut into wafers with 20-22% conversion efficiency in standard test conditions. Demand concentrates in Binh Thuan and Ninh Thuan utility-scale tenders where land scarcity rewards maximum output density per hectare.
- Bifacial:Double-glass modules capturing direct and reflected irradiance from albedo surfaces, achieving 10-20% yield gains over monofacial equivalents. Industrial parks in Dong Nai specify bifacial for rooftop installations where concrete surfaces amplify rear-side generation.
- Polycrystalline:Multi-crystal silicon cells with lower efficiency but historically lower wafer costs, now retreating to price-sensitive rural electrification projects.
- Thin-Film:Cadmium-telluride or CIGS layers deposited on flexible substrates, deployed in floating solar arrays where weight constraints override efficiency priorities.
Monocrystalline anchors the volume base while bifacial gains share at the steepest rate.
Application:
Cost-tier stratification separates premium bilateral PPA opportunities from standardized feed-in tariff submissions.
- Utility-Scale:Grid-connected installations exceeding 50 MW capacity requiring MOIT licensing and EVN interconnection agreements. Ninh Thuan province hosts the densest concentration as developers exploit coastal irradiance and available flat terrain.
- Rooftop:Distributed generation systems on commercial and industrial buildings, typically 1-10 MW, circumventing transmission bottlenecks through behind-the-meter consumption. Bac Ninh electronics manufacturers drive demand via renewable energy procurement mandates.
- Commercial:Mid-scale systems serving retail and office facilities, characterized by shorter development cycles and avoided-wheeling-charge economics.
- Residential:Sub-10 kW installations on single-family dwellings, limited by household financing access and net-metering administrative complexity.
Utility-scale commands the capital deployment while rooftop expands most quickly under industrial self-consumption incentives.
End User:
Customer-type fragmentation reflects divergent procurement capabilities and risk tolerance across public and private balance sheets.
- Industrial:Manufacturing facilities with 24-hour load profiles and renewable energy targets, negotiating direct PPAs or self-building captive capacity. Textile and semiconductor clusters in Binh Duong and Thai Nguyen dominate procurement volumes.
- Government:State-owned enterprises and provincial authorities developing public land resources through competitive bidding rounds.
- Private Sector:Commercial real estate developers and independent power producers seeking tariff-guaranteed revenue streams.
- Agricultural:Dragon fruit and aquaculture operators deploying agrivoltaic configurations for dual revenue streams.
Industrial offtakers anchor the volume base while agricultural deployments climb the fastest as land-use restrictions intensify.
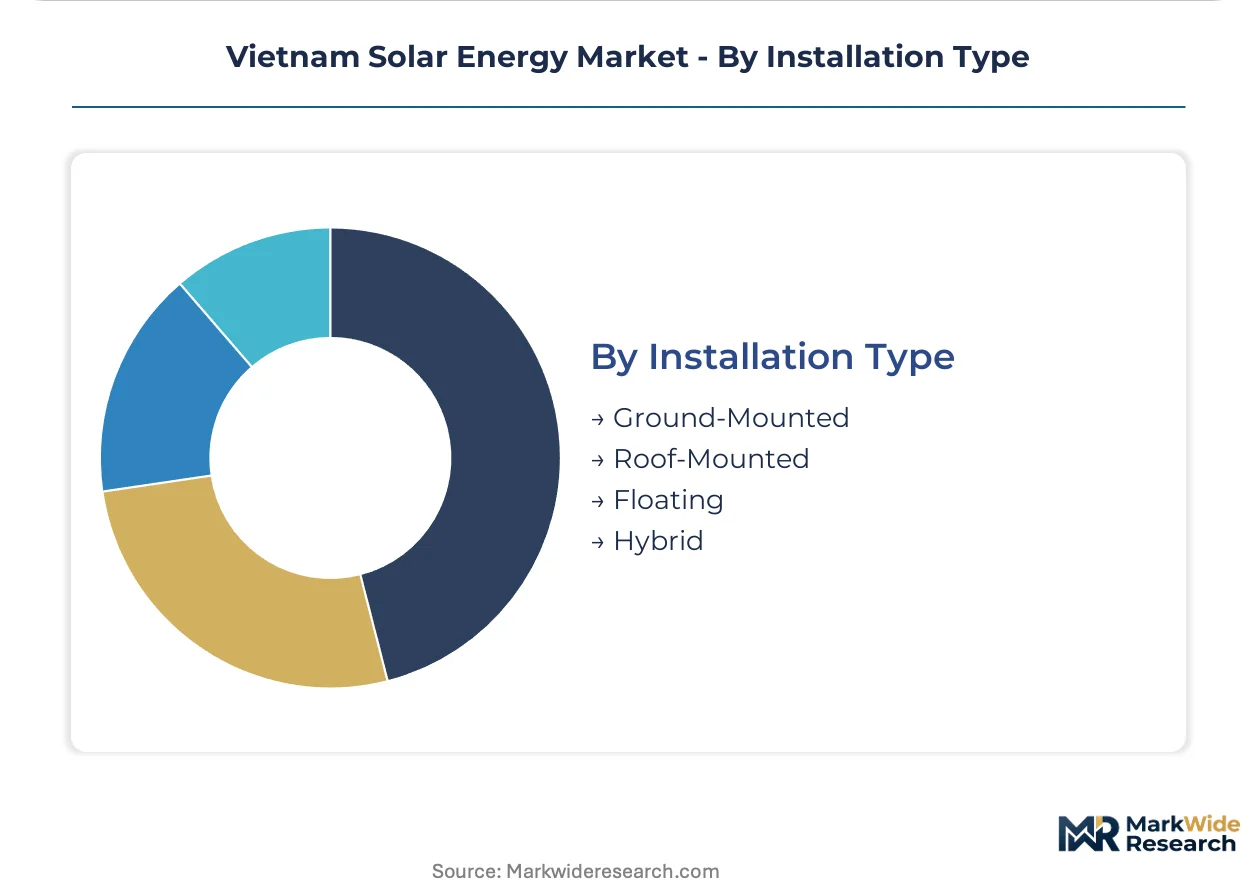
Installation Type:
Geography and site availability dictate installation architecture, with water-based and hybrid systems displacing ground-mounted alternatives where land competition escalates.
- Floating:Pontoon-mounted arrays on hydropower reservoirs and irrigation lakes, exploiting evaporative cooling gains and eliminating land-acquisition risk. Da Mi and Tri An dam complexes represent the primary development pipeline.
- Ground-Mounted:Fixed-tilt or tracking systems on agricultural or barren land, facing intensifying provincial zoning reclassification under Resolution 55/NQ-TW.
- Roof-Mounted:Ballasted or penetrating systems on industrial and commercial structures, constrained by structural load assessments and fire safety protocols.
- Hybrid:Co-located solar-plus-storage or agrivoltaic configurations bundling generation with ancillary services or agricultural output.
Ground-mounted retains the installed base while floating solar shows the steepest expansion trajectory as reservoir licensing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's solar module imports from Chinese wafer foundries exceed domestic assembly capacity by a widening margin, while exports of Vietnamese-assembled panels to ASEAN markets remain constrained by certificate-of-origin documentation requirements.
Ninh Thuan Province
Coastal irradiance exceeding 2,300 kWh/m² annually drives utility-scale development concentrated along the Ca Na corridor. Decision 13/2020/QD-TTg tariff guarantees expire in compressed windows, forcing developers to accelerate construction timelines. The Thanh Hai industrial cluster hosts the densest concentration of fixed-tilt installations feeding into EVN's 220 kV transmission backbone.
Binh Thuan Province
Dragon fruit agrivoltaic hybrids expand across Tuy Phong and Ham Thuan Nam districts, combining elevated panel arrays with export horticulture operations. Provincial People's Committees reclassify agricultural zones under Resolution 55/NQ-TW, creating permitting friction for ground-mounted alternatives. The Phan Ri Cua port logistics zone anchors module staging and construction equipment marshaling.
Dong Nai Province
Industrial self-consumption mandates from manufacturers in Bien Hoa and Long Thanh industrial parks accelerate rooftop procurement. Factory clusters now specify solar readiness in new construction permits issued by provincial planning departments. The Amata and Long Binh industrial zones command premium installation densities due to 24-hour load profiles from electronics assembly operations.
Binh Duong Province
Textile and footwear manufacturers in Thuan An and Di An deploy captive rooftop systems to circumvent grid instability and volatile commercial tariffs. The Vietnam-Singapore Industrial Park hosts the highest concentration of behind-the-meter installations with direct PPA structures. Provincial grid operators develop wheeling charge methodologies to accommodate bilateral contracting bypassing EVN intermediation.
Bac Ninh Province
Samsung and Foxconn supplier ecosystems drive demand for solar-plus-storage configurations guaranteeing sub-50 millisecond power quality. MOIT's draft circular expanding direct PPA eligibility to all voltage classes above 22 kV accelerates bilateral negotiations. The Yen Phong and Que Vo industrial zones anchor the northern corridor's fastest-growing procurement segment.
Vietnam Solar Energy Market Competitive Landscape
Concentration sits with integrated cell-and-module manufacturers possessing captive wafer capacity, while project-only developers compete on development velocity and land-access relationships. Chinese-headquartered producers with Vietnamese assembly operations anchor the supply base, competing against domestic fabricators leveraging proximity to southern province installations. Strategic archetypes separate integrated manufacturers, domestic assemblers, and hybrid project developers combining generation with agricultural or aquaculture revenue streams. Competitive moves center on securing utility-scale tender awards before tariff step-downs and expanding floating solar portfolios on hydropower reservoirs.
Among Chinese-originated integrated manufacturers, Trina Solar and JA Solar Technology occupy positions exemplifying captive wafer-to-module cost compression strategies. Vietnam Sunergy Joint Stock Company anchors the domestic assembler archetype through proximity advantages in southern province installations. Sao Mai Group represents the hybrid developer model combining aquaculture operations with floating solar arrays on reservoir surfaces.
| Leading Market Players |
|---|
| Trina Solar |
| Vietnam Sunergy Joint Stock Company |
| Sao Mai Group |
| Adani Green Energy |
| JA Solar Technology |
| Trung Nam Group |
| Canadian Solar |
| First Solar |
| LONGi Green Energy |
| Others |
Value Network & Pricing Analysis
Long-term feed-in tariff offtakes under Decision 13/2020/QD-TTg lock in both polysilicon supply access and project IRR visibility for Vietnamese developers racing construction timelines before tariff step-downs take effect.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium TOPCon bifacial, standard monocrystalline, and economy polycrystalline tiers. Price differentiation rests on cell efficiency grades and IEC 61215 certification tiers, with premium n-type modules commanding capital cost premiums of 8-12%. Cost compression in standard monocrystalline tiers is intensifying because Chinese wafer foundries are expanding ingot capacity, while rooftop commercial segments show highest price sensitivity due to constrained project scales.
Supply Chain Analysis
China and Vietnam anchor crystalline silicon module assembly, with Xinjiang and Inner Mongolia feeding polysilicon ingot sources that Vietnamese fabricators draw from for domestic production lines. Raw material dependencies center on metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames for module framing. Supply chain risk concentrates on US Customs detention orders targeting forced labor documentation from Xinjiang sources. Distribution runs through provincial EVN interconnection queues and EPC contractor procurement channels serving southern province utility-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's solar market represents a platform-economics inflection as direct power purchase agreement pilots fragment the traditional single-buyer structure and enable bilateral contracting between generators and industrial offtakers.
For Market Incumbents: Fortify captive wafer-to-module cost compression through backward integration into polysilicon sourcing or binding long-term ingot supply agreements with Xinjiang and Inner Mongolia producers. Defend utility-scale tender positions by accelerating construction timelines ahead of Decision 13/2020/QD-TTg tariff expirations, while diversifying into floating solar portfolios on Da Mi and Tri An reservoirs to evade land-acquisition friction.
For New Entrants and Emerging Players: SCADA integration services for legacy provincial distribution automation represent a critical service-layer gap where incumbents under-serve, creating entry paths for middleware specialists capable of protocol translation between solar farm inverters and EVN feeder management systems. Target Bac Ninh and Thai Nguyen electronics manufacturing clusters for solar-plus-storage configurations, leveraging direct PPA eligibility expansion to bypass EVN wheeling charges and capture premium power quality guarantees.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cell-and-module manufacturers with captive wafer capacity and long-term industrial offtake contracts, offering visibility through tariff regime transitions. Acquisition targets should emphasize developers with licensed reservoir surface rights for floating solar expansion and established provincial land-access relationships. The signal to watch is MOIT circular finalization expanding direct PPA eligibility beyond pilot participants, which would accelerate bilateral contracting fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Secures ingot supply from Xinjiang and Inner Mongolia against US detention risk. |
| Floating Solar Capacity Buildout | Exploits Da Mi and Tri An reservoir licensing to evade Resolution 55 land reclassification. |
| Direct Power Purchase Agreement | Bypasses EVN wheeling charges for Bac Ninh and Thai Nguyen electronics manufacturers. |
| Solar-Plus-Storage Configuration | Satisfies EVN ramp-rate requirements and Samsung supplier power quality guarantees. |
| Agrivoltaic Project Development | Combines Binh Thuan dragon fruit cultivation with elevated panel dual revenue streams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators, validated against secondary sources including EVN interconnection databases, MOIT regulatory filings, provincial land-use planning records, and customs import data for module and wafer trade flows. Bottom-up project pipeline aggregation was triangulated with top-down market sizing from electricity generation statistics.
Across the analysis window, forecasts modeled capacity deployment by technology architecture, application scale tier, end-user segment, and installation type, with CAGRs derived from regression analysis of historical installation velocity against tariff deadline compression effects and industrial procurement mandate expansion. Key inputs included irradiance mapping data for Ninh Thuan and Binh Thuan provinces, EVN transmission absorption capacity assessments, and provincial zoning reclassification timelines under Resolution 55/NQ-TW.
Underlying assumptions cover feed-in tariff guarantee continuity, polysilicon supply chain stability, and grid interconnection queue processing rates, with deviation risk concentrated in US Customs enforcement actions on forced labor documentation and provincial People's Committee land-use reclassification timing. Recalibration cycles align with material shifts in MOIT direct PPA circular finalization and EVN transmission infrastructure investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Solar Module Market