
 China Renewable Energy Market | 2026-2036
China Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
China Renewable Energy Market Outlook
The split between premium monocrystalline PERC and commodity polycrystalline modules is repositioning procurement strategies across China's utility sector. LONGi Green Energy Technology Co., Ltd. dominates high-efficiency wafer supply through in-house pulling and slicing capacity. JinkoSolar Holding Co., Ltd. competes on TOPCon cell conversion efficiency at mass-production scale. BYD Company Limited anchors grid-scale storage with blade battery architecture and vertical cell-to-pack integration.
China renewable energy encompasses solar photovoltaic, wind turbine, hydroelectric, and bioenergy systems engineered for electricity generation, thermal conversion, or mechanical power extraction, with crystalline silicon modules typically achieving 21-24% cell efficiency and wind turbines scaling from 2.5 MW onshore units to 16 MW offshore platforms. Solar Power leads installed capacity additions but faces margin compression from polysilicon oversupply cycles. Wind Power captures offshore expansion premiums along the Fujian and Jiangsu coastlines where water depths exceed 40 meters. Hydropower occupies baseload stability roles in southwestern provinces with limited new large-site availability.
MIIT governs equipment manufacturing standards through GB certification requirements, while NEEA administers renewable portfolio obligations and grid integration codes that determine project bankability. MEE enforces environmental impact assessments for utility-scale developments, particularly wind farms in ecologically sensitive grassland corridors. Stakeholders must track dispatch priority rule revisions and carbon market linkage mechanisms as these instruments reshape project revenue stacking.
Market Dynamics
NEEA's tightening dispatch priority rules and MIIT's GB certification revisions are compressing project development timelines while forcing asset owners to reconfigure revenue stacking models around carbon market linkage mechanisms.
Growth Catalysts
- Dual Carbon Goals:Beijing's 2030 peak and 2060 neutrality mandates hardwire renewable capacity additions into provincial five-year plans, locking in procurement quotas for state-grid utilities.
- Blade Battery Architecture:Cell-to-pack integration at grid-scale storage facilities is slashing system costs and accelerating 4-hour duration deployments in Jiangsu frequency regulation markets.
- Offshore Wind Premiums:Fujian and Jiangsu coastal zones with 40-meter water depths command higher feed-in tariffs, attracting specialized installation fleets and high-capacity turbine orders.
Market Restraints
- Polysilicon Oversupply Cycles:Commodity-grade silicon feedstock price volatility erodes module manufacturer margins and destabilizes long-term supply contracts for utility-scale developers.
- Ecological Corridor Restrictions:MEE enforcement of environmental impact assessments blocks wind farm permitting in Inner Mongolian grassland zones, constraining greenfield site availability.
- Grid Integration Queues:Provincial transmission capacity shortages in Guangdong create multi-year interconnection backlogs that delay commercial operation dates for solar and wind assets.
Strategic Opportunities
- Western Hydrogen Coupling:Sichuan and Yunnan hydropower surplus is redirecting toward electrolyzer-fed green ammonia exports, creating new offtake contracts for stranded renewable generation.
- Industrial Park Microgrids:NEEA efficiency mandates are unlocking behind-the-meter solar-plus-storage deployments for Jiangsu textile and Guangdong electronics manufacturing clusters.
- Carbon Market Linkage:National ETS expansion to cover power sector emissions is enabling renewable asset owners to stack carbon credit revenue atop electricity sales.
Industry Challenges
- Grid Code Compliance:NEEA's revised fault-ride-through and frequency response standards demand costly inverter retrofits for existing wind and solar fleets.
- Technical Talent Scarcity:Offshore turbine installation and floating foundation engineering expertise concentrates among a handful of state-owned construction consortia, bottlenecking project execution.
- Interprovincial Transmission Rights:Legacy dispatch hierarchies favor coal baseload in receiving provinces, complicating renewable power purchase agreement structuring for cross-border sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Renewable Energy Market |
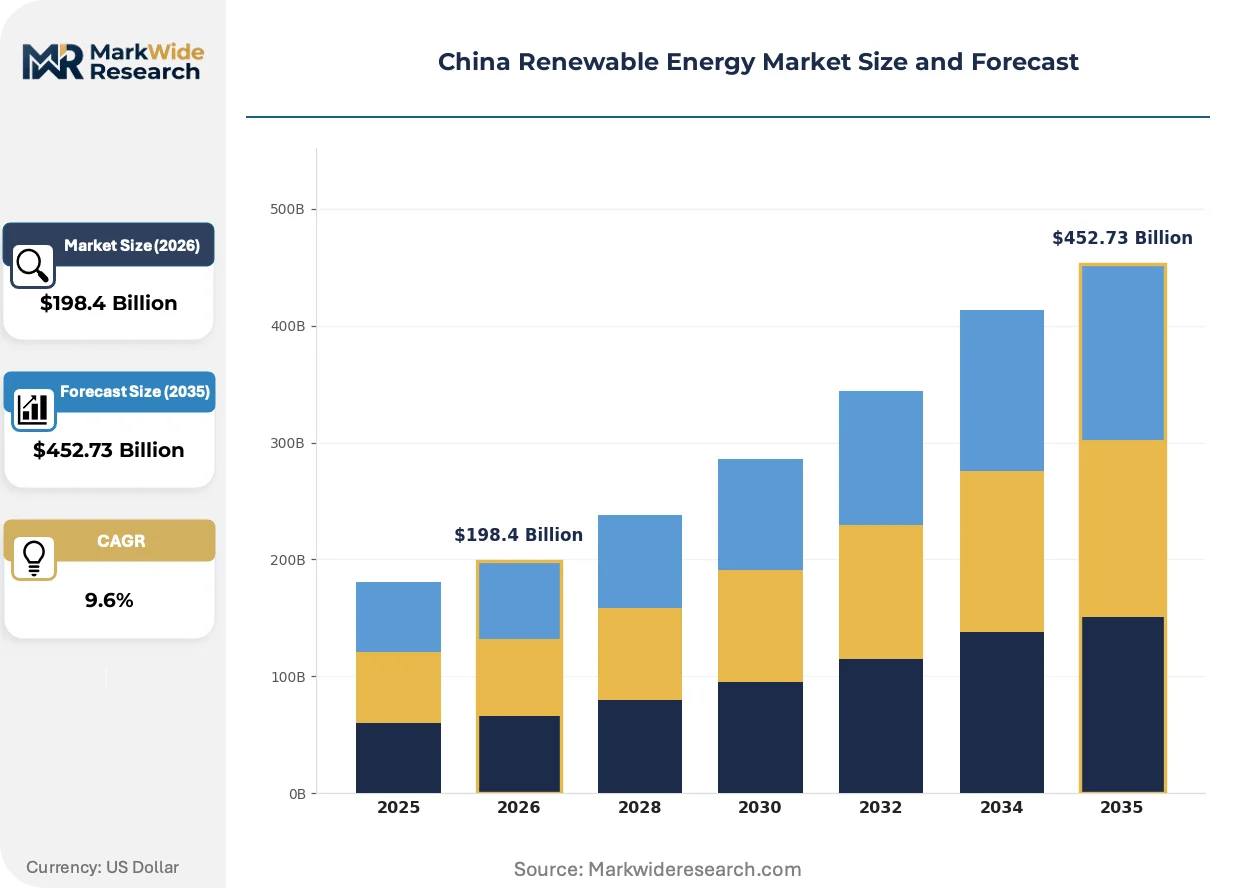
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $452.73 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Power, Wind Power, Hydropower, Biomass Energy Application: Power Generation, Heating, Transportation, Industrial End User: Utilities, Commercial, Residential, Government Service Type: Installation, Maintenance, Consulting, Equipment Supply |
| Companies Covered | Contemporary Amperex Technology Co., Limited, BYD Company Limited, LONGi Green Energy Technology Co., Ltd., Sungrow Power Supply Co., Ltd., Trina Solar Co., Ltd., Sinohydro Corporation, JinkoSolar Holding Co., Ltd., JA Solar Technology Co., Ltd., Risen Energy Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Renewable Energy Market Strategic Shifts
Technology convergence between power electronics and battery management systems is collapsing traditional boundaries between generation and storage assets, while regulatory pressure on dispatch flexibility accelerates software-defined grid integration.
TOPCon cell architecture is decentralizing the historical silicon supply chain by enabling thinner wafer processing and lower-temperature manufacturing, cutting polysilicon intensity per watt. Tier-one module houses in Jiangsu and Anhui are retrofitting PERC lines to capture the efficiency gain without full greenfield capex. The structural consequence is compressing tier-two poly-Si dependent manufacturers into contract assembly roles.
MIIT's GB/T 36276-2018 battery safety standard revision is mandating thermal runaway propagation testing for all grid-connected storage systems, forcing pack redesigns and fire suppression integration. Domestic cell suppliers are consolidating testing partnerships with state-affiliated certification bodies to accelerate approval timelines. Energy storage integrators in Guangdong and Shandong face the steepest compliance cost escalation given their project concentration.
Provincial utilities are consolidating procurement through centralized framework agreements rather than project-by-project tenders, concentrating supplier selection power with State Grid and Southern Grid procurement centers. Long-term service and O&M clauses are bundling into EPC contracts, displacing standalone aftermarket providers. This pattern is most visible in Inner Mongolia and Xinjiang where ultra-high-voltage transmission projects require unified equipment standards across multi-gigawatt portfolios.
China Renewable Energy Market Segmentation
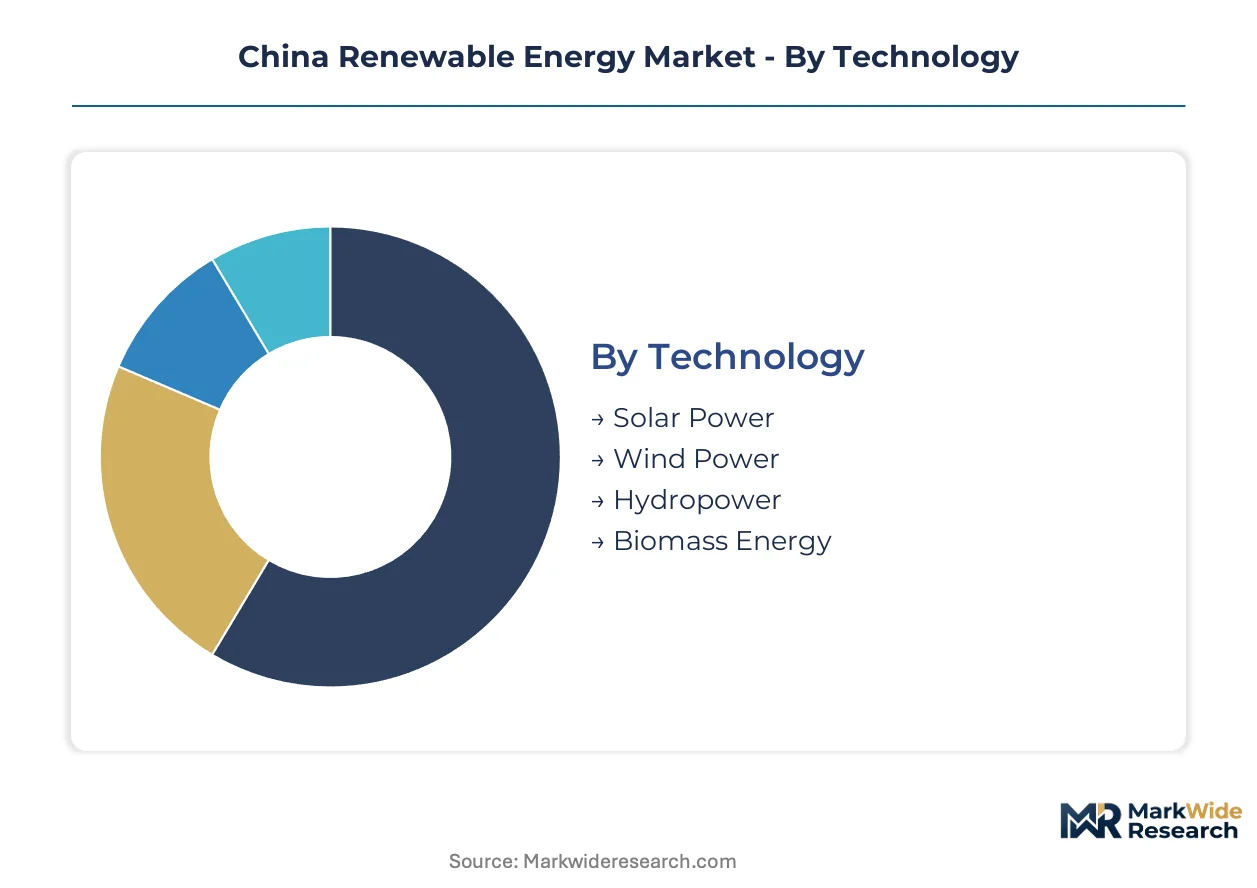
Technology integration depth determines procurement patterns across China's renewable sector, with grid-scale assets demanding bundled service contracts while distributed systems favor modular equipment supply. Provincial utilities and industrial clusters exhibit divergent buying behaviors that reshape segment prioritization.
Technology:
Standalone generation assets dominate utility procurement, while embedded hybrid systems penetrate industrial microgrids and building-integrated applications.
- Solar Power:Crystalline silicon modules achieve 21-24% cell efficiency through PERC and TOPCon architectures. Jiangsu and Anhui manufacturing clusters supply both utility-scale ground-mount projects and distributed rooftop installations for Guangdong electronics factories facing NEEA efficiency mandates.
- Wind Power:Onshore turbines scale from 2.5 MW units in northern plains to 16 MW offshore platforms along Fujian and Jiangsu coastlines where water depths exceed 40 meters. Feed-in tariff premiums attract specialized installation fleets to these zones.
- Hydropower:Southwestern Sichuan and Yunnan baseload plants provide grid stability with limited new large-site availability. Surplus generation increasingly couples to electrolyzer-fed green ammonia export contracts.
- Biomass Energy:Agricultural residue conversion systems concentrate in Shandong and Henan grain-producing regions. MEE environmental assessments constrain project permitting in ecologically sensitive corridors.
Volume placements concentrate in Solar Power; the faster expansion belongs to Wind Power.
Application:
Cost tier stratification separates capital-intensive grid infrastructure from operational expenditure-driven behind-the-meter deployments.
- Power Generation:Grid-scale solar and wind farms feed ultra-high-voltage transmission lines to coastal demand centers. State Grid and Southern Grid procurement centers consolidate multi-gigawatt framework agreements with unified equipment standards.
- Heating:District heating networks in northern provinces integrate geothermal and biomass thermal conversion. Industrial process heat applications in Jiangsu textile clusters drive solar thermal plus storage hybridization.
- Transportation:EV charging infrastructure expansion couples with renewable generation in urban agglomerations. Battery swapping stations for commercial fleets create distributed storage nodes.
- Industrial:Manufacturing parks deploy captive solar-plus-storage microgrids under NEEA dispatch flexibility requirements. Guangdong electronics and Jiangsu chemical facilities lead procurement.
Revenue concentration sits with Power Generation; Industrial applications are climbing the fastest.
End User:
Customer type determines contract structure, with state-owned utilities favoring long-term service bundles and private commercial buyers prioritizing equipment ownership.
- Utilities:Provincial grid operators execute centralized procurement through State Grid and Southern Grid frameworks. Carbon market linkage mechanisms enable revenue stacking atop electricity sales.
- Commercial:Manufacturing clusters and data centers pursue behind-the-meter solar-plus-storage under efficiency mandates. Jiangsu textile and Guangdong electronics sectors anchor demand.
- Residential:Distributed rooftop installations concentrate in affluent eastern provinces with net metering access. Financing constraints limit penetration in lower-tier cities.
- Government:Public building retrofits and municipal infrastructure projects follow green procurement guidelines. Dual carbon goal alignment drives budget allocation.
Contract value concentrates with Utilities; Commercial deployment is gaining share fastest.
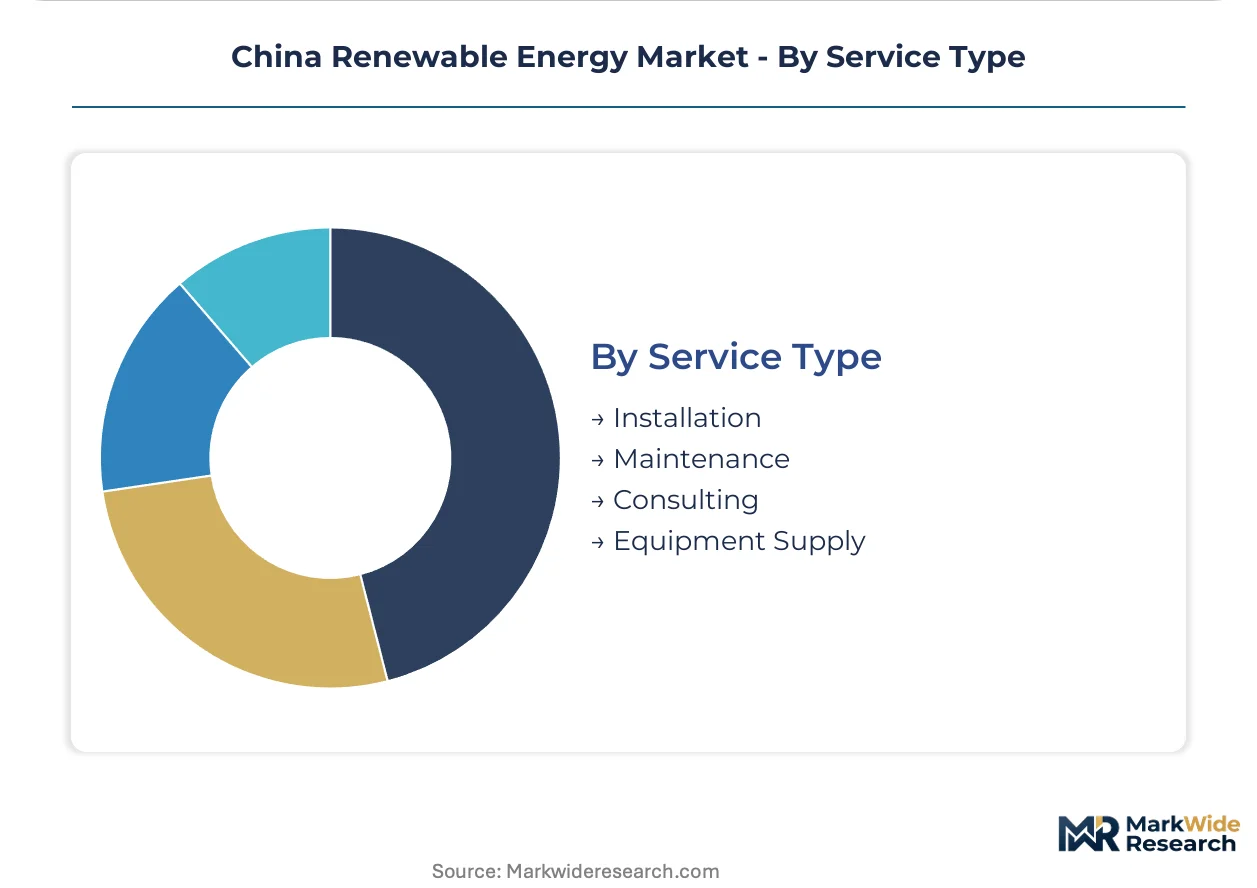
Service Type:
Supply concentration favors integrated EPC providers over standalone service specialists as procurement consolidates.
- Installation:Grid-scale project execution demands specialized offshore turbine fleets and high-voltage transmission expertise. State-owned construction consortia bottleneck capacity in floating foundation engineering.
- Maintenance:Long-term O&M clauses bundle into EPC contracts, displacing standalone aftermarket providers. Predictive analytics integration reduces downtime for utility-scale assets.
- Consulting:Grid code compliance advisory and carbon credit monetization support project bankability. MIIT GB certification navigation requires regulatory expertise.
- Equipment Supply:Module and inverter manufacturers face margin compression from polysilicon oversupply cycles. Blade battery architecture suppliers capture grid-scale storage premiums.
Revenue pools concentrate in Equipment Supply; Maintenance services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors China's renewable energy procurement through its ultra-high-voltage transmission corridors and offshore wind installations along the Yellow Sea coastline.
Inner Mongolia
Wind and solar resource abundance drives multi-gigawatt project development across the grassland corridor. MEE environmental impact assessments constrain permitting in ecologically sensitive zones. Hohhot and Ordos manufacturing clusters supply tower components and polysilicon feedstock to eastern demand centers.
Guangdong
Provincial grid operators face transmission capacity shortages that create multi-year interconnection backlogs for new assets. NEEA dispatch flexibility mandates accelerate behind-the-meter solar-plus-storage deployments. Shenzhen and Dongguan electronics manufacturing parks anchor industrial microgrid demand under efficiency regulations.
Sichuan
Southwestern hydropower surplus increasingly couples to electrolyzer-fed green ammonia export contracts. Dual carbon goal alignment redirects stranded renewable generation toward hydrogen offtake agreements. Chengdu industrial corridor hosts battery manufacturing and power electronics assembly operations.
Fujian
Offshore wind premiums attract specialized installation fleets to coastal zones where water depths exceed 40 meters. Feed-in tariff structures favor high-capacity turbine orders from state-owned developer consortia. Xiamen and Fuzhou port infrastructure supports floating foundation component fabrication.
China Renewable Energy Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and certification compliance. State-owned construction consortia bottleneck capacity in offshore installation and floating foundation engineering. Three archetypes dominate: vertically integrated cell-to-pack specialists, module houses with in-house wafer pulling capacity, and grid-scale storage integrators with captive battery architectures. Competitive moves concentrate on strategic partnerships for ultra-high-voltage project bundling and backward integration into polysilicon refining.
Within the premium-tier vector, LONGi Green Energy Technology Co., Ltd. and BYD Company Limited exemplify divergent specialization paths. LONGi occupies a position tied to high-efficiency wafer supply chains. BYD anchors grid-scale storage procurement through blade battery architecture representation. JinkoSolar Holding Co., Ltd. sits within the mass-production efficiency tier, competing on cell conversion metrics at scale.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited |
| BYD Company Limited |
| LONGi Green Energy Technology Co., Ltd. |
| Sungrow Power Supply Co., Ltd. |
| Trina Solar Co., Ltd. |
| Sinohydro Corporation |
| JinkoSolar Holding Co., Ltd. |
| JA Solar Technology Co., Ltd. |
| Risen Energy Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Floating foundation engineering talent clustering along Fujian and Jiangsu coastlines creates labor-cost differentials that widen pricing-tier spreads between premium offshore wind installations and commodity onshore projects.
Pricing Analysis
Yield-based pricing anchors utility-scale solar and wind contracts, with revenue tied to actual generation output rather than capacity installation. Three-tier pricing structure across premium, standard, and economy levels separates NEEA-certified high-efficiency modules from commodity-grade polysilicon products. Price differentiation rests on GB/T certification tier and after-sales O&M bundling. Cost compression in standard-tier modules is intensifying because polysilicon oversupply cycles erode manufacturer margins. State-grid utilities show least price sensitivity given procurement quota mandates, while distributed commercial buyers in Jiangsu manufacturing parks exhibit highest sensitivity to upfront capital costs.
Supply Chain Analysis
MIIT's GB/T 36276-2018 battery safety certification revision gates supplier qualification, forcing pack redesigns and thermal runaway testing partnerships with state-affiliated bodies. Geographic supply concentration centers on China for polysilicon refining and cell manufacturing, South Korea for high-purity electronic-grade silicon, and Japan for power electronics components. Raw material dependencies include polysilicon feedstock, lithium carbonate for blade battery architectures, and rare earth elements for turbine permanent magnets. Single-source vulnerability concentrates in offshore turbine installation fleets controlled by state-owned construction consortia. Distribution runs through State Grid and Southern Grid centralized procurement frameworks rather than project-by-project tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's renewable energy sector is consolidating around technology-integrated players as polysilicon oversupply and NEEA dispatch tightening force pure-play module manufacturers toward contract assembly roles or exit.
For Market Incumbents: To counter margin erosion from polysilicon price volatility, LONGi and JinkoSolar should deepen backward integration into wafer pulling capacity while BYD expands blade battery architecture licensing to provincial storage integrators. Securing MIIT GB certification pre-approval for next-generation TOPCon lines preserves premium-tier positioning against tier-two assemblers. For New Entrants and Emerging Players: Capture white-space in industrial park microgrids across Jiangsu textile and Guangdong electronics clusters where NEEA efficiency mandates create captive demand for solar-plus-storage bundles. Western hydrogen coupling in Sichuan and Yunnan offers penetrable offtake contracts for stranded renewable generation. A technology-licensing go-to-market model bypasses capital-intensive manufacturing scale-up. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cell-to-pack specialists given carbon market linkage mechanisms enabling revenue stacking atop electricity sales. Long-term viability favors players controlling both high-efficiency wafer supply and grid-scale storage integration. Watch for NEEA dispatch priority rule revisions as the inflection signal for portfolio reconfiguration toward flexibility-assets.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Multi-gigawatt solar and wind farms in Inner Mongolia feed ultra-high-voltage transmission corridors to coastal demand centers. |
| Power Purchase Agreement | Long-term offtake contracts with State Grid utilities lock in revenue visibility under dual carbon procurement quotas. |
| Technology Licensing | Blade battery architecture licensing expands BYD's footprint across provincial storage integrators without direct capex. |
| Backward Integration into Polysilicon | In-house refining capacity insulates module houses from commodity-grade silicon feedstock price volatility cycles. |
| Green Certification Program | NEEA carbon credit monetization enables renewable asset owners to stack environmental revenue atop electricity sales. |
Study Parameters
Multi-period observation of polysilicon spot prices, NEEA dispatch queue lengths, and MIIT certification approval timelines anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Jiangsu, Guangdong, and Inner Mongolia. Secondary validation drew from State Grid procurement disclosure databases, NEEA renewable portfolio obligation filings, MIIT GB standard revision drafts, and provincial five-year plan energy targets. Bottom-up project pipeline aggregation triangulated against top-down provincial capacity installation mandates.
Segment-weighting approaches distributed total addressable value across technology type, application tier, and end-user archetype, with cross-validation against provincial grid interconnection backlogs and ultra-high-voltage transmission commissioning schedules. CAGRs were derived from capacity addition trajectories modeled against dual carbon goal deadlines and NEEA efficiency mandate enforcement calendars. Forecast inputs incorporated polysilicon supply-demand balance projections and offshore wind installation fleet availability constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NEEA dispatch priority rule revisions, carbon market linkage mechanism implementation pace, and MEE environmental assessment enforcement intensity in grassland corridors. Forecasts reflect documented assumptions regarding provincial procurement quota adherence and polysilicon capacity expansion timelines. A model refresh is warranted upon material change in MIIT battery safety certification requirements or State Grid centralized procurement framework restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Philippines Power Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Africa Renewable Energy Market