
 Solar Cullet Market | 2026-2036
Solar Cullet Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cullet Market Analytics
Software-defined material traceability is shifting how solar cullet suppliers contract with buyers, embedding chain-of-custody verification into every ton sold. Saint-Gobain S.A. leverages its European flat-glass recycling infrastructure to pre-sort cullet by iron content for photovoltaic-grade output. Owens-Illinois Inc. anchors North American container-glass collection streams that feed secondary solar-glass melt operations. First Solar, Inc. competes through thin-film manufacturing protocols that specify low-iron cullet chemistry for cadmium-telluride substrates.
Solar cullet consists of post-consumer and post-industrial glass fragments processed to precise size gradations, typically screened below five millimeters and magnetically separated to achieve iron oxide content below 0.1 percent for photovoltaic applications. Its primary industrial purpose centers on displacing virgin silica in solar panel cover glass, reducing furnace energy consumption by leveraging the lower melting point of pre-fired glass. Crushed glass commands the volume lead among product types due to established collection infrastructure, while recycled glass carries premium positioning where carbon-accounting documentation supports module-level environmental product declarations. Flat glass segments concentrate margin pools because solar cover-sheet specifications demand tight thickness tolerances and minimal optical distortion.
The EU Green Deal and REACH frameworks mandate recycled-content thresholds for construction materials including solar modules, directly expanding addressable demand for certified cullet streams. EPA renewable energy waste guidelines in the United States shape end-of-life panel collection protocols that determine future cullet supply availability. China's MIIT dual carbon goals drive national standards for photovoltaic manufacturing inputs, including recycled glass purity benchmarks. Stakeholders must monitor evolving certification requirements across these jurisdictions to secure offtake agreements before supply bottlenecks tighten.
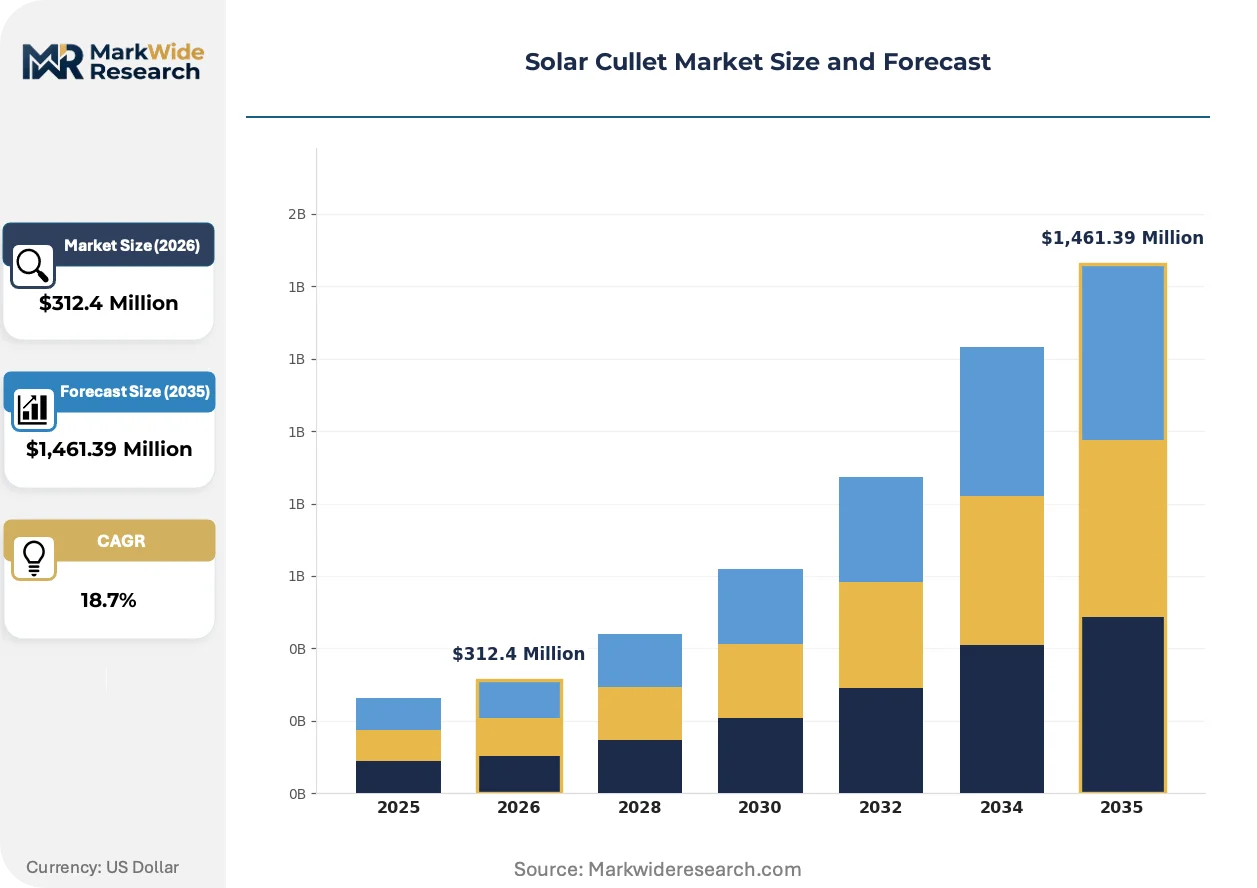
Market Dynamics
The EU Green Deal's recycled-content mandates are compressing supply chains into regional glass recycling clusters that feed photovoltaic manufacturers directly, eliminating cross-border cullet arbitrage.
Growth Catalysts
- REACH Recycled-Content Thresholds:The EU Green Deal mandates minimum recycled glass ratios in solar module construction materials, forcing module assemblers to secure certified cullet streams.
- Photovoltaic Encapsulation Demand:Solar panel manufacturers specify low-iron cullet for cover glass production to maximize light transmission efficiency.
- German Recycling Clusters:Concentrated flat-glass recycling infrastructure in Bavaria and Saxony-Anhalt enables just-in-time cullet delivery to domestic panel producers.
Market Restraints
- Natural Gas Price Volatility:Glass melting furnaces depend on natural gas inputs, and price spikes in European energy markets compress cullet processing margins.
- Collection Infrastructure Concentration:Post-consumer container glass availability concentrates in urban corridors, leaving rural solar glass manufacturers supply-constrained.
- Iron Content Technical Floor:Magnetic separation cannot reliably achieve below 0.08 percent iron oxide in mixed post-consumer streams, limiting photovoltaic-grade yield rates.
Strategic Opportunities
- Thin-Film Cadmium-Telluride Substrates:First Solar's manufacturing protocols specify ultra-low-iron cullet chemistry, creating premium pricing tiers for certified supply.
- Software-Defined Traceability:Blockchain-based chain-of-custody verification enables carbon-accounting documentation that supports module-level environmental product declarations.
- End-of-Life Panel Collection:EPA renewable energy waste guidelines in the United States are establishing collection protocols that will expand future cullet supply availability.
Industry Challenges
- Optical Purity Certification Timelines:Third-party verification of iron content and bubble density for photovoltaic-grade cullet extends sales cycles by four to six months.
- Furnace Retrofit Capex Requirements:Container-glass manufacturers seeking to supply solar-grade output must invest in batch reformulation systems and enhanced quality control instrumentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cullet Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Glass, Recycled Glass, Flat Glass, Container Glass Application: Solar Panels, Photovoltaic Systems, Glass Manufacturing, Reinforcement End User: Manufacturers, Installers, Distributors, Construction Companies Distribution Channel: Direct Sales, Online Sales, Wholesale, Retail |
| Companies Covered | Saint-Gobain S.A., AGC Inc., Owens-Illinois Inc., Ardagh Group S.A., Vetropack Holding AG, Şişecam Group, NSG Group, Gerresheimer AG, First Solar, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cullet Market Evolving Landscape
Digital traceability infrastructure and precision sorting technologies are compressing the gap between post-consumer waste streams and photovoltaic-grade material specifications.
Near-infrared optical sorting is absorbing contamination from mixed post-consumer glass streams at throughputs exceeding ten tons per hour. German recycling operators deploy this technology to pre-sort cullet by iron content before delivery to solar glass melt tanks. The resulting material uniformity is absorbing price volatility in virgin silica markets by stabilizing secondary glass input costs.
China's MIIT dual carbon goals are establishing national standards for photovoltaic manufacturing inputs including recycled glass purity benchmarks. Domestic panel producers must now document recycled-content ratios in module certification filings. This regulatory pressure is accelerating investment in automated cullet processing lines across Jiangsu and Zhejiang provinces.
Long-term offtake contracting is displacing spot-market purchasing among photovoltaic system developers. Module manufacturers now negotiate five-year supply agreements with recycling clusters to secure volume commitments for environmental product declarations. This procurement consolidation is most visible in Germany where Saint-Gobain's flat-glass recycling infrastructure has locked in multi-year contracts with domestic panel producers.
Solar Cullet Market Segmentation
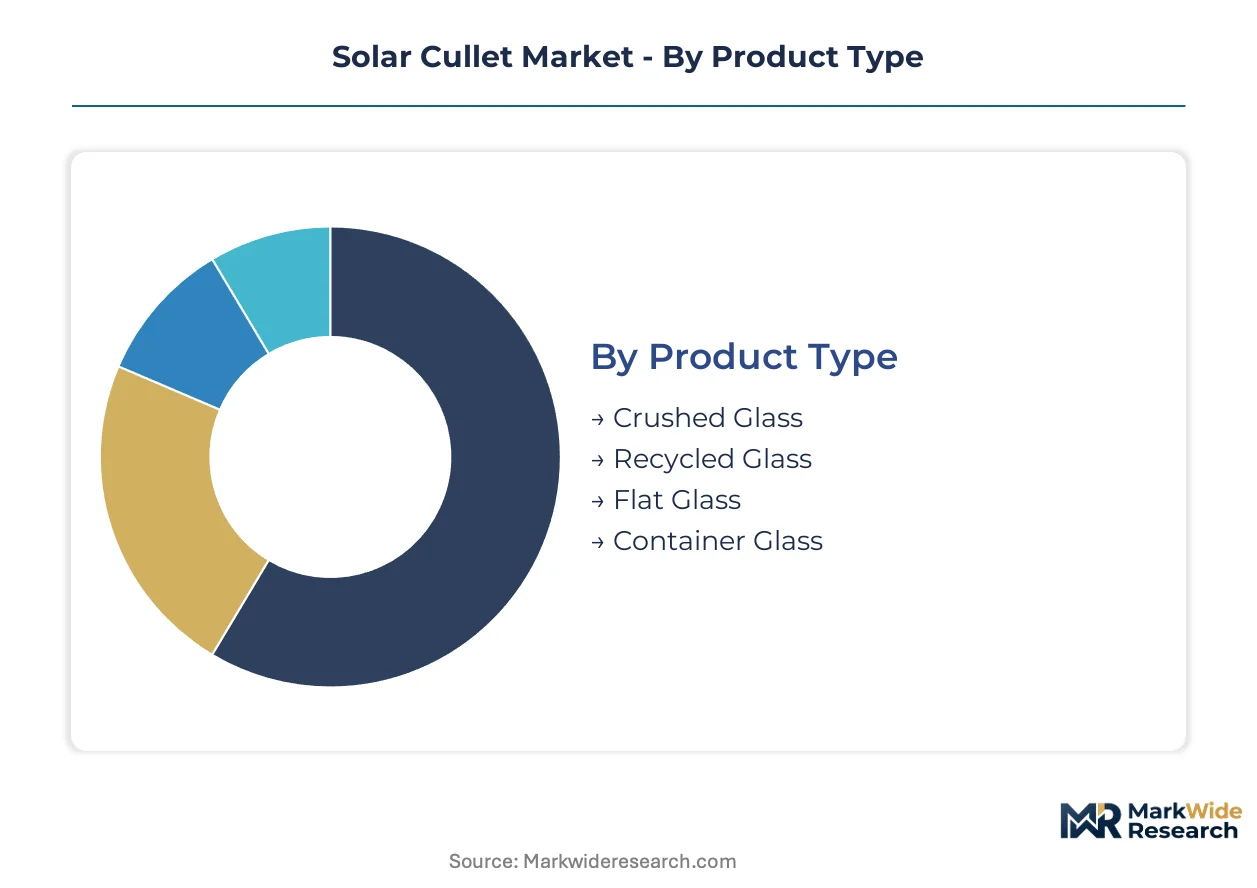
Segmentation in solar cullet markets reveals how material specifications fragment procurement strategies across photovoltaic supply chains. Iron content thresholds, melting point requirements, and optical purity standards create distinct commercial tiers that reshape supplier-buyer contracting patterns.
Product Type:
Volume leadership concentrates in crushed glass streams, while premium positioning attaches to certified recycled grades with documented carbon footprints.
- Crushed Glass:Post-consumer and post-industrial fragments screened below five millimeters and magnetically separated to sub-0.1 percent iron oxide content. German recycling clusters in Bavaria and Saxony-Anhalt leverage established container-glass collection infrastructure to feed solar glass melt tanks at scale.
- Recycled Glass:Premium-tier material carrying blockchain-verified chain-of-custody documentation that supports module-level environmental product declarations under EU Green Deal mandates. Saint-Gobain's European flat-glass recycling infrastructure pre-sorts by iron content to capture this pricing tier.
- Flat Glass:Tight thickness tolerances and minimal optical distortion specifications serve solar cover-sheet applications.
- Container Glass:Mixed post-consumer streams requiring enhanced magnetic separation to approach photovoltaic-grade yield rates.
Today's leader: Crushed Glass. Tomorrow's challenger: Recycled Glass.
Application:
Photovoltaic encapsulation commands margin concentration, while glass manufacturing feedstock absorbs volume scale.
- Solar Panels:Cover glass production specifies low-iron cullet chemistry to maximize light transmission efficiency in crystalline silicon modules. First Solar's thin-film cadmium-telluride protocols create premium pricing tiers for ultra-low-iron certified supply.
- Photovoltaic Systems:System developers now negotiate five-year offtake agreements with recycling clusters to secure volume commitments for environmental compliance filings.
- Glass Manufacturing:Displacement of virgin silica in furnace batches reduces energy consumption through lower melting points of pre-fired glass.
- Reinforcement:Secondary applications accepting higher iron content tolerances where optical purity requirements relax.
Procurement gravity centers on Solar Panels. Photovoltaic Systems are climbing the fastest as long-term contracting displaces spot purchasing.
End User:
Manufacturer integration depth determines supply security, while installer fragmentation creates spot-market volatility.
- Manufacturers:Module assemblers forced by REACH recycled-content thresholds to secure certified cullet streams with third-party verification of iron content and bubble density.
- Installers:Project developers sourcing crushed glass for encapsulation layers through direct recycling cluster relationships.
- Distributors:Intermediary positioning eroding as software-defined traceability enables producer-to-manufacturer contracting.
- Construction Companies:Emerging demand channel as building-integrated photovoltaics expand recycled-content requirements into construction material specifications.
Contracting power aggregates with Manufacturers. Construction Companies represent the steepest expansion trajectory as circular economy mandates broaden.
Distribution Channel:
Direct relationships capture premium tiers, while wholesale channels absorb commodity-grade volume.
- Direct Sales:Multi-year supply agreements between recycling clusters and panel producers locking in volume commitments for environmental product declarations.
- Online Sales:Digital platforms emerging for spot-market transactions in lower-grade cullet streams lacking certification documentation.
- Wholesale:Bulk aggregation of mixed post-consumer glass requiring downstream processing to approach photovoltaic specifications.
- Retail:Minimal penetration given industrial-scale batch requirements and technical specification complexity.
Channel control consolidates through Direct Sales. Online Sales are gaining share fastest as traceability infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China command contrasting supply chain architectures for solar cullet procurement. German recycling clusters leverage established flat-glass infrastructure to serve domestic panel producers with certified low-iron streams. Chinese manufacturers accelerate automated processing investments to meet MIIT dual carbon documentation requirements.
Germany
Flat-glass recycling clusters in Bavaria and Saxony-Anhalt enable just-in-time cullet delivery to crystalline silicon module producers. EU Green Deal recycled-content mandates force module assemblers to secure REACH-compliant certified streams with third-party iron verification. Saint-Gobain's European infrastructure pre-sorts material by chemistry to capture premium pricing tiers.
China
Domestic panel producers in Jiangsu and Zhejiang provinces must document recycled-content ratios in module certification filings under MIIT dual carbon goals. Automated cullet processing lines absorb contamination from mixed post-consumer streams at throughputs exceeding ten tons per hour. National standards for photovoltaic manufacturing inputs accelerate investment in precision sorting infrastructure.
United States
First Solar's thin-film cadmium-telluride manufacturing in Ohio and Arizona specifies ultra-low-iron cullet chemistry for substrate production. EPA renewable energy waste guidelines establish end-of-life panel collection protocols that determine future supply availability. Owens-Illinois anchors North American container-glass collection streams feeding secondary solar-glass operations.
India
Module manufacturers in Gujarat and Rajasthan source crushed glass for encapsulation layers through direct recycling relationships. BIS standards for construction materials increasingly reference recycled-content thresholds for solar installations. Domestic glass recycling infrastructure concentrates in urban corridors around Ahmedabad and Jaipur.
Japan
Photovoltaic system developers negotiate long-term offtake agreements with recycling operators to secure volume commitments for environmental compliance. METI industrial policy encourages circular economy integration in manufacturing supply chains. Flat-glass processing capabilities concentrate in the Osaka-Kobe industrial corridor.
Solar Cullet Market Competitive Landscape
Top-tier vendors anchor premium certified cullet supply, while mid-scale processors compete on volume scale and geographic proximity. The vendor base stratifies across integrated flat-glass manufacturers, specialized recycling operators, and thin-film module producers with captive chemistry requirements. Three archetypes dominate: European infrastructure owners with pre-sorting capabilities, North American container-glass aggregators, and Asian automated processing specialists. Competitive moves center on long-term offtake contracting and furnace retrofit investments for solar-grade output.
Among integrated flat-glass manufacturers, Saint-Gobain S.A. and AGC Inc. occupy positions defined by European recycling infrastructure ownership. Owens-Illinois Inc. represents the North American container-glass aggregation archetype. First Solar, Inc. exemplifies the captive demand model through thin-film manufacturing protocols that specify chemistry-controlled cullet inputs.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| AGC Inc. |
| Owens-Illinois Inc. |
| Ardagh Group S.A. |
| Vetropack Holding AG |
| Şişecam Group |
| NSG Group |
| Gerresheimer AG |
| First Solar, Inc. |
| Others |
Value Network & Pricing Analysis
Near-infrared optical sorting deployments in German recycling clusters are compressing processing costs while simultaneously concentrating supply ownership among infrastructure-equipped operators. This technology transition enables sub-0.1 percent iron oxide consistency at scale, allowing certified cullet suppliers to command premium positioning against commodity-grade competitors while locking in multi-year offtake agreements with photovoltaic manufacturers.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for photovoltaic-grade cullet through automated processing lines exceeding ten tons per hour. Contract-based long-term offtake dominates procurement, with pricing stratifying across premium certified tiers with blockchain traceability, standard REACH-compliant grades, and economy unverified streams. Price differentiation hinges on iron content certification and carbon-accounting documentation. Cost compression in standard grades is intensifying because MIIT dual carbon mandates force domestic panel producers to document recycled-content ratios. Installers exhibit highest price sensitivity due to project-margin constraints, while integrated module manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows from end-of-life solar panel collection under EPA renewable energy waste guidelines are establishing future cullet supply availability in the United States. Geographic supply concentrates in Germany, China, and the United States, with German flat-glass recycling clusters leveraging established container-glass infrastructure. Raw material dependencies center on post-consumer container glass streams, natural gas for furnace operations, and magnetic separation equipment. Single-source vulnerability runs through concentrated flat-glass recycling infrastructure in Bavaria and Saxony-Anhalt. Distribution runs through direct producer-to-manufacturer relationships that displace wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar cullet markets have entered a late-cycle quality phase where specification compliance trumps volume scale. Module manufacturers now prioritize certified low-iron streams with documented chain-of-custody over lowest-unit-cost sourcing.
For Market Incumbents: Hedge against thin-film technology substitution by securing furnace retrofit capabilities for ultra-low-iron output serving cadmium-telluride substrates. Invest in blockchain-verified traceability infrastructure to capture premium pricing tiers under EU Green Deal mandates. Capacity additions in China threaten margin compression for uncertified commodity grades. For New Entrants and Emerging Players: Automated precision sorting technology offers a technology-first wedge into photovoltaic-grade supply gaps left by legacy container-glass operators. Target India's Gujarat and Rajasthan module manufacturing corridors where BIS recycled-content thresholds are tightening but domestic processing infrastructure remains underdeveloped. Pursue direct recycling cluster partnerships with crystalline silicon producers seeking REACH-compliant documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European recycling operators lacking solar-grade certification capabilities but owning strategic geographic positioning. Long-term viability favors integrated players controlling both collection infrastructure and furnace operations. Monitor EPA guideline finalization for end-of-life panel collection protocols as inflection signal for North American supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Optical Sorting Deployment | Near-infrared systems in German clusters achieve photovoltaic-grade iron thresholds at commercial scale. |
| Blockchain Traceability Integration | Chain-of-custody verification supports module-level environmental product declarations under EU Green Deal. |
| Furnace Retrofit for Solar-Grade Output | Batch reformulation systems enable container-glass manufacturers to supply low-iron cover sheet specifications. |
| Long-term Offtake Contracting | Five-year agreements between recycling clusters and panel producers lock in volume for compliance filings. |
| End-of-Life Panel Collection Infrastructure | EPA guideline implementation determines future cullet supply availability in North American markets. |
Research Methodology
Direct dialogue with recycling plant operators, photovoltaic module procurement directors, flat-glass furnace engineers, and EU regulatory compliance officers grounded this analysis in operational reality. Secondary validation drew from ECHA REACH documentation, MIIT dual carbon policy filings, EPA renewable energy waste guidelines, and customs trade data on glass cullet movements. Bottom-up capacity assessments across German, Chinese, and North American processing facilities were triangulated against top-down demand modeling from photovoltaic installation forecasts.
Bottom-up modeling tracked installed optical sorting capacity, furnace retrofit timelines, and certification pipeline volumes across the projection horizon. Segmentation dimensions included product type by iron content tier, application by module technology, and end user by integration depth. CAGRs were derived from regression analysis of recycled-content mandate implementation schedules against processing capacity expansion curves. Forecast inputs incorporated natural gas price volatility scenarios and magnetic separation yield rate improvements.
The model holds under stable regulatory enforcement timelines; deviation in EU Green Deal implementation pace or MIIT certification deadline extensions would shift supply-demand balances. Forecasts reflect assumptions on end-of-life panel collection rates and furnace fuel cost trajectories. Practitioners should monitor EPA guideline finalization and German recycling cluster capacity utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
APAC Solar Micro Inverters Market