
 Prils Market | 2026-2036
Prils Market Size, Share, and Industry Trends Forecast 2026-2036
Prils Market Outlook
Maintenance and compliance monitoring services bundled with chronic therapy prescriptions is expanding what pharmaceutical suppliers monetize beyond the pill itself. Aurobindo Pharma leverages its vertically integrated API-to-finished-dose infrastructure to sustain cost leadership in generic prils manufacturing. Sun Pharmaceutical Industries Ltd anchors its position through concentrated R&D spending on complex formulations that differentiate against commodity substitutes.
Prils constitute a pharmacological class of angiotensin-converting enzyme inhibitors characterized by a proline-like ring structure that blocks conversion of angiotensin I to angiotensin II, typically administered as oral tablets with standard dosages ranging from 2.5 mg to 40 mg depending on indication. These agents serve as cornerstone therapeutics for hypertension management, heart failure risk reduction, and post-myocardial infarction cardioprotection across outpatient and inpatient settings. Prescription Prils command the dominant revenue position due to physician-controlled initiation and titration protocols, while Combination Prils represent the fastest-expanding segment as fixed-dose pairings with diuretics or calcium channel blockers improve adherence and outcomes in polypharmacy populations. Generics occupy the volume-heavy tier where margin compression from tender-based hospital procurement forces manufacturers to compete on manufacturing scale and regulatory filing speed.
The FDA governs prils approval through ANDA bioequivalence requirements and current Good Manufacturing Practice inspections that determine market access for generic entrants. EMA's centralized marketing authorization procedure and REACH-compliant active pharmaceutical ingredient sourcing standards shape European competitive dynamics. India's CDSCO aligns with ICH guidelines while enforcing BIS packaging standards and PLI scheme incentives for domestic bulk drug production. Stakeholders must monitor evolving pharmacovigilance signal detection for rare angioedema events and regulatory divergence on impurity thresholds that could trigger reformulation costs or supply disruptions.
Market Dynamics
Fixed-dose combination formulations are compressing single-agent prescribing patterns as payers prioritize adherence metrics over ingredient count in chronic disease management protocols.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive program for bulk drug manufacturing is expanding domestic API capacity for prils active pharmaceutical ingredients.
- Heart failure protocols:Cardiology departments in tertiary hospitals are embedding ACE inhibitors deeper into post-MI discharge pathways per updated AHA/ACC guidelines.
- Pharmacopeial harmonization:Alignment between USP, Ph. Eur., and IP standards is reducing regulatory filing duplication for generic manufacturers.
Market Restraints
- API supply concentration:China dominates key starting material production for enalapril and ramipril intermediates, creating single-source vulnerability.
- Impurity threshold divergence:FDA and EMA maintain different acceptance criteria for N-nitrosamine contaminants, forcing parallel stability studies.
- ARB substitution pressure:Angiotensin receptor blockers with superior side-effect profiles are displacing first-line prils prescriptions in hypertension monotherapy.
Strategic Opportunities
- Brazil's ANVISA fast-track:Simplified bioequivalence pathways for established prils molecules are accelerating market entry for cost-optimized generics.
- Remote patient monitoring:Integration of blood pressure telemetry with prescription fulfillment is creating adherence-linked reimbursement models.
- Complex formulation development:Sustained-release matrix technologies paired with diuretics offer differentiation against immediate-release commoditized supply.
Industry Challenges
- Analytical method transfer:Migrating impurity testing from HPLC to UPLC platforms requires revalidation across multiple manufacturing sites.
- Pharmacovigilance signal management:Rare angioedema case reporting demands dedicated safety surveillance infrastructure that mid-tier manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prils Market |
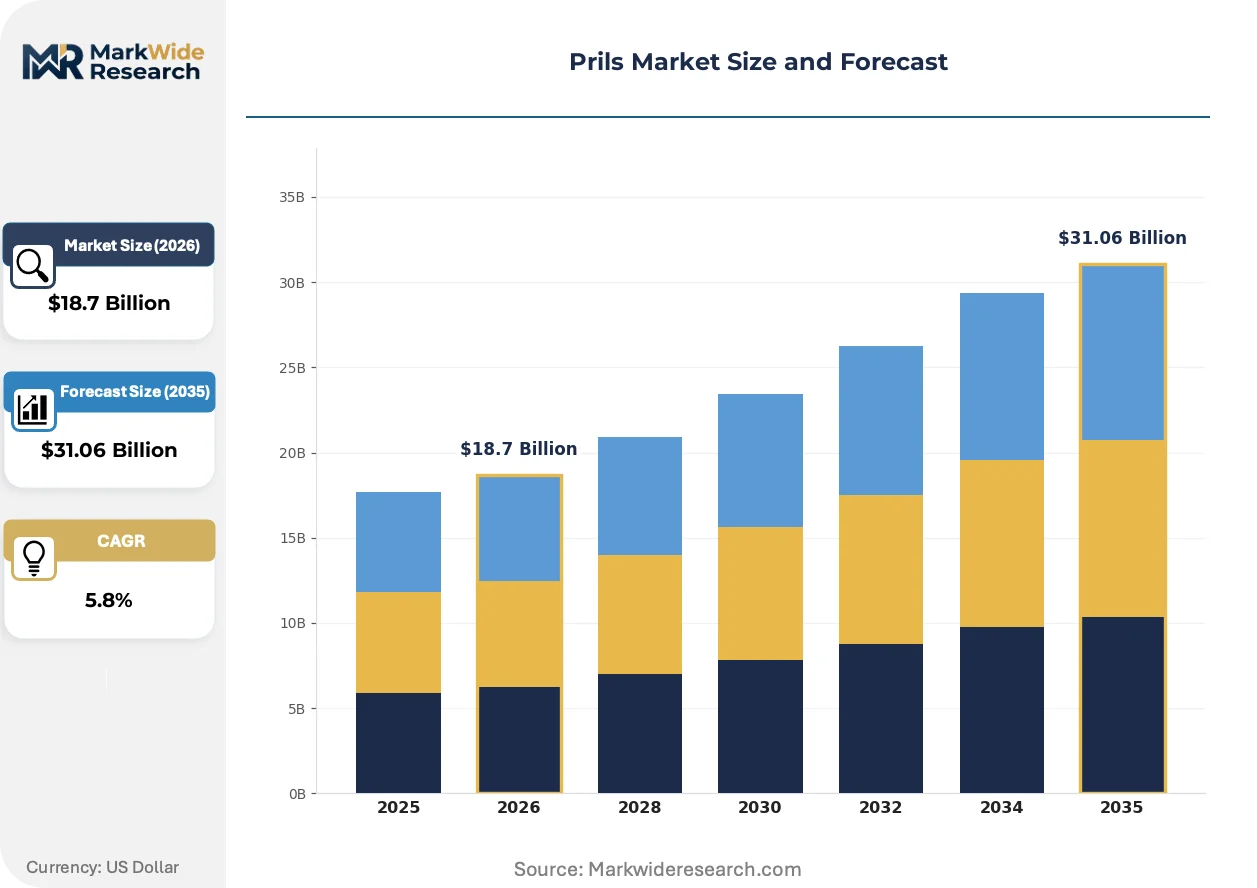
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OTC Prils, Prescription Prils, Combination Prils, Generics Delivery Mode: Oral Tablets, Injectable Solutions, Suspensions, Oral Liquids End User: Hospitals, Clinics, Pharmacies, Homecare Therapy Area: Cardiovascular, Hypertension, Renal Disorders, Others |
| Companies Covered | Aurobindo Pharma, Sun Pharmaceutical Industries Ltd, Lupin, Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd, Merck KGaA, Mylan N.V., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prils Market Strategic Shifts
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times while tightening quality assurance precision across oral solid dose production.
Continuous direct compression is automating powder-to-tablet processing for prils formulations, eliminating traditional wet granulation steps. Contract development and manufacturing organizations in Germany and Switzerland are deploying these lines for high-volume generic supply. The technology is automating quality control sampling frequency and reducing hold times between production stages.
REACH-compliant active pharmaceutical ingredient sourcing standards are mandating full supply chain disclosure for European market access. EMA's tightened expectations on nitrosamine risk assessment documentation are extending development timelines for new generic entrants. Manufacturers serving EU markets are responding by qualifying secondary API suppliers in India with equivalent quality systems.
Hospital procurement consortia are consolidating tender awards around single-source suppliers with bundled inventory management services. Group purchasing organizations in the United States are displacing fragmented distributor relationships with direct manufacturer contracts. This concentration is most visible in integrated delivery networks managing hypertension populations across multiple states.
Prils Market Segmentation
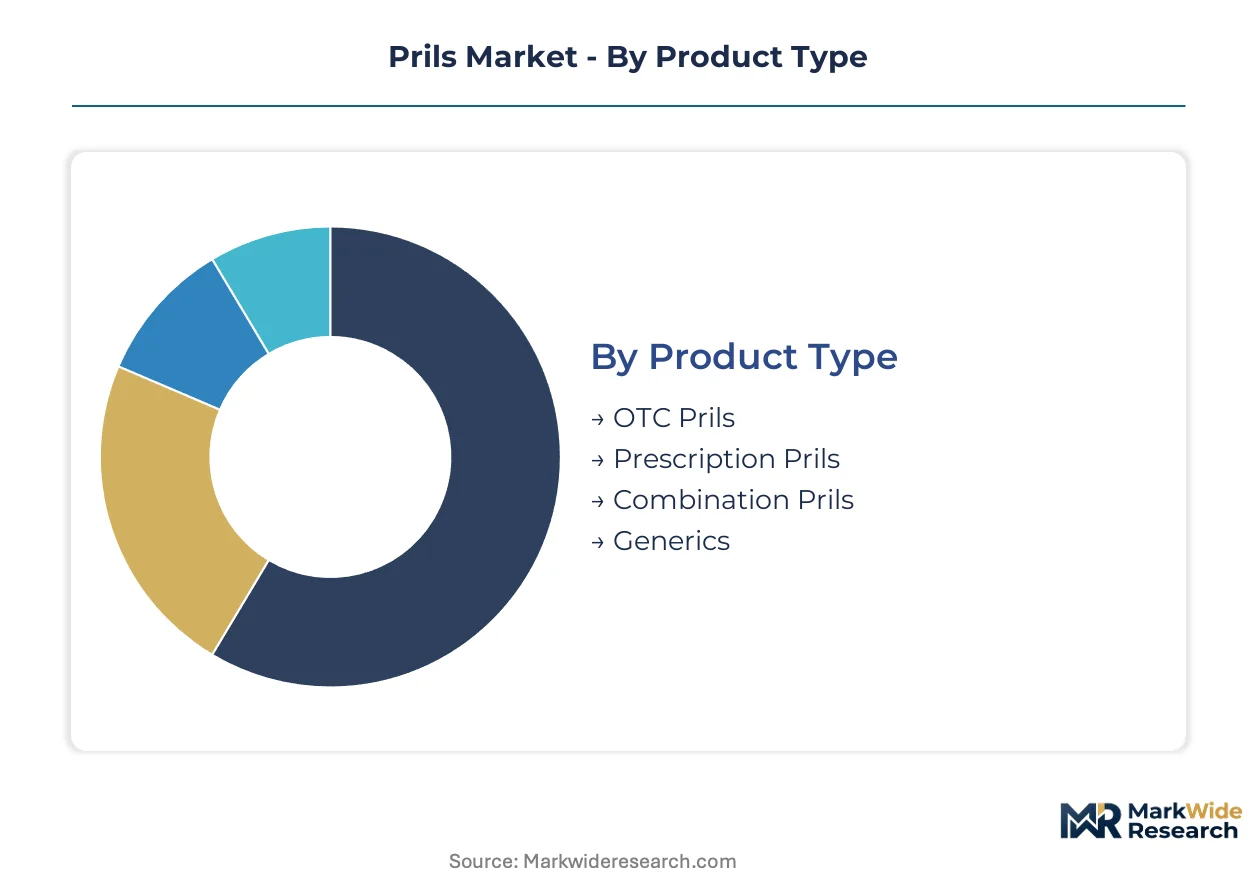
Prils market segmentation reveals distinct upgrade pathways from acute hospital administration to chronic home-based management. Therapy protocols increasingly favor fixed-dose combinations and sustained-release formats over single-agent immediate-release tablets. Each segment category carries specific regulatory filing requirements and margin structures that shape manufacturer portfolio priorities.
Product Type:
Patient progression from acute intervention to chronic maintenance drives product type substitution patterns across the treatment continuum.
- Prescription Prils:Physician-directed initiation and dose titration of enalapril, ramipril, and lisinopril formulations require controlled dispensing through licensed pharmacies. Hospital systems in the United States and Germany anchor demand through chronic disease management protocols that mandate specialist oversight for the first 90 days of therapy.
- Combination Prils:Fixed-dose pairings with hydrochlorothiazide or amlodipine improve adherence metrics in polypharmacy populations. Payer formularies in Western European markets prioritize these formulations for step-therapy hypertension protocols, compressing single-agent prescribing volumes.
- Generics:Tender-based hospital procurement in India and Brazil concentrates volume around cost-optimized manufacturers with rapid regulatory filing capabilities.
- OTC Prils:Limited availability restricted to low-dose lisinopril formulations in select European markets with pharmacist-supervised dispensing requirements.
Volume placements concentrate in Generics; the faster expansion belongs to Combination Prils.
Delivery Mode:
Manufacturing scale economics and bioequivalence complexity create divergent margin profiles across dosage form categories.
- Oral Tablets:Immediate-release and sustained-release matrix technologies dominate production volume. German and Swiss contract manufacturers deploy continuous direct compression lines that compress batch cycle times while tightening quality assurance precision.
- Injectable Solutions:Enalaprilat formulations serve acute hypertensive emergency protocols in tertiary hospital settings. EMA's tightened nitrosamine risk assessment documentation extends development timelines for new generic entrants in this category.
- Oral Liquids:Pediatric and geriatric populations drive demand for lisinopril suspensions with precise dosing flexibility.
- Suspensions:Limited commercial presence concentrated in compounding pharmacy channels for patients with swallowing difficulties.
Margin concentration favors Injectable Solutions; Oral Tablets deliver the volume base.
End User:
Care setting migration from institutional to ambulatory environments reshapes distribution infrastructure and service bundling requirements.
- Hospitals:Integrated delivery networks in the United States consolidate procurement around single-source suppliers with bundled inventory management services. Post-myocardial infarction discharge protocols embed ACE inhibitors deeper into cardiology pathways per AHA/ACC guidelines.
- Clinics:Outpatient hypertension management in India's tier-2 cities relies on CDSCO-regulated generic substitution with price-controlled procurement.
- Pharmacies:Retail dispensing channels in Germany face REACH-compliant API sourcing documentation requirements for European market access.
- Homecare:Remote patient monitoring integration with prescription fulfillment creates adherence-linked reimbursement models in North American markets.
Procurement consolidation is accelerating in Hospitals; Homecare is gaining share fastest.
Therapy Area:
Clinical guideline updates and comorbidity prevalence patterns determine indication-specific demand trajectories.
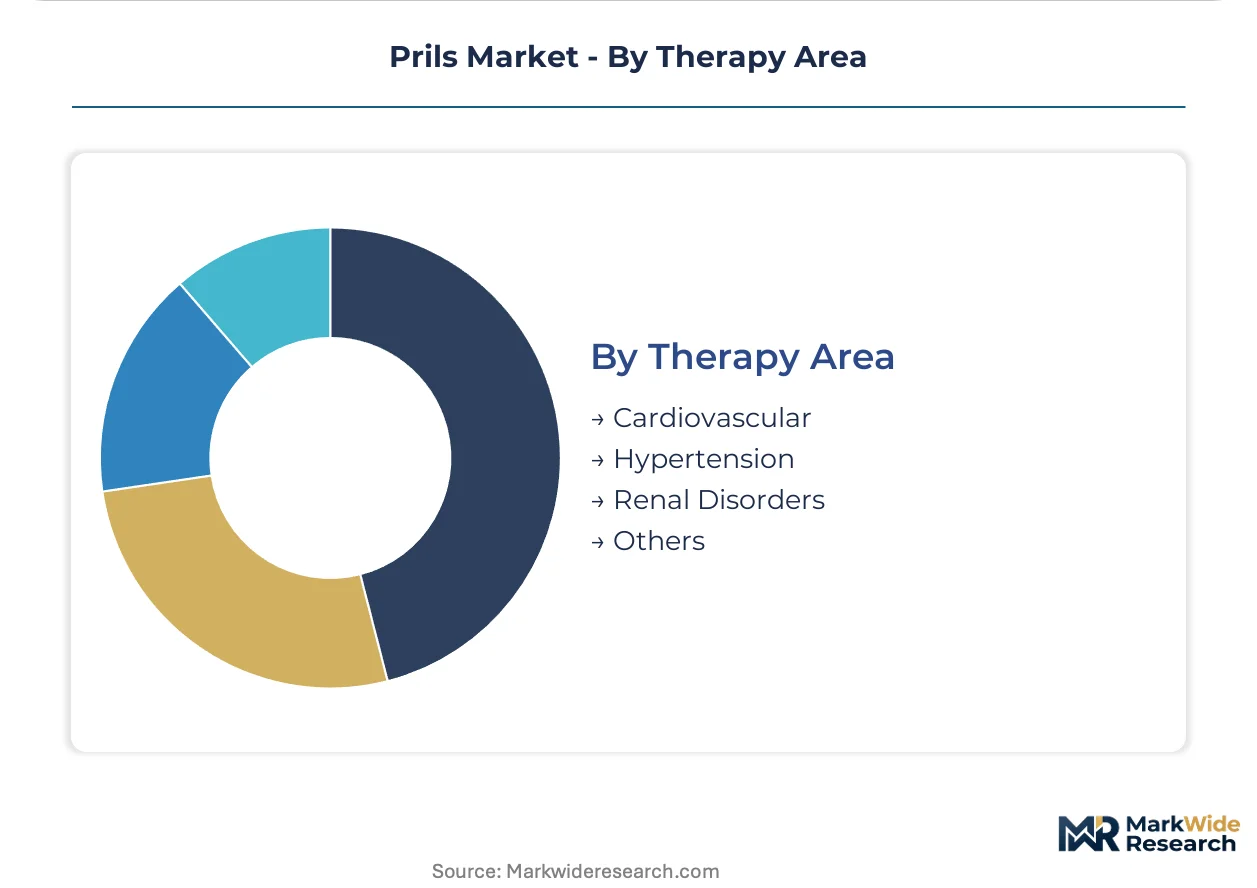
- Hypertension:First-line ACE inhibitor therapy faces substitution pressure from angiotensin receptor blockers with superior side-effect profiles. ARB displacement is most pronounced in United States monotherapy prescribing.
- Cardiovascular:Post-MI cardioprotection and heart failure risk reduction protocols sustain prils adoption despite hypertension segment pressure. AHA/ACC guideline alignment drives protocol embedding in tertiary hospital systems.
- Renal Disorders:Diabetic nephropathy management protocols favor ACE inhibitors for albuminuria reduction in type 2 diabetes populations.
- Others:Scleroderma renal crisis and migraine prophylaxis represent niche indications with limited commercial volume.
Clinical protocol anchoring is strongest in Cardiovascular; Renal Disorders shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API production concentrates in India and China, while formulation manufacturing and consumption cluster in the United States, Germany, and Western European hospital systems. This geographic split shapes regulatory filing strategies and supply chain risk profiles for prils manufacturers.
United States
Integrated delivery networks in Texas and California consolidate procurement around single-source suppliers with bundled inventory management services. FDA bioequivalence requirements and current Good Manufacturing Practice inspections determine market access for generic entrants. Philadelphia-area pharmaceutical clusters anchor formulation development for cardiovascular therapy protocols.
Germany
Tertiary hospital systems in Bavaria and North Rhine-Westphalia embed ACE inhibitors deeper into post-myocardial infarction discharge pathways per updated cardiology guidelines. EMA centralized marketing authorization and REACH-compliant API sourcing standards shape competitive dynamics. Swiss and German contract manufacturers deploy continuous direct compression lines for high-volume generic supply.
India
Tier-2 city clinics in Maharashtra and Gujarat rely on CDSCO-regulated generic substitution with price-controlled procurement for hypertension management. The PLI scheme for bulk drug manufacturing expands domestic API capacity for enalapril and ramipril intermediates. Hyderabad and Ahmedabad pharmaceutical corridors concentrate vertically integrated API-to-finished-dose infrastructure.
Brazil
ANVISA fast-track bioequivalence pathways for established prils molecules accelerate market entry for cost-optimized generics serving public health system tenders. São Paulo and Minas Gerais anchor outpatient hypertension management demand. Hospital procurement consortia consolidate tender awards around manufacturers with local packaging and distribution capabilities.
Switzerland
Swissmedic oversight and pharmacovigilance signal detection requirements for rare angioedema events extend safety surveillance obligations for manufacturers serving Alpine markets. Basel and Zurich pharmaceutical clusters specialize in complex formulation development and sustained-release matrix technologies. REACH-compliant supply chain disclosure mandates drive secondary API supplier qualification in India.
Prils Market Competitive Environment
Top-tier vendors anchor hospital procurement consortia and integrated delivery network contracts, while mid-tier generic manufacturers compete on regulatory filing speed and tender pricing. The vendor base stratifies across three tiers: multinational innovators with legacy cardiovascular portfolios, vertically integrated Indian pharmaceutical conglomerates, and regional generic specialists. Competitive positioning hinges on manufacturing scale, pharmacopeial harmonization capabilities, and bundled service offerings beyond the pill itself.
Within the vertically integrated tier, Aurobindo Pharma and Sun Pharmaceutical Industries Ltd exemplify cost leadership through captive API production and concentrated R&D spending on complex formulations. Pfizer Inc. occupies a position representing legacy brand equity and hospital system relationships in North American and Western European markets. These three anchors illustrate divergent strategic archetypes: scale-driven generic manufacturing, differentiated formulation development, and incumbent brand preservation.
| Leading Market Players |
|---|
| Aurobindo Pharma |
| Sun Pharmaceutical Industries Ltd |
| Lupin |
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Merck KGaA |
| Mylan N.V. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Value Chain & Pricing Dynamics
Enalapril maleate API price indices cascading from Chinese intermediate suppliers compress margin structures across three-tier pricing stratification separating patented originators from bioequivalent generics and tender-optimized economy supply. Hospital procurement consortia in the United States and Germany exploit this concentration to extract volume discounts that propagate downstream through distributor networks.
Pricing Analysis
Margin tightening in economy-tier generics reflects tender-based hospital procurement compression and API import duty exposure. Three-tier pricing structure across premium originator, standard generic, and economy tender levels stratifies by bioequivalence certification grade and pharmacopeial compliance tier. Cost-down pressure on standard generics accelerates because EMA-FDA impurity threshold divergence forces parallel stability study investments. Clinic buyers in India's tier-2 cities exhibit highest price sensitivity; Swiss hospital systems show lowest due to bundled inventory management service premiums.
Supply Chain Analysis
Reverse-logistics for recalled batches containing elevated N-nitrosamine levels strains quality assurance infrastructure across Indian and Chinese API manufacturers. Active pharmaceutical ingredient production concentrates in China and India, with formulation finishing clustered in Germany and Switzerland. Key starting material dependencies include 2-oxoprolinate esters, proline derivatives, and maleic acid. Single-source vulnerability in enalapril intermediate supply from Zhejiang province creates tariff-exposed chokepoints. Distribution runs through hospital procurement consortia and group purchasing organizations displacing fragmented wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API capacity constraints in REACH-compliant European sourcing prop pricing resilience for manufacturers with backward-integrated supply. China's dominance in key starting materials creates structural scarcity supporting margin defense.
For Market Incumbents: Extend pharmacopeial harmonization capabilities to capture EMA centralized marketing authorization efficiencies against mid-tier competitors lacking multi-jurisdiction filing infrastructure. Deepen captive production of ramipril and lisinopril intermediates in Hyderabad and Ahmedabad corridors to offset Chinese supply vulnerability. Prioritize complex formulation R&D in sustained-release matrix technologies to differentiate against commodity immediate-release substitution. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Brazilian public health tenders creates entry opportunity for cost-optimized manufacturers with ANVISA fast-track bioequivalence documentation. Target outpatient hypertension management in India's tier-2 cities where CDSCO-regulated generic substitution protocols favor rapid regulatory filers. Deploy direct-to-clinic distribution bypassing fragmented wholesale layers to capture price-controlled procurement volumes. For Investors and Strategic Acquirers: The window for entry favors vertically integrated API-to-finished-dose specialists with captive enalapril and ramipril intermediate production. Long-term viability hinges on manufacturing scale sufficient to absorb tender pricing compression while funding pharmacovigilance infrastructure for rare angioedema signal detection. Monitor EMA-FDA convergence on nitrosamine impurity thresholds as inflection indicator for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive supply of enalapril intermediates insulates margin from Chinese price volatility and tariff exposure. |
| Complex Formulation Development | Sustained-release matrix technologies paired with diuretics command premium positioning against immediate-release commoditization. |
| Regulatory Filing Acceleration | ANVISA fast-track pathways in Brazil compress time-to-revenue for cost-optimized generic entrants. |
| Pharmacovigilance Infrastructure Investment | Dedicated safety surveillance systems address rare angioedema reporting obligations required by Swissmedic and EMA. |
| Continuous Manufacturing Deployment | Direct compression automation in German and Swiss contract facilities tightens quality assurance precision and batch cycle times. |
Study Parameters
Multi-period observation of FDA ANDA approval timelines, EMA centralized marketing authorization patterns, and CDSCO generic substitution volumes anchored the trend analysis, supplemented by interviews with regulatory affairs leads at formulation manufacturers, hospital procurement managers in integrated delivery networks, and API sourcing directors at vertically integrated pharmaceutical conglomerates. Secondary validation drew from FDA Orange Book filings, EMA EPAR documentation, Indian Pharmacopoeia Commission standards, and USP monograph revisions. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation reconciled segment-level estimates.
Input-output matrices mapped API production capacity through formulation finishing to end-use consumption across therapy area, product type, delivery mode, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to base-year volume and value estimates. Forecast inputs incorporated PLI scheme incentive trajectories, AHA/ACC guideline protocol embedding rates, and nitrosamine regulatory threshold evolution.
Inputs from FDA inspection databases and EMA pharmacovigilance signal repositories were available through the study window; gaps in real-time tender award pricing from Brazilian hospital procurement consortia introduce uncertainty bands around Latin America volume projections. Forecasts assume sustained regulatory divergence on impurity thresholds and stable API trade flows from Chinese intermediate suppliers. Practitioners should monitor REACH-compliant supply chain disclosure mandates and CDSCO PLI scheme disbursement rates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Cellulose Acetate Phthalate Market