
 Magnesium Chelates Market | 2026-2036
Magnesium Chelates Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Chelates Market Analytics
Asset-light contract manufacturing and toll-processing arrangements are reshaping competitive entry in magnesium chelates, allowing smaller formulators to bypass capital-intensive chelation infrastructure. Albion Laboratories leverages its patented mineral amino acid chelate technology to sustain premium positioning in human nutrition. BASF SE anchors agricultural chelate supply through its global micronutrient distribution network. Kemin Industries differentiates via vertically controlled fermentation and chelation operations for animal feed applications.
Magnesium chelates are coordination compounds where magnesium ions are bound to organic ligands—typically amino acids such as glycine or aspartic acid—through heteroatomic bonds, yielding ring structures with enhanced gastrointestinal absorption and metabolic bioavailability compared to inorganic magnesium salts. These complexes serve primarily as stabilized mineral delivery systems in nutraceuticals, fortified foods, and precision agriculture where ionic magnesium would otherwise precipitate or antagonize other nutrients. Powder chelates dominate volume due to blending compatibility across tablet, capsule, and premix formats, while liquid chelates command margin premiums in hydroponic fertigation and injectable veterinary formulations. Chelate complexes incorporating multiple trace minerals represent the fastest-growing structural category as compounders seek simplified premix logistics.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements and the EPA's pesticide tolerance frameworks for agricultural micronutrients jointly constrain chelate purity thresholds and label claims in the United States. REACH registration requirements and EFSA novel food assessments in Europe add compliance layers that favor established suppliers with toxicological dossiers and analytical capabilities. Stakeholders must monitor evolving EFSA opinions on amino acid chelate bioequivalence and the potential for consolidated positive lists that could exclude non-standard ligand systems from approved food and feed uses.
Market Dynamics
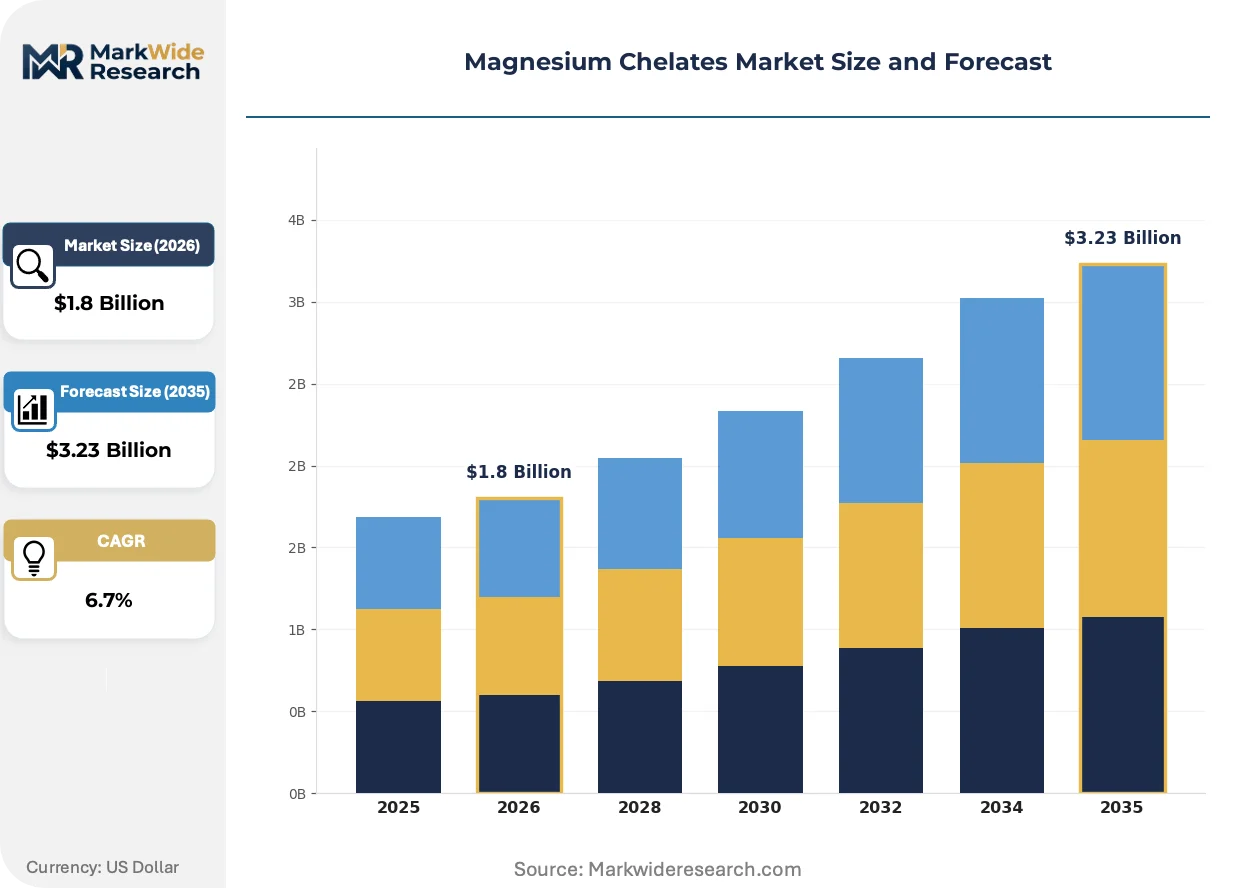
Asset-light contract manufacturing is compressing capital barriers for magnesium chelate entrants, while REACH compliance and EFSA novel food assessments concentrate supply among dossier-capable incumbents with analytical infrastructure.
Growth Catalysts
- EFSA novel food pathways:Approved amino acid chelate bioequivalence opinions are expanding permissible ligand systems for fortified foods and supplements, accelerating formulation diversity.
- Precision agriculture expansion:Hydroponic fertigation systems in greenhouse clusters are absorbing liquid magnesium chelates for micronutrient delivery without precipitation losses.
- Frankfurt-Rhine-Main ingredient hub:Germany's specialized nutrition cluster concentrates R&D infrastructure, technical service capabilities, and regulatory expertise for chelated mineral exports.
Market Restraints
- Amino acid input volatility:Glycine and aspartic acid prices fluctuate with fermentation feedstock costs, compressing margins for chelate manufacturers without captive amino acid supply.
- REACH registration concentration:Toxicological dossier requirements favor established EU-registered suppliers, structurally excluding smaller importers from commercial volumes.
- Inorganic salt substitution:Magnesium oxide and sulfate remain cost-competitive for price-sensitive agricultural applications, limiting chelate penetration in commodity fertilizer channels.
Strategic Opportunities
- Compound chelate formulations:Multi-mineral chelate complexes are simplifying premix logistics for feed and food manufacturers, consolidating supply relationships.
- Veterinary injectable channels:Liquid magnesium chelates with enhanced stability profiles are displacing inorganic solutions in ruminant deficiency correction protocols.
- EU Green Deal nutrient recovery:Circular economy mandates for phosphorus and micronutrient recycling are creating demand for chelated mineral recovery from organic waste streams.
Industry Challenges
- Analytical method standardization:Inconsistent chelate stability testing protocols across laboratories complicate quality assurance and regulatory submission timelines.
- Chelate characterization capex:X-ray crystallography and advanced spectroscopy infrastructure requirements strain mid-tier formulators without contract laboratory partnerships.
- Legacy premix integration:Compound feed manufacturers face formulation rebalancing costs when substituting chelated minerals for inorganic sources in established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Chelates Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chelates, Powder Chelates, Granular Chelates, Chelate Complexes Form: Organic Forms, Inorganic Forms, Synthetic Forms, Natural Forms Application: Agricultural Fertilizers, Animal Feed Supplements, Nutraceuticals, Food Additives End User: Agribusinesses, Feed Manufacturers, Dietary Supplement Firms, Food Industry |
| Companies Covered | Balchem Corporation, Pure Encapsulations, Albion Laboratories, Innophos, BASF SE, Archer Daniels Midland (ADM), Kemin Industries, NOW Foods, Solgar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Chelates Market Evolving Landscape
Fermentation-derived amino acid production and advanced chelation kinetics are converging to reshape mineral bioavailability engineering, while regulatory data requirements and buyer procurement sophistication are filtering supplier capabilities.
Continuous flow chelation reactors are replacing batch processing for magnesium glycinate and aspartate production. Nutraceutical contract manufacturers in North American dietary supplement corridors are adopting these systems to reduce solvent use and improve ligand-to-metal ratios. The technology is hybridizing quality control protocols, merging in-process analytical sensors with traditional batch release testing to compress certification timelines.
REACH registration dossiers for amino acid chelates are expanding beyond basic toxicological endpoints to include environmental fate and bioaccumulation studies. ECHA's updated guidance on complex substance identification is forcing suppliers to characterize chelate speciation more precisely. Agricultural micronutrient formulators with incomplete dossiers are exiting the EU market, consolidating supply among registrants with full Annex IX and X data packages.
Certificate of analysis-driven procurement is displacing spot-market purchasing for magnesium chelates in premium supplement channels. Brand owners are mandating third-party validated chelate content, heavy metal limits, and microbial specifications before contract execution. This pattern is most pronounced in German and Swiss finished goods manufacturing, where quality agreements now specify analytical method references and auditor access rights to raw material suppliers.
Magnesium Chelates Market Segmentation
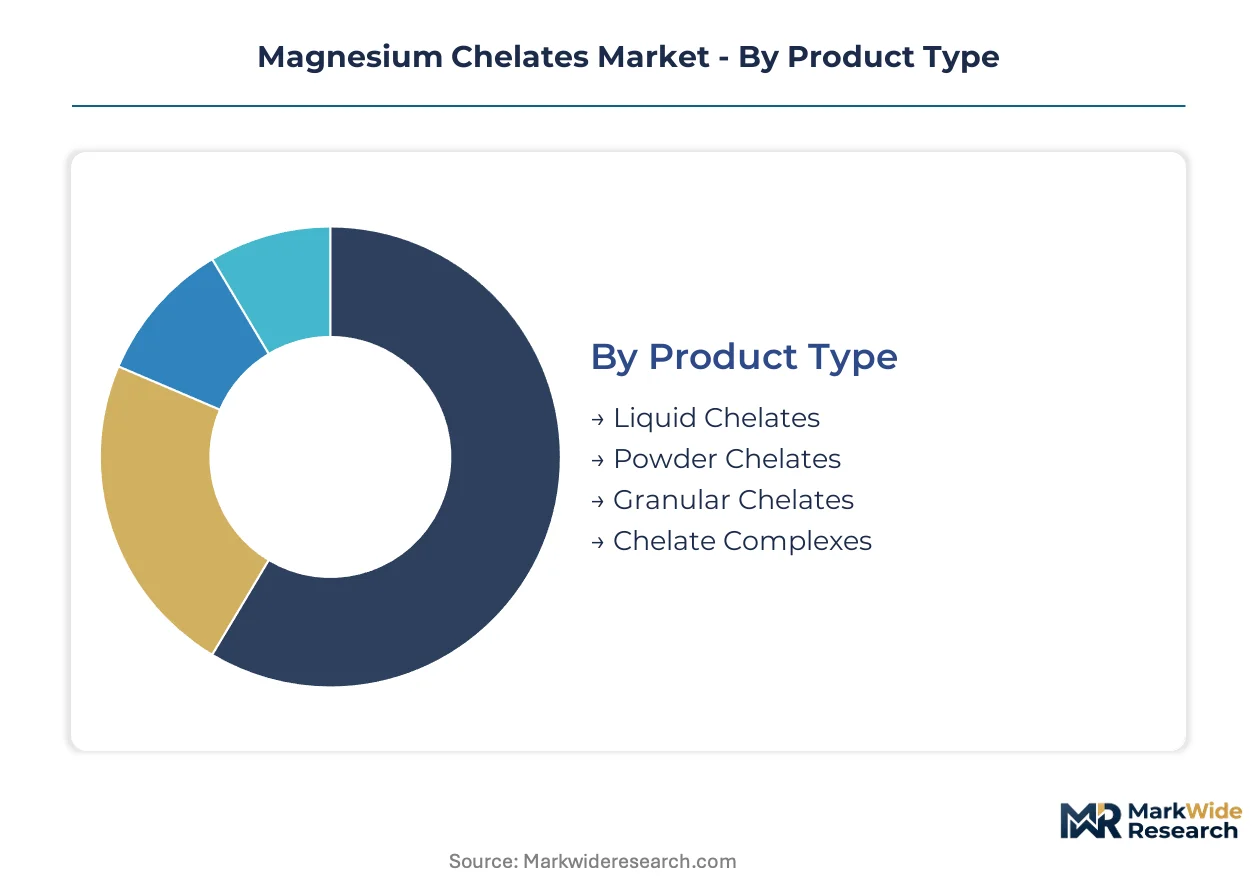
Magnesium chelate segmentation reflects divergent technical requirements across delivery systems and end-use specifications. Formulators select product types based on blending compatibility, stability profiles, and regulatory compliance thresholds for target applications.
Product Type:
Mature powder formats dominate established premix channels, while liquid and complex variants capture emerging precision delivery applications.
- Powder Chelates:Dry, free-flowing magnesium amino acid complexes engineered for tablet compression, capsule filling, and dry premix integration. Demand concentrates in German and Swiss dietary supplement manufacturing, where certificate-of-analysis procurement mandates favor validated powder specifications with documented ligand-to-metal ratios.
- Liquid Chelates:Aqueous or solvent-based magnesium coordination compounds stabilized for hydroponic fertigation and injectable veterinary protocols. Hydroponic greenhouse clusters in the Netherlands and Spain absorb volumes for micronutrient delivery without precipitation losses in recirculating systems.
- Granular Chelates:Agglomerated particles sized for broadcast fertilizer application and soil incorporation.
- Chelate Complexes:Multi-mineral coordination systems binding magnesium with zinc, copper, or manganese in single-molecule structures.
Powder chelates handle the majority of throughput; chelate complexes are gaining share fastest through premix simplification.
Form:
Cost tier stratification separates fermentation-derived organic inputs from commodity-scale synthetic production.
- Organic Forms:Magnesium chelates synthesized from fermentation-derived amino acids, typically glycine or L-aspartic acid, yielding specified stereochemistry and bioavailability profiles. Dietary supplement firms in the Frankfurt-Rhine-Main cluster specify organic forms for EFSA novel food submissions requiring documented amino acid provenance.
- Synthetic Forms:Laboratory-synthesized magnesium coordination compounds produced via chemical chelation with petrochemical-derived ligands. Agricultural applications in Eastern European markets absorb synthetic volumes where cost positioning outweighs organic certification requirements.
- Inorganic Forms:Magnesium salts without organic ligand coordination, excluded from strict chelate definitions but competing in price-sensitive mineral supplementation.
- Natural Forms:Chelates derived from protein hydrolysates or plant-based amino acid sources.
Organic forms command premium positioning; synthetic forms expand most quickly in agricultural channels.
Application:
Volume concentration tracks fertilizer commodity cycles, while margin expansion centers on nutraceutical and feed precision formulation.
- Agricultural Fertilizers:Soil-applied and foliar magnesium chelates correcting deficiency in high-value horticulture and arable crops. French and Italian specialty crop producers specify liquid chelates for fertigation in protected cultivation, bypassing soil fixation losses.
- Nutraceuticals:Magnesium amino acid chelates formulated for bioavailability-conscious consumers seeking alternatives to inorganic magnesium salts. German finished goods manufacturers drive procurement with third-party validated chelate content specifications.
- Animal Feed Supplements:Chelated magnesium for ruminant, poultry, and aquaculture nutrition premixes.
- Food Additives:Fortification-grade magnesium chelates for processed foods and beverages.
Agricultural fertilizers handle the majority of throughput; nutraceuticals climb the fastest on margin expansion.
End User:
Customer type determines procurement sophistication, from spot-market agricultural purchasing to quality-agreement supplement manufacturing.
- Dietary Supplement Firms:Brand owners and contract manufacturers requiring validated chelate content, heavy metal limits, and microbial specifications for finished goods. Swiss and German manufacturers impose auditor access rights to raw material suppliers, consolidating supply among dossier-capable registrants.
- Agribusinesses:Large-scale farming operations and agricultural cooperatives purchasing magnesium chelates for direct application or on-farm blending. Spanish and Portuguese greenhouse cooperatives specify liquid chelates for hydroponic integration.
- Feed Manufacturers:Compound feed producers integrating chelated minerals into premixes for livestock and aquaculture.
- Food Industry:Processed food and beverage manufacturers fortifying products with bioavailable magnesium.
Agribusinesses handle the majority of throughput; dietary supplement firms are the fastest mover on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented chelate production concentrates in Germany's Rhine-Main corridor, while import-dependent agricultural markets in Southern Europe absorb liquid formulations for protected cultivation. Trade flows reflect divergent regulatory dossier capabilities across jurisdictions.
Germany
Dietary supplement manufacturers in Frankfurt and Darmstadt drive organic-form magnesium glycinate procurement for EFSA novel food submissions. REACH registration requirements filter supply to dossier-capable incumbents with full Annex IX toxicological data. The Rhine-Main cluster houses specialized analytical laboratories serving chelate exporters to Swiss and Austrian markets.
United States
FDA Current Good Manufacturing Practice enforcement elevates quality agreement requirements for contract manufacturers in Utah and California supplement corridors. Nutraceutical brand owners mandate third-party validated chelate content specifications before procurement execution. The EPA's pesticide tolerance frameworks constrain agricultural chelate label claims for foliar application.
Netherlands
Hydroponic greenhouse operators in Westland and Aalsmeer absorb liquid magnesium chelates for recirculating fertigation systems without precipitation losses. The country's national fertilizer regulator enforces micronutrient purity thresholds for soil-applied products. Rotterdam's port infrastructure handles bulk chelate imports for redistribution to Belgian and French agricultural markets.
Spain
Almería and Murcia greenhouse cooperatives specify liquid chelate formulations for high-value horticulture exports to Northern European retailers. The country's national food safety authority aligns with EFSA opinions on amino acid chelate bioequivalence for feed applications. Valencia's specialized chemical distributors maintain refrigerated storage for temperature-sensitive liquid chelate inventories.
China
Synthetic glycine production in Shandong and Jiangsu provinces supplies cost-competitive chelate intermediates for agricultural markets. The Ministry of Ecology and Environment's dual carbon goals pressure fermentation-based amino acid producers to upgrade energy intensity. Qingdao's chemical export terminals handle bulk powder chelate shipments to Southeast Asian feed compounders.
Magnesium Chelates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with ligand chemistry and chelation kinetics expertise. The supplier base stratifies between fermentation-derived amino acid producers, toll-processing contract manufacturers, and finished premix compounders. Three archetypes dominate: patent-holding mineral technology licensors, vertically controlled fermentation operators, and asset-light formulation houses. Competitive moves center on REACH dossier consolidation and continuous-flow reactor licensing partnerships.
Among diversified chemical conglomerates, BASF SE occupies a position exemplifying agricultural micronutrient platform integration. Specialty mineral technology developers Albion Laboratories and Balchem Corporation represent the patent-anchored tier, sitting within a segment where validated chelate content specifications determine procurement access. These three entities illustrate the divergence between scale-driven agricultural supply and premium-tier nutraceutical positioning.
| Leading Market Players |
|---|
| Balchem Corporation |
| Pure Encapsulations |
| Albion Laboratories |
| Innophos |
| BASF SE |
| Archer Daniels Midland (ADM) |
| Kemin Industries |
| NOW Foods |
| Solgar Inc. |
| Others |
Value Network & Pricing Analysis
Shandong and Jiangsu province glycine production concentrates upstream cost leverage for magnesium chelate manufacturers, compressing margin pools downstream toward EFSA-compliant formulators with validated chelate content specifications. Contract manufacturers in the Frankfurt-Rhine-Main cluster capture premium positioning through certificate-of-analysis procurement mandates that filter price-sensitive spot buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across agricultural fertilizer channels. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived organic forms from synthetic glycinate and commodity inorganic salts. Cost compression in synthetic tiers intensifies because Shandong glycine oversupply feeds contract renegotiation. Agribusiness cooperatives in Southern Europe exhibit highest price sensitivity; Swiss dietary supplement manufacturers show least sensitivity due to EFSA novel food compliance requirements.
Supply Chain Analysis
Extended payment terms from German toll-processors to Shandong amino acid suppliers stabilize working capital across the chelation value chain. Manufacturing concentrates in China, Germany, and the Netherlands; raw material dependencies rest on fermentation-derived glycine, L-aspartic acid, and magnesium oxide feedstock. Single-source vulnerability runs through Shandong glycine capacity concentration. Distribution runs through Rotterdam bulk terminals for liquid chelates and Frankfurt specialized chemical distributors for powder formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with EFSA novel food pathway expansion, as bioequivalence opinion diversification creates niches for ligand-specific specialists beyond incumbent patent holders.
For Market Incumbents: Pre-empt REACH dossier consolidation by acquiring mid-tier registrants with incomplete Annex IX toxicological data packages. Patent-holding mineral technology licensors should deepen backward integration into fermentation-derived amino acid supply to offset glycine price volatility threatening margin stability. For New Entrants and Emerging Players: Establish a beachhead in veterinary injectable liquid chelates, where stability-profile requirements filter competition more than capital scale. Spanish and Portuguese greenhouse cooperatives offer the most penetrable agribusiness channel; lead with hydroponic fertigation technical service capabilities rather than commodity pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing platforms in North American dietary supplement corridors. Five-to-ten year viability hinges on EFSA consolidated positive list outcomes; watch for ECHA guidance updates on complex substance identification as inflection signal for chelate speciation analytical capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Fermentation | Captive glycine supply insulates Albion Laboratories and BASF SE from Shandong price volatility. |
| Continuous Flow Reactor Licensing Partnership | Contract manufacturers in Utah supplement corridors adopt solvent-reduction technology for EFSA submission readiness. |
| EFSA Novel Food Dossier Expansion | Multi-ligand bioequivalence opinions unlock fortified food applications beyond established glycinate systems. |
| REACH Annex IX Data Package Completion | Full toxicological registration filters agricultural micronutrient competitors from EU commercial volumes. |
| Veterinary Injectable Channel Development | Liquid chelate stability profiles displace inorganic solutions in ruminant deficiency correction protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food opinions, ECHA REACH registration databases, and customs trade data for glycine and magnesium chelate shipments. Interviews with fermentation plant managers, dietary supplement procurement leads, agricultural cooperative technical directors, and specialized chemical distributors informed supply chain mapping. Bottom-up volume estimates from chelation reactor capacity and top-down demand triangulation from premix manufacturer offtake patterns were cross-validated.
Forecast inputs include product type segmentation across powder, liquid, and complex chelates; form differentiation between organic fermentation-derived and synthetic chemical synthesis; application splits across agricultural fertilizers, nutraceuticals, and animal feed; and end-user procurement sophistication tiers. CAGRs were derived from ligand-specific volume trajectories and price elasticity modeling across the projection horizon. Industry-specific inputs incorporate EFSA opinion issuance timelines and greenhouse cultivation expansion rates in Mediterranean protected agriculture.
Sensitivities concentrate around EFSA consolidated positive list revisions and REACH substance identification guidance updates. Forecasts reflect assumptions on amino acid feedstock cost stabilization and chelate stability testing protocol standardization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Encapsulated Lactic Acid Market