
 Phenylbenzimidazole Sulfonic Acid Market | 2026-2036
Phenylbenzimidazole Sulfonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylbenzimidazole Sulfonic Acid Market Analytics
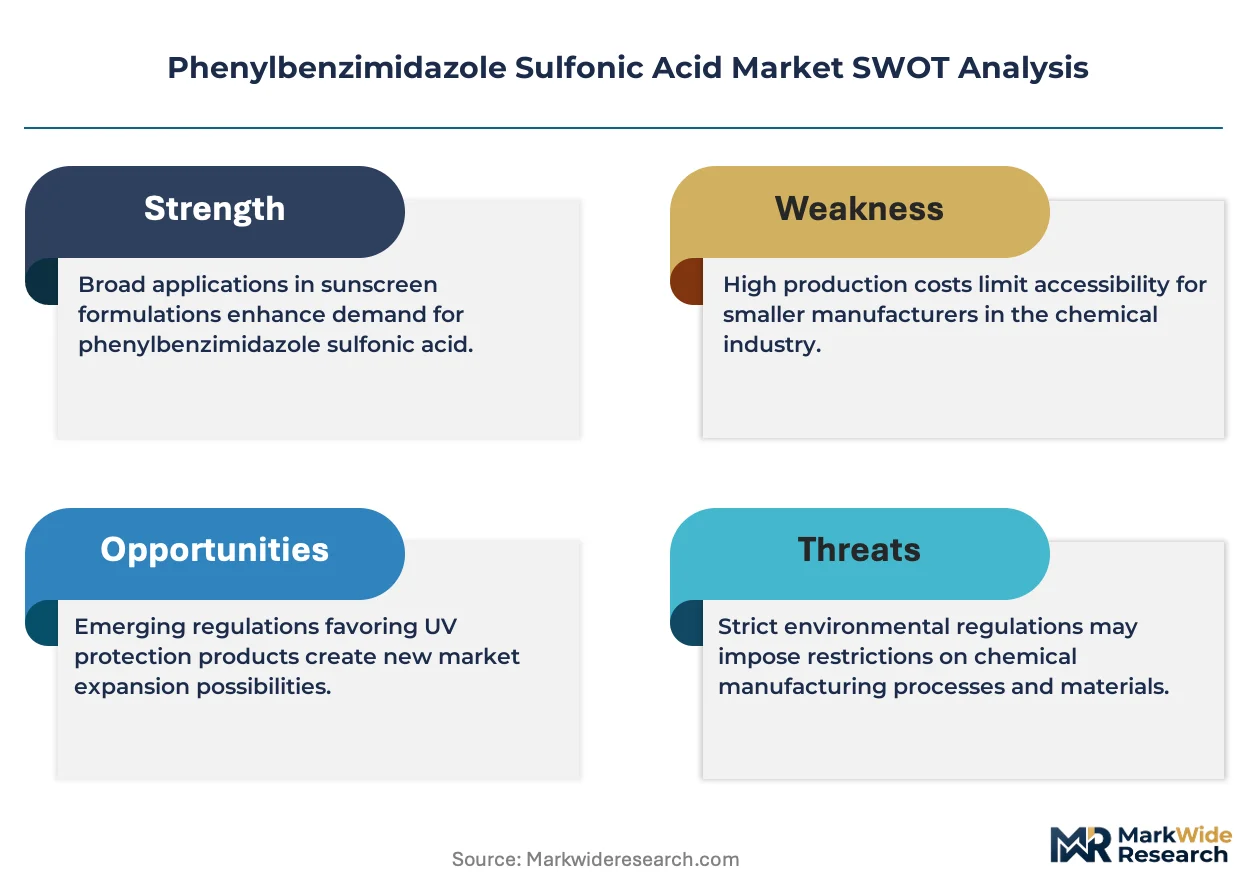
China is fragmenting as domestic intermediate producers scale sulfonic acid capacity for export markets. BASF SE leverages its integrated aromatics chain to sustain cost-advantaged supply of benzimidazole derivatives. Clariant AG anchors European quality positioning through pharmaceutical-grade certification. Evonik Industries AG specializes in high-purity grades for sensitive cosmetic applications.
Phenylbenzimidazole sulfonic acid functions as a water-soluble organic UV-B filter with an absorption maximum near 310 nanometers, synthesized through sulfonation of 2-phenylbenzimidazole under controlled temperature conditions. The compound serves primarily as an active sunscreen agent in oil-free and clear cosmetic formulations where photostability and water solubility prove critical. Active ingredient grades command premium positioning as cosmetic brands reformulate toward reef-safe and photostable UV protection. UV filter applications dominate volume offtake while stabilizer demand in plastics accelerates from automotive interior specifications. Raw material sourcing faces margin compression from benzimidazole precursor volatility.
REACH registration requirements in Europe govern substance volume thresholds and toxicological data packages for cosmetic ingredient placement. FDA sunscreen monograph compliance in the United States dictates permitted active concentrations and labeling protocols for over-the-counter drug-cosmetic hybrids. China's NMPA and SAMR enforce new cosmetic ingredient notification rules that extend approval timelines for imported UV filters. Stakeholders must monitor regulatory divergence between jurisdictions as ingredient authorization lags fragment market access timelines.
Market Dynamics
REACH compliance deadlines in Western Europe are compressing formulation timelines for cosmetic manufacturers, forcing rapid substitution of legacy UV filters with photostable alternatives that satisfy both safety dossier requirements and reef-safe marketing claims.
Growth Catalysts
- REACH authorization pressure:ECHA's tightening scrutiny on organic UV filter safety profiles accelerates reformulation cycles toward benzimidazole derivatives with complete toxicological data packages.
- Reef-safe positioning:Hawaii and Key West bans on oxybenzone and octinoxate redirect sunscreen brand R&D spending toward water-soluble UV-B alternatives that bypass marine toxicity concerns.
- Automotive interior specifications:Polymer stabilization demand from dashboard and trim manufacturers in Germany's automotive corridor expands off-label applications beyond personal care.
Market Restraints
- Benzimidazole precursor volatility:Aromatic amine feedstock costs fluctuate with crude oil derivatives and agricultural aniline supply, squeezing contract manufacturer margins.
- Single-source sulfonation capacity:China's concentration of intermediate production creates geographic risk for European and North American formulators dependent on imported sulfonic acid grades.
- Photostability ceiling:The 310 nanometer absorption maximum limits efficacy against full UV-B spectrum, requiring combination with other actives that complicate formulation chemistry.
Strategic Opportunities
- India personal care expansion:CDSCO's streamlined cosmetic ingredient notification process opens regulatory pathways for imported UV filters serving domestic sunscreen manufacturers.
- Stabilizer convergence:Integration of UV-B protection with HALS polymer stabilization creates dual-function additives for outdoor construction plastics and agricultural films.
- Direct-to-brand distribution:Specialty chemical houses bypass traditional distributor networks to capture margin from multinational cosmetic formulators consolidating supplier bases.
Industry Challenges
- Toxicologist certification scarcity:REACH-compliant safety assessor capacity constraints extend dossier preparation timelines by eight to fourteen months for new cosmetic ingredient registrations.
- Multijurisdictional filing complexity:Divergent data requirements between ECHA, FDA sunscreen monograph updates, and China's NMPA notification rules force redundant testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylbenzimidazole Sulfonic Acid Market |
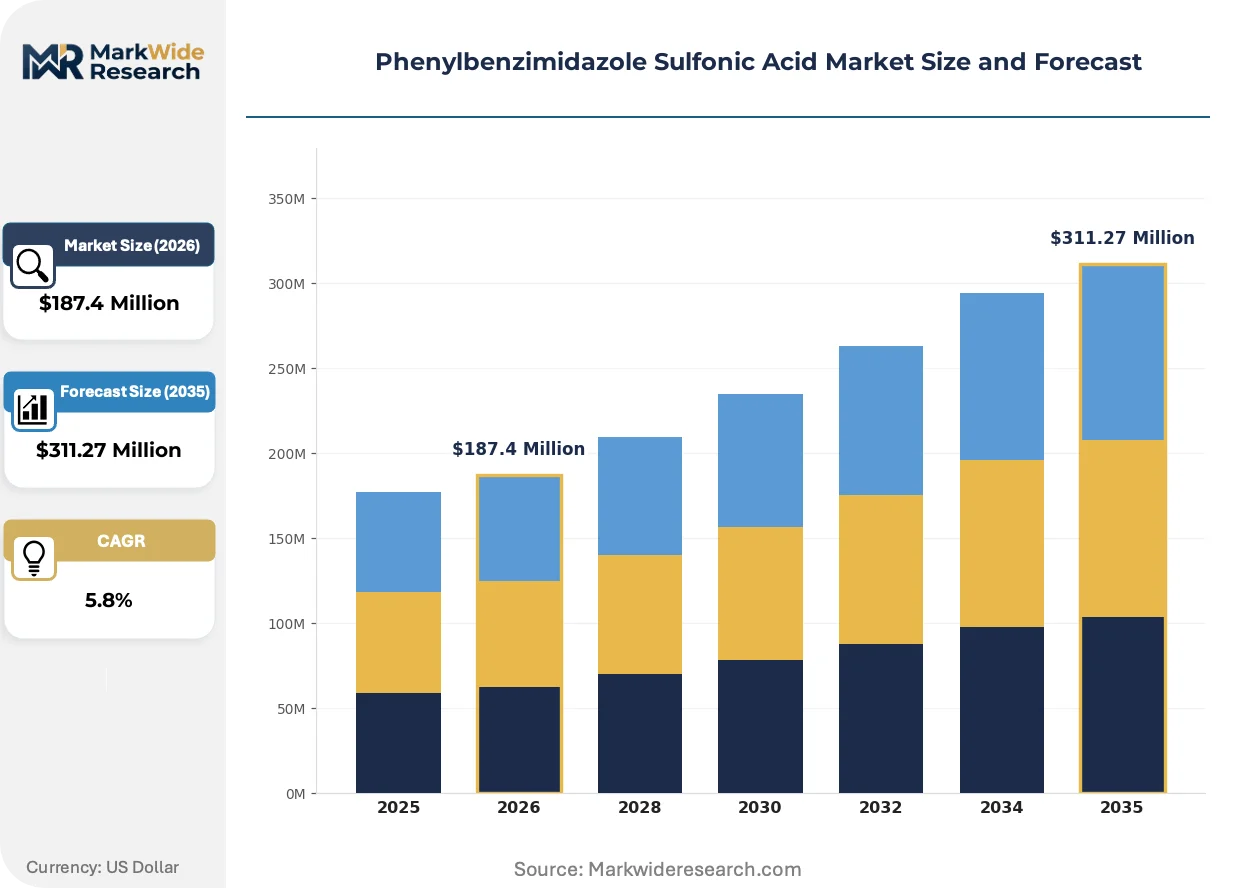
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Material, Intermediate, Active Ingredient, Functional Additive End User: Cosmetics, Pharmaceuticals, Agrochemicals, Plastics Application: UV Filter, Stabilizer, Pigment, Antioxidant Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Clariant AG, Shanghai Hanhong Chemical, BASF SE, Merck KGaA, J&K Scientific, DSM, Evonik Industries AG, Galaxy Surfactants Ltd., Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylbenzimidazole Sulfonic Acid Market Evolving Landscape
Formulation science is converging with regulatory foresight as cosmetic chemists engineer UV filters that satisfy preemptive bans on marine-toxic actives while maintaining photostability under accelerated aging protocols.
Encapsulation technology using silica and melanin-derived shells is collapsing the trade-off between water solubility and photostability that has constrained benzimidazole derivative performance. Premium sunscreen brands in France and South Korea adopt these hybrid particles to extend protection duration without increasing active loading. The structural consequence compresses differentiation between commodity and specialty UV filter grades.
REACH authorization list expansion is systematically disqualifying competing organic UV filters from European cosmetic formulations. ECHA's 2024-2025 substance evaluation roadmap targets additional benzophenone derivatives, redirecting formulator attention toward pre-registered alternatives with favorable toxicological profiles. German and Dutch cosmetic ingredient houses accelerate dossier completion for phenylbenzimidazole sulfonic acid to capture substitution demand.
Clean beauty certification programs are rewiring procurement criteria beyond regulatory minimums toward voluntary standards that restrict additional substance classes. Sephora's Clean at Sephora and Ulta's Conscious Beauty criteria now exclude certain sulfonic acid salts, forcing ingredient suppliers to segment production lines by certification tier. This behavioral shift concentrates volume with suppliers maintaining parallel pharmaceutical-grade and cosmetic-grade manufacturing capabilities.
Phenylbenzimidazole Sulfonic Acid Market Segmentation
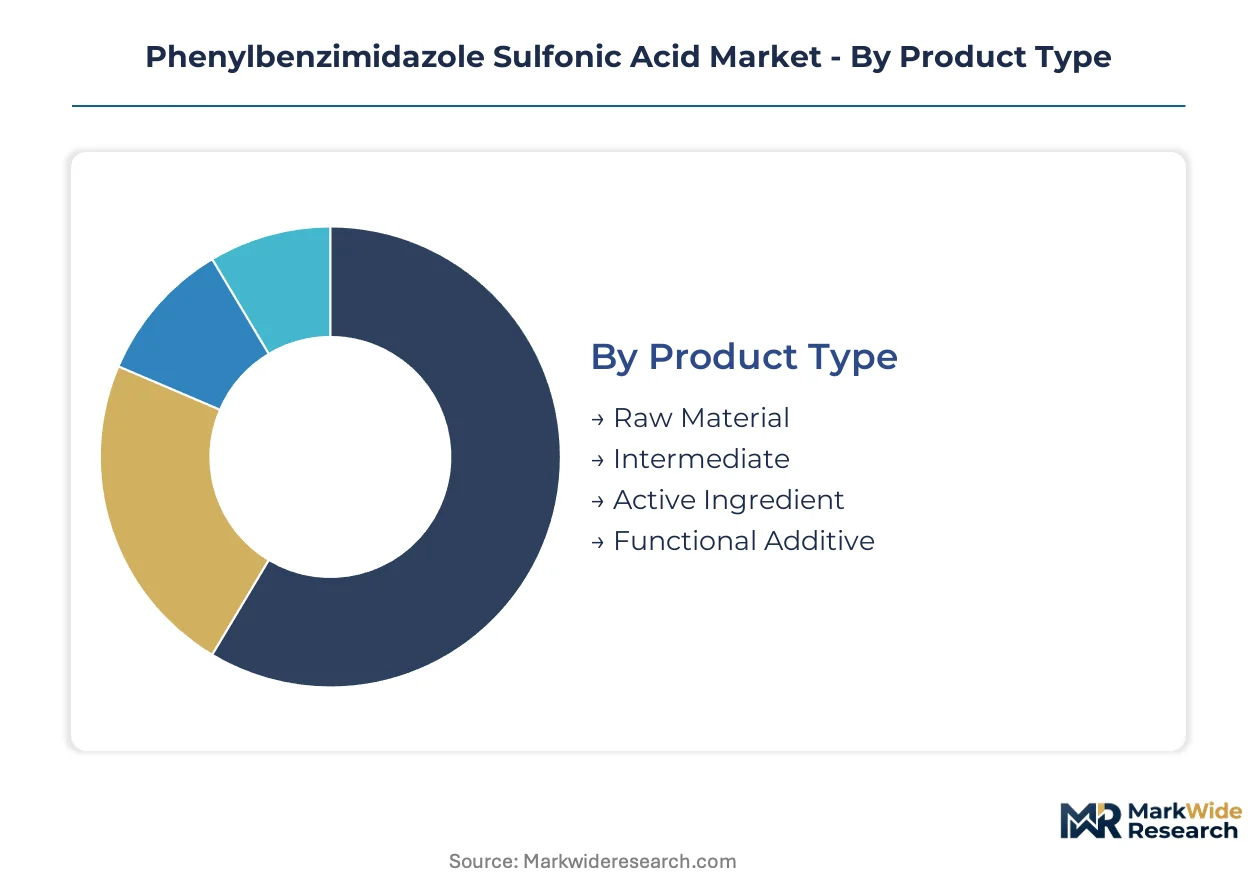
Phenylbenzimidazole sulfonic acid traverses multiple value chain tiers, from commodity sulfonation intermediates to pharmaceutical-grade actives. Segment-level profitability diverges sharply based on certification burden and customer concentration. Formulation houses prioritize supply security over unit economics for active ingredient grades.
Product Type:
Cycle times compress from years for active ingredient dossier maintenance to weeks for raw material spot trading. Inventory velocity and margin stability vary inversely across this spectrum.
- Active Ingredient:Pharmaceutical-grade material with complete REACH toxicological dossiers and FDA sunscreen monograph compliance. Demand clusters with German and French cosmetic formulators serving reef-safe sunscreen brands replacing banned benzophenone derivatives. ECHA substance evaluation timelines dictate procurement urgency.
- Intermediate:Sulfonated benzimidazole derivatives awaiting final purification and certification. Chinese producers in Jiangsu and Shandong provinces scale capacity for export to European toll manufacturers facing REACH registration deadlines.
- Raw Material:Crude sulfonation outputs with minimal processing. Spot-market trading dominates with pricing indexed to aniline feedstock volatility.
- Functional Additive:Blended formulations incorporating HALS stabilizers for polymer applications. Automotive interior specifications in Germany's manufacturing corridor drive qualification programs.
Active Ingredient dominates installed base. Intermediate is where expansion concentrates.
End User:
Customer sophistication determines service intensity, with cosmetics requiring technical support and plastics demanding volume reliability.
- Cosmetics:Sunscreen and daily-wear UV protection formulations. South Korean and French premium brands adopt encapsulated variants for extended photostability claims. Clean beauty certification programs segment procurement tiers.
- Plastics:Dashboard and trim stabilization for automotive interiors. German OEM specifications mandate UV-B protection combined with thermal stability for cabin components.
- Pharmaceuticals:Excipient and active applications with GMP manufacturing requirements. Swissmedic and Health Canada oversight elevates documentation burden.
- Agrochemicals:Crop protection formulation stabilizers. Agricultural film manufacturers in Spain and Italy specify UV resistance for greenhouse coverings.
Cosmetics commands premium pricing. Plastics is climbing the fastest on volume uptake.
Application:
Performance specifications fragment by end-use environment, from aqueous cosmetic matrices to high-temperature polymer processing.
- UV Filter:Primary sunscreen active with 310 nanometer absorption maximum. Hawaii and Key West marine toxicity bans redirect R&D spending from oxybenzone toward water-soluble benzimidazole alternatives.
- Stabilizer:Polymer protection against photodegradation in outdoor construction and automotive applications. HALS convergence creates dual-function additives for agricultural films.
- Pigment:Color-stable derivatives for coatings and inks. Niche demand from industrial formulation houses.
- Antioxidant:Secondary thermal stabilization in polymer compounding. Substitution for hindered phenol alternatives in food-contact applications.
UV Filter anchors revenue concentration. Stabilizer is gaining share fastest on automotive specification expansion.
Packaging Type:
Handling economics and contamination risk shape format selection across supply chain tiers.
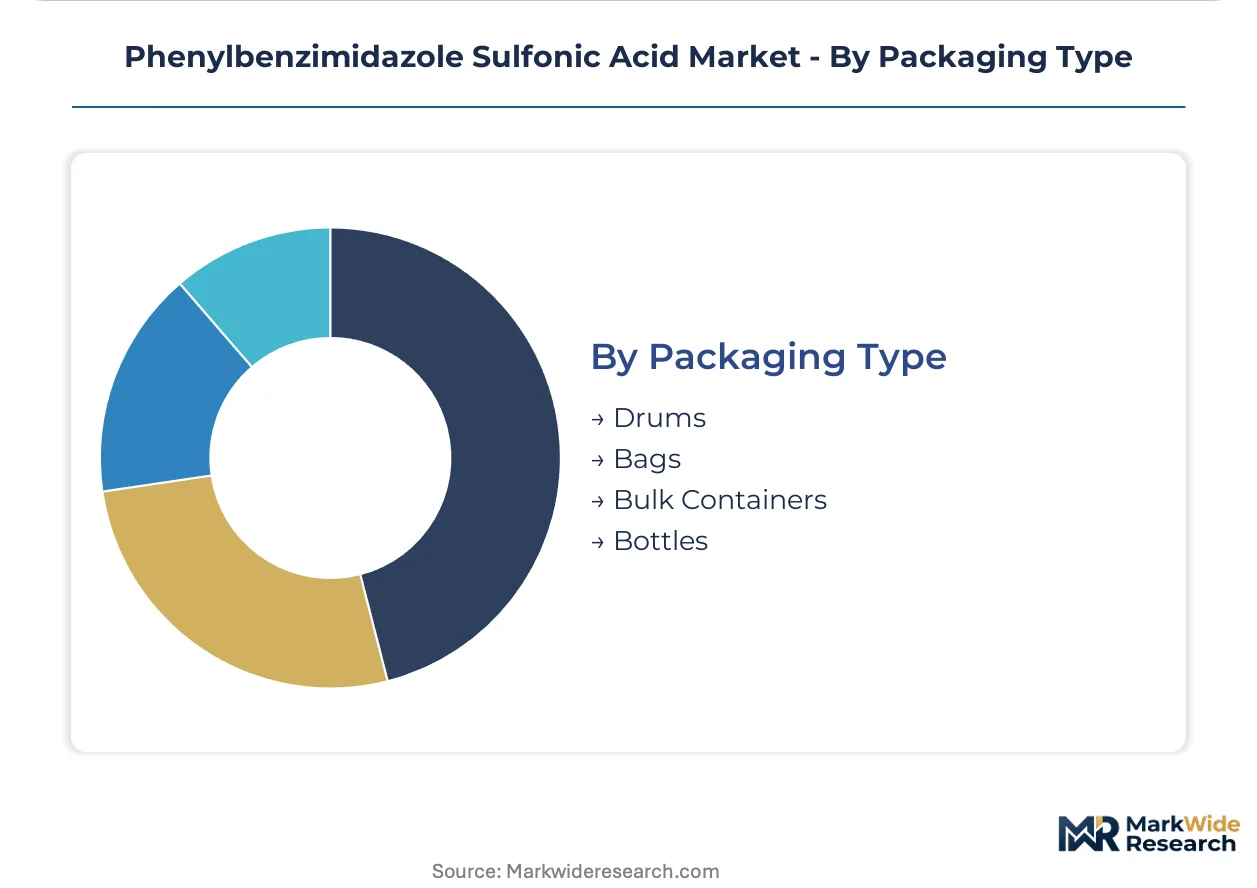
- Drums:Standard 200-liter steel and polyethylene containers for mid-volume cosmetic ingredient shipments. German logistics hubs maintain drum cleaning and reconditioning networks.
- Bulk Containers:Intermediate bulk containers and tank trucks for polymer stabilizer deliveries to automotive compounders. Just-in-time contracts with BASF and Evonik manufacturing sites.
- Bags:Multi-layer laminated sacks for powder-grade intermediates. Chinese export packaging with moisture barrier specifications.
- Bottles:Laboratory and sampling quantities for formulation development. Direct-to-brand distribution bypasses traditional distributor markups.
Drums dominate installed base. Bulk Containers is where expansion concentrates on automotive contract volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH authorization timelines compress formulation cycles across Western Europe, while Asia-Pacific capacity expansion and North American reef-safe legislation redirect trade flows for benzimidazole-derived UV filters.
Germany
Cosmetic ingredient houses cluster along the Rhine-Main chemical corridor to access REACH-compliant toxicological assessors. The country's Federal Institute for Risk Assessment (BfR) coordinates sunscreen safety evaluations with ECHA substance evaluation roadmaps. BASF and Evonik manufacturing sites in Ludwigshafen and Essen supply pharmaceutical-grade actives to French and Dutch formulators facing 2024-2025 registration deadlines.
China
Jiangsu and Shandong provinces scale sulfonation capacity for export markets as domestic intermediate producers capture toll manufacturing contracts from European REACH registrants. NMPA and SAMR notification rules extend approval timelines for imported UV filters, incentivizing local production. Shanghai Hanhong Chemical anchors the Yangtze River Delta cluster serving both cosmetic and polymer stabilization demand.
United States
FDA sunscreen monograph compliance dictates permitted active concentrations for over-the-counter drug-cosmetic hybrids. Hawaii and Key West marine toxicity bans on oxybenzone redirect brand R&D spending toward water-soluble benzimidazole alternatives. California-based clean beauty brands drive qualification programs for reef-safe UV filter grades.
France
ANSM oversight of cosmetic ingredient safety converges with ECHA authorization pressure to accelerate substitution of legacy benzophenone derivatives. Premium sunscreen brands in the Île-de-France region adopt encapsulated phenylbenzimidazole variants for extended photostability claims. Clariant AG's French operations anchor European pharmaceutical-grade certification capacity.
India
CDSCO's streamlined cosmetic ingredient notification process opens regulatory pathways for imported UV filters serving domestic sunscreen manufacturers. Galaxy Surfactants Ltd. in Maharashtra state qualifies benzimidazole derivatives for personal care formulators targeting Southeast Asian export markets. Mumbai-Pune chemical corridor capacity expansion addresses regional supply security concerns.
Phenylbenzimidazole Sulfonic Acid Market Competitive Landscape
Integrated aromatics specialists and pharmaceutical-grade certifiers split the market between cost-advantaged supply chains and regulatory-compliant active ingredient positioning. The vendor base concentrates around three strategic archetypes: multinational chemical conglomerates with backward integration into benzimidazole precursors, European specialty houses with REACH dossier expertise, and Chinese intermediate producers scaling sulfonation capacity for toll export. Dominant competitive moves include capacity expansion in Asia-Pacific sulfonation corridors and strategic partnerships between European formulators and dossier completion specialists.
Among integrated chemical conglomerates, BASF SE exemplifies the archetype of captive aromatics supply chains sustaining cost-advantaged benzimidazole derivative production. Evonik Industries AG occupies a position within the high-purity grade specialization tier, serving sensitive cosmetic applications where pharmaceutical-grade certification commands premium positioning. Clariant AG anchors the European quality positioning archetype through regulatory dossier completion capabilities that accelerate REACH-compliant market access.
| Leading Market Players |
|---|
| Clariant AG |
| Shanghai Hanhong Chemical |
| BASF SE |
| Merck KGaA |
| J&K Scientific |
| DSM |
| Evonik Industries AG |
| Galaxy Surfactants Ltd. |
| Symrise AG |
| Others |
Value Network & Pricing Analysis
Jiangsu and Shandong province sulfonation capacity concentration feeds directly into margin capture by European toll manufacturers completing REACH dossiers. Active ingredient grades command substantial premiums over intermediate trading tiers as certification burden and toxicological assessor scarcity create supply bottlenecks.
Pricing Analysis
Geographic price spreads between Chinese intermediate exports and European pharmaceutical-grade actives exceed threefold multiples. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels segments buyer access by certification completeness. Cost compression in intermediate trading runs through aniline feedstock volatility and spot-market indexing. Polymer stabilizer buyers exhibit highest price sensitivity due to specification commoditization, while reef-safe sunscreen brands absorb premium positioning with minimal volume negotiation.
Supply Chain Analysis
Tariff exposure between China and Western Europe dominates supply chain risk planning for benzimidazole derivative procurement. Production gravity centers on Jiangsu and Shandong provinces for sulfonation, Germany for pharmaceutical-grade finishing, and India for emerging toll capacity. Raw material dependencies draw from aniline feedstocks, sulfuric acid supply, and benzimidazole precursor availability. Single-source sulfonation vulnerability concentrates risk for European formulators. Distribution runs through specialty chemical distributors for mid-volume cosmetic ingredient shipments and direct-to-brand contracts for automotive polymer stabilizer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-compliant toxicological assessor availability constrains market access timelines, creating competitive advantage for incumbents with completed dossiers and stranded capacity for challengers awaiting certification.
For Market Incumbents: Build captive toxicological assessment capabilities to accelerate dossier completion cycles as ECHA substance evaluation timelines compress. Expand sulfonation capacity in India to diversify geographic risk from Chinese intermediate concentration. Anchor supply security contracts with French and German cosmetic formulators facing 2024-2025 registration deadlines. For New Entrants and Emerging Players: Build out polymer stabilizer qualification programs targeting German automotive OEM specifications where dual-function HALS convergence creates white-space demand. Penetrate India's CDSCO-streamlined notification pathway before incumbent supply contracts solidify. Pursue direct-to-brand distribution models bypassing legacy distributor markups in clean beauty certification tiers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty chemical houses holding REACH dossier libraries but lacking Asian manufacturing footprint. Long-term viability hinges on regulatory compliance durability across jurisdictions rather than commodity cost position. Monitor ECHA authorization list expansion velocity as the inflection signal for substitution demand magnitude.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | BASF's Ludwigshafen aromatics chain demonstrates margin defense against agricultural supply volatility. |
| REACH Dossier Completion Partnership | Clariant's regulatory expertise accelerates market access timelines for cosmetic ingredient substitution cycles. |
| Encapsulation Technology Licensing | South Korean premium brands adopt silica-shell variants for extended photostability claims. |
| Automotive Stabilizer Qualification Program | German OEM dashboard specifications mandate UV-B protection combined with thermal stability. |
| Direct-to-Brand Distribution Buildout | Evonik's high-purity grade positioning captures margin from consolidating multinational formulators. |
Research Methodology
A spread of perspectives from cosmetic formulators, polymer compounders, regulatory affairs specialists, and specialty chemical distributors converged on the working assumptions driving this analysis. Primary fieldwork with REACH compliance officers and toxicological assessors in Germany's Rhine-Main corridor combined with secondary validation from ECHA substance evaluation roadmaps, FDA sunscreen monograph updates, and customs trade data. Bottom-up volume estimates from sulfonation capacity installations triangulated against top-down demand modeling from sunscreen formulation trends and automotive specification expansion.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework. Segmentation dimensions modeled include product grade tier, end-use industry, application function, and regional regulatory cluster. CAGRs derived from installed capacity expansion rates, substitution elasticity estimates, and customer procurement cycle timing. Industry-specific forecast inputs incorporated REACH authorization list expansion velocity and marine toxicity ban implementation schedules.
Practitioners should monitor ECHA substance evaluation timeline shifts, aniline feedstock price volatility, and clean beauty certification program expansion for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
VCI Aerosol Market