
 Silver Paste Market | 2026-2036
Silver Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Paste Market Intelligence
Custom formulation development for specific end-use applications is rebalancing the traditional volume-based sales model in the silver paste sector. Heraeus Electronics leverages its deep R&D in photovoltaic pastes to serve leading solar cell manufacturers. DuPont competes on the basis of its broad portfolio of electronic materials, including specialized conductive pastes for advanced packaging. Giga Solar Materials Corp. specializes in high-performance front-side silver pastes for solar applications.
Silver paste is a functional material composed of fine silver particles suspended in a matrix of glass frit, resin, and organic solvents. Its primary purpose is to form conductive traces, electrodes, and interconnects on various substrates after a high-temperature sintering or curing process. Conductive pastes for solar cells dominate application volumes, driven by the renewable energy end-user segment. However, adhesive and thermal pastes for the semiconductor industry represent a high-value, technically demanding category.
Regulatory frameworks such as the EU's RoHS directive heavily influence material composition, restricting the use of hazardous substances. Concurrently, standards from China's MIIT and disposal guidelines from the US EPA shape manufacturing processes and waste management for electronic materials. Suppliers must navigate the persistent challenge of balancing high silver content for performance against price volatility and customer cost pressures.
Market Dynamics
The silver paste market's trajectory is defined by the technological race in the photovoltaic sector. The industry-wide transition to higher-efficiency solar cell architectures like TOPCon and HJT demands new paste formulations, creating a performance-driven innovation cycle concentrated in China.
Growth Catalysts
- Renewable Energy Mandates:National policies, including the EU Green Deal and China's dual carbon goals, accelerate solar panel installations, directly increasing consumption of front-side metallization pastes for photovoltaic cells.
- Advanced Photovoltaic Technologies:The shift toward TOPCon and HJT solar cells creates demand for specialized, low-temperature curing silver pastes that enable finer line printing and improved cell efficiency.
- 5G and IoT Expansion:Growth in telecommunications and connected devices drives demand for silver pastes used in manufacturing multilayer ceramic capacitors (MLCCs), resistors, and other critical passive components.
Market Restraints
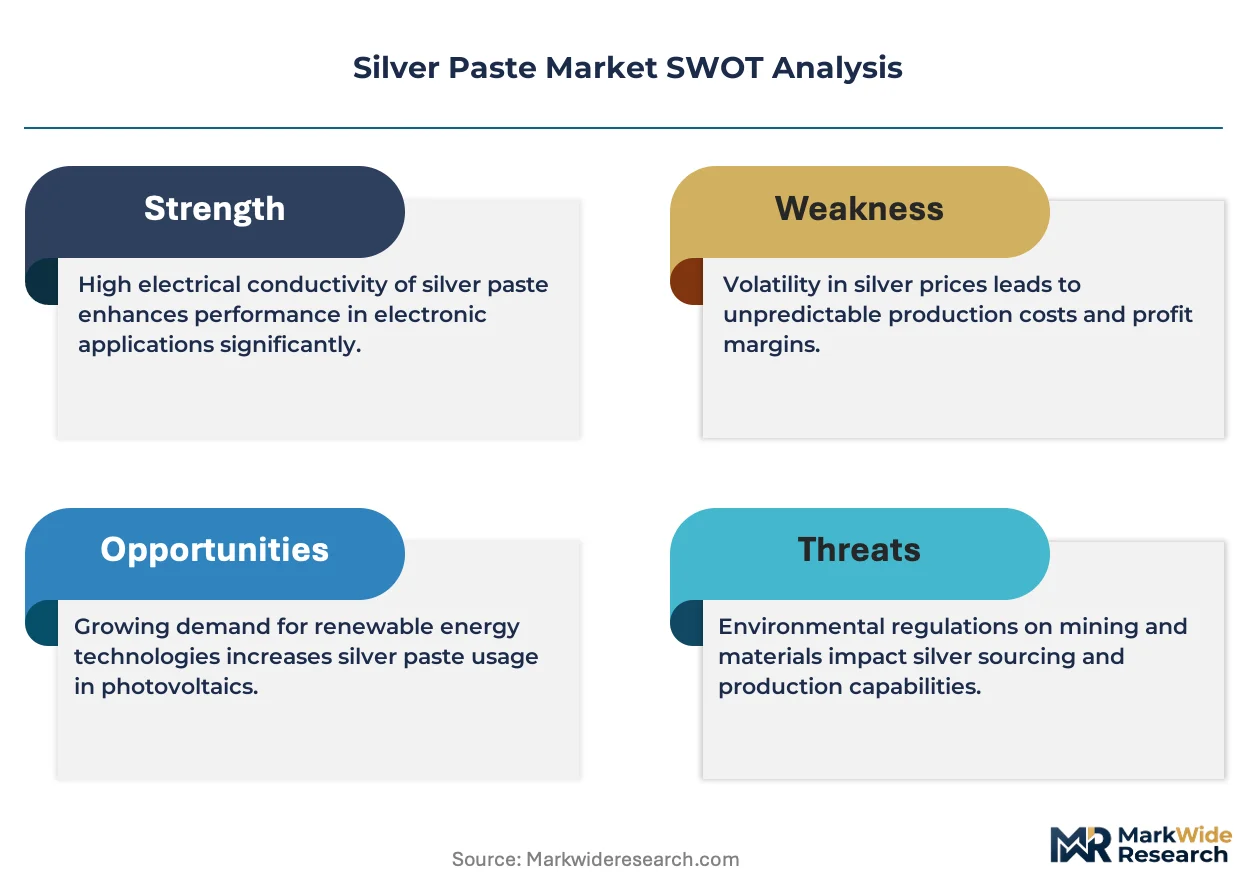
- Silver Price Volatility:High dependence on silver as the primary raw material exposes paste manufacturers and their customers to significant commodity price fluctuations, complicating cost management and pressuring margins.
- Threat of Copper Substitution:In certain cost-sensitive and lower-performance applications, ongoing research and development into copper-based conductive pastes presents a long-term substitution risk for silver-based products.
- Technical Limits in Fine-Line Printing:Achieving the ultra-fine line widths required for next-generation solar cells without compromising electrical conductivity or mechanical adhesion remains a significant material science and processing hurdle.
Strategic Opportunities
- Flexible and Wearable Electronics:The emergence of printed electronics on flexible substrates like PET films opens a new application frontier for low-temperature curable silver pastes in sensors, antennas, and smart textiles.
- High-Value Thermal Pastes:Formulating silver pastes for thermal interface materials (TIMs) in advanced semiconductor packaging, LED lighting, and electric vehicle power modules represents a high-margin growth area.
- Low-Silver Content Formulations:Developing hybrid pastes with silver-coated copper particles or reduced silver loading offers a direct solution to cost pressures, appealing to large-volume solar cell manufacturers.
Industry Challenges
- Hazardous Waste Management:Adherence to environmental regulations, such as disposal guidelines from the US EPA, for waste streams containing silver particles and organic solvents increases operational complexity and cost.
- Formulation and Qualification Cycles:Developing and qualifying custom pastes for specific end-user processes, particularly for new photovoltaic technologies, involves long and resource-intensive R&D cycles.
- Raw Material Sourcing Risks:A high concentration of suppliers for essential inputs like high-purity silver powder and specialized glass frits creates potential for supply chain bottlenecks and price instability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Paste Market |
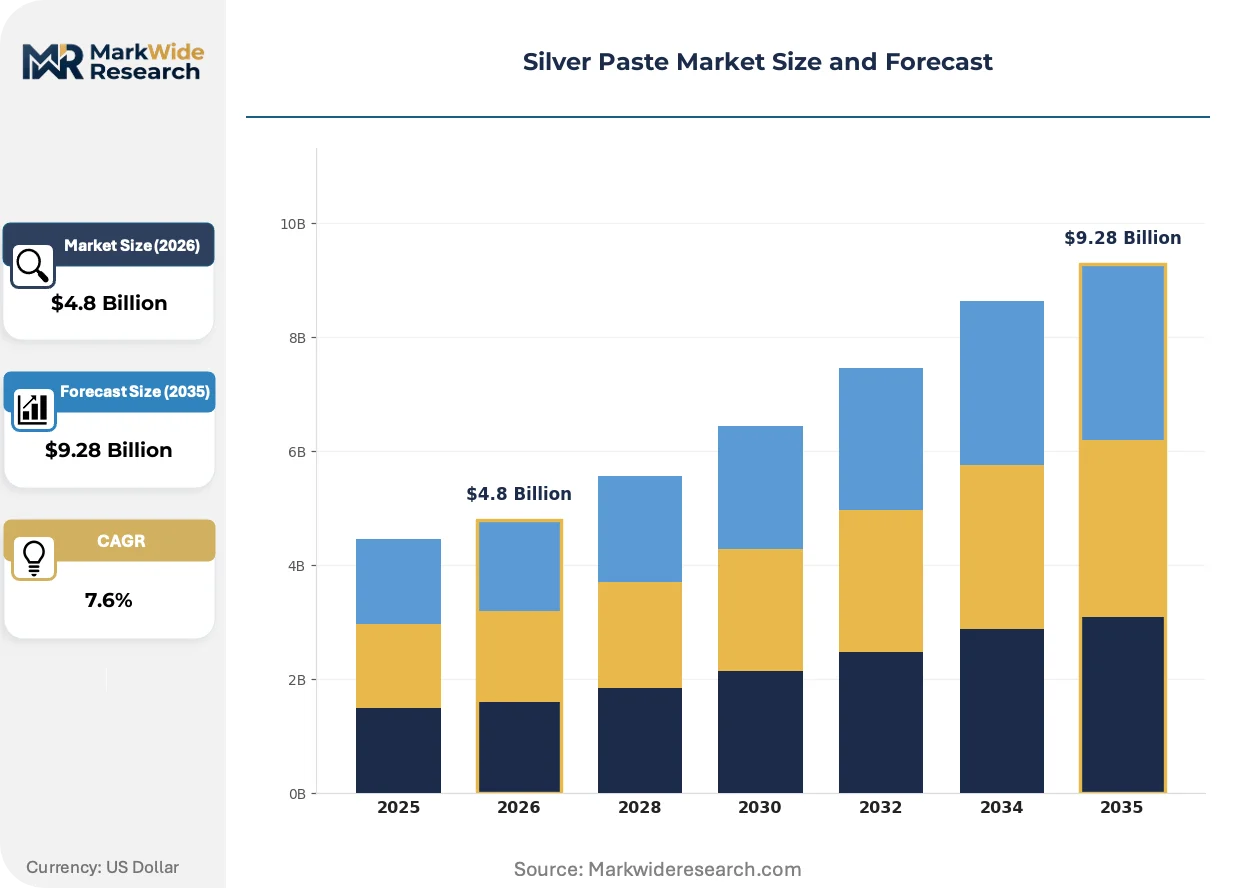
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Paste, Thermal Paste, Adhesive Paste, Specialty Paste Application: Solar Cells, Electronics, LED Manufacturing, Coatings End User: Semiconductor Industry, Renewable Energy, Consumer Electronics, Automotive Sector Form: Powder, Paste, Ink, Sheet |
| Companies Covered | Henkel AG & Co. KGaA, Johnson Matthey PLC, Heraeus Electronics, Daejoo Electronic Materials Co., Ltd., Taiyo Holdings Co., Ltd., DuPont, Mitsubishi Materials Corporation, Sun Chemical Corporation, Giga Solar Materials Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Paste Market Strategic Shifts & Innovations
Innovation is driven by a fundamental tension between the need for higher electrical performance for advanced electronics and the persistent pressure to reduce material costs. This dynamic forces continuous evolution in material science, particularly in binder systems and particle morphology, to optimize the performance-to-cost ratio.
Low-temperature curing pastes are a critical product evolution designed for temperature-sensitive substrates. Solar manufacturers are rapidly adopting these formulations for advanced cell types like heterojunction (HJT) that cannot withstand traditional high-temperature sintering. This technology is consolidating the market around suppliers with advanced chemical expertise, as they are the only ones capable of delivering reliable adhesion and conductivity below conventional processing temperatures.
The European Union's Restriction of Hazardous Substances (RoHS) directive continues to influence material composition. This regulation restricts the use of lead and other hazardous materials in electronic components, forcing paste producers to reformulate their glass frit and binder systems. The semiconductor and consumer electronics segments are most affected, requiring significant R&D to develop compliant pastes that maintain high electrical and mechanical performance.
A notable shift in purchasing behavior involves a move from transactional, volume-based orders to collaborative, application-specific formulation partnerships. This change disrupts the traditional sales model, especially for high-performance solar pastes, replacing it with long-term development agreements between suppliers and cell producers. This trend is most visible in China, where major photovoltaic manufacturers work directly with paste suppliers to co-develop custom materials for their specific TOPCon production lines.
Silver Paste Market Segmentation
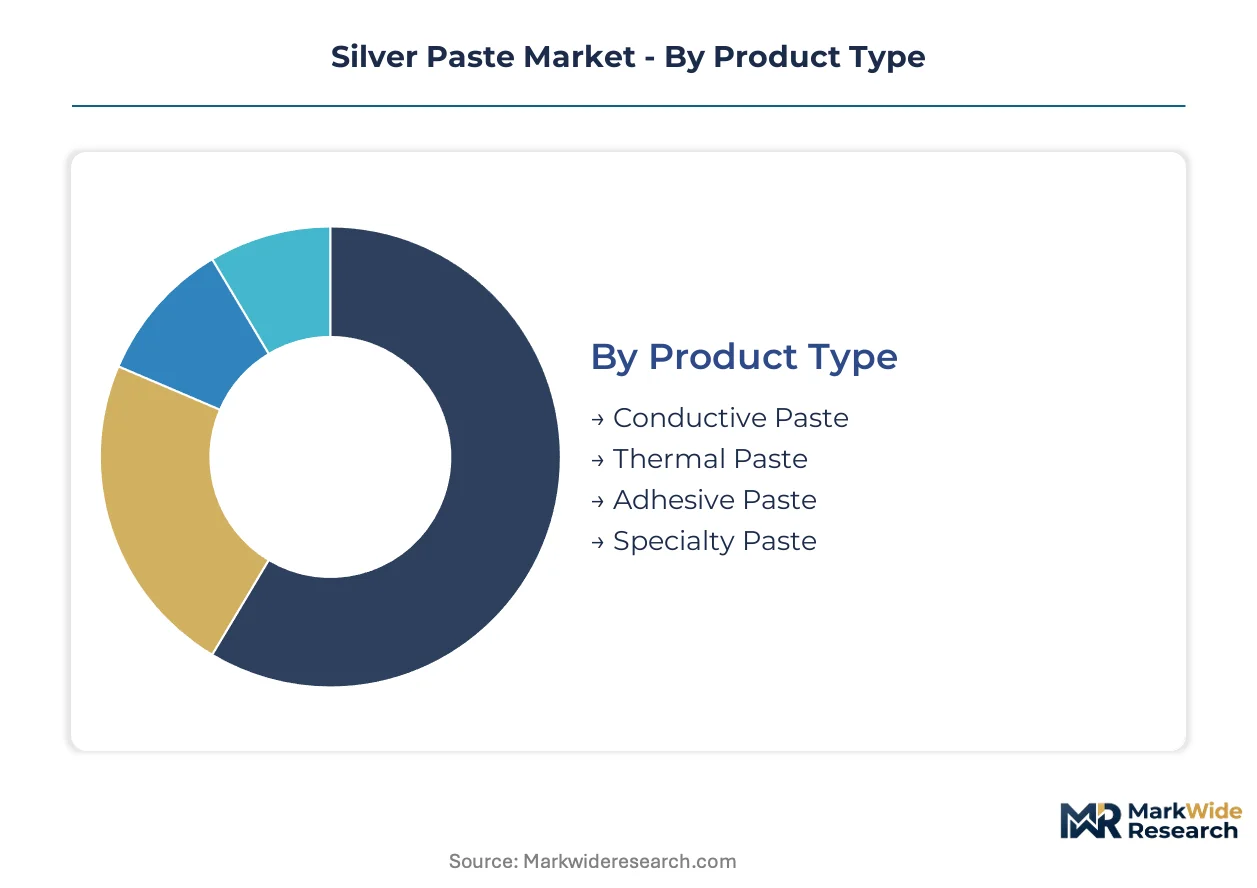
The silver paste market segmentation reflects a diverse range of material compositions and application requirements. Understanding these distinct categories is essential for manufacturers to tailor product development and for end-users to optimize material selection for specific performance criteria in advanced electronics and energy systems.
Product Type:
The product type dimension highlights the spectrum from highly customized, application-specific formulations to more standardized, high-volume offerings.
- Conductive Paste:This functional material consists of fine silver particles suspended in a matrix; it forms electrical pathways after sintering. Conductive pastes dominate solar cell metallization volumes, driven by global renewable energy mandates and China's massive photovoltaic production.
- Thermal Paste:Engineered for high thermal conductivity, these pastes facilitate efficient heat dissipation in electronic devices. Thermal pastes are critical for advanced semiconductor packaging in high-power applications, such as electric vehicle power modules.
- Adhesive Paste:These formulations provide both mechanical bonding and electrical connection; they are widely used in electronic assembly for attaching components to substrates.
- Specialty Paste:Custom-developed for unique performance demands, specialty pastes address specific requirements in niche applications like flexible and wearable electronics.
Most installed capacity flows through Conductive Paste. Expansion is steepest in Thermal Paste.
Application:
Application segments reveal how silver paste consumption is distributed across various industries, indicating areas of high volume versus specialized use.
- Solar Cells:This sector utilizes silver paste primarily for front-side metallization in photovoltaic panels; it drives substantial paste volume due to the global push for renewable energy.
- Electronics:A broad application area encompassing printed circuit boards, sensors, and passive components; it supports the expansion of 5G infrastructure and IoT devices.
- LED Manufacturing:Silver pastes form reflective layers and conductive paths within LED packages; this enhances the light output and operational lifespan of LED lighting solutions.
- Coatings:Applied for electromagnetic shielding, anti-static properties, or decorative finishes; these coatings serve specialized industrial and consumer product requirements.
Solar Cells represent the largest application volume. Electronics applications are experiencing rapid diversification.
End User:
The end-user segmentation illustrates which industries are the primary consumers, reflecting their technological demands and market dynamics.
- Renewable Energy:This sector is the leading consumer, primarily for solar cell metallization; it is propelled by national policies like the EU Green Deal and China's dual carbon goals.
- Semiconductor Industry:Employs silver pastes for advanced packaging, die attach, and thermal interface materials; this industry demands high-performance, specialized formulations for miniaturization and reliability.
- Consumer Electronics:Utilizes silver pastes in manufacturing multilayer ceramic capacitors (MLCCs) and printed circuitry; it supports the compact and high-density designs of modern devices.
- Automotive Sector:Incorporates silver pastes for various components, including sensors, heating elements, and advanced driver-assistance systems; this requires robust, high-reliability materials for demanding operating environments.
The Renewable Energy sector commands the largest share of paste consumption. The Semiconductor Industry offers significant high-value growth.
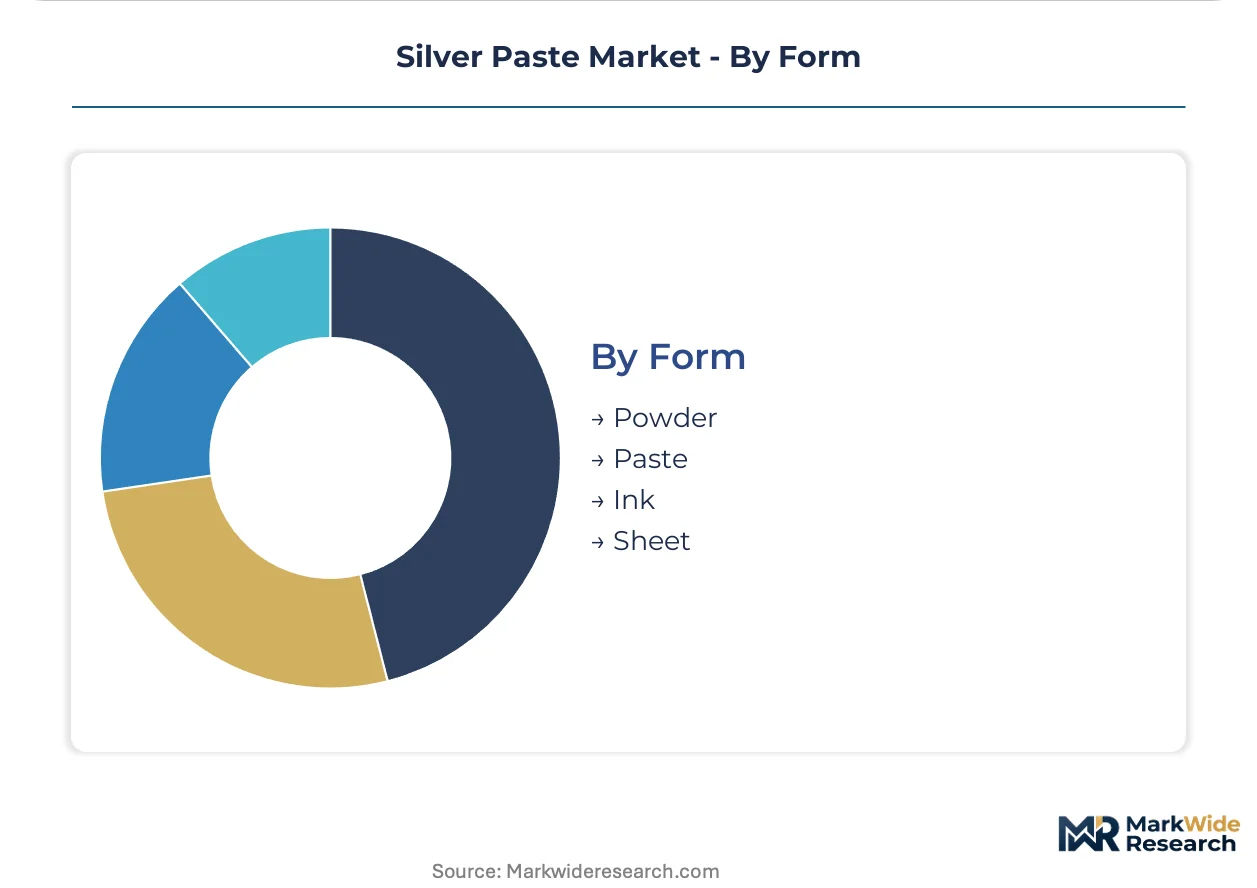
Form:
The form category distinguishes silver paste products by their physical state and intended manufacturing process, highlighting different processing requirements.
- Powder:This is the raw material input for producing various silver paste formulations; it is primarily traded as a commodity input for paste manufacturers.
- Paste:A viscous suspension of silver particles, glass frit, and organic vehicles; it is typically applied via screen printing for high-volume applications like solar cells and electronic components.
- Ink:Lower viscosity formulations designed for inkjet or aerosol jet printing processes; this enables ultra-fine line printing for flexible electronics and advanced packaging.
- Sheet:Pre-formed films or foils with precise silver patterns; these are used in specialized applications requiring consistent geometries and simplified processing.
Paste is the most prevalent form for high-volume applications. Ink formulations are gaining traction for advanced manufacturing techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China drives immense volumes in silver paste consumption, the United States focuses on high-value semiconductor applications. Global renewable energy mandates and expanding electronics production influence regional market trajectories. Each geography presents distinct demand patterns for advanced paste formulations.
China
China's vast solar panel manufacturing capacity creates substantial demand for front-side metallization pastes. The MIIT promotes domestic material innovation to support its dual carbon goals. Major photovoltaic manufacturers in provinces like Jiangsu and Anhui co-develop custom paste formulations with suppliers.
United States
The United States semiconductor industry requires high-performance silver pastes for advanced packaging and thermal management. The EPA's disposal guidelines shape waste management practices for electronic materials. Silicon Valley and Austin-based tech clusters drive demand for specialized conductive and thermal pastes.
Germany
Germany's automotive sector and industrial electronics production create demand for robust silver pastes. EU Green Deal initiatives accelerate solar energy adoption, influencing paste consumption. Bavaria's advanced manufacturing hubs focus on high-reliability materials for electric vehicle power modules.
South Korea
South Korea's leadership in display technologies and memory semiconductors requires advanced silver paste solutions. Local material standards influence product development for high-density electronic components. The Gyeonggi Province, a major electronics cluster, sees significant innovation in conductive paste applications.
Japan
Japan's precision electronics and specialized industrial applications drive demand for high-quality silver pastes. METI policies support advanced material research for next-generation devices. Osaka and Nagoya's electronics manufacturing centers focus on fine-line printing and low-temperature curing formulations.
Silver Paste Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the silver paste market structure. This market exhibits a tiered consolidation, with a few large, established players dominating high-volume solar and electronics applications. Archetypes include diversified chemical giants, specialized materials providers, and regional niche players. Portfolio diversification and strategic partnerships represent dominant competitive moves among these participants.
Specialists in high-performance materials like Heraeus Electronics and DuPont exemplify the premium segment, focusing on advanced research and development for demanding applications. Heraeus Electronics, a German company, leverages its deep R&D in photovoltaic pastes to serve leading solar cell manufacturers globally. DuPont, a US-based chemical giant, occupies a position with its broad portfolio of electronic materials, including specialized conductive pastes for advanced packaging. Giga Solar Materials Corp., a Taiwan-based company, represents a focused provider of high-performance front-side silver pastes for solar applications, emphasizing high-efficiency photovoltaic technologies.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Johnson Matthey PLC |
| Heraeus Electronics |
| Daejoo Electronic Materials Co., Ltd. |
| Taiyo Holdings Co., Ltd. |
| DuPont |
| Mitsubishi Materials Corporation |
| Sun Chemical Corporation |
| Giga Solar Materials Corp. |
| Others |
Cost & Logistics Intelligence
The industry-wide transition to higher-efficiency solar cell architectures like TOPCon simultaneously reshapes cost economics and supply concentration. This shift demands specialized, low-temperature curing silver pastes, increasing R&D investment and favoring suppliers with advanced chemical expertise.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume conductive pastes used in solar applications. The dominant pricing model for these materials is contract-based long-term offtake, especially for major photovoltaic manufacturers. Price differentiation stems from the customization level required for advanced PV technologies and the volume scale of orders. Cost compression from Chinese solar manufacturers intensifies pricing pressure across all segments. Solar cell manufacturers are highly price-sensitive, while the semiconductor industry exhibits lower price sensitivity for high-value thermal and adhesive pastes.
Supply Chain Analysis
Single-source vulnerability sits with high-purity silver powder suppliers, a critical input for all paste formulations. Geographic supply concentration for silver paste manufacturing centers heavily in China, with raw silver mining primarily occurring in countries like Australia, Mexico, and Peru. Key raw material dependencies include high-purity silver powder, specialized glass frits, and organic solvents. Commodity price volatility for silver represents a significant structural risk for paste manufacturers. Distribution typically runs through direct sales channels for large original equipment manufacturers and specialized distributors for smaller accounts and niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards high-value thermal pastes for advanced semiconductor packaging.
For Market Incumbents: Acquire specialized R&D capabilities in low-temperature curing chemistries. Consolidate market share in advanced TOPCon and HJT paste formulations to mitigate the threat of copper substitution. Investment in low-silver content formulations represents a key lever against persistent cost pressures. Reinforce long-term development agreements with leading solar cell manufacturers.
For New Entrants and Emerging Players: Begin with niche, high-value applications such as flexible electronics or advanced thermal interface materials. The most penetrable segment for new players involves specialized thermal pastes for electric vehicle power modules. A strong go-to-market angle involves offering custom formulation partnerships, particularly for performance-critical semiconductor applications. Focus on developing proprietary binder systems for unique performance requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with strong intellectual property in specific paste chemistries. Long-term viability hinges on companies positioned in high-performance materials for advanced packaging and next-generation photovoltaic technologies. Acquisition targets should include firms possessing proprietary binder systems or strong R&D pipelines in low-temperature curing. The rapid adoption rate of new PV technologies serves as a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Supports the massive solar panel production volume and domestic material innovation goals. |
| R&D Investment in Low-Temperature Curing | Enables adoption for temperature-sensitive advanced solar cells and flexible electronics. |
| Strategic Partnership with Solar OEMs | Secures long-term supply contracts and facilitates co-development of custom formulations. |
| Green Manufacturing Transition | Ensures compliance with strict environmental regulations like EU RoHS and US EPA guidelines. |
| Portfolio Diversification into Thermal Pastes | Captures high-margin growth from advanced semiconductor packaging and EV power modules. |
Research Approach
Multiple input streams — primary interviews, industry reports, and financial disclosures — were reconciled for comprehensive market understanding. This approach combined direct conversations with R&D directors, procurement managers, solar cell engineers, and electronics manufacturers. Secondary data sources included MIIT reports, EPA guidelines, company annual reports, and trade association publications, triangulated with bottom-up and top-down analyses.
Data-stream reconciliation validated segment-specific growth trends across the analysis window. The analytical framework modeled market dynamics across product type, application, end-user, form, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, future demand projections, and technological adoption curves. Key forecast inputs included global solar installation rates and advancements in semiconductor packaging technologies.
Several conditions sit outside the modeled scope, including geopolitical shifts and unforeseen raw material supply disruptions. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Silver price volatility and accelerated copper substitution represent specific risk factors that could revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Global Imaging Chemicals Market
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Global 5G EMI Materials Market
Electronic Chemicals
Electronic Chemicals Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Global Electronic Materials and Chemicals Market