
 Software Protection Dongle Market | 2026-2036
Software Protection Dongle Market Size, Share, and Industry Trends Forecast 2026-2036
Software Protection Dongle Market Analytics
A capital-intensity divergence between integrated security chip fabricators and software-only licensing vendors is redrawing competitive boundaries in software protection hardware. Wibu-Systems leverages proprietary ASIC designs to anchor premium positioning in industrial automation licensing. SafeNet competes through Thales-backed supply chain scale across enterprise IT security deployments. Keylok specializes in cost-optimized USB dongle manufacturing for mid-market software publishers seeking physical license enforcement without custom silicon investment.
A software protection dongle is a physical hardware device that attaches to a computer port—typically USB, serial, or parallel—to authenticate software execution and enforce license terms through embedded cryptographic processors and secure memory elements. The device generates encrypted license verification tokens that prevent unauthorized duplication or concurrent use beyond purchased entitlements. USB dongles dominate volume shipments due to universal port compatibility and minimal driver dependencies across operating systems. Hardware security modules command premium pricing within digital rights management use cases where tamper-resistant key storage justifies higher unit costs. Network dongles serve multi-workstation environments through centralized license pooling, though this segment faces displacement pressure from cloud-native floating license servers.
Germany's BSI technical guidelines, the United States FCC equipment authorization requirements, and China's GB/T cryptographic module standards collectively shape hardware security device compliance obligations for cross-border vendors. ETSI standards in Europe and NIST FIPS 140-2 alignment in North America further segment certification costs and market access timelines. Stakeholders must monitor whether browser-based WebAssembly licensing and TPM-backed machine fingerprinting erode the addressable base for discrete dongle hardware before committing to capacity expansion.
Market Dynamics
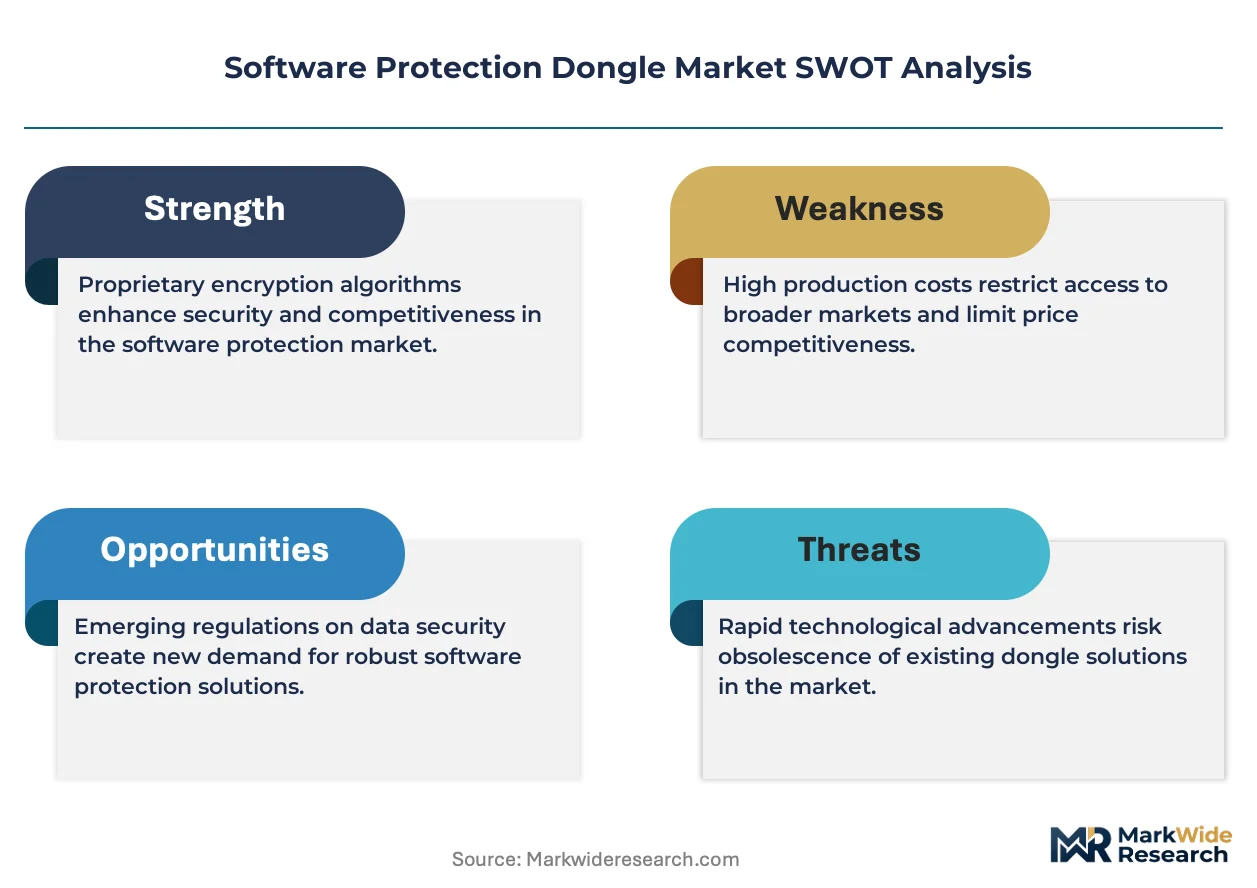
USB-C and NFC interface integration is decomposing legacy USB-A form factor dominance across European industrial automation sectors, forcing hardware vendors to redesign physical token architectures while maintaining backward cryptographic compatibility with installed license management systems.
Growth Catalysts
- BSI Technical Guidelines:Germany's federal cybersecurity agency mandates tamper-resistant hardware for critical infrastructure software licensing, creating procurement pull across energy and manufacturing sectors.
- Cloud-Hybrid Deployments:Enterprise software vendors require physical license anchors for on-premise components even as SaaS layers expand, sustaining dongle demand in mixed environments.
- IP Protection Standards:Stricter enforcement regimes in the United States, Germany, and China compel software publishers to deploy hardware-backed enforcement rather than pure software licensing.
Market Restraints
- Semiconductor Supply Concentration:Secure element fabrication concentrates among a handful of Asian foundries, exposing dongle vendors to single-source risk for cryptographic processors.
- Cloud-Native Substitution:Browser-based WebAssembly licensing and TPM-backed machine fingerprinting erode the addressable base for discrete hardware tokens in SMB segments.
- Certification Timeline Friction:NIST FIPS 140-2 validation cycles extend 18-24 months, delaying product launches for vendors targeting North American government and defense buyers.
Strategic Opportunities
- Industrial IoT Expansion:Edge device authentication in factory automation creates demand for ruggedized, wide-temperature-range dongles with extended operational lifecycles.
- EU Cybersecurity Act:Common Criteria certification mandates for critical digital infrastructure create a compliance-driven replacement cycle across European enterprise software deployments.
- Network Dongle Convergence:License pooling hardware integrated with zero-trust network architectures addresses multi-site manufacturing environments seeking centralized entitlement management.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Secure firmware development and side-channel attack mitigation require specialized expertise that commands premium compensation in tight labor markets.
- Legacy System Integration Complexity:Dongle vendors must maintain driver compatibility across decades-old industrial control systems while supporting modern operating system security architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Protection Dongle Market |
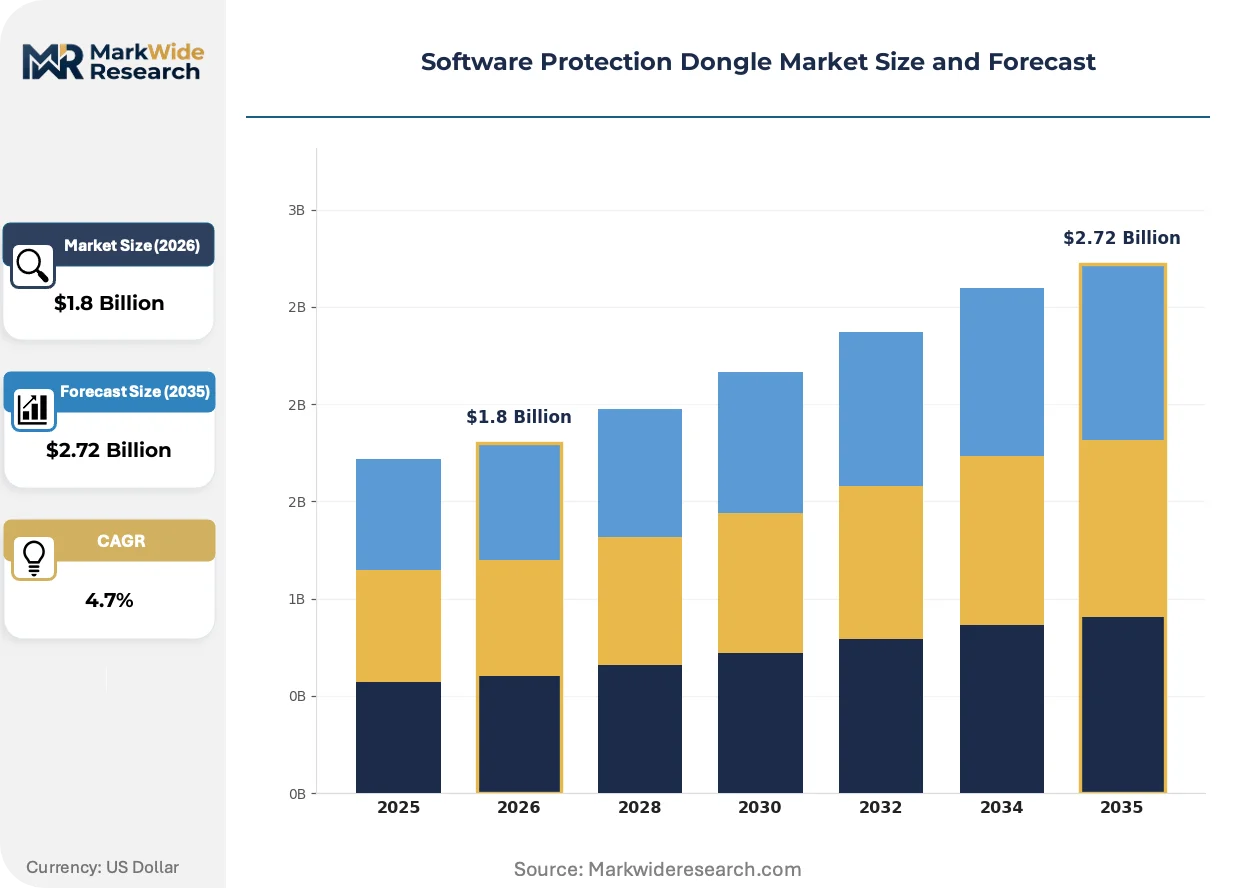
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Dongles, Network Dongles, Hardware Security Modules, Smart Card Readers Use Case: Gaming Software, SaaS Applications, Digital Rights Management, Industrial Control Systems End User: Software Developers, Gaming Companies, IT Security Firms, Educational Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Value-Added Resellers |
| Companies Covered | Wibu-Systems, Keylok, SafeNet, CodeMeter, Reprise Software, Thales, Microcosm, Protector Software, Gemalto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Protection Dongle Market Evolving Landscape
Hardware security architectures are fragmenting across interface standards and cryptographic implementations, with vendors racing to embed quantum-resistant algorithms before regulatory mandates crystallize.
USB-C form factors with integrated secure elements are decomposing the historical USB-A installed base in European industrial automation. German automotive and machine tool manufacturers are standardizing on reversible connectors with power delivery capabilities. This physical transition is compressing margins for dongle vendors managing dual-SKU inventories while accelerating obsolescence of legacy token designs.
ETSI consumer IoT cybersecurity standards and the EU Cybersecurity Act are mandating hardware-backed device authentication for software controlling connected industrial equipment. Equipment manufacturers must now certify license enforcement mechanisms as part of overall product security assessments. Medical device and automotive software suppliers face the steepest compliance ramps under these frameworks.
Subscription licensing models are unbundling perpetual hardware purchases from software entitlement duration. Industrial software buyers in the United States now prefer term-based license pools with hardware tokens as renewable authentication anchors rather than permanent physical assets. This shift compresses average contract values while expanding recurring revenue relationships for vendors who restructure pricing accordingly.
Software Protection Dongle Market Segmentation
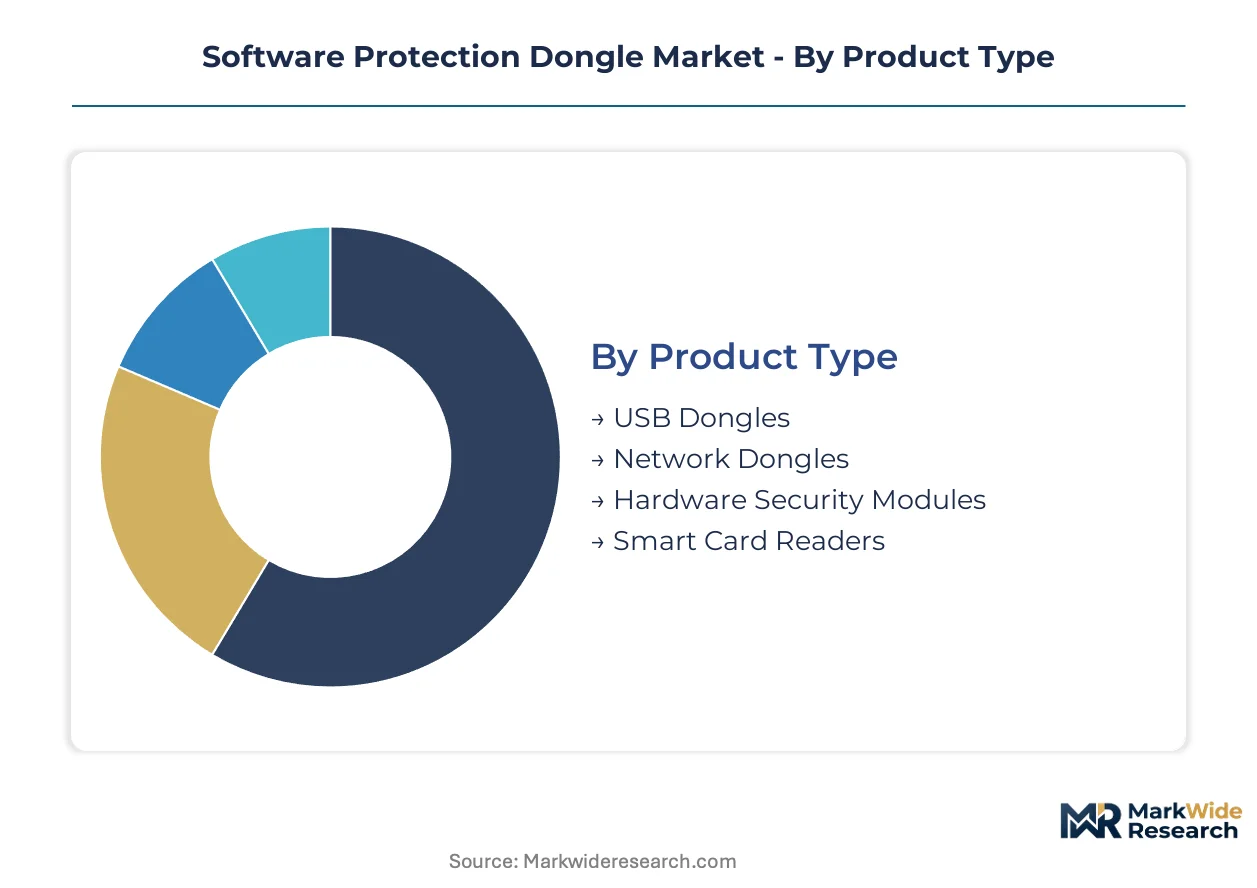
Product architecture, deployment context, and procurement channel each reshape margin structures and compliance burdens across the software protection dongle market. Vendors must align form factor decisions with interface standards, while end-use verticals dictate tamper-resistance specifications and certification requirements.
Product Type:
FCC equipment authorization in the United States, BSI technical guidelines in Germany, and GB/T cryptographic module standards in China segment certification costs and hardware engineering priorities across physical token categories.
- USB Dongles:Universal serial bus tokens embed secure elements within compact removable enclosures, with USB-C form factors displacing legacy USB-A designs across European industrial automation. German machine tool manufacturers and automotive software suppliers concentrate procurement here, driven by BSI mandates for tamper-resistant hardware in critical infrastructure licensing.
- Network Dongles:Centralized license servers pool entitlements across multi-workstation environments through ethernet-connected hardware appliances. Demand clusters in United States enterprise IT deployments seeking zero-trust architecture integration, though cloud-native floating license servers exert displacement pressure in mid-market accounts.
- Hardware Security Modules:Tamper-resistant processors with dedicated cryptographic acceleration command premium positioning in digital rights management and high-assurance government applications.
- Smart Card Readers:Contact and contactless interface devices support PKI-based authentication for enterprise software licensing in regulated European financial services.
Established volume favors USB Dongles; emerging adoption favors Network Dongles.
Use Case:
Application-specific threat models and licensing complexity determine whether vendors deploy discrete hardware tokens or migrate toward software-based enforcement.
- Gaming Software:Anti-piracy dongles protect AAA title distribution through encrypted license verification, with Chinese publishers facing strict IP protection enforcement from SAMR.
- SaaS Applications:Hybrid cloud deployments sustain physical token demand for on-premise software components even as subscription layers expand, particularly among German enterprise vendors.
- Digital Rights Management:High-value content protection commands hardware security module deployment for tamper-resistant key storage in United States media distribution.
- Industrial Control Systems:Ruggedized wide-temperature-range dongles authenticate edge device software in factory automation, with EU Cybersecurity Act mandates accelerating replacement cycles across European manufacturing.
Industrial Control Systems dominate procurement scale; SaaS Applications climb the fastest as cloud-hybrid architectures proliferate.
End User:
Technical sophistication and compliance exposure stratify purchasing criteria across buyer categories, from cost-optimized volume procurement to custom silicon development.
- Software Developers:Independent publishers and mid-market ISVs seek cost-optimized USB dongle solutions without proprietary ASIC investment, concentrating procurement through distributor channels.
- Gaming Companies:AAA studios and regional publishers deploy hardware-backed enforcement for boxed and digital distribution, with Chinese studios responding to strengthened IP protection standards.
- IT Security Firms:Enterprise security vendors integrate dongle-based licensing into broader identity and access management portfolios, favoring FIPS 140-2 validated hardware for North American government contracts.
- Educational Institutions:Volume licensing programs for campus-wide software deployment drive demand for network dongles with concurrent user pooling across laboratory environments.
IT Security Firms command premium pricing tolerance; Educational Institutions represent the most price-sensitive procurement segment.
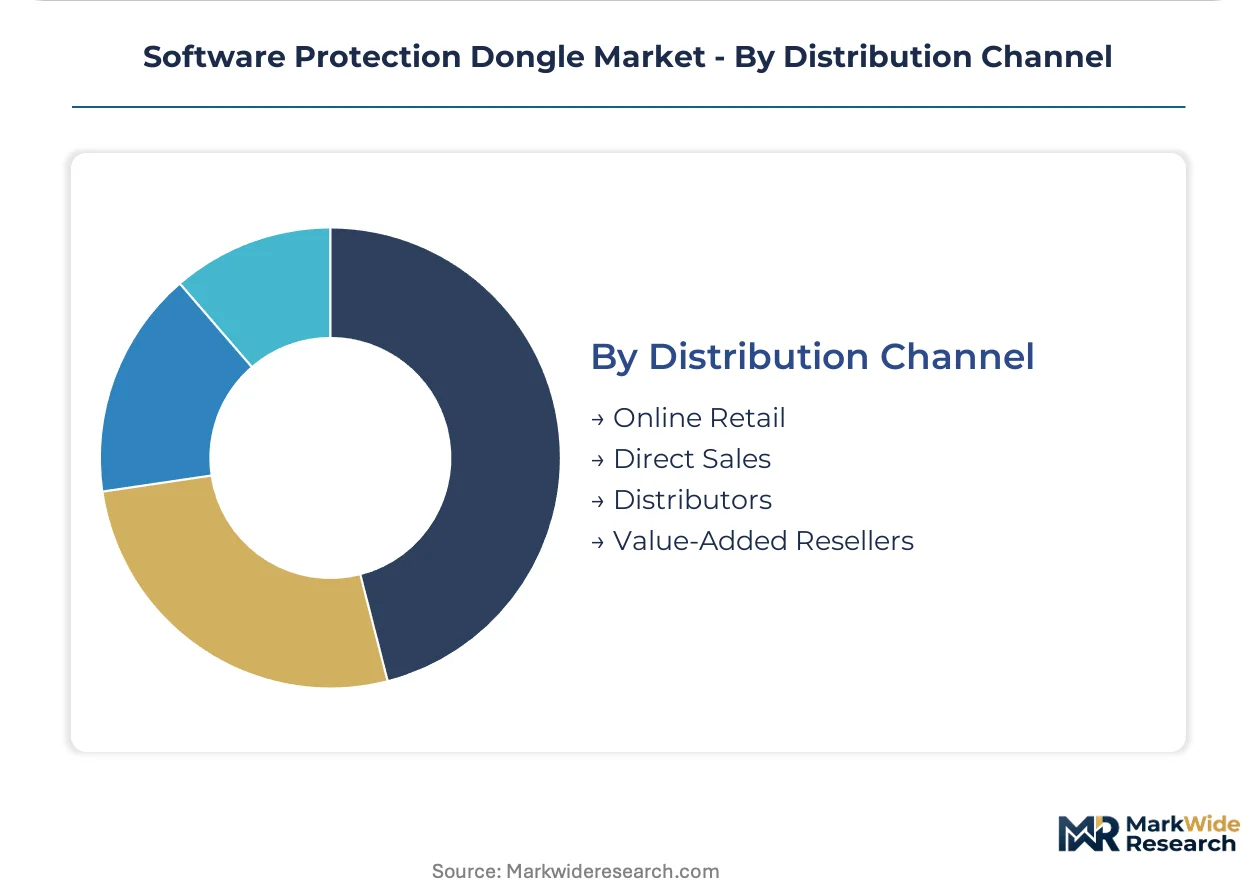
Distribution Channel:
Channel economics and technical support requirements shape how vendors reach fragmented end-user bases across geographies and verticals.
- Online Retail:Direct-to-publisher procurement platforms serve cost-sensitive independent developers and small ISVs with standardized USB dongle SKUs and rapid fulfillment.
- Direct Sales:Enterprise account teams engage major software publishers and industrial automation vendors for customized hardware security architectures and long-term entitlement management contracts.
- Distributors:Broadline and specialty electronics distributors aggregate mid-market demand across European and North American territories, managing inventory for multi-SKU product lines.
- Value-Added Resellers:Systems integrators bundle dongle-based licensing with implementation services for industrial control and medical device software deployments under EU regulatory frameworks.
Distributors capture the highest transaction volume; Value-Added Resellers secure the steepest margin expansion on complex deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation buyers favor ruggedized USB-C tokens with BSI certification, while United States enterprise procurement prioritizes FIPS-validated hardware for federal contracts. Chinese gaming publishers drive volume demand for cost-optimized dongles under tightened IP enforcement.
United States
Federal defense contractors and enterprise IT security vendors anchor procurement of hardware security modules with NIST FIPS 140-2 validation. FCC equipment authorization requirements extend product launch timelines for cryptographic devices. Silicon Valley software publishers and Washington DC-area government contractors concentrate demand for high-assurance license enforcement tokens.
Germany
Automotive software suppliers and machine tool manufacturers standardize on USB-C form factors with integrated secure elements. BSI technical guidelines mandate tamper-resistant hardware for critical infrastructure licensing across energy and manufacturing sectors. Munich and Stuttgart industrial clusters drive replacement cycles as EU Cybersecurity Act compliance deadlines approach.
China
AAA gaming studios and industrial software publishers deploy hardware-backed enforcement under stricter SAMR IP protection standards. GB/T cryptographic module standards segment compliance costs for cross-border vendors. Shenzhen electronics manufacturing hubs and Shanghai software development clusters concentrate domestic production and procurement.
Japan
Precision machinery software vendors and medical device manufacturers seek wide-temperature-range dongles for factory automation environments. METI industrial cybersecurity guidelines shape procurement specifications for embedded license enforcement. Nagoya automotive software suppliers and Osaka industrial equipment manufacturers anchor regional demand.
United Kingdom
Financial services software vendors and enterprise security firms drive demand for PKI-based smart card reader solutions. FCA operational resilience requirements intersect with hardware-backed licensing for critical trading systems. London fintech clusters and Cambridge software development hubs concentrate procurement of certified authentication hardware.
Software Protection Dongle Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in software protection hardware. Proprietary ASIC designers and secure element fabricators occupy differentiated positions against cost-optimized USB dongle assemblers. Competitive moves concentrate on interface standard transitions and certification timeline acceleration.
Within the integrated security tier, Wibu-Systems and SafeNet exemplify divergent scale strategies. Wibu-Systems anchors proprietary silicon development for industrial automation licensing. SafeNet occupies a position leveraging Thales-backed supply chain scale across enterprise IT deployments. Keylok represents the cost-optimized manufacturing archetype serving mid-market software publishers without custom cryptographic investment.
| Leading Market Players |
|---|
| Wibu-Systems |
| Keylok |
| SafeNet |
| CodeMeter |
| Reprise Software |
| Thales |
| Microcosm |
| Protector Software |
| Gemalto |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements with Asian secure element foundries lock in both cryptographic processor supply and unit cost visibility for dongle vendors navigating NIST FIPS 140-2 certification timelines. These contractual structures insulate premium hardware security module producers from spot-market semiconductor volatility while compressing margins for vendors without locked-in wafer allocations.
Pricing Analysis
Project-based licensing with hardware token bundles dominates enterprise procurement, though subscription-term structures are gaining traction among United States industrial software buyers. Price differentiation rests on certification tier—FIPS 140-2 validated hardware commands substantial premiums over standard USB dongles—and vertical integration depth, with proprietary ASIC designers capturing margin unavailable to assembly-only vendors. Cost compression in mid-market USB dongles is intensifying because Chinese manufacturers are scaling GB/T-compliant production for domestic gaming publishers. Educational institutions represent the most price-sensitive procurement segment, while federal defense contractors show minimal price elasticity for high-assurance modules.
Supply Chain Analysis
TSMC and Samsung Foundry capacity allocation in Taiwan and South Korea represents the critical chokepoint for secure element fabrication serving the entire dongle market. Raw material dependencies span silicon wafers, tamper-resistant epoxy resins, and USB-C connector assemblies predominantly sourced from Shenzhen manufacturing clusters. Single-source vulnerability concentrates in advanced cryptographic processor nodes where only two foundries maintain certified production lines. Distribution runs through broadline electronics distributors aggregating mid-market demand, with direct sales teams handling customized enterprise security architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interface standard fragmentation and regulatory certification divergence are creating defendable niches across the software protection hardware landscape. The shift from USB-A to USB-C and emerging NFC requirements splits demand into multiple technical competency domains.
For Market Incumbents: Shield proprietary ASIC investments by accelerating quantum-resistant algorithm migration before regulatory mandates crystallize. Secure exclusive foundry capacity reservations for FIPS 140-2 validated secure elements to deny supply access to emerging competitors targeting North American government contracts. Consolidate distributor relationships in German industrial automation corridors where BSI certification creates switching costs.
For New Entrants and Emerging Players: Lead with cloud-hybrid license management integration as the wedge against legacy hardware-only vendors, targeting mid-market SaaS publishers in the United States seeking unified entitlement platforms. The most penetrable segment sits in educational institution network dongle deployments, where price sensitivity and concurrent-user pooling requirements favor agile challengers over established premium brands. Pursue value-added reseller channel partnerships for European medical device software compliance projects under EU Cybersecurity Act deadlines.
For Investors and Strategic Acquirers: Niche certification specialists with embedded firmware expertise present the most compelling acquisition targets for portfolio consolidation plays. Long-term viability hinges on whether hardware tokens retain relevance as TPM-backed machine fingerprinting and WebAssembly licensing mature across the analysis window. Monitor browser-based licensing adoption rates in SMB software segments as the critical inflection signal for discrete dongle demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Proliferation | Proprietary silicon development locks in industrial automation margins against commodity USB dongle assemblers. |
| Quantum-Resistant Firmware Migration | Early algorithm embedding captures premium positioning before NIST post-quantum cryptographic standards finalize. |
| USB-C Form Factor Transition | Reversible connector standardization aligns with German automotive and machine tool manufacturer procurement mandates. |
| EU Cybersecurity Act Certification | Common Criteria validation opens replacement cycle revenue across European critical infrastructure software deployments. |
| Cloud-Native License Integration | Hybrid entitlement platforms address United States enterprise demand for unified SaaS and on-premise authentication. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from hardware security vendors, ETSI cybersecurity standard drafts, and NIST cryptographic module validation lists. Primary interviews engaged hardware engineering directors at industrial automation firms, enterprise IT procurement officers managing software license portfolios, and distributor category managers for electronic security components. Secondary validation drew from FIPS 140-2 validation databases, BSI technical guideline publications, and GB/T standard certification registries. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions across product type and regional segments.
Segmentation dimensions modeled span interface standard, tamper-resistance certification tier, deployment context, and end-use vertical complexity. Volume and value outputs anchor in installed base replacement cycles, cloud-hybrid architecture adoption patterns, and regulatory compliance deadline clustering across the projection horizon. CAGRs derive from license management system upgrade intentions, semiconductor capacity expansion timelines, and cryptographic standard evolution trajectories. Industry-specific forecast inputs include BSI mandate implementation schedules and EU Cybersecurity Act enforcement phase-ins.
The analysis sits within stated boundaries; outcomes outside stable regulatory certification timelines and continued hardware-backed enforcement preference would require recalibration. Forecasts assume persistent demand for physical license anchors in critical infrastructure and industrial control environments. Practitioners should keep alternative scenarios live as browser-based WebAssembly licensing and TPM-backed authentication evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market
Security Software
Business Email Compromise (BEC) Market
Security Software
User Provisioning Software Market
Security Software
Europe Enterprise Firewall Market
Security Software
Geofencing Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Network Camera Market
Security Software
Europe User Provisioning Market
Security Software
Smart Video Doorbell Market
Security Software
Global Anti-Spam Software Market
Security Software
Application Control Software Market
Security Software
Door Phone Market