
 Global Anti-Spam Software Market | 2026-2036
Global Anti-Spam Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Spam Software Market Foresight
Cloud-native filtering architectures is hardening cost advantages over on-premises appliances by eliminating per-server licensing overhead. Proofpoint Inc. leverages behavioral analysis patents to sustain premium positioning in financial services. Cisco Systems Inc. anchors enterprise share through unified threat management bundling with its networking hardware. Trend Micro Inc. competes aggressively in Asia-Pacific via localized threat intelligence feeds and regional data residency.
Anti-spam software comprises algorithmic systems that inspect email headers, payload content, sender reputation scores, and network behavior to block unsolicited or malicious messages before delivery to user inboxes. These platforms typically process traffic at line speeds exceeding 10 Gbps while maintaining false-positive rates below 0.1 percent, serving the commercial purpose of protecting organizational productivity and preventing credential theft or malware propagation. Cloud-based deployment now captures the dominant margin pool as enterprises abandon capital-intensive appliance refresh cycles, while behavioral analysis solutions represent the fastest-growing solution type as signature-based detection fails against polymorphic threats. Email filtering remains the mature revenue baseline, though URL filtering grows fastest as link-based phishing displaces attachment-based attacks.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape product requirements by mandating explainable filtering decisions and audit-ready logging across European operations. The US Federal Trade Commission and SEC enforce breach disclosure rules that heighten enterprise liability for email-derived data loss, directly expanding procurement of reputation management modules. Stakeholders must weigh whether to consolidate around integrated secure email gateways or maintain best-of-breed architectures as AI-generated phishing erodes traditional detection boundaries.
Market Dynamics
Machine-learning filtering architectures are compressing competitive margins for legacy signature-based vendors as polymorphic phishing campaigns overwhelm rule-dependent detection systems. Cloud-native delivery models now capture procurement preference across mid-market and enterprise segments, eliminating capital-intensive appliance refresh cycles.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face audit obligations for algorithmic email filtering decisions, accelerating replacement of opaque black-box systems with explainable ML platforms.
- Behavioral analysis adoption:Financial services firms deploy sender-reputation and network-behavior inspection to counter business email compromise campaigns targeting wire-transfer authorization workflows.
- German manufacturing concentration:Mittelstand automotive suppliers and industrial equipment manufacturers face intensified spear-phishing attacks, expanding procurement of integrated secure email gateways.
Market Restraints
- Cloud infrastructure cost volatility:Multi-tenant SaaS architectures expose vendors to compute and storage pricing fluctuations from hyperscaler providers.
- False-positive sensitivity:Financial and healthcare segments demand sub-0.1% false-positive rates, constraining aggressive heuristic tuning that would improve malware catch rates.
- Data residency fragmentation:Divergent national data-localization requirements in Russia, China, and emerging markets force redundant infrastructure deployment.
Strategic Opportunities
- India enterprise digitization:RBI-mandated cybersecurity frameworks for banks and SEBI disclosure requirements for securities firms drive first-time secure email gateway adoption.
- API-native security convergence:Integration of anti-spam filtering with zero-trust network access and cloud access security broker architectures creates unified procurement opportunities.
- ISO 27001 certification tailwinds:Supply-chain security audits increasingly require documented email threat protection, expanding addressable market into supplier tiers.
Industry Challenges
- Adversarial ML expertise scarcity:Vendors struggle to recruit data scientists capable of training robust models against adversarial examples and model-extraction attacks.
- Legacy email server integration:On-premises Microsoft Exchange and IBM Domino environments require complex protocol adaptation for cloud-native filtering deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Spam Software Market |
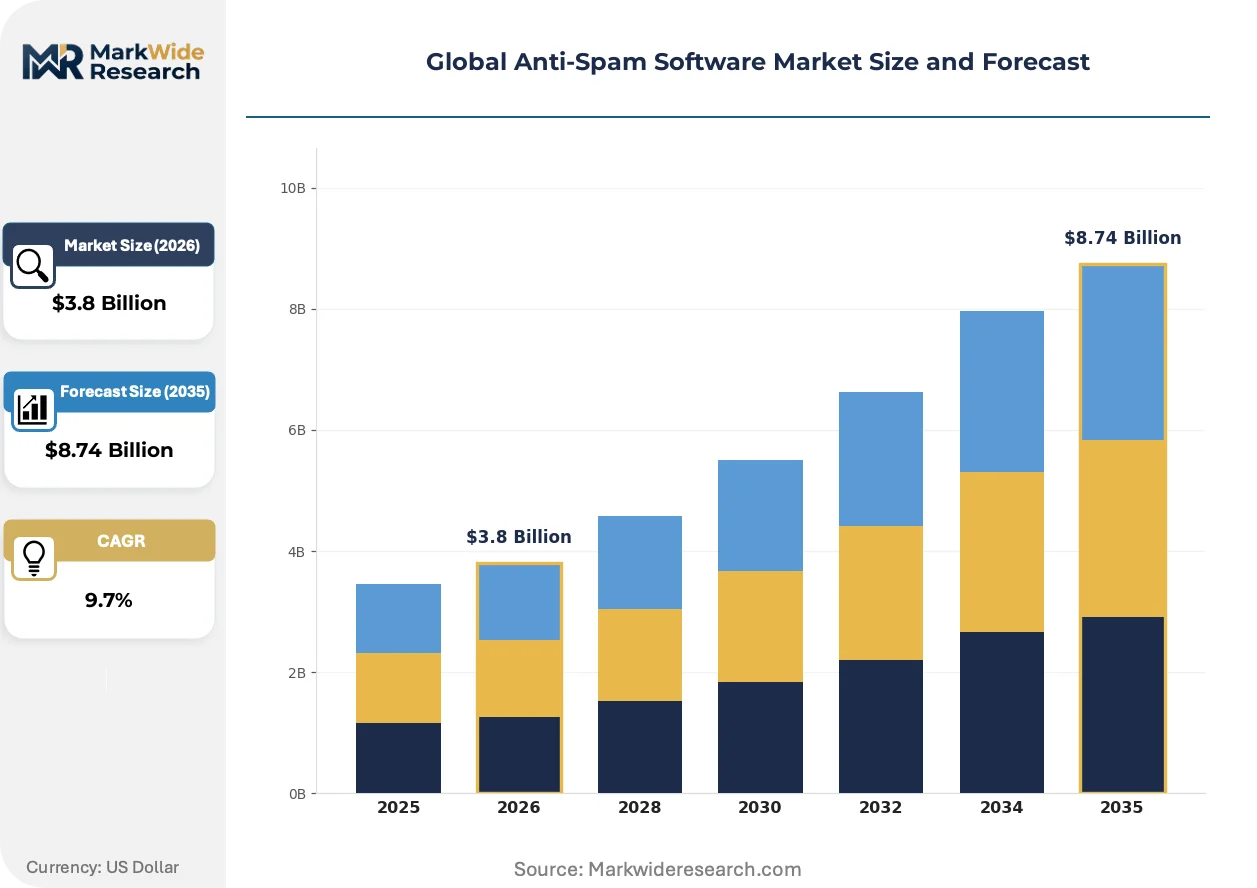
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtual Appliance Solution Type: Email Filtering, Content Analysis, URL Filtering, Behavioral Analysis, Reputation Management Application: Corporate Communications, Government Communications, Educational Institutions, Financial Services, Telecommunication Networks End User: Enterprises, Managed Service Providers, Internet Service Providers, Data Centers |
| Companies Covered | Symantec Corporation, Trend Micro Inc., Cisco Systems Inc., Proofpoint Inc., Mimecast Limited, Barracuda Networks Inc., Fortinet Inc., McAfee LLC, Sophos Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Spam Software Market Shifts & Advancements
Generative AI tools now enable attackers to craft linguistically polished phishing content at scale, forcing defensive vendors to accelerate innovation in behavioral and contextual detection methods.
Natural language processing models with transformer architectures are electrifying email content inspection by analyzing semantic intent rather than keyword patterns. Large financial institutions in North America and Europe deploy these systems to detect subtle social-engineering cues in executive impersonation attempts. The technology is electrifying competitive differentiation as vendors race to demonstrate superior detection against AI-generated synthetic content.
GDPR Article 22 and the EU AI Act's automated decision-making provisions now mandate human-reviewable filtering logic for high-risk processing contexts. European enterprises must maintain audit trails explaining why specific messages were quarantined or blocked. German and French data protection authorities actively enforce these requirements, pushing vendors to develop interpretable model architectures.
Consumption-based licensing models are displacing per-user or per-mailbox pricing in enterprise procurement. Mid-market buyers prefer usage-aligned billing that scales with actual email volume rather than fixed annual commitments. This shift is most visible in United States technology and professional services verticals where CFOs prioritize operational expenditure classification.
Global Anti-Spam Software Market Segmentation
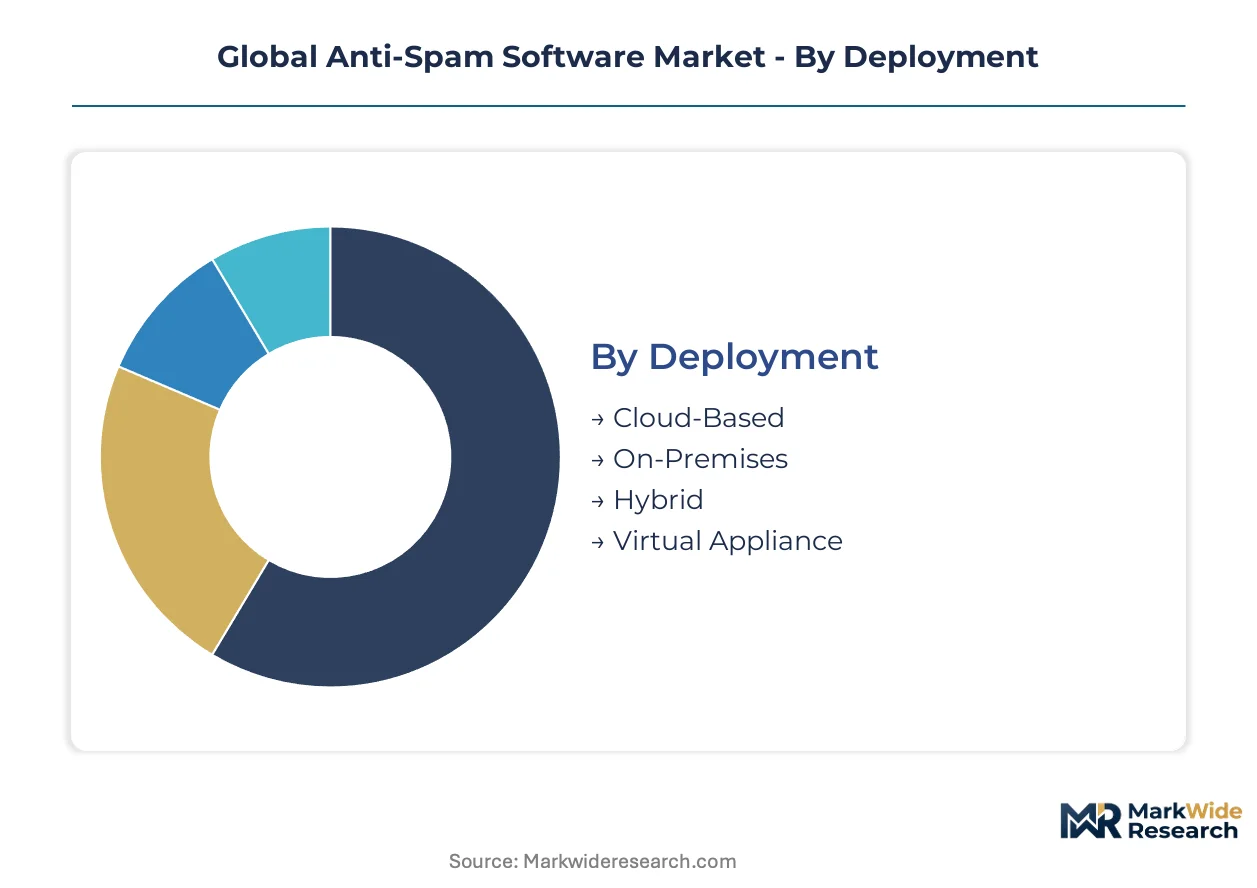
Segmentation in anti-spam software reveals how compliance burdens, infrastructure maturity, and threat actor targeting patterns reshape procurement priorities across customer archetypes. Understanding these divisions exposes where vendors must align product architecture with specific regulatory and operational requirements.
Deployment:
Cloud-based platforms carry lighter ISO 27001 certification overhead than on-premises equivalents, while hybrid deployments demand dual compliance documentation across both infrastructure modes.
- Cloud-Based:Multi-tenant SaaS architectures eliminate per-server licensing and hardware refresh cycles. Financial services firms in Germany and the United States concentrate procurement here as GDPR and SEC disclosure rules elevate audit requirements for rapid scaling.
- On-Premises:Dedicated appliance or software installations within customer data centers. Russian and Chinese data localization mandates force continued investment despite global cloud migration trends.
- Hybrid:Split processing across cloud and local infrastructure. Japanese manufacturing conglomerates favor this model to isolate intellectual property while outsourcing commodity traffic filtering.
- Virtual Appliance:Software-defined filtering deployed on customer-managed hypervisors. Indian banks under RBI cybersecurity frameworks select this for controlled upgrade cadences.
Cloud-based sits at the top of the volume ranking, with hybrid climbing the fastest as sovereignty requirements fragment deployment strategies.
Solution Type:
Cost tiering separates premium behavioral analysis modules from baseline email filtering, with price spreads reflecting ML model sophistication and threat intelligence feed quality.
- Behavioral Analysis:Sender-reputation scoring and network-behavior inspection detect polymorphic phishing. Wire-transfer authorization workflows at North American and European financial institutions drive concentrated demand.
- Email Filtering:Header inspection, payload scanning, and signature matching at line speeds exceeding 10 Gbps. Mature revenue baseline serving productivity protection across all verticals.
- Content Analysis:Natural language processing for semantic intent detection. Transformer architectures now inspect executive impersonation attempts for social-engineering cues.
- URL Filtering:Real-time link reputation checking and sandbox detonation. Fastest-expanding category as phishing displaces attachment-based attacks.
- Reputation Management:Domain and IP reputation scoring with takedown orchestration. Procurement expands under FTC and SEC breach disclosure enforcement.
Email filtering commands the largest installed base, though URL filtering gains share fastest as attack vectors shift.
Application:
Volume concentration clusters where regulatory penalty exposure intersects with high-value fraud targets.
- Financial Services:Business email compromise protection for treasury operations. EU AI Act audit obligations and SEC disclosure rules accelerate ML platform replacement of rule-based systems.
- Corporate Communications:General enterprise email protection against malware propagation and credential theft. German Mittelstand manufacturers anchor procurement volume.
- Government Communications:Classified and unclassified network protection. National data sovereignty requirements dominate vendor selection criteria.
- Educational Institutions:Student and faculty email filtering with limited IT staffing. Budget constraints favor consolidated secure email gateway bundles.
- Telecommunication Networks:Carrier-grade filtering for subscriber email services. Scale requirements favor appliance-based or virtualized deployments.
Corporate communications leads by deployment count, with financial services expanding most steeply as phishing sophistication escalates.
End User:
Customer type determines whether procurement favors consumption-based licensing or fixed enterprise agreements.
- Enterprises:Direct deployment for employee email protection. Mid-market buyers in United States technology verticals prefer usage-aligned billing over per-mailbox commitments.
- Managed Service Providers:Multi-tenant platform resale to downstream clients. API-native integration with zero-trust architectures creates differentiation.
- Internet Service Providers:Subscriber-facing email services at carrier scale. Regional data residency requirements in Asia-Pacific shape infrastructure decisions.
- Data Centers:Colocation and hosting provider filtering services. Colocation facilities in Frankfurt and Singapore concentrate demand.
Enterprises represent the dominant addressable base, with managed service providers capturing the steepest expansion trajectory as security outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and industrial manufacturing clusters anchor procurement concentration for behavioral analysis solutions, with Mittelstand suppliers facing intensified business email compromise campaigns. Regulatory enforcement across multiple jurisdictions is fragmenting deployment architectures as data sovereignty requirements harden.
United States
Financial services firms in New York and Chicago deploy sender-reputation scoring to protect wire-transfer authorization workflows from polymorphic phishing. SEC disclosure rules and FTC breach enforcement expand procurement of reputation management modules. Silicon Valley technology companies favor consumption-based licensing models that align with operational expenditure priorities.
Germany
Baden-Württemberg automotive suppliers and Bavarian industrial equipment manufacturers drive concentrated demand for integrated secure email gateways. EU AI Act audit obligations and GDPR Article 22 provisions mandate explainable filtering decisions with human-reviewable logic. Frankfurt data centers anchor hybrid deployment preferences among Mittelstand exporters managing cross-border intellectual property.
United Kingdom
London financial institutions accelerate replacement of legacy rule-based filters with machine-learning platforms under Financial Conduct Authority operational resilience requirements. ISO 27001 certification tailwinds expand addressable market into supplier tiers as supply-chain security audits intensify. The Southeast technology corridor favors API-native security convergence with zero-trust architectures.
India
Mumbai banking headquarters and Bangalore technology parks drive first-time secure email gateway adoption under RBI-mandated cybersecurity frameworks. SEBI disclosure requirements for securities firms elevate email threat protection to board-level procurement priority. Virtual appliance deployments dominate as controlled upgrade cadences satisfy regulatory compliance officers.
Japan
Tokyo manufacturing conglomerates favor hybrid filtering models to isolate intellectual property while outsourcing commodity traffic processing. METI cybersecurity guidelines emphasize documented email threat protection for critical infrastructure operators. Osaka-based financial institutions deploy transformer-architecture content analysis to detect executive impersonation attempts.
Global Anti-Spam Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate anti-spam filtering with broader security architectures. The market structures around three tiers: hyperscale platform providers with unified threat management portfolios, specialized secure email gateway vendors with behavioral analysis depth, and regional players leveraging localized threat intelligence. Two archetypes define competitive positioning: bundling-focused incumbents anchoring enterprise share through networking hardware integration, and cloud-native specialists capturing mid-market preference via consumption-based licensing. Geographic expansion and technology licensing represent the dominant competitive moves as vendors address data residency fragmentation.
Within the platform-provider tier, Cisco Systems Inc. and Fortinet Inc. exemplify bundling strategies that anchor enterprise procurement through infrastructure integration. Proofpoint Inc. occupies a specialized position representing premium behavioral analysis capabilities targeting financial services compliance requirements. Trend Micro Inc. anchors Asia-Pacific regional presence through localized threat intelligence feed development. These three companies collectively illustrate how competitive positioning stratifies across integration depth, compliance specialization, and geographic threat intelligence proximity.
| Leading Market Players |
|---|
| Symantec Corporation |
| Trend Micro Inc. |
| Cisco Systems Inc. |
| Proofpoint Inc. |
| Mimecast Limited |
| Barracuda Networks Inc. |
| Fortinet Inc. |
| McAfee LLC |
| Sophos Group plc |
| Others |
Supply & Pricing Matrix
Hyperscaler compute pricing indices cascade through SaaS delivery models into three-tier subscription structures, compressing margins for multi-tenant platforms while consumption-based billing absorbs volatility for mid-market buyers. This cost pass-through dynamic stratifies vendor positioning between premium behavioral analysis modules and baseline email filtering tiers.
Pricing Analysis
Input-cost pass-through from AWS, Azure, and Google Cloud infrastructure fees shapes SaaS-tiered subscription pricing across deployment tiers. Price differentiation separates premium behavioral analysis with EU AI Act-compliant audit trails from standard email filtering and economy gateway bundles lacking NLP inspection. Pricing pressure stems from hyperscaler storage rate hikes forcing mid-market vendors toward usage-aligned billing. Financial services buyers exhibit lowest price sensitivity due to SEC disclosure liability, while educational institutions face acute budget constraints favoring consolidated bundles.
Supply Chain Analysis
Dual-sourcing requirements from German automotive suppliers and US financial institutions mandate redundant threat intelligence feed qualification across independent providers. Geographic supply concentration centers on Ireland and Singapore for EU and Asia-Pacific data residency, with India emerging for virtual appliance development. Raw material dependencies encompass GPU clusters for transformer model training, sandbox infrastructure for URL detonation, and proprietary sender-reputation databases. Single-source vulnerability concentrates in hyperscaler compute contracts. Distribution runs through managed service providers and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in anti-spam software rests on consumption-based billing adoption and premium-tier behavioral analysis penetration, with cloud infrastructure cost absorption shifting downstream to volume-scaled buyers.
For Market Incumbents: Extend platform integration depth through API-native convergence with zero-trust architectures and cloud access security brokers. Fortify data residency infrastructure in Frankfurt and Singapore to preempt regulatory fragmentation. Consolidate around behavioral analysis patents as generative AI phishing erodes signature-based detection value. For New Entrants and Emerging Players: Cloud-native channel partnerships with regional managed service providers offer the lowest-friction route to scaled deployment. Target Indian banking verticals under RBI cybersecurity mandates with virtual appliance offerings. White-space exists in ISO 27001-certified supplier-tier email protection for German Mittelstand manufacturing ecosystems. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized behavioral analysis vendors holding financial services compliance depth and explainable ML architectures. Long-term viability favors platforms demonstrating adversarial ML robustness against model-extraction attacks. Watch for EU AI Act enforcement velocity as inflection signal for replacement-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native convergence with zero-trust architectures captures unified procurement budgets at US financial institutions. |
| Geographic Expansion | Frankfurt and Singapore data center buildouts satisfy GDPR and APAC data sovereignty fragmentation. |
| Acquisition of Specialist Firm | Behavioral analysis depth from niche vendors anchors premium positioning against Cisco bundling strategies. |
| Product Launch | Transformer-architecture content analysis detects AI-generated executive impersonation at Osaka financial institutions. |
| Strategic Partnership | Hyperscaler co-selling agreements with AWS and Azure accelerate mid-market consumption-based adoption. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory databases. Bottom-up deployment model sizing and top-down vendor revenue triangulation anchored volume estimates.
Comparable-period anchoring to historical SaaS adoption curves and appliance refresh cycles structured the projection horizon across deployment mode, organization size, vertical compliance burden, integration complexity, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with aggregate vendor guidance. Forecast inputs encompassed phishing volume telemetry and ML model training cost trajectories.
Hyperscaler pricing volatility, adversarial ML breakthrough timelines, and EU AI Act enforcement intensity are the dominant revision risks. Deviation in hyperscaler storage rate trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Digital Risk Protection Software Market
Security Software
Network Camera Market
Security Software
Global Digital Identity Solutions Market
Security Software
AI in Security Market
Security Software
Online Background Check Market
Security Software
Security Information and Event Management Software Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Content Protection and Watermarking Market
Security Software
North America Secure Access Service Edge Market
Security Software
Personal Data Recovery Software Market
Security Software
Cloud Encryption Software Market
Security Software
Endpoint Detection and Response Market
Security Software
ATM Security Market
Security Software
Global Enterprise Key Management Market