
 Geofencing Market | 2026-2036
Geofencing Market Size, Share, and Industry Trends Forecast 2026-2036
Geofencing Market Analysis
Location-data reseller channels is fragmenting as enterprise buyers demand direct API access and cleaner consent pipelines. Google LLC dominates cloud-based geofencing infrastructure through its Maps and advertising ecosystems. Esri specializes in geographic information system overlays that anchor industrial asset-tracking deployments. Foursquare Labs Inc. competes on proprietary venue-recognition databases that differentiate its retail analytics offerings.
Geofencing denotes the creation of virtual geographic boundaries that trigger software actions when a mobile device enters, exits, or dwells within a defined perimeter, typically relying on GPS coordinates within 5-20 meter accuracy or Bluetooth beacon proximity under 10 meters for indoor refinement. Its primary commercial purpose spans targeted marketing delivery, workforce clock-in automation, and fleet route verification. Bluetooth-based proximity detection captures margin pools in retail loyalty programs where indoor positioning precision commands premium pricing. GPS-enabled fleet tracking sustains the largest revenue base across logistics and transportation applications. Cloud deployment models lead adoption curves among mid-market advertisers seeking rapid campaign activation without infrastructure capital.
The Federal Trade Commission enforces location-privacy disclosures under Section 5 of the FTC Act, compelling vendors to document consent mechanisms or face enforcement actions that reshape product design. Europe's GDPR and the EU AI Act impose data-minimization and automated-decisioning constraints that limit cross-border location profiling and raise compliance costs for multinational deployments. Stakeholders must monitor evolving state-level biometric and geolocation statutes in the United States while calibrating deployment architectures for divergent consent standards across jurisdictions.
Market Dynamics
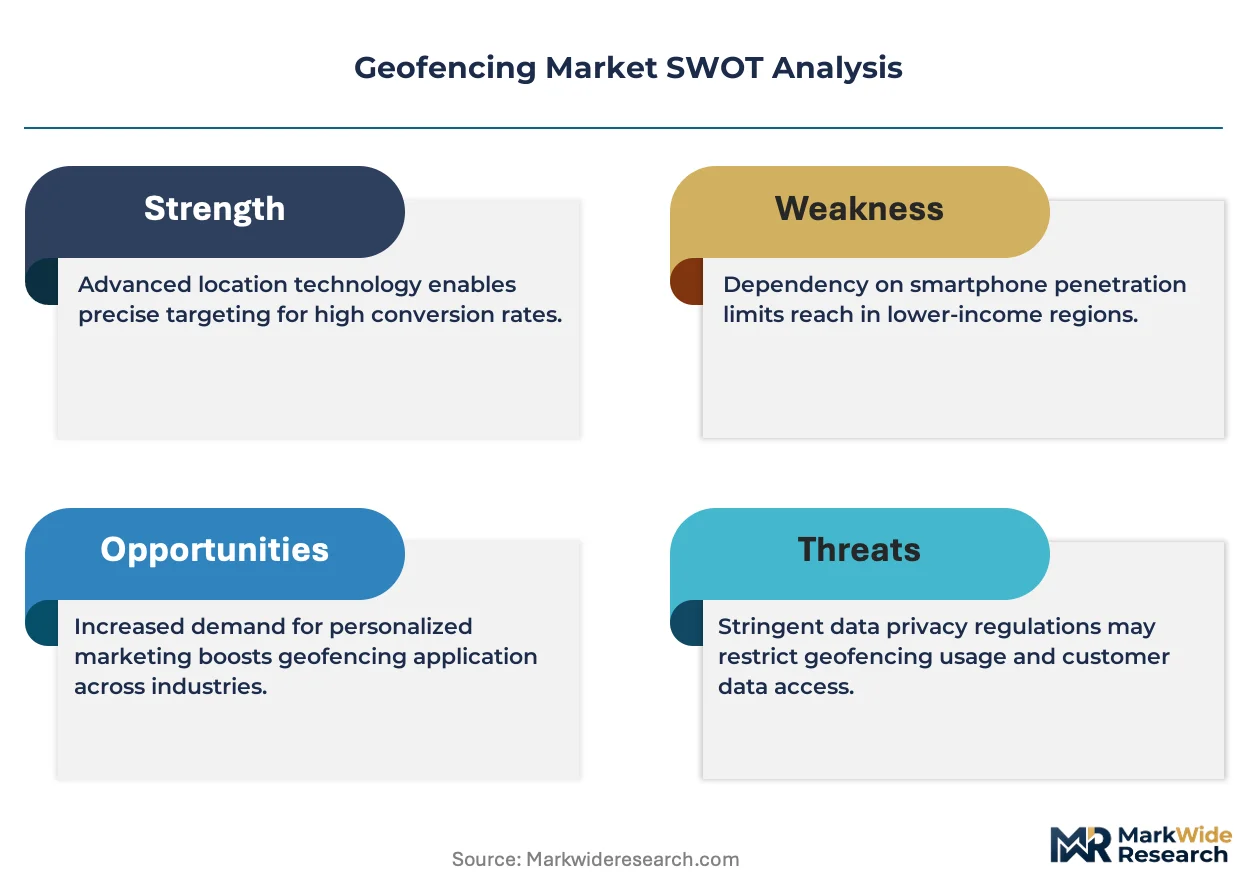
Location-privacy enforcement is compressing vendor business models as the FTC, GDPR, and emerging state biometric statutes force architectural redesign of consent pipelines and data-retention policies.
Growth Catalysts
- Logistics fleet automation:Transportation operators deploy GPS-triggered route verification and driver-behavior monitoring to reduce fuel waste and insurance premiums. Perimeter-based workflows cut administrative overhead in last-mile delivery networks.
- GDPR Article 6 lawful-basis frameworks:European regulators clarified legitimate-interest pathways for location analytics, reducing legal uncertainty for retail loyalty programs that rely on proximity detection.
- Bluetooth beacon indoor positioning:Retail chains install sub-10-meter accuracy infrastructure to capture margin pools in high-frequency loyalty engagement where GPS signals fail.
Market Restraints
- Input cost volatility in semiconductor components:GPS chipsets and Bluetooth modules face pricing pressure from foundry capacity constraints in Taiwan and South Korea.
- Supply concentration in cloud infrastructure:Three hyperscalers control the majority of geofencing API hosting, creating single-point-of-failure risk for enterprise deployments.
- Technical limitation in urban canyon accuracy:Dense metropolitan environments degrade GPS precision below commercial thresholds for fleet verification applications.
Strategic Opportunities
- Underpenetrated quick-service restaurant automation:Drive-thru chains in India and Southeast Asia lack perimeter-triggered kitchen workflows that optimize labor scheduling during demand spikes.
- EU AI Act automated-decisioning carve-outs:The regulation creates compliance-safe harbors for geofencing systems that exclude profiling algorithms, favoring pure location-triggered automation vendors.
- Convergence of 5G network slicing and edge computing:Telecommunications operators partner with software vendors to deliver sub-50-millisecond latency for industrial safety-zone applications.
Industry Challenges
- Scarcity of geospatial data scientists:Enterprises competing for talent capable of integrating GIS overlays with real-time streaming pipelines face 18-month hiring cycles.
- Legacy fleet management system integration:Transportation operators struggle to bridge 1990s-era telematics hardware with modern API-first geofencing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geofencing Market |
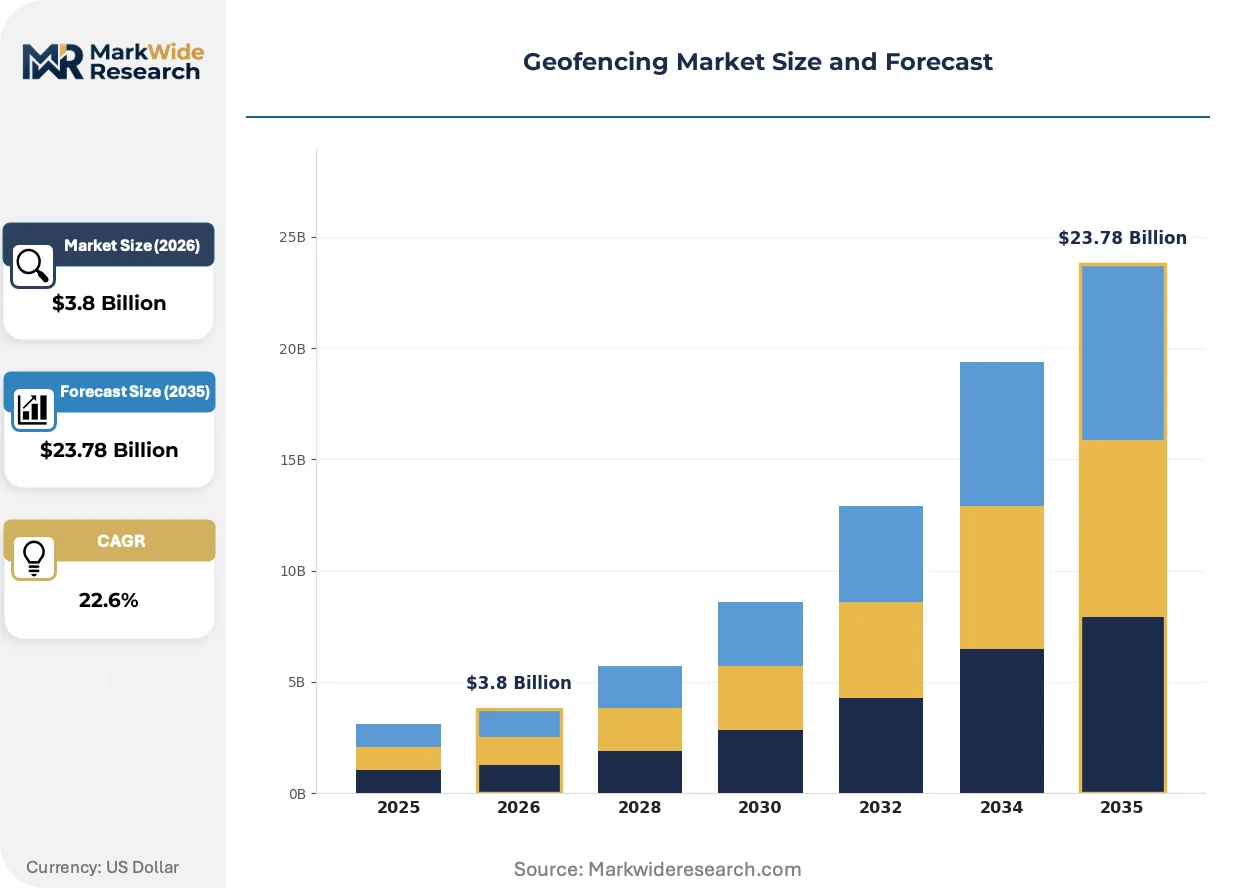
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail, Marketing, Logistics, Transportation Technology: Bluetooth, GPS, RFID, Wi-Fi End User: Automotive, Real Estate, Advertising, Entertainment Deployment: Cloud, On-Premises, Hybrid, Mobile |
| Companies Covered | Bluedot Innovation, Google LLC, IBM Corporation, Radar Labs Inc., Apple Inc., Inffilion, Esri, Foursquare Labs Inc., GroundTruth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geofencing Market Emerging Trajectories
Three forces are compressing vendor differentiation windows: edge-AI processing, privacy-preserving computation, and direct API procurement models that bypass traditional reseller channels.
Ultra-wideband (UWB) chipsets are collapsing the cost barrier for centimeter-accurate indoor positioning. Automotive manufacturers embed UWB anchors in vehicle access systems, repurposing the infrastructure for retail and logistics proximity applications. The technology is collapsing the premium pricing tier that Bluetooth beacons previously commanded in high-precision use cases.
The EU AI Act's risk-classification framework imposes documentation burdens on geofencing systems that incorporate predictive analytics. Vendors stripping machine-learning components from their stacks gain faster compliance certification. Industrial asset-tracking deployments in Germany and France are accelerating procurement of rule-based perimeter systems to avoid the Act's high-risk system obligations.
Enterprise buyers now demand direct API access with granular consent-audit trails, bypassing location-data aggregators. Quick-service restaurant chains negotiate bilateral contracts with infrastructure providers. This pattern is most visible in the United States, where large fleet operators and retail brands have sufficient technical staff to manage integration complexity in-house.
Geofencing Market Segmentation
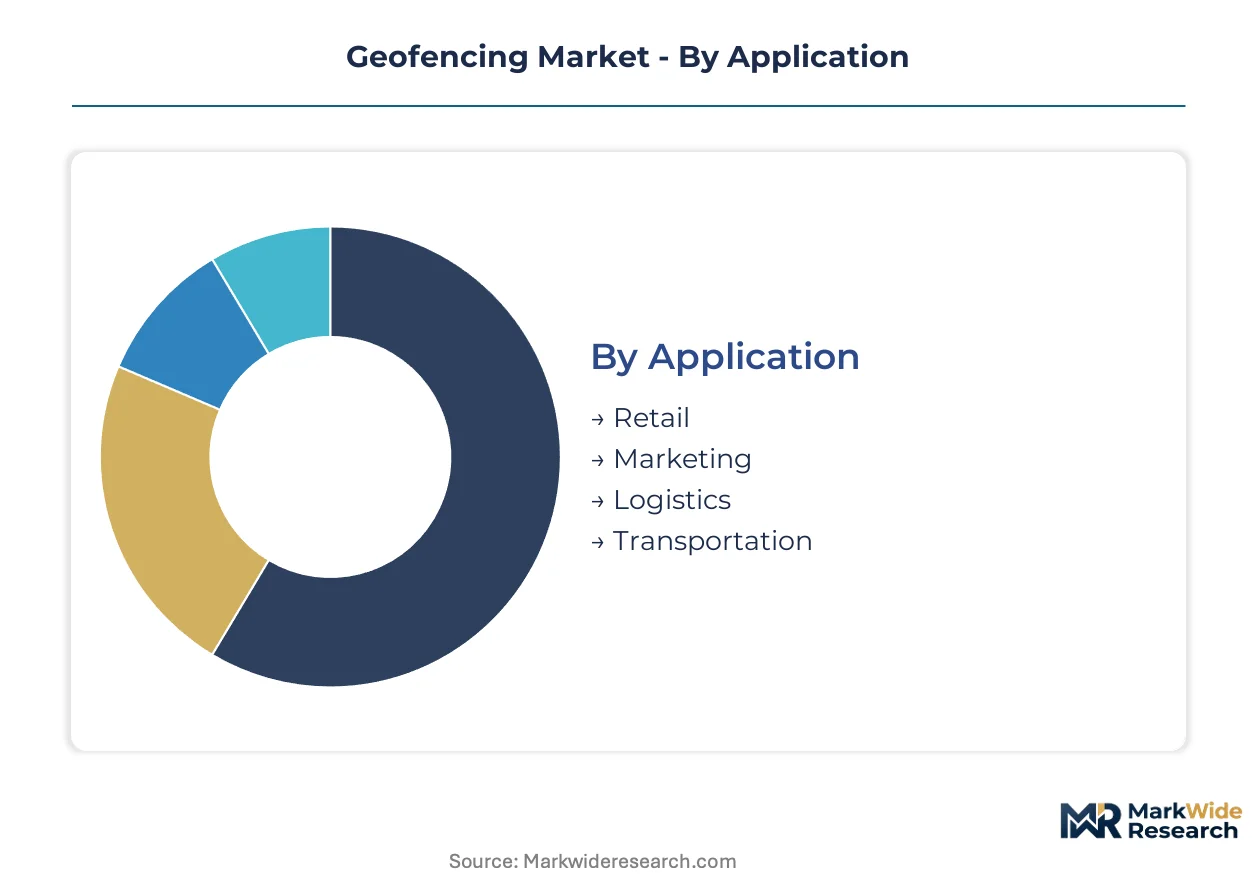
Geofencing deployments vary sharply by precision requirements, infrastructure investment, and regulatory exposure. Segmentation reveals how GPS fleet verification commands fundamentally different architectures than Bluetooth-powered retail loyalty programs.
Application:
Mature logistics deployments anchor revenue while emerging marketing use cases reshape growth trajectories.
- Retail:Bluetooth beacon networks enable sub-10-meter indoor positioning for loyalty program automation. Quick-service restaurant chains in the United States deploy perimeter-triggered kitchen workflows to optimize labor scheduling during demand spikes.
- Marketing:Proximity-triggered promotional delivery relies on GPS coordinates with 5-20 meter accuracy for outdoor campaigns. European retailers navigate GDPR Article 6 lawful-basis requirements to maintain consent pipelines for location analytics.
- Logistics:GPS-enabled fleet tracking sustains the largest revenue base across transportation applications. Perimeter-based route verification cuts fuel waste and insurance premiums for last-mile delivery networks.
- Transportation:Driver-behavior monitoring through geofenced zones reduces administrative overhead in commercial vehicle operations. Urban canyon signal degradation in dense metropolitan environments constrains accuracy thresholds.
Logistics retains volume leadership; marketing holds the steepest expansion curve.
Technology:
Cost tiers separate satellite-dependent outdoor systems from infrastructure-heavy indoor precision layers.
- Bluetooth:Low-energy beacon deployments capture margin pools in retail loyalty programs where indoor positioning precision commands premium pricing. Ultra-wideband chipsets are collapsing the cost barrier for centimeter-accurate alternatives.
- GPS:Satellite-based coordinates within 5-20 meter accuracy sustain fleet verification and outdoor marketing applications. Foundry capacity constraints in Taiwan and South Korea create input cost volatility for chipset procurement.
- RFID:Passive tag systems anchor industrial asset-tracking with limited real-time positioning capability. Manufacturing facilities integrate RFID gates for zone-based presence verification rather than continuous tracking.
- Wi-Fi:Fingerprinting techniques leverage existing infrastructure for indoor positioning without dedicated beacon hardware. Accuracy limitations and interference susceptibility restrict deployment to cost-sensitive environments.
GPS sustains the broadest installed base; Bluetooth beacons are climbing the fastest as UWB displacement accelerates.
End User:
Customer type determines whether deployments prioritize consumer consent pipelines or operational efficiency metrics.
- Automotive:Vehicle access systems embed ultra-wideband anchors that infrastructure providers repurpose for retail and logistics proximity applications. Manufacturers demand sub-50-millisecond latency for safety-zone applications.
- Real Estate:Property managers deploy perimeter systems for tenant experience automation and facility security. Cloud deployment models dominate among mid-market operators seeking rapid activation without infrastructure capital.
- Advertising:Location-data aggregators face fragmentation as enterprise buyers demand direct API access with granular consent-audit trails. The FTC enforces location-privacy disclosures under Section 5 of the FTC Act.
- Entertainment:Venue operators leverage proximity detection for crowd flow management and personalized content delivery. GDPR and the EU AI Act impose data-minimization constraints on cross-border location profiling.
Advertising commands the highest data-pipeline investment; automotive is gaining share fastest through UWB integration.
Deployment:
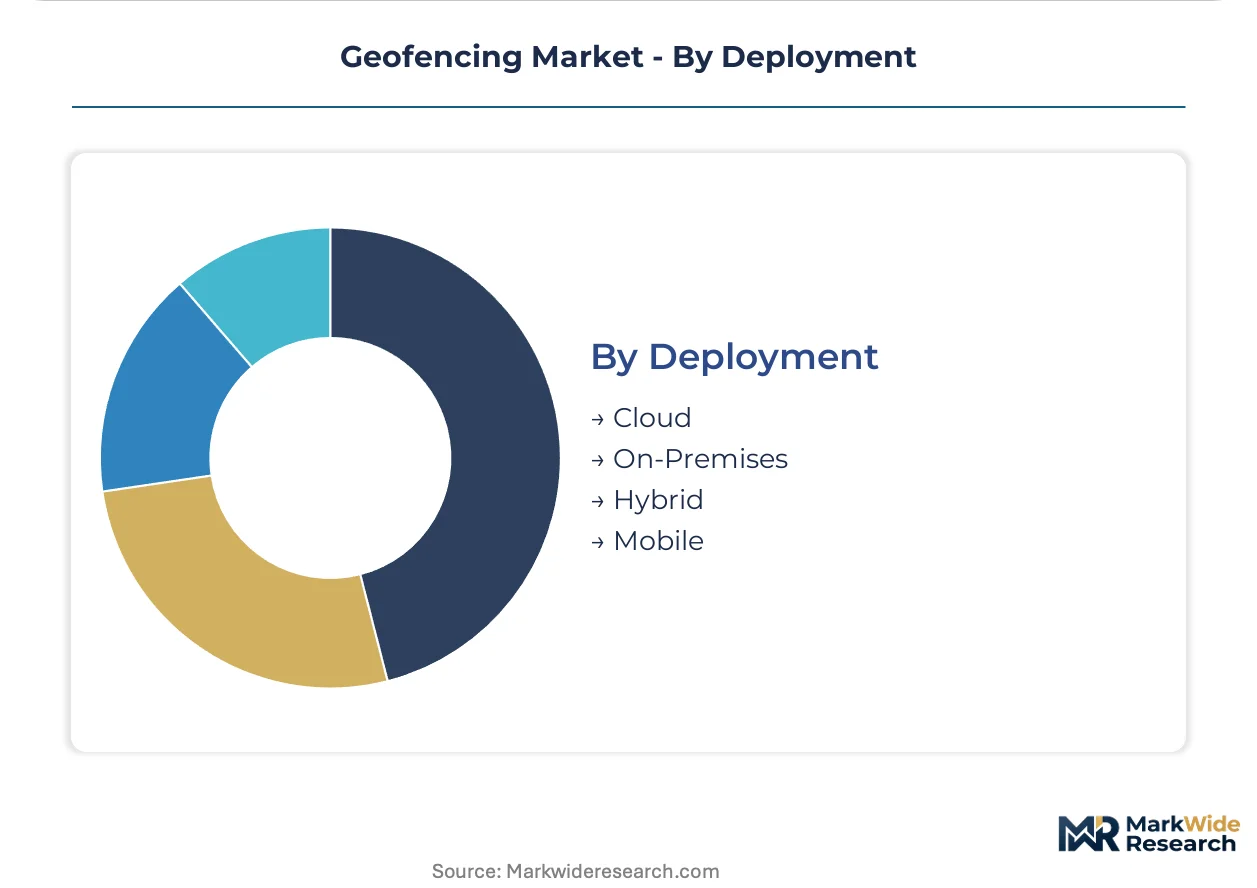
Volume concentration sits with cloud models while margin accrues to hybrid architectures balancing control and scalability.
- Cloud:API-first platforms enable rapid campaign activation for mid-market advertisers. Three hyperscalers control the majority of geofencing API hosting, creating single-point-of-failure risk.
- On-Premises:Enterprise operators with legacy fleet management systems from the 1990s maintain on-site infrastructure for regulatory data sovereignty. Integration complexity with modern platforms constrains upgrade paths.
- Hybrid:Rule-based perimeter systems gain procurement preference in Germany and France to avoid the EU AI Act's high-risk system obligations for predictive analytics. Edge-AI processing reduces latency for industrial safety applications.
- Mobile:SDK-embedded solutions enable rapid deployment for application developers without dedicated infrastructure. Battery consumption and background location permission restrictions limit sustained engagement.
Cloud deployment retains volume leadership; hybrid architectures hold the steepest expansion curve as regulatory carve-outs reshape procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC enforces location-privacy disclosures across the United States, compelling vendors to redesign consent pipelines while European regulators under GDPR constrain cross-border data flows. Demand concentrates in logistics corridors and quick-service restaurant chains where perimeter-triggered workflows reduce operational overhead.
United States
Logistics fleets and quick-service restaurants deploy GPS-triggered route verification and kitchen automation at scale. The FTC Act Section 5 mandates documented consent mechanisms for location-data collection. Dallas-Fort Worth anchors transportation technology clusters where fleet operators integrate geofenced driver-behavior monitoring.
Germany
Industrial asset-tracking deployments accelerate procurement of rule-based perimeter systems to avoid EU AI Act high-risk obligations. The KBA and BSI coordinate standards for automotive safety-zone applications. Stuttgart's automotive manufacturers embed ultra-wideband anchors repurposed for logistics proximity detection.
United Kingdom
Mid-market advertisers adopt cloud deployment models for rapid campaign activation without infrastructure capital. The Information Commissioner's Office enforces GDPR Article 6 lawful-basis requirements for retail loyalty programs. London's advertising technology corridor concentrates demand for direct API access with granular consent-audit trails.
India
Quick-service restaurant chains in metropolitan corridors lack perimeter-triggered kitchen workflows that optimize labor scheduling. TRAI guidelines shape data-localization requirements for location-analytics vendors. Bangalore's technology parks host SDK-embedded solution providers serving application developers.
Japan
Automotive manufacturers demand sub-50-millisecond latency for safety-zone applications through 5G network slicing partnerships. METI promotes edge-computing infrastructure for industrial geofencing. Nagoya's manufacturing belt integrates Bluetooth beacon networks for facility security and tenant experience automation.
Geofencing Market Vendor Landscape
Cloud infrastructure providers and specialized geographic information system vendors split the market between scale-driven API platforms and precision-focused industrial deployments. Three hyperscalers control the majority of geofencing API hosting, creating concentrated supply-side architecture. Strategic archetypes span advertising-technology aggregators, logistics-focused fleet verification specialists, and industrial GIS overlay providers. Competitive moves center on direct API procurement negotiations with enterprise buyers and edge-AI processing partnerships with telecommunications operators.
Within the cloud infrastructure tier, Google LLC and Apple Inc. occupy positions as scale-driven platform anchors whose mapping and device ecosystems shape baseline technical standards for the industry. IBM Corporation exemplifies the enterprise-systems archetype, bridging legacy fleet management integrations with modern API-first architectures. Esri represents the specialized geographic information systems tier, anchoring industrial asset-tracking deployments through proprietary overlay capabilities that differentiate high-precision use cases from commodity location services.
| Leading Market Players |
|---|
| Bluedot Innovation |
| Google LLC |
| IBM Corporation |
| Radar Labs Inc. |
| Apple Inc. |
| Inffilion |
| Esri |
| Foursquare Labs Inc. |
| GroundTruth |
| Others |
Supply Flow & Price Mechanics
Taiwan's foundry capacity constraints in GPS chipset and Bluetooth module production transmit directly into margin compression for downstream geofencing platform vendors. Semiconductor input costs now dictate tier boundaries in cloud API pricing, with hyperscaler concentration amplifying pass-through volatility.
Pricing Analysis
North American enterprise buyers face 15-25% premiums over Asia-Pacific contract rates for identical API throughput volumes. Three-tier pricing structure across premium, standard, and economy levels segments by data-retention duration and consent-audit granularity. Cost compression in standard-tier SaaS subscriptions is intensifying because hyperscaler infrastructure fees are rising faster than platform absorption capacity. Quick-service restaurant chains exhibit highest price sensitivity due to thin operational margins, while automotive manufacturers prioritize latency guarantees over unit cost.
Supply Chain Analysis
US export-control restrictions on advanced positioning semiconductors limit flows to Chinese system integrators, fragmenting procurement channels. Manufacturing gravity centers on Taiwan for GPS chipsets, South Korea for Bluetooth modules, and mainland China for beacon assembly. Raw material dependencies include rare-earth elements for magnetometers, silicon wafers for RF components, and lithium for mobile power systems. Single-source vulnerability in Taiwan Semiconductor Manufacturing's advanced-node capacity creates chokepoint exposure. Distribution runs through direct API contracts with enterprise buyers, bypassing traditional location-data aggregator intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geofencing incumbents confront substitution pressure from privacy-preserving federated learning systems that eliminate centralized location repositories. This threat demands architectural repositioning before regulatory momentum accelerates displacement.
For Market Incumbents: Pre-empt compliance-driven churn by stripping machine-learning components from core stacks to qualify for EU AI Act carve-outs. Accelerate backward integration into UWB anchor manufacturing through partnerships with Stuttgart and Nagoya automotive suppliers, securing captive supply chains before semiconductor export controls tighten further.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated quick-service restaurant automation segment, where perimeter-triggered kitchen workflows remain absent in metropolitan corridors. Lead with SDK-embedded mobile solutions that circumvent infrastructure capital requirements, leveraging Bangalore's developer ecosystem for rapid deployment scaling.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence in consent standards creates acquisition opportunities for rule-based system vendors with EU certification. Target mid-cap specialists holding KBA and BSI automotive safety-zone approvals. Monitor TRAI data-localization enforcement intensity as the inflection signal for India market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Processing Partnership | Telecommunications operators in Japan deliver sub-50-millisecond latency for industrial safety zones through METI-backed infrastructure. |
| Direct API Procurement Negotiation | US quick-service restaurant chains bypass location-data aggregators to secure granular consent-audit trails under FTC Section 5. |
| UWB Infrastructure Repurposing | Stuttgart automotive manufacturers embed centimeter-accurate anchors that logistics providers leverage for proximity applications. |
| Rule-Based Stack Certification | German industrial buyers accelerate procurement to avoid EU AI Act high-risk obligations for predictive analytics systems. |
| GDPR Article 6 Compliance Architecture | UK retailers navigate ICO enforcement to maintain lawful-basis pathways for retail loyalty program automation. |
Methodological Framework
The analysis maps GPS fleet verification, Bluetooth beacon retail networks, UWB automotive proximity systems, and cloud API platform tiers, each validated through primary interviews with logistics operations directors, quick-service restaurant technology officers, automotive platform engineers, and telecommunications infrastructure planners. Secondary validation draws from SEC hyperscaler capex disclosures, TRAI regulatory circulars, EMA data-localization guidance, and EU AI Act implementation documents. Bottom-up deployment counts triangulate against top-down cloud infrastructure revenue segmentation.
Assumptions held fixed include current FTC enforcement intensity, GDPR Article 6 interpretation stability, and Taiwan foundry capacity allocation patterns; variables stress-tested encompass EU AI Act risk-classification expansion, 5G network slicing deployment velocity, and UWB chipset cost-collapse trajectories. Segmentation dimensions span application type, technology precision tier, deployment architecture, and end-user vertical. CAGRs derive from logistic curve fitting to enterprise adoption timelines, with inputs including fleet telematics upgrade cycles and retail beacon installation rates.
Stress conditions across semiconductor supply disruption severity, biometric statute proliferation at US state level, and cloud infrastructure concentration risk were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology substitution thresholds. Material shifts in EU AI Act automated-decisioning scope interpretations or US state-level geolocation consent requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Social Media Security Market
Security Software
Device Vulnerability Management Market
Security Software
Identity Governance and Administration Market
Security Software
Internet Filter Software Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Decentralized Identity Software Market
Security Software
Secure Flash Drive Market
Security Software
Global Visitor Management System Market
Security Software
Cloud Security Software Market
Security Software
Enterprise Rights Management Solution Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Security Information and Event Management Software Market
Security Software
Privacy Management Software Market
Security Software
Network Camera Market
Security Software
Global Background Check Software Market