
 Asia-Pacific Smart Doorbell Market | 2026-2036
Asia-Pacific Smart Doorbell Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Doorbell Market Insights
Multi-source component procurement is hardening across the Asia-Pacific smart doorbell supply chain as manufacturers hedge against semiconductor volatility. Xiaomi Corp. leverages its Mi Home ecosystem to anchor consumer lock-in across connected devices. Panasonic Corporation sustains premium positioning through in-house sensor calibration and Japanese manufacturing standards. Shenzhen VStarcam Technology Co., Ltd competes on cost-optimized video modules for budget-tier installers.
A smart doorbell integrates a camera, microphone, speaker, and motion sensor into a door-mounted unit that streams audiovisual data to homeowner devices via internet protocol networks. Resolution thresholds now start at 1080p with HDR compensation for low-light entryways, while edge-based AI processing enables on-device person detection without cloud dependency. Video doorbell units capture the dominant revenue share as consumers prioritize visual verification over audio-only solutions. Cloud storage subscription tiers generate recurring margin pools that offset hardware commoditization in the wireless doorbell segment. Wi-Fi connectivity dominates installation profiles though Zigbee adoption rises in multi-device smart home deployments across South Korea and Japan.
Japan's METI enforces cybersecurity certification under its IoT security labeling scheme, forcing firmware audit cycles that extend product development timelines. India's TRAI data localization mandates and China's GB standards for networked cameras create divergent compliance burdens for cross-border vendors. Australia's ACMA radiofrequency rules constrain transmission power in wireless doorbell designs. Stakeholders must monitor evolving encryption requirements as regional regulators treat doorbell footage as biometric-adjacent personal data.
Market Dynamics
TRAI's data localization mandates under India's Digital Personal Data Protection Act are forcing architectural redesigns across product lines, while semiconductor procurement hedging is fragmenting vendor relationships.
Growth Catalysts
- Cloud Storage Subscription Models:Recurring revenue streams from tiered video archival services offset hardware margin compression in residential deployments.
- India's TRAI Localization Push:Mandates for in-country data processing create captive demand for regionally architected firmware and local server infrastructure.
- Edge AI Processing:On-device person detection reduces latency and cloud dependency, accelerating replacement cycles in bandwidth-constrained Southeast Asian housing complexes.
Market Restraints
- Semiconductor Input Volatility:Image sensor and Wi-Fi module costs fluctuate with foundry allocation cycles, squeezing budget-tier manufacturers.
- Compliance Fragmentation:Japan's METI cybersecurity labeling, India's TRAI mandates, and China's GB standards force parallel certification tracks that extend time-to-market.
- Technical Interoperability Limits:Proprietary smart home ecosystems from dominant Chinese brands lock out third-party doorbell integration.
Strategic Opportunities
- Underpenetrated Indian Tier-Two Cities:Rising disposable incomes and builder-installed smart home packages drive first-time video doorbell adoption outside metro cores.
- Zigbee Multi-Device Convergence:Integration with lighting and climate control systems in South Korean and Japanese apartments creates bundled installation demand.
- Australia's ACMA Certification Pathway:Streamlined radiofrequency compliance for low-power devices reduces barrier-to-entry for new market entrants.
Industry Challenges
- Firmware Audit Timeline Compression:Japan's METI IoT security labeling requires third-party penetration testing that extends development cycles by 4-6 months.
- Legacy Analog Infrastructure:Pre-digital apartment intercom systems in older Japanese and South Korean residential blocks complicate retrofit wiring and power delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Doorbell Market |
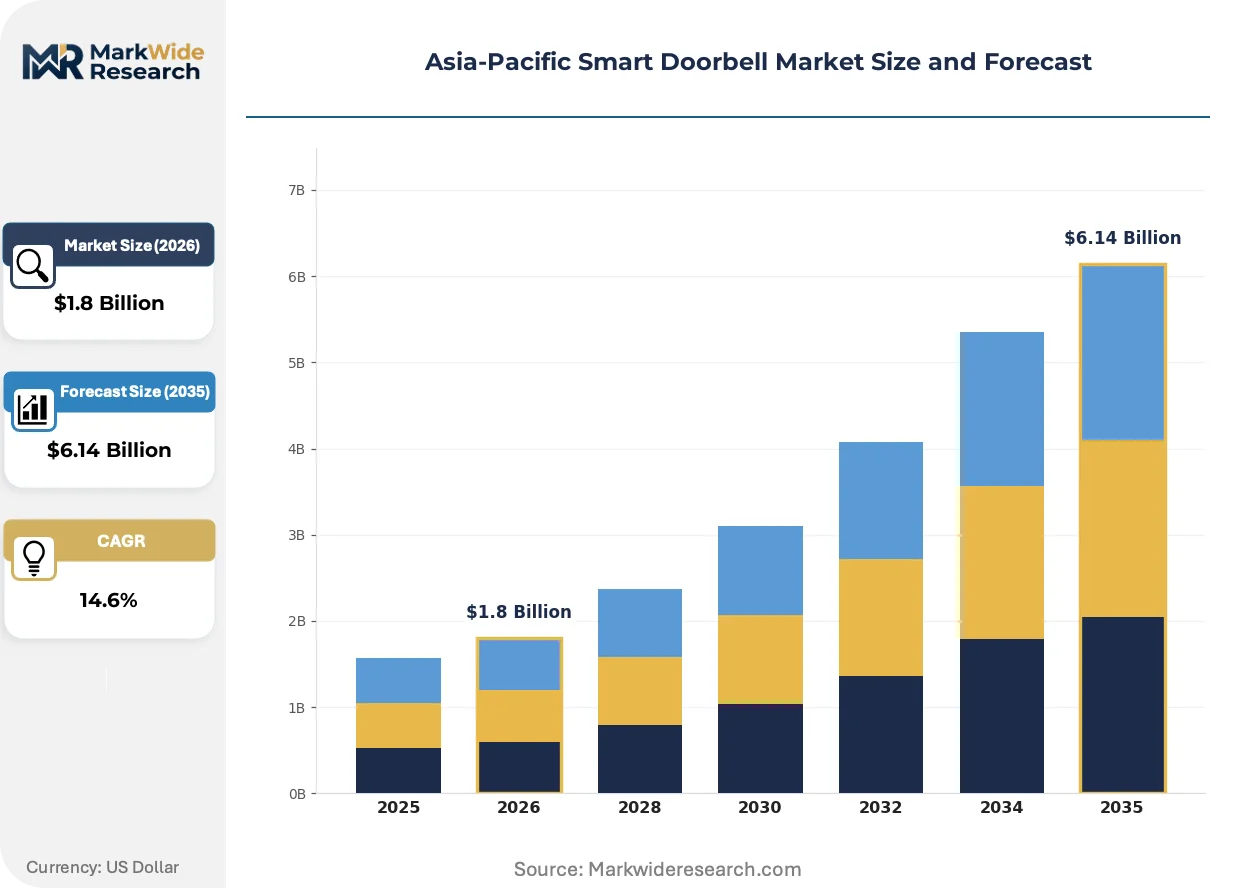
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Doorbell, Wireless Doorbell, Video Doorbell, Smart Speakers Feature: Motion Detection, Two-Way Audio, Night Vision, Cloud Storage End User: Residential, Commercial, Retail, Hospitality Connectivity: Wi-Fi, Bluetooth, Ethernet, Zigbee |
| Companies Covered | Panasonic Corporation, Xiaomi Corp., Shenzhen VStarcam Technology Co., Ltd, Amazon.com Inc, Arlo Technologies, Inc., Vivint Smart Home, Inc., August, Inc., Google LLC, SkyBell Technologies, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Doorbell Market Trends and Innovations
Resolution thresholds and AI processing capabilities are advancing faster than price erosion, while regulatory divergence is splintering product architectures across national boundaries.
Edge-based computer vision is converging with low-power neural network accelerators to enable real-time person detection without cloud round-trips. Premium residential installers in China's tier-one cities specify these modules for latency-sensitive entry monitoring. The shift compresses demand for basic motion-sensor units while expanding addressable margin in the professional channel.
India's TRAI localization mandates under the Digital Personal Data Protection Act force server infrastructure relocation and encryption key management redesigns. Cross-border vendors must maintain parallel firmware branches, raising engineering overhead. Chinese manufacturers with existing domestic cloud partnerships capture advantage in compliance velocity.
Builder-direct procurement now dominates new residential construction in Vietnam and Indonesia, displacing retail channel dependence. Developers specify pre-installed video doorbells as standard amenities in mid-market condominiums. This concentration shifts pricing power toward volume contractors and compresses brand visibility among end consumers.
Asia-Pacific Smart Doorbell Market Segmentation
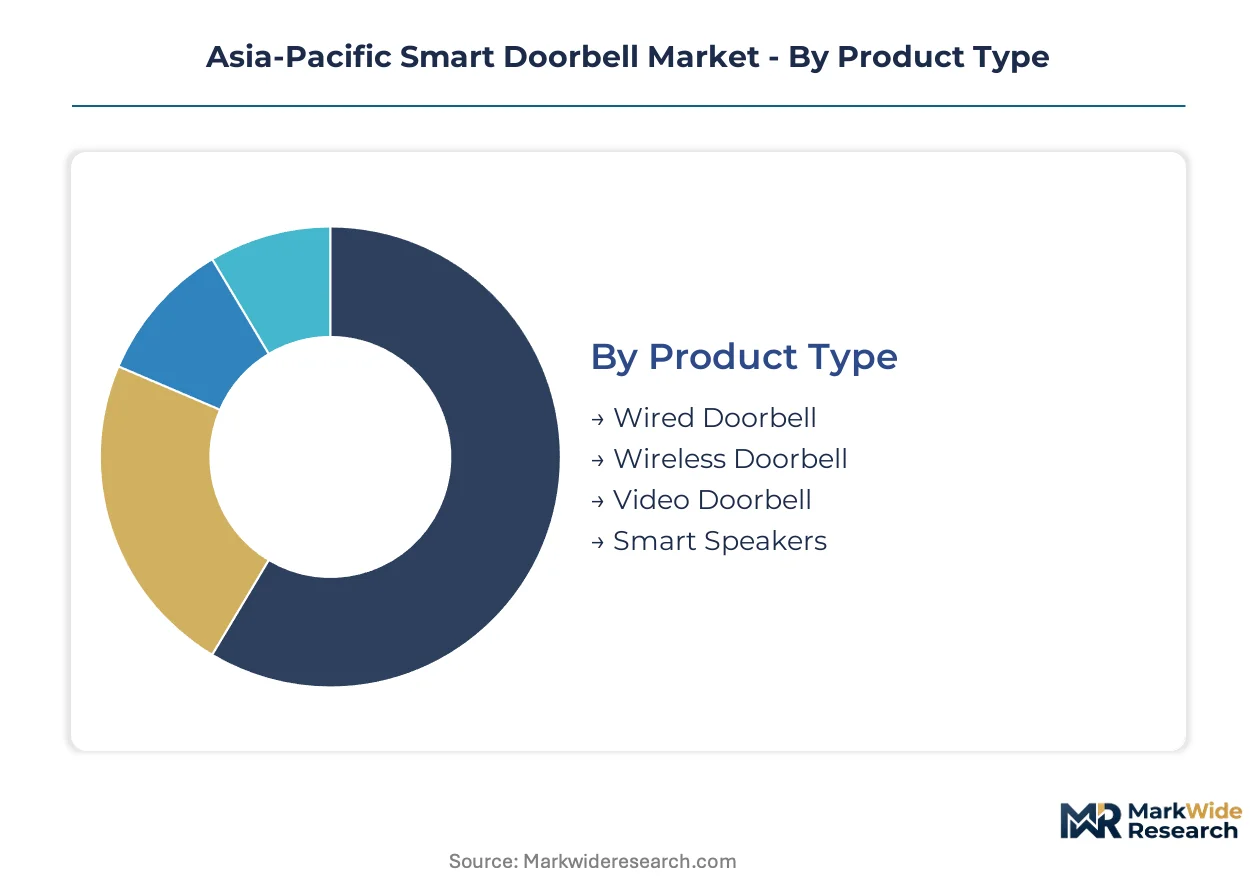
Smart doorbell segmentation in Asia-Pacific tracks divergent technology maturity across installation environments. Product architecture, feature bundling, and connectivity protocols each carry distinct regulatory and infrastructure dependencies that reshape vendor priorities across national markets.
Product Type:
Customization-to-standardization tension runs deepest here, with hardwired legacy compatibility clashing against battery-powered flexibility demands.
- Video Doorbell:Combines 1080p HDR camera modules with edge AI processors for on-device person detection. Demand clusters in China's tier-one cities where Xiaomi and Huawei ecosystem integration drives replacement cycles. Cloud storage subscriptions generate recurring revenue that offsets hardware margin compression.
- Wireless Doorbell:Battery-powered units with Wi-Fi or Zigbee radios eliminate retrofit wiring requirements. Accelerating uptake in Southeast Asian residential complexes where builder-direct procurement specifies pre-installed units as standard amenities in mid-market condominiums.
- Wired Doorbell:PoE or low-voltage transformer designs serving legacy intercom replacements in older Japanese and South Korean apartment blocks.
- Smart Speakers:Voice-integrated entry units with Alexa or Google Assistant compatibility, concentrated in premium Australian and Japanese installations.
Leading the category by volume: Video Doorbell. Expanding most quickly: Wireless Doorbell.
Feature:
Cost tier stratification separates basic motion-alert units from AI-enhanced premium configurations with localized data handling.
- Cloud Storage:Tiered archival services with India-mandated local server infrastructure under TRAI's Digital Personal Data Protection Act. Chinese vendors with domestic cloud partnerships capture compliance velocity advantage. Subscription tiers now anchor business models for hardware commoditization defense.
- Motion Detection:PIR sensors and radar-based presence detection in budget-tier units across Vietnam and Indonesia. Baseline specification for builder-direct procurement contracts.
- Two-Way Audio:Full-duplex voice communication with echo cancellation, standard in professional channel specifications across South Korea and Japan.
- Night Vision:IR LED arrays and low-light sensor optimization for entryway illumination variance.
Leading the category by volume: Motion Detection. Steepest expansion trajectory: Cloud Storage.
End User:
Application maturity separates established residential replacement cycles from emerging commercial security integration.
- Residential:Single-family homes and multi-unit dwellings across China's tier-one cities and India's tier-two growth corridors. Builder-installed packages displace retail channel dependence in Vietnam and Indonesia.
- Commercial:Office building access control with centralized management platforms. Zigbee multi-device convergence with lighting and climate systems in South Korean and Japanese commercial deployments.
- Retail:Customer flow monitoring and loss prevention integration in convenience store chains.
- Hospitality:Guest verification and concierge integration in boutique hotel segments.
Leading the category by volume: Residential. Gaining share fastest: Commercial.
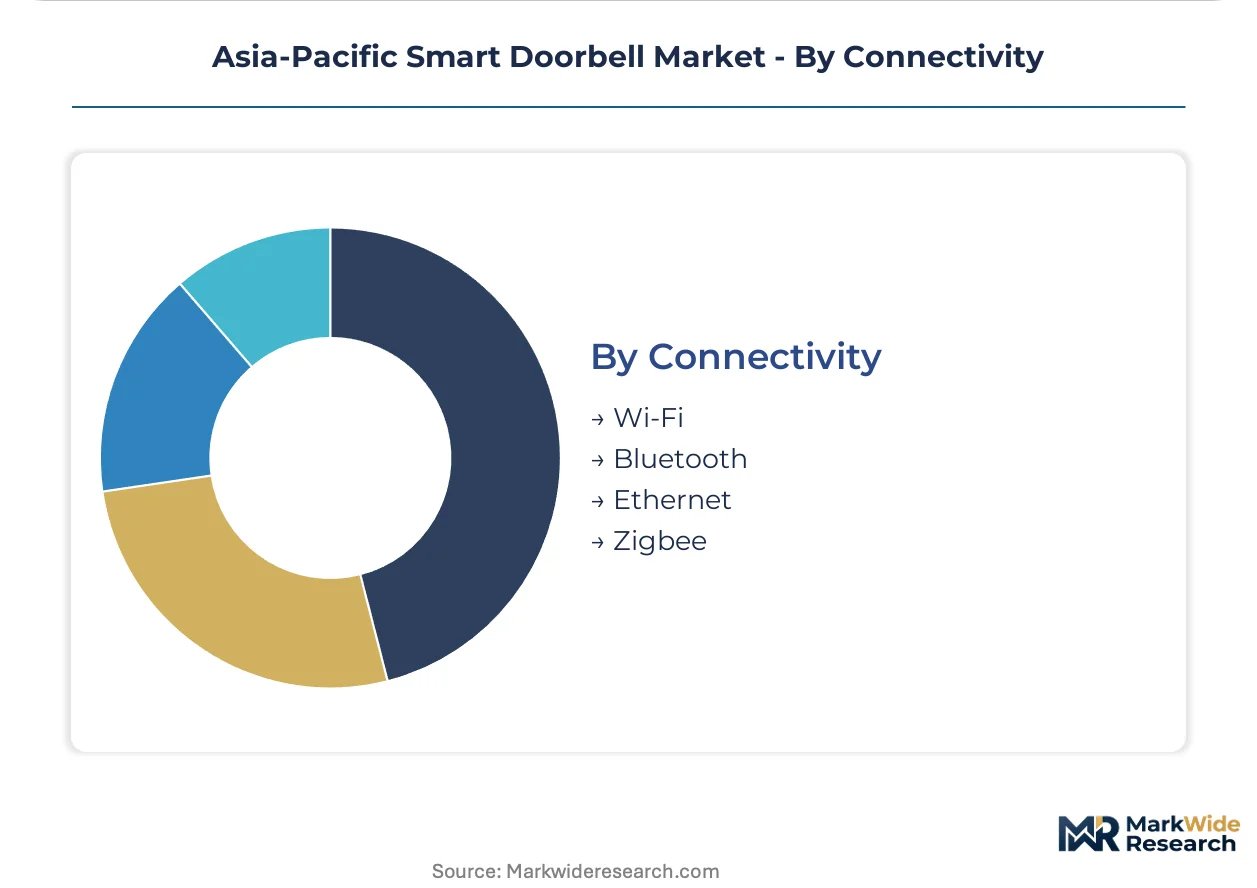
Connectivity:
Supply concentration around Wi-Fi silicon contrasts with emerging protocol diversification for smart home ecosystem lock-in.
- Wi-Fi:2.4GHz and 5GHz dual-band radios dominating installation profiles. Semiconductor input volatility from foundry allocation cycles squeezes budget-tier manufacturers dependent on commodified modules.
- Zigbee:Mesh networking for multi-device deployments with localized gateway control. Rising adoption in South Korean and Japanese apartments where bundled lighting and climate integration drives specification.
- Bluetooth:Low-energy proximity pairing for initial device setup and mobile credential handoff.
- Ethernet:PoE hardwired reliability for commercial installations with existing infrastructure.
Leading the category by volume: Wi-Fi. Climbing the fastest: Zigbee.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's tier-one cities where Xiaomi and Huawei smart home ecosystems drive replacement cycles, while India's tier-two corridors emerge as volume expansion zones under builder-installed procurement models.
China
Xiaomi and Huawei ecosystem integration anchors consumer lock-in across Beijing, Shanghai, and Shenzhen residential complexes. MIIT's GB standards for networked cameras mandate encryption protocols that extend firmware development timelines. The Yangtze River Delta manufacturing corridor supplies cost-optimized video modules for domestic and export markets.
India
Builder-direct procurement in tier-two cities like Pune and Ahmedabad displaces retail channel dependence for first-time video doorbell adoption. TRAI's data localization mandates under the Digital Personal Data Protection Act force server infrastructure relocation and parallel firmware branches. The Delhi-NCR corridor hosts regional cloud partnerships that accelerate compliance velocity for cross-border vendors.
Japan
Legacy analog intercom retrofits in Tokyo and Osaka residential blocks drive wired doorbell replacement demand. METI's IoT security labeling scheme requires third-party penetration testing that extends product development cycles by 4-6 months. The Kanto region concentrates premium installer networks specifying edge AI modules for latency-sensitive entry monitoring.
South Korea
Zigbee multi-device convergence with lighting and climate systems drives bundled installation demand in Seoul Capital Area apartments. MFDS-equivalent cybersecurity frameworks for consumer IoT devices impose firmware audit requirements. The Busan-Ulsan corridor supplies semiconductor components for Wi-Fi and mesh networking modules.
Australia
ACMA radiofrequency rules constrain transmission power in wireless doorbell designs, creating streamlined compliance pathways for low-power device entrants. Premium residential installations in Sydney and Melbourne specify voice-integrated entry units with Alexa compatibility. The New South Wales-Victoria corridor concentrates professional channel distributors serving boutique builder segments.
Asia-Pacific Smart Doorbell Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors navigate compliance fragmentation across national boundaries. The vendor base stratifies across three tiers: ecosystem-anchored consumer electronics conglomerates, premium-tier sensor specialists, and cost-optimized module fabricators. Archetypes include smart home ecosystem integrators, in-house manufacturing standards bearers, and budget-tier video module suppliers. M&A activity and technology licensing agreements represent the dominant competitive moves as firms seek compliance velocity in regulated markets.
Within the ecosystem-anchored tier, Xiaomi Corp. and Google LLC exemplify platform lock-in strategies, while Panasonic Corporation occupies a position among premium-tier specialists emphasizing manufacturing standards. Shenzhen VStarcam Technology Co., Ltd sits within the cost-optimized fabricator segment serving budget-tier installer channels.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Xiaomi Corp. |
| Shenzhen VStarcam Technology Co., Ltd |
| Amazon.com Inc |
| Arlo Technologies, Inc. |
| Vivint Smart Home, Inc. |
| August, Inc. |
| Google LLC |
| SkyBell Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between METI-labeled premium units and uncertified budget-tier modules manifests in both margin structures and supplier qualification requirements across Japan and Southeast Asia. Hardware commoditization in wireless doorbells intensifies cost competition among Shenzhen-based module fabricators, while cloud subscription bundling props up lifetime value calculations for ecosystem-anchored vendors.
Pricing Analysis
Volume-vs-margin splits sharply across the builder-direct and retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden dispersion, with METI cybersecurity labeling and TRAI data localization mandates adding compliance premiums to Japanese and Indian market tiers. Price erosion runs through battery-powered wireless units as Shenzhen manufacturers compete on video module cost. Builder-direct procurement in Vietnam and Indonesia exhibits highest price sensitivity, while Australian professional channel buyers absorb premiums for ACMA-compliant low-power designs.
Supply Chain Analysis
Dual-sourcing requirements from tier-one OEMs now mandate qualified secondary suppliers for image sensors and Wi-Fi modules to hedge against foundry allocation volatility. Component manufacturing concentrates in China, South Korea, and Taiwan, with the Yangtze River Delta supplying cost-optimized video modules and the Busan-Ulsan corridor producing semiconductor components for mesh networking. Supply chain risk centers on single-source vulnerability in edge AI processor supply. Distribution runs through professional installer networks in Japan and Australia, while Southeast Asian markets favor direct developer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
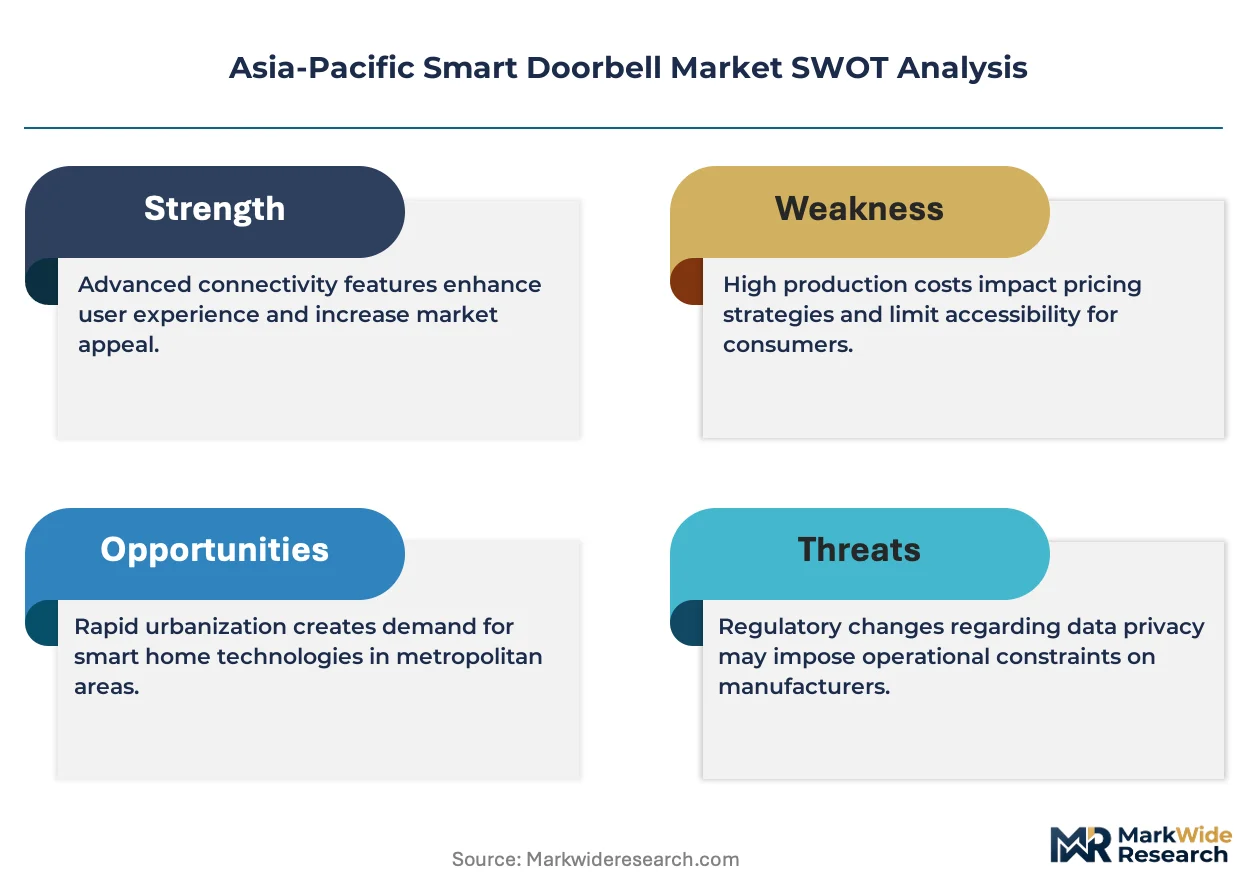
Semiconductor foundry capacity constraints prop pricing power for vendors with secured wafer allocations, creating a supply-constrained market structure that favors incumbents with established supplier relationships.
For Market Incumbents: Hedge against compliance fragmentation by maintaining parallel firmware branches for Japan's METI cybersecurity labeling, India's TRAI localization mandates, and China's GB standards. Secure captive supply agreements for image sensors and neural network accelerators to defend margin position amid foundry allocation volatility. Channel control through professional installer networks in Australia and Japan offers defensive moats against ecosystem-anchored competitors. For New Entrants and Emerging Players: Australia's ACMA streamlined radiofrequency compliance opens a window for low-power device specialists to establish beachhead positions before ecosystem consolidation hardens. Target India's tier-two builder-direct procurement corridors in Pune and Ahmedabad where first-time video doorbell adoption outpaces established metro markets. Zigbee multi-device convergence in South Korean apartments offers a go-to-market angle through bundled lighting and climate integration partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with premium-tier sensor specialists given METI certification scarcity and extended firmware audit timelines that constrain new entrant velocity. Long-term viability favors vendors with in-house manufacturing standards and regional cloud partnerships that accelerate compliance velocity across divergent regulatory frameworks. Watch for inflection in India's Digital Personal Data Protection Act enforcement intensity as a signal for localization-mandate market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cloud Partnership Formation | TRAI localization mandates force server infrastructure relocation to Delhi-NCR corridor partners. |
| Edge AI Processor Integration | On-device person detection reduces latency for bandwidth-constrained Southeast Asian housing complexes. |
| Zigbee Multi-Device Certification | South Korean and Japanese apartment bundling creates specification lock-in with lighting and climate systems. |
| Builder-Direct Channel Development | Vietnam and Indonesia developer procurement displaces retail dependence in mid-market condominiums. |
| METI Cybersecurity Label Acquisition | Third-party penetration testing extends development cycles but anchors premium positioning in Tokyo-Osaka corridor. |
Research Methodology
Multi-period observation of semiconductor allocation cycles, regulatory enforcement timelines, and builder procurement patterns anchored the trend analysis, supplemented by interviews with smart home platform engineers, residential developer procurement leads, professional installer network managers, and cloud infrastructure architects. Secondary validation drew from MIIT GB standard filings, TRAI localization mandate circulars, METI IoT security labeling documentation, and customs trade data for video module imports. Bottom-up unit shipment modeling and top-down ecosystem revenue estimates were triangulated against channel inventory checks.
Input-output matrices mapped connectivity protocol adoption, feature bundling intensity, and end-user segment penetration across the projection horizon. Segmentation dimensions included product architecture, connectivity standard, installation environment, and regional regulatory cluster. CAGRs were derived from fitted growth curves against observed replacement cycles and new construction penetration rates. Forecast inputs incorporated edge AI processor cost curves and cloud storage subscription attach rate assumptions.
The model assumes a particular technology adoption path for edge-based computer vision; alternative pathways for cloud-dependent processing would alter the outlook for bandwidth infrastructure requirements and latency tolerance thresholds. Deviation in foundry capacity allocation or cybersecurity certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Runtime Application Self-Protection Market
Security Software
Application Control Market
Security Software
Identity Governance and Administration Market
Security Software
Information Rights Management Market
Security Software
Global Email Verification Tools Market
Security Software
Cloud Encryption Software Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Europe Smart Doorbell Market
Security Software
Global Visitor Management System Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Decentralized Identity Software Market
Security Software
User Provisioning Software Market
Security Software
Secure Flash Drive Market
Security Software
United States Lawful Interception Market
Security Software
Mobile Security Market
Security Software
IAM Security Services Market